
 Jaw Crushers Market | 2026-2036
Jaw Crushers Market Size, Share, and Industry Trends Forecast 2026-2036
Jaw Crushers Market Intelligence
High-capacity specification tiers above 500 tonnes per hour is rotating capital allocation toward heavy-duty mining configurations. Metso Outotec Corporation leverages its aftermarket services network to sustain recurring revenue streams. Sandvik AB anchors its position through alloy metallurgy leadership in jaw plate durability. Thyssenkrupp competes on integrated plant engineering capabilities that bundle crushers with downstream screening.
A jaw crusher is a compression-type machine that reduces feed material between a fixed and a moving jaw surface, with typical operating speeds of 100-350 RPM and reduction ratios ranging from 3:1 to 5:1 depending on ore hardness and chamber geometry. Its primary purpose is primary size reduction of hard rock, ore, and recycled concrete for downstream processing or direct construction use. Single toggle designs command the largest installed base in mining applications due to lower weight and higher throughput per horsepower, while mobile configurations are gaining traction in urban recycling where site relocation frequency justifies portability premiums. Stationary installations retain margin concentration in greenfield quarry projects with 15-plus year operational horizons.
MSHA workplace safety mandates and EPA National Emission Standards for Hazardous Air Pollutants shape dust suppression and enclosure requirements for domestic crushing operations. CE marking under the EU Machinery Directive and REACH compliance for lubricants and hydraulic fluids govern market access for equipment imported into Europe. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content requirements as procurement criteria extend beyond technical specifications into supply chain provenance verification.
Market Dynamics
The jaw crushers market is experiencing structural pressure from declining ore grades in mature mining districts, which forces operators toward higher-throughput equipment configurations and accelerates replacement cycles for older, less efficient installations.
Growth Catalysts
- MSHA dust exposure limits:Underground mining operations in the United States face stricter permissible exposure limits for respirable silica, driving enclosure and suppression retrofits on existing crushing circuits.
- India's mineral corridor expansion:State-owned mining corporations in Odisha and Chhattisgarh are expanding iron ore and bauxite extraction capacity, creating concentrated demand for heavy-duty primary crushing infrastructure.
- Recycled concrete specification:Municipal infrastructure agencies in Germany and France are mandating minimum recycled aggregate content in public construction, expanding mobile crusher deployment for urban demolition feedstock.
Market Restraints
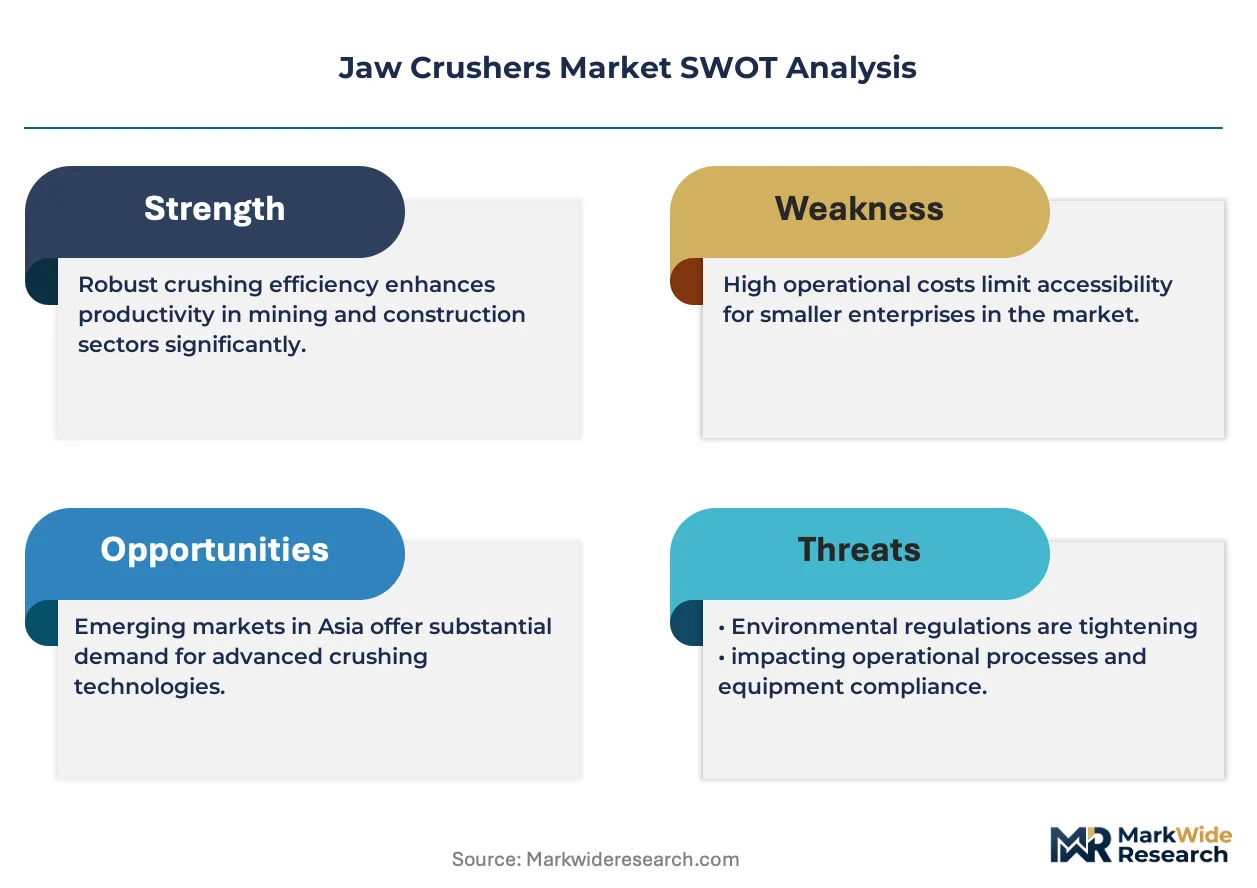
- Manganese steel price volatility:Jaw plate and liner consumables depend on ferroalloy input costs that fluctuate with South African electricity supply interruptions and export duty adjustments.
- Foundry capacity concentration:Specialized castings for high-wear crusher components concentrate among a limited supplier base in India and China, creating lead time vulnerability for European and North American OEMs.
- CE Machinery Directive compliance costs:Third-party conformity assessment for noise emissions and safety interlocks adds fixed certification overhead that disadvantages smaller equipment manufacturers.
Strategic Opportunities
- Western Australian lithium spodumene expansion:Hard-rock lithium projects in the Pilbara and Goldfields regions require dedicated primary crushing circuits optimized for pegmatite ore hardness and abrasiveness.
- Digital twin integration:Real-time liner wear monitoring combined with predictive maintenance algorithms enables outcome-based service contracts that capture recurring revenue from uptime guarantees.
- EU Carbon Border Adjustment Mechanism:Embodied carbon accounting in imported steel components creates competitive opening for European foundries with electric arc furnace production and renewable energy sourcing.
Industry Challenges
- Reliability engineering specialization:OEMs struggle to recruit personnel capable of translating vibration analysis and thermographic data into actionable maintenance protocols for remote mining installations.
- Legacy control system integration:Modern drive and automation packages must interface with decades-old PLC architectures common in brownfield quarry operations, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jaw Crushers Market |
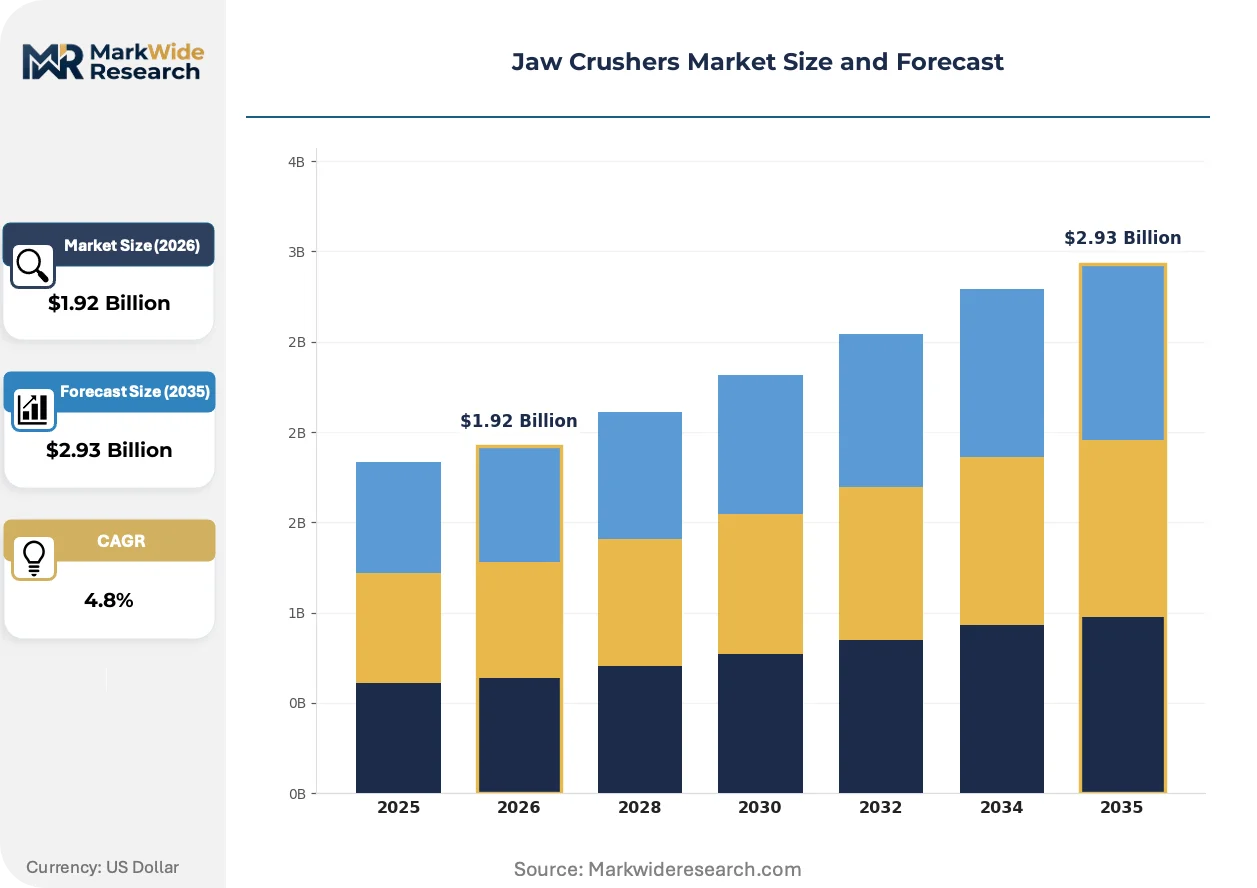
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Toggle, Double Toggle, Compact, Mobile End User: Mining, Construction, Recycling, Quarrying Installation Type: Stationary, Portable, Semi-Portable, Integrated Sales Channel: Direct Sales, Distributors, Online Retail, Auctions |
| Companies Covered | Metso Outotec Corporation, Sandvik AB, Terex Corporation, Thyssenkrupp, Astec Industries, McLanahan Corporation, Eagle Crusher Company, Komatsu Ltd., FLSmidth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jaw Crushers Market Strategic Shifts & Innovations
Equipment intelligence and material science are converging to redefine performance benchmarks in comminution, with digitalization and sustainability mandates acting as parallel forcing mechanisms across supplier and operator communities.
Hybrid-electric drive architectures are bifurcating the installed base between grid-tied stationary installations and diesel-electric mobile units optimized for energy recovery during deceleration cycles. Mining operators in Scandinavia and Canada are piloting trolley-assist configurations that draw grid power during pit ramp ascents while retaining diesel autonomy for remote relocation. This technology is bifurcating capital allocation between fully electrified greenfield sites and retrofit-compatible hybrid packages for existing fleets.
EPA National Emission Standards for Hazardous Air Pollutants are tightening enclosure and capture efficiency requirements for particulate matter from crushing, screening, and conveying operations. Equipment suppliers must now engineer integrated dust suppression systems with automated water injection and negative-pressure enclosures as standard rather than optional configurations. Surface mining operations in Arizona, Nevada, and Wyoming are experiencing the most acute compliance pressure due to ambient air quality maintenance plan designations.
Asset-light contracting models are displacing traditional equipment purchase arrangements in European aggregates and recycling sectors. Contractors in the United Kingdom and Benelux markets increasingly specify throughput-based rental agreements with full maintenance inclusion, transferring operational risk to OEM finance arms and specialized rental houses. This shift concentrates fleet ownership among capital-efficient lessors while fragmenting the operator landscape toward smaller, nimbler demolition and earthmoving specialists.
Jaw Crushers Market Segmentation
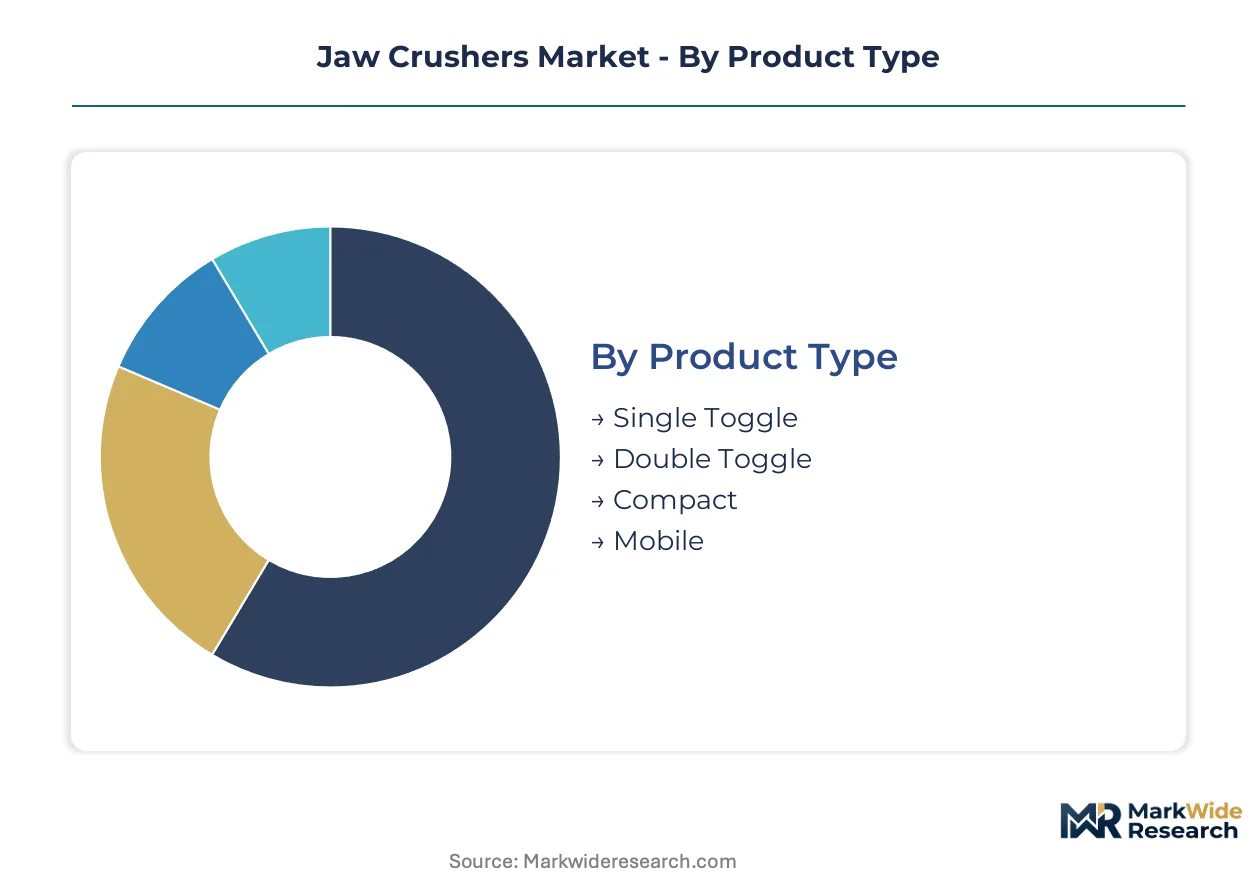
Jaw crusher segmentation reveals divergent margin structures across product architectures and deployment modes. Equipment specification tiers separate mining-grade heavy-duty installations from mobile urban recycling units with vastly different aftermarket economics.
Product Type:
Margin pools concentrate in configurations optimized for specific ore hardness and throughput requirements, with metallurgical durability commanding premium positioning.
- Single Toggle:Lower weight-to-throughput ratio enables higher crushing speeds with reduced horsepower draw. Mining operators in Western Australia's Pilbara region specify these for iron ore primary circuits where energy recovery justifies capital outlay. Declining ore grades force faster liner replacement cycles, embedding recurring revenue in OEM service contracts.
- Double Toggle:Heavier pitman and toggle plate assembly distributes crushing force across eccentric shaft bearings for extended service intervals in abrasive conditions. Underground hard-rock mines in Canada's Sudbury Basin favor this architecture for nickel-copper ore with high quartz content, accepting throughput penalties for reliability gains.
- Compact:Reduced feed opening dimensions suit laboratory-scale sample preparation and pilot plant validation work.
- Mobile:Track-mounted or wheeled chassis configurations with onboard power units enable rapid site relocation for urban demolition contractors.
Single Toggle holds installed capacity. Mobile is rotating up the share rankings.
End User:
Application intensity separates capital-intensive primary crushing circuits from intermittent-duty recycling operations with divergent equipment utilization profiles.
- Mining:Continuous-duty specifications with 6000+ annual operating hours demand manganese steel liners rated for 150,000+ tonne throughput. Western Australian lithium spodumene projects in the Goldfields region specify dedicated pegmatite-optimized chambers with enhanced abrasion resistance.
- Recycling:Variable feed composition from reinforced concrete and asphalt requires hydraulic release systems for uncrushable tramp metal protection. German municipal aggregate mandates for minimum recycled content in public infrastructure accelerate mobile crusher deployment around Berlin and Munich demolition corridors.
- Construction:Roadbuilding and tunneling contractors specify intermediate-duty units for processed aggregate supply.
- Quarrying:Dimension stone and aggregate producers balance throughput against product shape requirements for asphalt and concrete feedstock.
Mining anchors capital deployment. Recycling is expanding most quickly as circular economy mandates tighten.
Installation Type:
Portability premiums reflect site tenure economics, with mobility trading capital efficiency against operational flexibility in fragmented feedstock markets.
- Stationary:Reinforced concrete foundations and grid-tied electrical infrastructure support 15-plus year operational horizons in greenfield quarry developments. Scandinavian hard-rock aggregate producers favor fully electrified configurations with trolley-assist compatibility for carbon intensity reduction.
- Portable:Skid-mounted or trailer-transported units with quick-disconnect utilities suit contract crushing services with 6-18 month site commitments. British aggregates contractors in the Midlands specify these for rail ballast supply contracts with defined volume windows.
- Semi-Portable:Modular sub-assemblies reduce relocation downtime for multi-pit mining operations with 2-5 year extraction phases.
- Integrated:Pre-engineered crushing-screening-conveying packages from single OEM sources compress commissioning schedules.
Stationary dominates quarry ownership. Portable is climbing the fastest as rental penetration deepens.
Sales Channel:
Channel economics separate high-touch specification support from transactional volume plays, with financing integration increasingly decisive in capital equipment procurement.
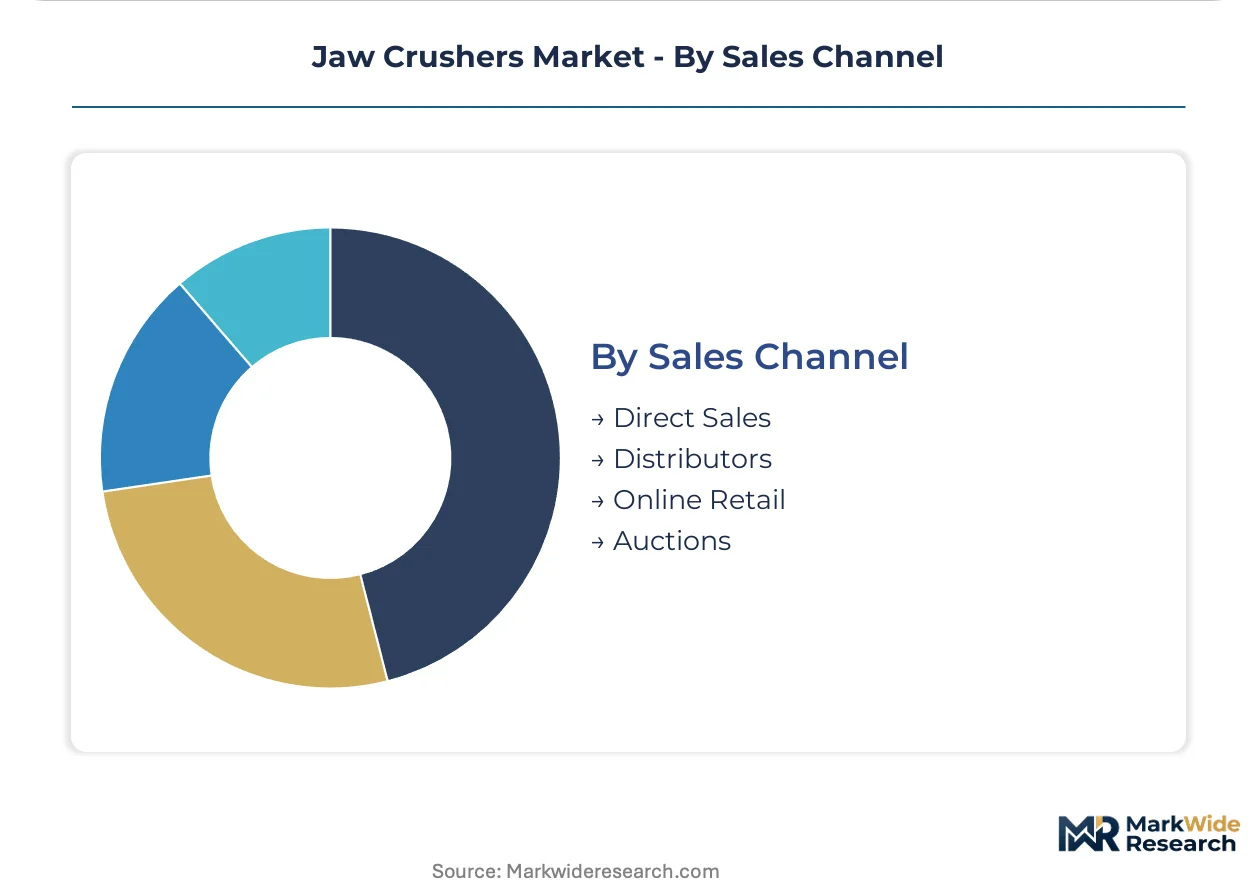
- Direct Sales:OEM application engineering teams configure custom chamber geometries and drive packages for mine-specific ore characteristics. Metso Outotec and Sandvik AB deploy technical sales specialists to Western Australian and Chilean mining districts for greenfield project capture.
- Distributors:Regional inventory positioning and aftermarket parts availability support mid-market quarry and recycling operators. Indian equipment distributors in Odisha and Chhattisgarh maintain manganese liner stockpiles for state-owned iron ore miners with compressed procurement cycles.
- Online Retail:Standardized compact units and wear parts catalogs serve small contractors with predictable specification requirements.
- Auctions:Secondary market liquidation channels for fleet renewal and insolvency-driven asset disposition.
Direct Sales captures mining project value. Distributors is gaining share fastest in emerging market volume tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Australian mining operators absorb premium specifications for throughput gains, while Indian quarry contractors prioritize capital efficiency and local parts availability.
United States
Surface mining operations in Arizona and Nevada face EPA National Emission Standards for Hazardous Air Pollutants enforcement for particulate capture efficiency. MSHA dust exposure limits for respirable silica drive enclosure retrofits on existing crushing circuits. Equipment suppliers concentrate application engineering resources around Phoenix and Denver to serve copper and aggregate producers.
Australia
Western Australian lithium spodumene projects in the Pilbara and Goldfields regions require primary crushing circuits optimized for pegmatite hardness. State environmental regulators mandate dust management plans for open-pit operations. Fleet renewal activity concentrates around Kalgoorlie and Port Hedland as iron ore grades decline and throughput requirements rise.
India
State-owned mining corporations in Odisha and Chhattisgarh are expanding iron ore and bauxite extraction capacity under mineral corridor development programs. BIS certification requirements govern equipment safety and electromagnetic compatibility for domestic market access. Crushing equipment demand clusters in the eastern mineral belt where infrastructure investment accelerates.
Germany
Municipal infrastructure agencies mandate minimum recycled aggregate content in public construction, expanding mobile crusher deployment around Berlin and Munich demolition corridors. CE marking under the EU Machinery Directive and REACH compliance for lubricants govern market access. Trolley-assist electrification pilots in Scandinavian-influenced quarry operations create specification pull for grid-compatible stationary installations.
Brazil
Iron ore producers in the Carajás mineral province and Minas Gerais iron quadrangle specify heavy-duty primary crushing for itabirite and hematite ores. ANVISA and environmental licensing requirements shape equipment import documentation and local content verification. Equipment procurement concentrates around Belo Horizonte and São Luís as major mining houses expand capacity.
Jaw Crushers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The installed base concentrates among full-line comminution specialists with integrated plant engineering capabilities and regional fabricators serving price-sensitive quarry markets. Three archetypes dominate: metallurgy-led durability specialists, integrated plant engineering bundlers, and mobile equipment mobility innovators. Competitive moves center on aftermarket service contract penetration and digital twin integration for predictive maintenance revenue capture.
Among Nordic-based full-line suppliers, Metso Outotec Corporation and Sandvik AB exemplify the metallurgy-led archetype with emphasis on alloy development for wear component longevity. Thyssenkrupp occupies a position within the integrated plant engineering tier, bundling crushers with downstream screening and materials handling. These three anchors represent distinct strategic vectors: aftermarket services network depth, materials science specialization, and system integration capability respectively.
| Leading Market Players |
|---|
| Metso Outotec Corporation |
| Sandvik AB |
| Terex Corporation |
| Thyssenkrupp |
| Astec Industries |
| McLanahan Corporation |
| Eagle Crusher Company |
| Komatsu Ltd. |
| FLSmidth |
| Others |
Cost & Logistics Intelligence
Foundry scale economies in manganese steel casting concentrate production among Indian and Chinese suppliers, compressing margin capture for European OEMs while establishing price floors tethered to ferroalloy input volatility. This concentration shapes procurement strategies across mining-grade equipment tiers, with buyers trading lead time certainty against capital efficiency.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European market access, separating premium-certified heavy-duty mining configurations from economy-tier portable units lacking conformity assessment documentation. Price differentiation rests on abrasion-resistant alloy grades and aftermarket service bundling, with OEMs commanding premiums for predictive maintenance integration. Cost compression in standard-tier mobile equipment is intensifying because rental fleet operators consolidate procurement volume. Small quarry contractors in India's mineral belt exhibit highest price sensitivity, while Australian lithium producers absorb specification premiums for pegmatite-optimized chamber geometries.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites logistics risk for manganese ore feedstock flowing from South African mines to Asian foundries. Component manufacturing draws from India, China, and Germany, with specialized castings for high-wear liners sourcing from concentrated supplier bases in Indore and Jinan. Single-source vulnerability concentrates in electric arc furnace capacity for low-carbon steel components serving EU Carbon Border Adjustment Mechanism compliance. Distribution runs through OEM-direct specification teams for mining projects and regional distributor networks for mid-market quarry operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration and predictive maintenance algorithms are reshaping revenue capture, converting capital equipment sales into recurring service contracts across mining installations.
For Market Incumbents: Fortify aftermarket service network density in Western Australia's Pilbara and Goldfields regions, where lithium spodumene expansion accelerates wear component replacement cycles. Deepen backward integration into manganese steel foundry partnerships to buffer ferroalloy price volatility. Lock in long-term liner supply agreements with state-owned miners in Odisha before distributor competition intensifies. For New Entrants and Emerging Players: BIS certification fast-track for electromagnetic compatibility and safety interlocks unlocks access to India's eastern mineral corridor expansion. Target mobile recycling configurations for German municipal aggregate mandates, where CE marking barriers filter out unqualified competitors. Pursue throughput-based rental partnerships with British Midlands contractors seeking asset-light ballast supply arrangements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with installed base telemetry and predictive maintenance algorithms, positioning them for outcome-based contracting expansion. Acquisition focus should center on regional distributors with manganese liner inventory positioning in Chhattisgarh and Odisha. Monitor EPA enforcement intensity in Arizona and Nevada as signal for dust suppression retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Enables predictive maintenance contracts with Western Australian lithium producers. |
| Backward Integration into Foundry Capacity | Secures manganese steel supply against South African electricity interruption risk. |
| CE Marking Fast-Track Investment | Accelerates market access for mobile units serving German recycling mandates. |
| Regional Distributor Acquisition | Captures aftermarket parts velocity in India's mineral corridor expansion. |
| Trolley-Assist Electrification Partnership | Positions stationary installations for Scandinavian carbon intensity reduction requirements. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC equipment manufacturer filings, and mining project development databases. Interview program coverage spans maintenance directors at Australian iron ore operations, procurement leads at Indian state-owned mining corporations, aftermarket service heads at Nordic OEMs, and plant engineers at German quarry operators. Bottom-up equipment shipment analysis triangulates against top-down mineral extraction capacity expansion tracking across the analysis window.
Segmentation dimensions modeled include product architecture, installation mobility, end-use application intensity, and sales channel structure. CAGRs derive from equipment replacement cycle analysis and greenfield project pipeline assessment. Forecast inputs incorporate ore grade decline trajectories in mature mining districts and circular economy mandate adoption timelines across European municipal procurement.
Underlying assumptions cover sustained infrastructure investment in India's mineral corridor and EPA enforcement continuity in southwestern US surface mining, with deviation risk concentrated in ferroalloy price volatility and foundry capacity utilization shocks. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and local content requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
United States Hand Holes Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Dock Levelers Market