
 Global Light Towers Market | 2026-2036
Global Light Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Light Towers Market Outlook
China is rewriting light tower supply dynamics through expanded manufacturing clusters in Jiangsu and Shandong provinces. Atlas Copco leverages its compressor heritage to dominate mobile lighting rentals across Nordic infrastructure projects. Generac Power Systems anchors North American demand through its dealer network density in utility and construction verticals. Wacker Neuson SE specializes in compact electric units for European urban job sites where noise ordinances tighten.
Light towers are self-contained illumination systems, typically mounted on telescopic masts ranging from 9 to 30 meters, powered by diesel generators, battery packs, or solar arrays with LED lamp banks exceeding 100,000 lumens. These units serve critical visibility functions in construction zones, mining pits, and emergency staging areas where grid power remains unavailable or unreliable. Diesel-powered mobile towers still occupy the largest revenue pool across rental fleets, though solar-hybrid configurations represent the fastest-expanding segment as fuel cost volatility and carbon reporting requirements intensify. The contractor end-user channel controls the dominant procurement volume, while government-led disaster response tenders command premium pricing for rapid-deployment specifications.
EPA Tier 4 Final emission mandates in the United States restrict diesel engine particulate output, pushing fleet operators toward hybrid-electric architectures. The EU F-Gas Regulation and Machinery Directive (2006/42/EC) collectively shape European product compliance, while China's GB standards enforce domestic manufacturing conformity for noise and exhaust parameters. Stakeholders must monitor battery energy density improvements and regional carbon border adjustments to calibrate product roadmaps against shifting total-cost-of-ownership calculations.
Market Dynamics
EPA Tier 4 Final emission mandates are forcing diesel-to-hybrid transitions across rental fleets, compressing total-cost-of-own calculations and rewiring procurement criteria toward lifecycle carbon metrics.
Growth Catalysts
- EPA Tier 4 Final:US emission mandates accelerate diesel-to-hybrid fleet replacement cycles, opening revenue pools for electric-hybrid architectures.
- Mining pit operations:Australian surface extraction sites drive replacement demand as dust ingress degrades legacy lamp housings and mast hydraulics.
- LED lumen density:Solid-state illumination exceeding 100,000 lumens per bank cuts fuel consumption while extending service intervals.
Market Restraints
- Lithium-ion cell volatility:Battery raw material price swings compress margin predictability for hybrid unit manufacturers.
- Jiangsu-Shandong supply concentration:Chinese manufacturing cluster dominance creates single-source vulnerability for global tower assembly.
- Diesel engine residual value collapse:Pre-Tier 4 equipment depreciation accelerates as rental fleets face stranded asset risk.
Strategic Opportunities
- Permian Basin corridor:Texas oilfield contractors seek rapid-deployment solar-hybrid units for 24-hour drilling pad illumination.
- EU F-Gas Regulation:Phase-down of fluorinated gases creates regulatory tailwind for refrigerant-free battery thermal management systems.
- Disaster response tenders:Government-led emergency staging protocols command premium pricing for autonomous, trailer-mounted units.
Industry Challenges
- Telematics integration:Fleet operators struggle to retrofit legacy diesel towers with IoT-enabled fuel monitoring and predictive maintenance.
- CE marking timeline:EU Machinery Directive conformity assessment delays product launches by 8-14 months for non-European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Light Towers Market |
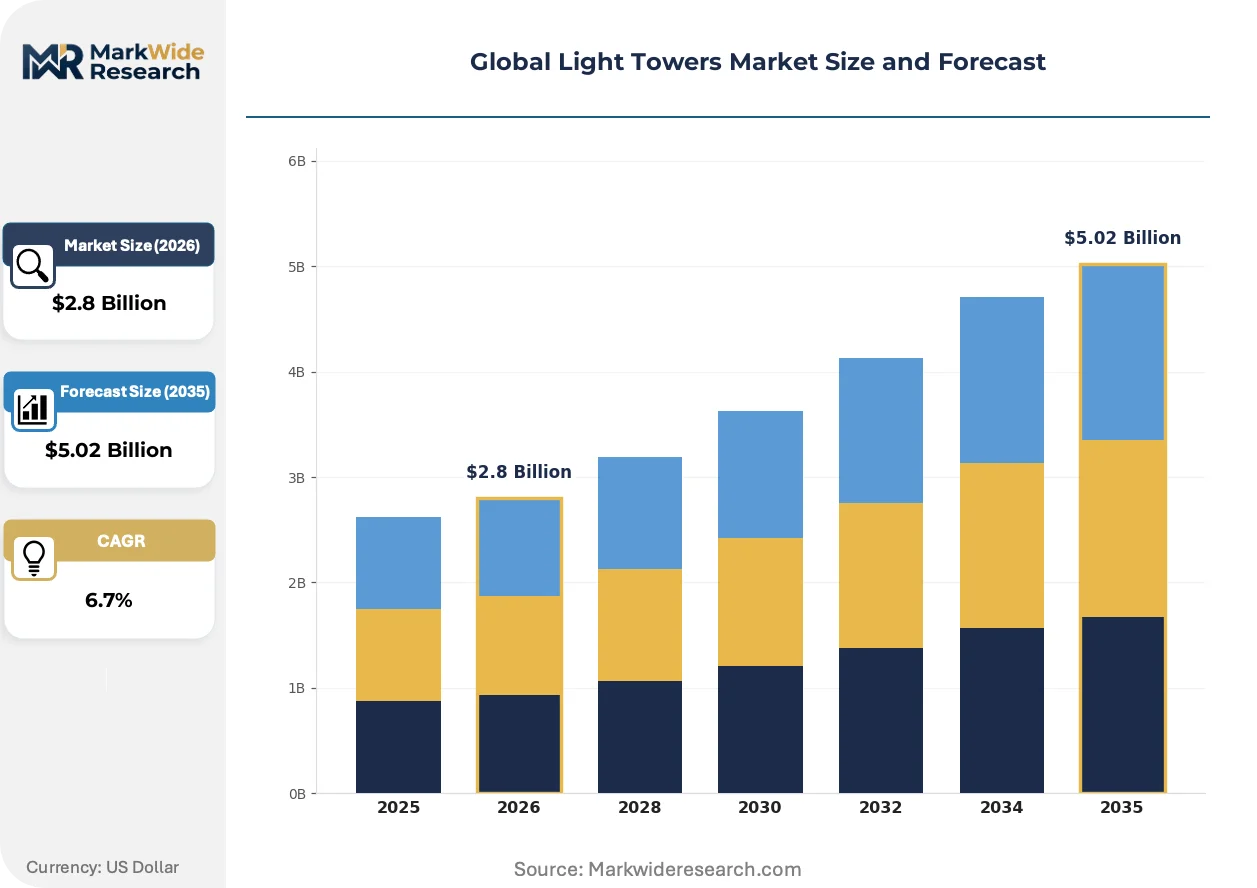
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mobile, Fixed, Solar, Diesel Application: Construction, Mining, Events, Emergency Response End User: Government, Contractors, Industrial, Commercial Power Source: Electric, Hybrid, Fuel, Others |
| Companies Covered | Atlas Copco, Generac Power Systems, Wacker Neuson SE, Terex Corporation, Doosan Portable Power, Larson Electronics, Allmand Bros., Trime, Himoinsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Light Towers Market Strategic Shifts
Illumination technology is migrating from conventional metal-halide lamps toward solid-state LED banks, rewiring powertrain architectures and compressing maintenance schedules across rental fleets.
Solid-state LED technology is migrating from premium positioning to standard fleet specification. Mining contractors in Western Australia now specify LED-only towers for pit operations. The shift enables smaller generator sizing and extends refueling intervals from 72 to 200-plus hours.
EU F-Gas Regulation phase-down mandates are reshaping thermal management design. Battery pack cooling systems must eliminate hydrofluorocarbon refrigerants by 2030. Nordic infrastructure rental fleets face accelerated obsolescence risk for liquid-cooled hybrid units.
Outcome-based rental contracts are displacing traditional equipment purchase in European urban construction. Contractors in Germany and the Netherlands now pay per-lumen-hour rather than daily rates. The model transfers capex burden to lessors while demanding real-time fuel and runtime telemetry.
Global Light Towers Market Segmentation
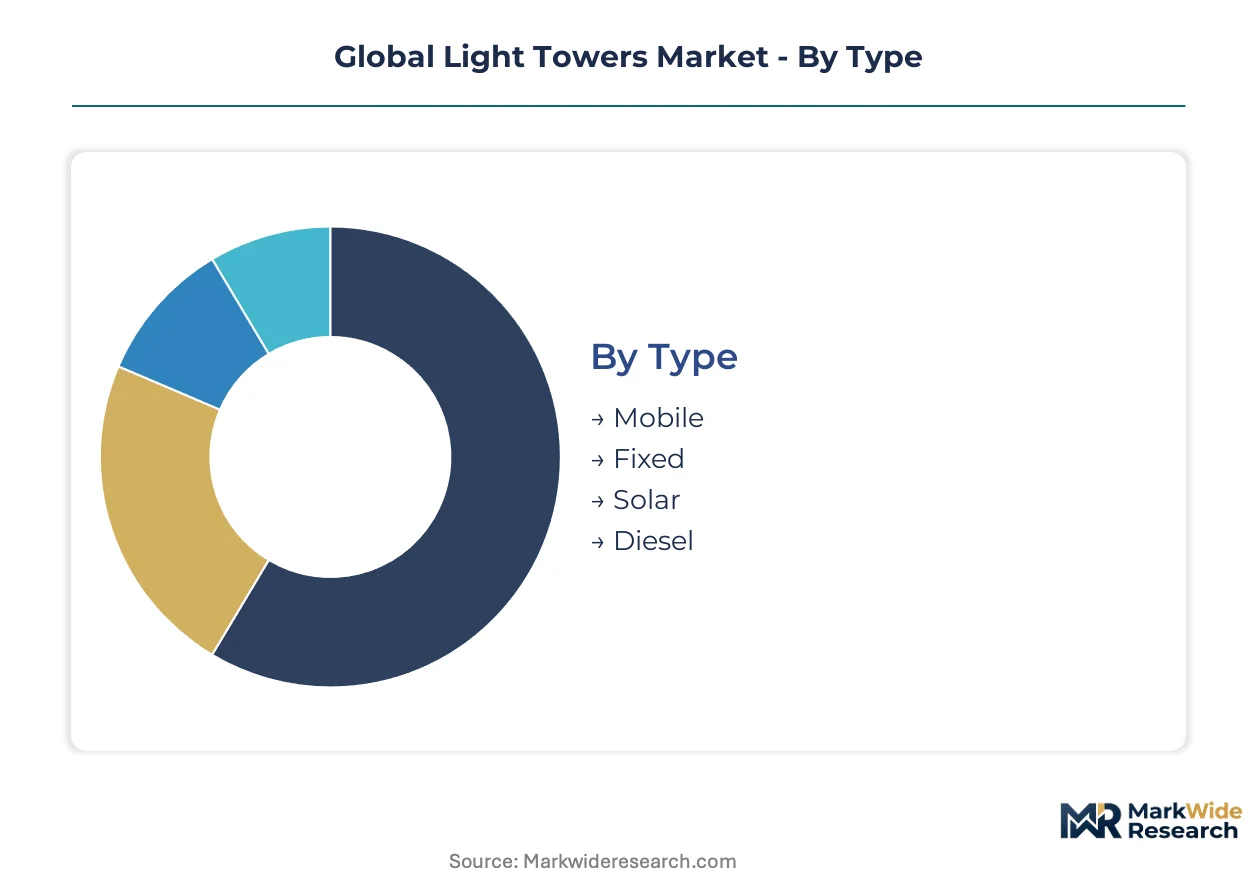
Light tower procurement patterns diverge sharply across mobility requirements, energy architectures, and end-user risk profiles. Rental fleet managers and site operators calibrate specifications against fuel access, deployment duration, and regulatory exposure in each operating jurisdiction.
Type:
Mature diesel-powered units still anchor rental fleet depreciation schedules, while emerging solar-hybrid configurations reset total-cost-of-ownership calculations for carbon-constrained contracts.
- Mobile:Trailer-mounted telescopic masts enable rapid repositioning across construction phases and mining benches. Australian surface extraction contractors specify these for pit perimeter illumination where dust degradation demands frequent relocation.
- Fixed:Permanent-installation towers serve long-duration infrastructure projects and security perimeters. These units dominate airport runway extension contracts in the United States where FAA lighting standards mandate stationary positioning.
- Solar:Photovoltaic arrays with battery storage eliminate refueling logistics for remote deployments. Texas Permian Basin drilling contractors favor these for 24-hour pad illumination where diesel delivery costs erode margins.
- Diesel:Conventional generator-powered towers remain prevalent in emergency response inventories. EPA Tier 4 Final compliance costs are compressing residual values and shortening replacement cycles for pre-2015 fleet assets.
Mobile units handle the majority of throughput; solar configurations are gaining share fastest as fuel volatility intensifies.
Application:
Volume concentrates in earthmoving and extraction operations, while margin accrues to rapid-deployment emergency specifications where procurement timelines compress.
- Construction:General contracting activity drives baseline rental demand for perimeter and task lighting. German and Dutch urban sites increasingly specify electric-hybrid units under tightening municipal noise ordinances.
- Mining:Surface pit operations in Western Australia generate replacement demand as dust ingress degrades legacy lamp housings and mast hydraulics. LED-only specifications now dominate new procurement.
- Events:Temporary outdoor entertainment and sports installations require silent-running electric units. European festival organizers face F-Gas Regulation constraints on battery thermal management systems.
- Emergency Response:Government-led disaster staging protocols command premium pricing for autonomous trailer-mounted units. FEMA and state emergency management agencies in the United States prioritize rapid-deployment solar-hybrid architectures.
Construction absorbs the largest equipment days; emergency response delivers the steepest expansion trajectory as climate-related disaster frequency climbs.
End User:
Procurement authority fragments across public-sector tender protocols and private fleet ownership models, with distinct specification priorities for each.
- Government:Federal and state agencies mandate domestic content and emission compliance above first-cost optimization. U.S. military and disaster response inventories drive demand for autonomous, trailer-mounted solar-hybrid units.
- Contractors:Rental fleet operators and construction subcontractors prioritize utilization rates and maintenance intervals. Outcome-based per-lumen-hour contracts in Germany and the Netherlands transfer capex burden to lessors.
- Industrial:Mining and oilfield operators specify heavy-duty masts and dust-sealed electrical enclosures. Australian iron ore and coal extraction sites generate concentrated replacement demand for LED-only configurations.
- Commercial:Retail, logistics, and entertainment venues require compact electric units for parking lot and loading bay illumination. European urban noise restrictions favor battery-powered alternatives.
Contractors control the dominant procurement volume; government tenders command the highest per-unit pricing for rapid-deployment specifications.
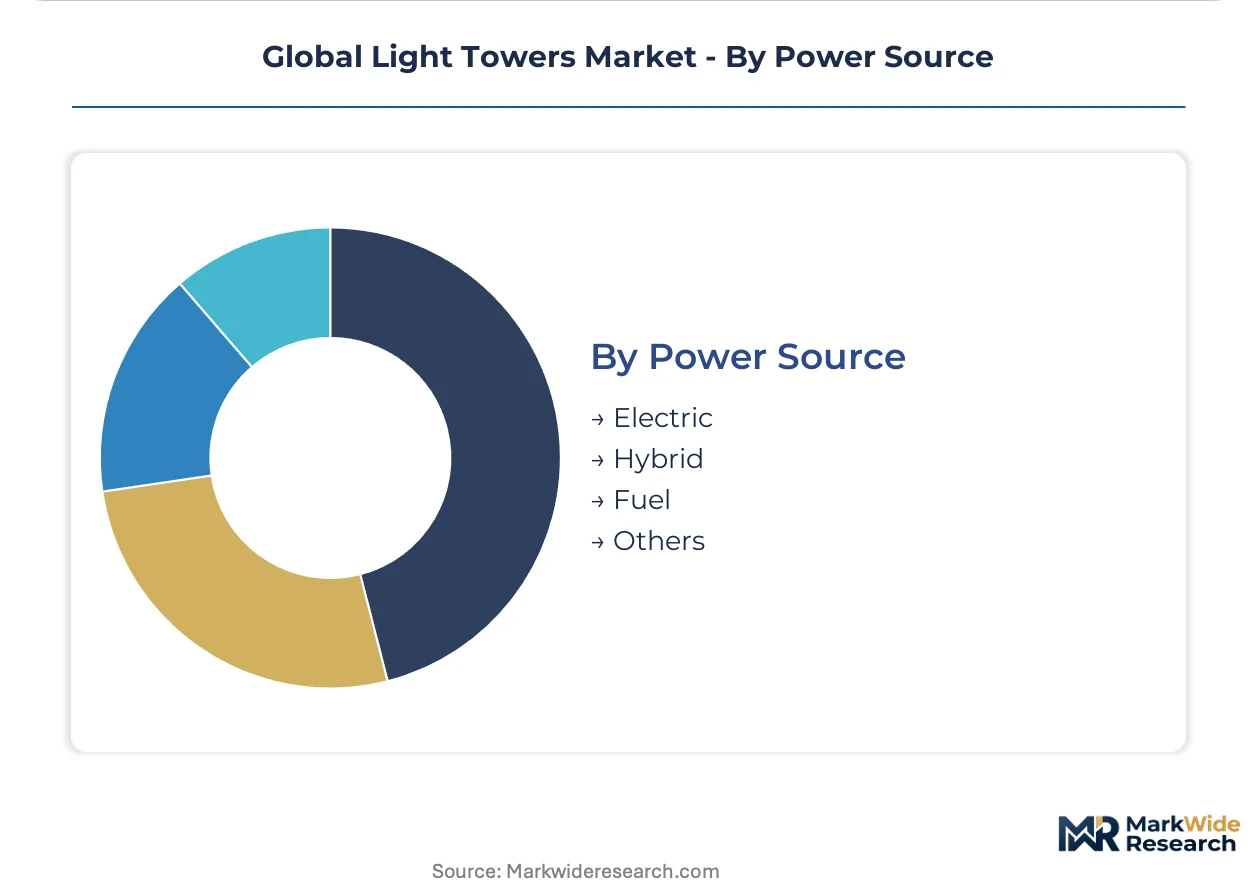
Power Source:
Energy architecture selection increasingly hinges on carbon reporting obligations and regional fuel access economics rather than capital cost alone.
- Electric:Grid-tied or battery-powered units serve urban construction and commercial applications. Nordic infrastructure rental fleets face accelerated obsolescence risk as EU F-Gas Regulation phase-down mandates eliminate hydrofluorocarbon refrigerants.
- Hybrid:Diesel-electric architectures balance runtime flexibility with emission reduction. EPA Tier 4 Final compliance is forcing U.S. rental fleet operators toward these configurations as pure diesel residual values collapse.
- Fuel:Conventional diesel and alternative liquid fuels retain relevance for remote deployments lacking charging infrastructure. Pre-Tier 4 equipment depreciation accelerates as stranded asset risk mounts.
- Others:Hydrogen fuel cell and compressed natural gas prototypes serve niche decarbonization pilots. These configurations remain limited to demonstration projects and subsidy-backed deployments.
Hybrid architectures absorb the largest share of new fleet investment; electric configurations are climbing fastest as battery energy density improves and carbon border adjustments tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Australian mining operators prioritize dust-sealed LED configurations for pit perimeter work, while European urban contractors specify near-silent electric units under tightening municipal noise ordinances. The United States splits between EPA-driven fleet replacement in Texas oilfields and FEMA rapid-deployment tenders for disaster response.
United States
EPA Tier 4 Final mandates compress diesel fleet residual values and accelerate hybrid-electric procurement across rental operators. The Permian Basin corridor in Texas generates concentrated demand for solar-hybrid rapid-deployment units serving 24-hour drilling pad illumination. FEMA and state emergency management agencies command premium pricing for autonomous trailer-mounted configurations.
Australia
Surface extraction operations in Western Australia's Pilbara region drive replacement demand as dust ingress degrades legacy lamp housings and mast hydraulics. LED-only specifications now dominate new procurement for iron ore and coal extraction sites. The country's national mining safety regulator encloses illumination performance standards within broader site compliance frameworks.
Germany
EU F-Gas Regulation phase-down mandates eliminate hydrofluorocarbon refrigerants from battery thermal management systems by 2030, accelerating obsolescence risk for liquid-cooled hybrid units. Outcome-based per-lumen-hour rental contracts displace traditional equipment purchase in urban construction. The country's national industrial standards body shapes conformity assessment timelines for Machinery Directive compliance.
China
GB standards enforce domestic manufacturing conformity for noise and exhaust parameters across Jiangsu and Shandong province production clusters. The Ministry of Ecology and Environment's dual carbon goals redirect export-oriented capacity toward solar-hybrid configurations. Shanghai and Qingdao port infrastructure supports outbound shipment to Southeast Asian and Middle Eastern project sites.
United Arab Emirates
Expo 2020 legacy infrastructure and ongoing logistics corridor development sustain demand for fixed-installation perimeter lighting at airport and seaport extensions. The country's national standards body aligns product certification with Gulf Cooperation Council technical regulations. Dubai and Abu Dhabi municipal procurement favors low-noise electric units for nighttime construction in dense urban districts.
Global Light Towers Market Competitive Environment
Capability concentration sits with specialized manufacturers possessing compressor heritage and rental fleet integration expertise; scale advantage sits with diversified power equipment conglomerates commanding dense distribution networks. The market structures around three tiers: integrated industrial groups with multi-product portfolios, regional specialists focused on compact electric architectures, and contract manufacturers serving private-label demand. Dominant competitive moves include strategic partnerships between tower assemblers and battery cell suppliers, plus backward integration into LED engine production.
Within the integrated industrial tier, Atlas Copco and Generac Power Systems exemplify divergent geographic anchoring strategies. The Swedish industrial group leverages its compressor heritage across Nordic infrastructure rental fleets, while the American power equipment corporation commands North American utility and construction verticals through dealer network density. Wacker Neuson SE occupies a position among European compact equipment specialists, with its German corporate structure signaling engineering-intensive product development.
| Leading Market Players |
|---|
| Atlas Copco |
| Generac Power Systems |
| Wacker Neuson SE |
| Terex Corporation |
| Doosan Portable Power |
| Larson Electronics |
| Allmand Bros. |
| Trime |
| Himoinsa |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Shandong province manufacturing clusters exert asymmetric leverage over global tower assembly costs, with capacity utilization swings in these provinces transmitting directly into OEM pricing power across export markets. Battery cell supply tightness from Korean and Japanese suppliers compounds input cost volatility for hybrid-electric configurations, compressing margin predictability for assemblers lacking captive chemistry partnerships.
Pricing Analysis
North American rental fleets command premium positioning against Asian project tenders, with EPA Tier 4 Final compliance costs widening the spread between certified and pre-standard equipment. Three-tier pricing structure across premium, standard, and economy levels separates LED-hybrid units with telemetry integration from basic diesel towers and stripped emergency-response configurations. Pricing pressure stems from lithium-ion raw material volatility, which erodes manufacturer margins on fixed-price annual contracts. Contractors in German urban construction prove least price-sensitive under outcome-based per-lumen-hour arrangements, while commodity rental operators in Texas oilfields prioritize acquisition cost above lifecycle metrics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for tower assemblers serving North American demand. Component sourcing concentrates in China for steel mast fabrication, South Korea for lithium-ion cell supply, and Germany for precision hydraulic systems. LED engine and battery thermal management subsystems draw from Taiwanese and Japanese electronics corridors. Single-source vulnerability concentrates in Jiangsu province stamping operations for telescopic mast sections. Distribution runs through national rental fleet operators in developed markets and EPC contractor direct procurement in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final emission mandates and EU F-Gas Regulation phase-downs are forcing simultaneous powertrain and thermal management redesigns, creating a compressed window for technology transition. This regulatory inflection rewards manufacturers with integrated R&D and captive battery supply.
For Market Incumbents: Insulate core rental fleet relationships by accelerating backward integration into LED engine production and securing multi-year lithium supply offtakes. Pre-Tier 4 diesel residual value collapse threatens stranded asset exposure for pure-play rental operators lacking hybrid transition roadmaps. Capacity addition in Vietnamese assembly plants mitigates tariff exposure for North American-bound shipments. For New Entrants and Emerging Players: Southeast Asian infrastructure corridors present the most penetrable geographic entry point, with Indonesian and Vietnamese project developers specifying solar-hybrid units for port and logistics zone construction. White-space exists in compact electric architectures for European urban noise-restricted job sites. Target outcome-based rental contracts in German and Dutch metropolitan construction as the go-to-market anchor, transferring capex burden to lessor balance sheets while demonstrating runtime telemetry capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized lighting tower divisions lacking battery chemistry partnerships. Long-term viability hinges on regulatory compliance agility across EPA, EU F-Gas, and Chinese dual carbon frameworks. Mid-cap specialists with captive LED production and established rental fleet telemetry integration represent priority acquisition archetypes. Battery energy density improvements and regional carbon border adjustment implementations serve as the critical signal to watch for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium-ion cell allocation from Korean suppliers for hybrid tower production scaling. |
| LED Engine Backward Integration | Captures lumen density improvements and reduces dependency on Taiwanese optics suppliers. |
| Telemetry Platform Integration | Enables per-lumen-hour outcome contracting for German and Dutch urban rental fleets. |
| Geographic Manufacturing Footprint | Vietnamese assembly capacity circumvents tariff exposure on US-bound tower shipments. |
| Green Certification Program | Aligns product portfolios with EU F-Gas Regulation and Chinese dual carbon compliance timelines. |
Study Parameters
Initial hypotheses were tested against primary input from rental fleet operations directors, construction procurement managers, mining site engineers, and battery supplier account executives and refined through secondary validation. Primary fieldwork combined structured interviews with equipment lessors across Nordic, North American, and Australian markets with technical consultations at Jiangsu and Shandong manufacturing facilities. Secondary sources included EPA engine certification databases, EU Machinery Directive conformity assessment records, customs trade data for steel mast and LED component flows, and SEC filings from publicly traded power equipment conglomerates. Bottom-up unit economics from rental fleet depreciation schedules were triangulated against top-down market sizing from national construction and mining output projections.
Demand-supply balance framing anchored the analytical approach, with deployment modeling across the projection horizon calibrated against regional fuel access economics and carbon reporting obligation intensity. Segmentation dimensions included mobility configuration, energy architecture, end-user risk profile, and application-specific illumination performance requirements. CAGRs were derived from equipment replacement cycle compression analysis and rental fleet utilization rate trajectories. Forecast inputs incorporated battery energy density improvement curves and regional emission standard implementation timelines without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed manufacturers or sudden lithium supply disruption would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Crane Buffer Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Utility Locator Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Pressure Washer Market
Construction Equipment
India Crane Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Roadheaders Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Fogging Machine Market