
 Cementing Accessories Market | 2026-2036
Cementing Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Cementing Accessories Market Analytics
API Specification 10D is rebalancing the cost-of-entry calculus for cementing accessories suppliers seeking offshore qualification. Halliburton leverages its integrated service model to dominate deepwater project bundling across the Gulf of Mexico. Schlumberger anchors its position through R&D intensity in composite centralizer designs that reduce trip times. Baker Hughes differentiates via manufacturing scale across multiple steel grades and rubber compounds.
Cementing accessories comprise mechanical devices including centralizers, float equipment, casing accessories, and packers manufactured from steel, composite, rubber, or plastic formulations to ensure proper casing placement and zonal isolation during well construction. These components operate under downhole pressures exceeding 10,000 psi and temperatures above 150°C in deep well applications. Float equipment represents the most mature product category with established margin pools, while composite material formulations represent the fastest-growing segment as operators seek weight reduction and corrosion resistance. Application demand concentrates in oil and gas drilling where well complexity drives premium accessory specification, though mining and infrastructure segments sustain steady procurement of standard steel centralizers.
API standards, the EPA's methane emissions monitoring framework, and BSEE well integrity regulations collectively shape product certification requirements and demand specifications across U.S. offshore and onshore operations. The EPA's New Source Performance Standards for oil and gas facilities directly influence packer and seal material selection to minimize fugitive emissions during completion activities. Stakeholders must monitor evolving well integrity mandates and material traceability requirements as regulators tighten documentation standards for subsea installations.
Market Dynamics
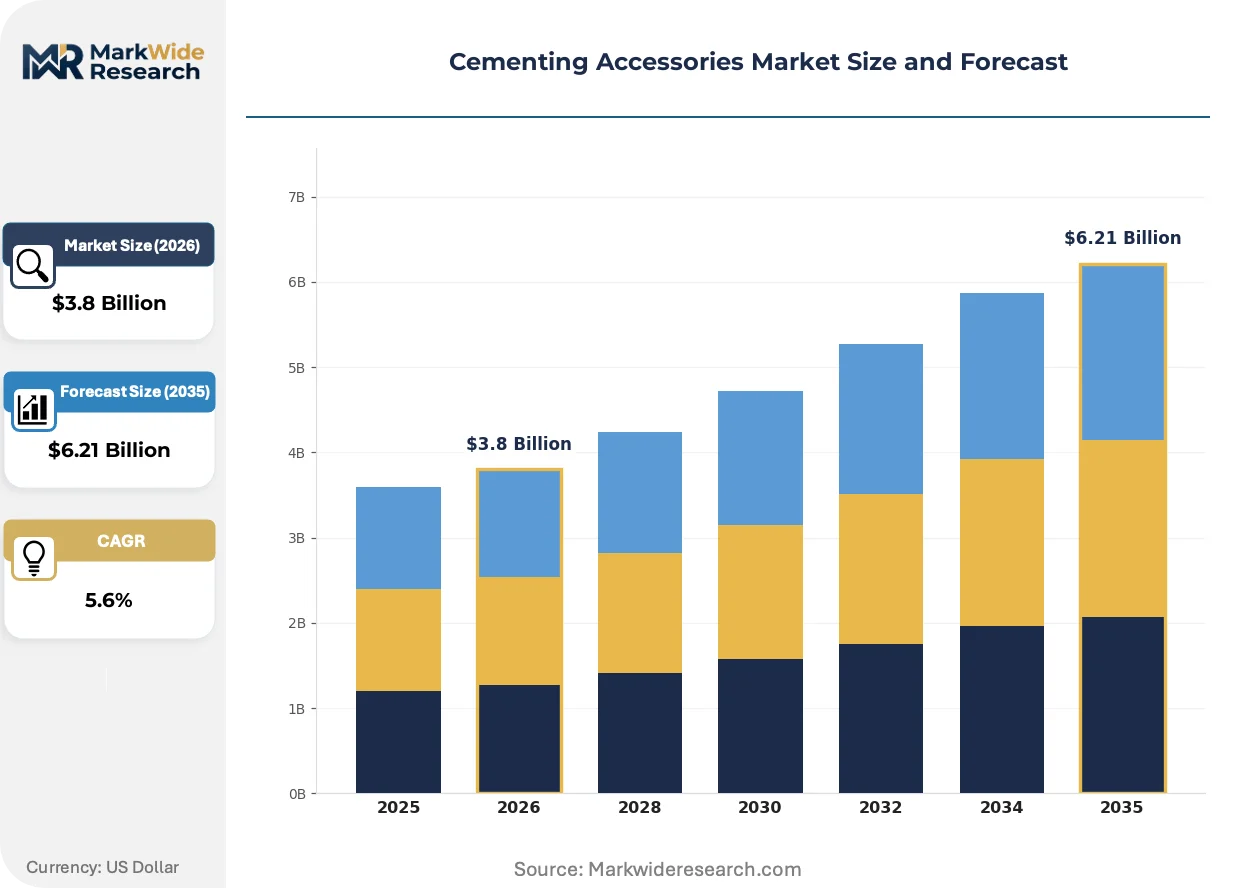
Deepwater complexity in the Gulf of Mexico is forcing operators to specify premium-grade centralizers and float equipment that withstand 15,000 psi pressures and temperatures exceeding 175°C. This technical escalation is compressing supplier margins while raising certification barriers for market entry.
Growth Catalysts
- Horizontal Well Complexity:Extended-reach laterals in Texas and Louisiana shale basins require rigid centralizer designs that maintain standoff across 10,000-foot horizontal sections. Service companies are standardizing API Specification 10D-certified accessories to reduce non-productive time.
- EPA Methane Framework:The EPA's New Source Performance Standards mandate fugitive emissions monitoring during completion activities. Packer and seal manufacturers are qualifying fluoropolymer compounds that maintain integrity under cyclic pressure loading.
- Composite Material Transition:Corrosion-resistant centralizer formulations are displacing traditional steel in sour gas environments. Weight reduction of 40-60% per joint reduces rig hoisting requirements and trip times.
Market Restraints
- Steel Price Volatility:Alloy steel and chromium-molybdenum bar stock account for 35-45% of centralizer manufacturing cost. Input cost swings compress margin predictability for forged-product suppliers.
- Supplier Concentration:Deepwater qualification requires BSEE-approved manufacturing facilities concentrated along the US Gulf Coast. Limited third-party testing capacity extends certification timelines.
- Technical Limitation:Elastomer packer elements degrade in high-H2S environments above 50 ppm. Material science gaps restrict application in certain Permian Basin sour zones.
Strategic Opportunities
- Carbon Capture Wells:Class VI injection well construction requires cementing accessories rated for CO2 exposure. Manufacturers qualifying corrosion-resistant packers for 30-year design life will capture early specification lock-in.
- Geothermal Expansion:Enhanced geothermal systems in Nevada and Utah require centralizers engineered for 200°C+ static temperatures. Product lines proven in oilfield service can transfer to this adjacent demand.
- Digital Integration:RFID-embedded centralizers enabling real-time casing standoff verification during cementing operations. Operators in the Bakken formation are piloting this technology to reduce remedial squeeze cementing.
Industry Challenges
- API 10D Certification Timeline:Third-party testing for centralizer start and running forces requires 90-120 days. Extended qualification cycles delay product launches and revenue recognition.
- Legacy Equipment Interoperability:New composite centralizer designs must interface with existing casing running tools. Engineering teams face compatibility testing burdens across multiple OEM tool configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cementing Accessories Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralizers, Float Equipment, Casing Accessories, Packers Application: Oil & Gas, Mining, Construction, Infrastructure End User: Energy Companies, Contractors, Service Providers, Consultancies Material: Steel, Composite, Rubber, Plastics |
| Companies Covered | Halliburton, Schlumberger, Baker Hughes, Weatherford, NOV, China Oilfield Services, ChampionX, NexTier Oilfield Solutions, Advanced Cementing Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cementing Accessories Market Evolving Landscape
Material substitution and digital verification protocols are compressing traditional equipment lifecycles while opening specification windows for advanced formulations. Suppliers must now engineer for simultaneous weight reduction, corrosion immunity, and real-time performance visibility.
Composite centralizer technology is modularizing field deployment across the Permian and Eagle Ford basins. These glass-reinforced polymer designs reduce single-joint weight from 45 pounds to 18 pounds while maintaining 67% standoff in deviated wellbores. Operators running 200-plus casing joints per well are specifying composite systems to reduce rig crew fatigue and accelerate trip times.
The EPA's methane emissions monitoring framework is redefining packer seal specifications for completion operations. Fluorocarbon and perfluoroelastomer compounds are displacing nitrile rubber in high-pressure gas wells where fugitive emissions thresholds tighten annually. Manufacturers with pre-qualified material traceability documentation are capturing preferred-vendor status with integrated service companies.
Buyer consolidation among Permian Basin independents is compressing procurement cycles and unbundling after-sales service contracts. Large private-equity-backed producers are centralizing accessory specification across drilling programs, forcing distributors to carry deeper inventory of API-certified stock. This concentration is visible most acutely in Midland-Odessa supply yards where same-day centralizer availability determines vendor selection.
Cementing Accessories Market Segmentation
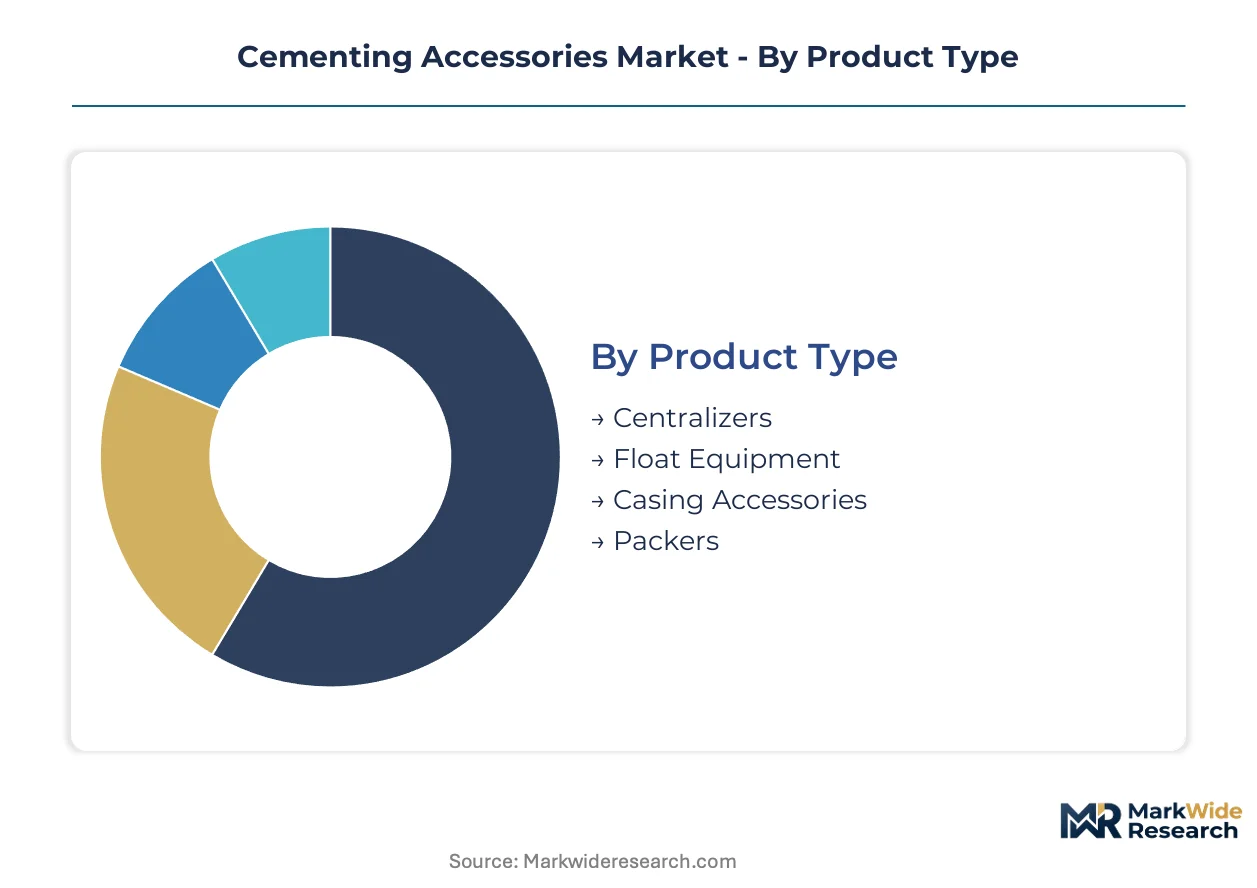
Segmentation in cementing accessories reveals how certification requirements, material specifications, and end-use complexity fragment procurement patterns across well construction workflows. Understanding these divisions exposes where margin pools concentrate and where technical barriers protect incumbent positions.
Product Type:
API 10D certification mandates reallocate supplier qualification burdens unevenly across product categories, with centralizers and float equipment facing the most stringent third-party testing protocols.
- Centralizers:Rigid and bow-spring designs manufactured from steel or composite formulations maintain casing standoff during cement placement. Demand clusters in Texas and Louisiana horizontal wells where extended-reach laterals require 67% minimum standoff across 10,000-foot sections. API Specification 10D start-force and running-force testing extends qualification timelines to 90-120 days.
- Float Equipment:Float collars and shoes prevent cement backflow while enabling casing running operations. Gulf of Mexico deepwater projects specify premium grades rated for 15,000 psi and 175°C, compressing supplier margins while raising technical barriers. This category commands the most mature margin pools in the product mix.
- Casing Accessories:Stop collars, cement baskets, and scratchers manufactured to operator-specific lengths and thread configurations. Standard steel variants serve mining and infrastructure with minimal certification overhead.
- Packers:Elastomer-element seals for zonal isolation during completion and production. EPA methane monitoring frameworks are forcing fluoropolymer compound qualification for high-pressure gas applications.
Leading the category by volume: Centralizers. Growing fastest: Composite-formulation centralizers climbing on weight-reduction specifications.
Application:
Application segmentation maps directly to performance tier requirements, with oil and gas commanding premium specifications while mining and construction sustain standardized procurement.
- Oil & Gas:Exploration and production operations specify API-certified accessories for well integrity assurance. Deepwater Gulf of Mexico complexity drives premium centralizer and float equipment procurement with full material traceability documentation.
- Mining:Borehole stabilization in mineral extraction employs standard steel centralizers with minimal elastomer content. Procurement concentrates on durability in abrasive drilling environments rather than pressure-temperature extremes.
- Construction:Geotechnical drilling and foundation work utilizes basic casing accessories without API certification requirements. Volume demand tracks infrastructure spending cycles in urban corridor development.
- Infrastructure:Tunnel boring and micro-piling operations require corrosion-resistant centralizers for groundwater exposure. Specifications prioritize longevity over real-time performance monitoring.
Highest specification density: Oil & Gas. Steadiest replacement demand: Mining and Infrastructure.
End User:
End user structure determines contract bundling patterns, with integrated service companies capturing specification authority while independents fragment procurement decisions.
- Energy Companies:Supermajors and national oil companies set technical standards that cascade through supply chains. Their master service agreements lock in preferred vendors for multi-year drilling programs.
- Contractors:Drilling contractors operating on day-rate contracts prioritize accessory availability over specification optimization. Same-day centralizer availability in Midland-Odessa supply yards determines vendor selection.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle cementing accessories within integrated well construction packages. Their procurement volumes shape manufacturer product development roadmaps.
- Consultancies:Engineering firms specify accessories for third-party well design validation. Their influence concentrates in carbon capture and geothermal project certification.
Dominant procurement authority: Service Providers. Fastest-expanding influence: Consultancies on energy transition projects.
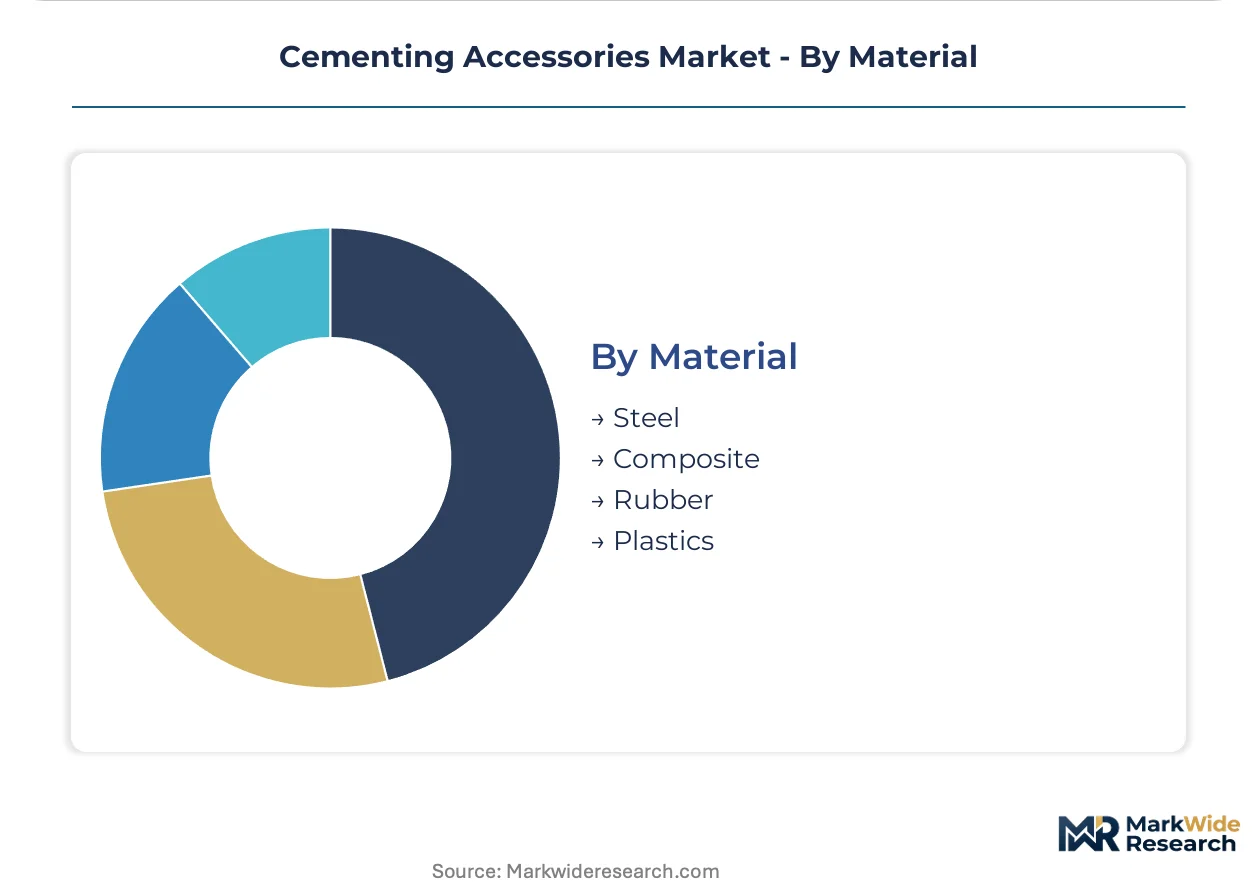
Material:
Material selection bifurcates on corrosion resistance versus cost, with sour gas environments and weight-sensitive operations driving formulation transitions.
- Steel:Forged alloy and chromium-molybdenum bar stock centralizers dominate standard oilfield applications. Input cost volatility in alloy steel accounts for 35-45% of manufacturing cost, compressing margin predictability.
- Composite:Glass-reinforced polymer formulations reduce single-joint weight from 45 pounds to 18 pounds while maintaining standoff performance. Permian and Eagle Ford operators running 200-plus casing joints per well specify composites to accelerate trip times.
- Rubber:Nitrile and hydrogenated nitrile elastomers serve packer elements in standard pressure-temperature windows. High-H2S environments above 50 ppm degrade rubber compounds, restricting application in certain Permian Basin zones.
- Plastics:Thermoplastic centralizers address low-load mining and construction applications with minimal corrosion concerns. Cost positioning enables volume penetration in price-sensitive procurement.
Highest volume material: Steel. Steepest adoption curve: Composite formulations displacing steel in deviated wellbores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor anchors cementing accessories manufacturing through Louisiana's Port of South Louisiana Foreign Trade Zone and Texas Enterprise Zone incentives that concentrate forging and composite fabrication capacity.
United States
Horizontal drilling intensity in the Permian Basin and Eagle Ford shale drives procurement of API 10D-certified centralizers for extended-reach laterals. EPA New Source Performance Standards mandate fugitive emissions monitoring that shapes packer seal specifications. Midland-Odessa supply yards operate as same-day fulfillment hubs where inventory depth determines vendor selection among drilling contractors.
Canada
Montney and Duvernay shale development in Alberta and British Columbia requires cold-weather-rated cementing accessories for sub-zero operating conditions. The Canadian Environmental Protection Act governs material traceability for subsea installations in Atlantic offshore fields. Calgary-based engineering consultancies specify accessories for carbon capture injection well projects seeking Class VI certification.
Saudi Arabia
Aramco's unconventional gas program in the Jafurah Basin is expanding horizontal well construction requiring premium centralizer specifications. The Saudi Standards, Metrology and Quality Organization enforces conformity assessment for oilfield equipment imports. Dammam's King Abdulaziz Port industrial zone hosts regional distribution centers serving Eastern Province drilling operations.
China
Sinopec and PetroChina shale gas development in Sichuan Basin is scaling composite centralizer procurement for weight-sensitive mountain drilling operations. GB standards administered by SAMR govern oilfield equipment certification alongside API specifications. Chengdu and Chongqing manufacturing clusters produce glass-reinforced polymer formulations for domestic and export markets.
United Arab Emirates
ADNOC's offshore expansion in the Upper Zakum and Umm Shaif fields drives specification of high-pressure float equipment rated for 175°C bottom-hole temperatures. The Emirates Authority for Standardization and Metrology coordinates with API for dual-certification acceptance. Jebel Ali Free Zone concentration enables re-export logistics serving Iraq and North African drilling markets.
Cementing Accessories Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered qualification requirements. The vendor base stratifies between integrated service companies bundling accessories within drilling contracts and independent manufacturers supplying catalog products to distributors. Three archetypes dominate: full-service oilfield conglomerates with captive accessory production, specialized centralizer and float equipment fabricators with API certification depth, and regional metal-forming shops serving mining and construction with non-certified standard products. Competitive moves center on composite material R&D partnerships and backward integration into polymer compounding to control formulation costs.
Within the integrated service tier, Halliburton, Schlumberger, and Baker Hughes occupy positions that exemplify bundling power across Gulf of Mexico deepwater projects. These Houston-based entities anchor procurement specification authority through master service agreements that cascade technical requirements to their approved vendor lists. Their scale advantages concentrate in qualification documentation and multi-year program commitments that independent fabricators cannot match.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Baker Hughes |
| Weatherford |
| NOV |
| China Oilfield Services |
| ChampionX |
| NexTier Oilfield Solutions |
| Advanced Cementing Services |
| Others |
Value Network & Pricing Analysis
Alloy steel and chromium-molybdenum bar stock indices cascade through cementing accessories manufacturing, compressing margin pools for forged-product suppliers while amplifying pricing power for composite-formulation producers with polymer compounding control.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with same-day centralizer availability in Midland-Odessa supply yards commanding 15-25% markups over standard delivery windows. Contract-based long-term offtake agreements anchor volume procurement for integrated service companies, while spot inventory discounts attract price-sensitive drilling contractors operating on day-rate contracts. Certification grade and API Specification 10D documentation status drive price differentiation, with BSEE-approved offshore-qualified products sustaining margin premiums. Price erosion runs through standard steel centralizer tiers as buyer consolidation among Permian Basin independents intensifies competitive bidding.
Supply Chain Analysis
Specialty polymer compounding capacity rests on US Gulf Coast petrochemical corridors and Chinese glass-reinforced polymer manufacturing clusters in Chengdu and Chongqing. Chromium-molybdenum steel bar stock, nitrile rubber compounds, and fluoropolymer elastomers constitute critical input dependencies. Single-source vulnerability concentrates in BSEE-approved testing facilities along the Louisiana-Texas coastline, where limited third-party capacity extends certification timelines. Distribution runs through master service agreements with integrated oilfield service companies, supplemented by regional distributor networks serving independent drilling contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite centralizer technology is displacing legacy steel formulations across horizontal well construction, creating specification windows for corrosion-resistant, weight-optimized product lines.
For Market Incumbents: Anticipate margin compression in standard steel centralizer categories as Chinese composite manufacturers achieve API 10D certification depth. Defensive consolidation through backward integration into polymer compounding secures formulation cost control. Prioritize R&D investment in RFID-embedded centralizers for real-time cementing verification, locking in technology differentiation before digital integration becomes table stakes. For New Entrants and Emerging Players: EPA New Source Performance Standards in the United States open a window for fluoropolymer packer specialists with pre-qualified material traceability documentation. Carbon capture injection well construction and enhanced geothermal systems in Nevada and Utah represent the most penetrable white-space targets, with engineering consultancies serving as specification gatekeepers. Pursue consultative go-to-market positioning targeting Class VI certification projects. For Investors and Strategic Acquirers: Distressed-cycle entries favor API-certified composite centralizer fabricators with established BSEE qualification in the US Gulf Coast region. Long-term viability hinges on 30-year design life capabilities for CO2-exposure applications. Watch composite material adoption rates in Permian Basin horizontal wells as the inflection indicator for technology-transition momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material R&D Partnership | Glass-reinforced polymer formulations reduce joint weight 40-60% while maintaining API 10D standoff performance. |
| Backward Integration into Polymer Compounding | In-house formulation control insulates margin pools from specialty chemical price volatility. |
| RFID-Enabled Digital Integration | Real-time casing standoff verification reduces remedial squeeze cementing in Bakken formation pilots. |
| Carbon Capture Well Certification | Class VI injection well qualification locks in 30-year specification authority for corrosion-resistant packers. |
| Geothermal Product Line Extension | 200°C-rated centralizers transfer oilfield proven designs to Nevada and Utah enhanced geothermal demand. |
Research Methodology
SEC 10-K filings, BSEE well integrity reports, and API certification databases formed the secondary backbone, supplemented by customs records tracking alloy steel and polymer compound trade flows. Primary interviews with drilling contractors, cementing service engineers, procurement managers at integrated oilfield service companies, and composite material R&D directors validated demand specifications and technology adoption timelines. Bottom-up triangulation across product category volumes and top-down macroeconomic anchoring ensured forecast consistency.
Historical trendline analysis established baseline growth patterns across centralizer, float equipment, and packer categories, with segmentation modeling by material formulation, application complexity tier, and end-user procurement authority. CAGRs were derived through regression analysis of drilling activity indicators and accessory specification intensity across the projection horizon. Forecast inputs incorporated horizontal well length trajectories, EPA regulatory implementation schedules, and composite material penetration curves in deviated wellbore applications.
Caveats apply where steel price volatility, BSEE regulatory amendments, or composite material qualification delays could materially shift the outlook. Forecasts reflect documented assumptions regarding drilling program continuity and certification timeline stability. A small set of triggers—API specification revisions, methane monitoring threshold adjustments, and geothermal project development acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Europe Crane Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Induction Furnace Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Jackhammer Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Multi Attachment Loaders Market