
 Plasma Cutting Machine Market | 2026-2036
Plasma Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Cutting Machine Market Analysis
China is rewriting capacity dynamics for plasma cutting equipment as domestic fabricators expand production lines to serve shipbuilding and heavy machinery demand. Hypertherm leverages its technology leadership in high-definition plasma systems to sustain premium positioning across North American and European accounts. ESAB Corporation anchors its competitive stance through backward integration into consumables and torch technology. Miller Electric Mfg. LLC differentiates via channel control and brand strength in the contractor and fabrication shop segments.
A plasma cutting machine generates an electrically conductive channel of ionized gas to sever electrically conductive metals at temperatures exceeding 20,000°C, serving primary industrial purposes in steel fabrication, shipbuilding, and automotive manufacturing. CNC mechanized systems dominate the product type landscape due to repeatability requirements in high-volume production environments. Hybrid plasma technology captures expanding margin pools as fabricators seek reduced dross and faster cut speeds on stainless and aluminum grades. The aerospace end user segment specializes in precision-thickness applications where tolerance control justifies equipment premiumization.
The EPA enforces emission standards that shape plasma cutting equipment specifications for particulate and fume capture in US fabrication facilities. China's MEE implements dual carbon goals that accelerate demand for energy-efficient plasma systems with reduced auxiliary power consumption. OSHA workplace exposure limits and REACH substance restrictions in Europe further constrain consumable chemistry and ventilation design. Stakeholders must monitor how evolving carbon border adjustments and local content requirements reshape equipment procurement criteria across major fabrication economies.
Market Dynamics
Shipbuilders in South Korea and heavy machinery fabricators in China are pulling plasma cutting equipment toward higher automation, while dual carbon mandates from China's MEE force energy-efficiency redesigns across supplier portfolios.
Growth Catalysts
- Dual carbon goals:China's MEE emission standards compel fabricators to retire legacy oxy-fuel systems and adopt plasma alternatives with lower auxiliary power draw and fume capture integration.
- CNC mechanized systems:Automotive and aerospace production lines demand repeatability thresholds that only automated plasma platforms achieve, locking in equipment refresh cycles.
- Stainless and aluminum grades:Hybrid plasma technology expands addressable metal thickness ranges, opening precision applications in chemical processing and food equipment fabrication.
Market Restraints
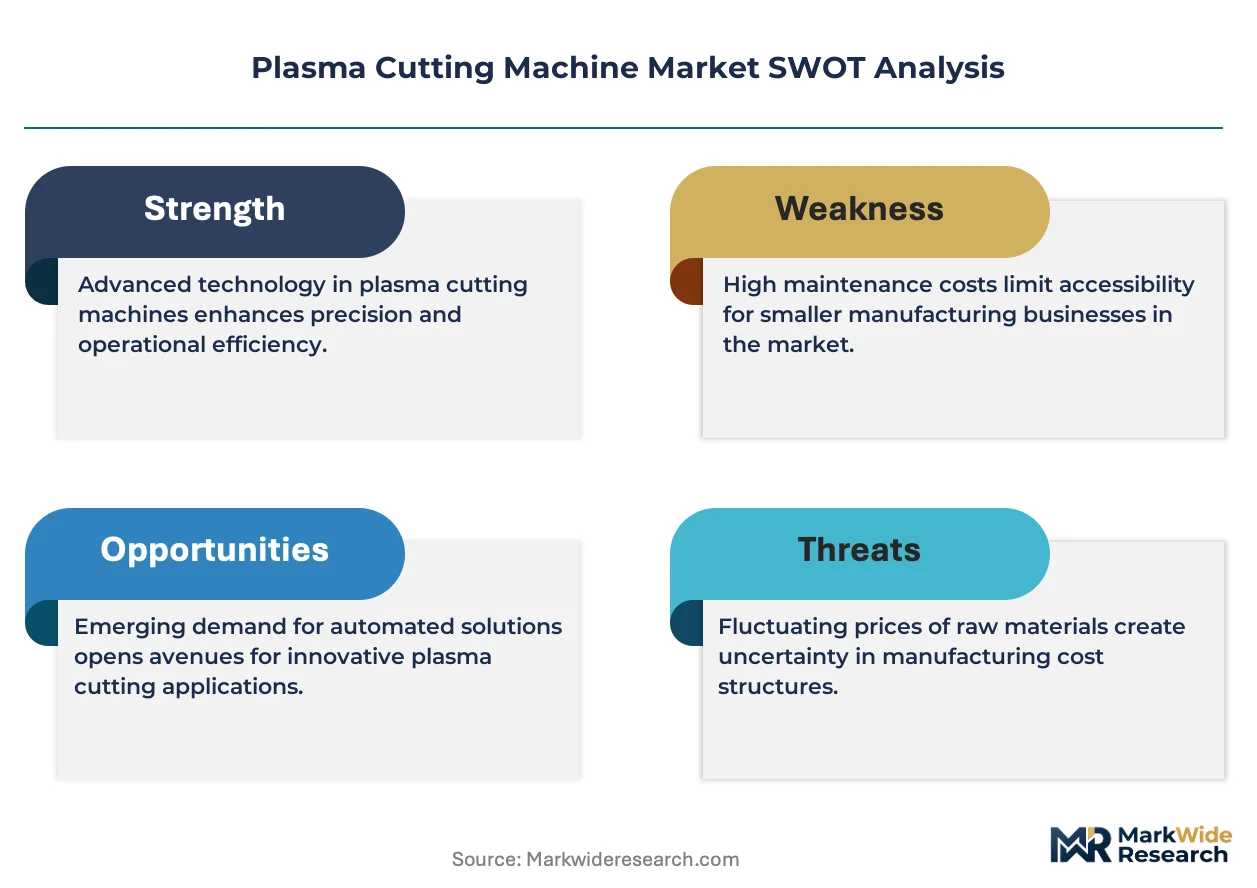
- Consumables cost volatility:Electrode and nozzle replacement cycles impose recurring opex burdens that oxy-fuel competitors exploit in price-sensitive contract bidding.
- Supply concentration in torch technology:Proprietary torch architectures from dominant North American and European vendors create vendor lock-in and limit second-source availability.
- Technical limitation on non-conductive materials:Plasma systems cannot process composites or ceramics, excluding the technology from expanding wind turbine blade and electric vehicle battery tray segments.
Strategic Opportunities
- Underpenetrated Indian fabrication:India's PLI scheme for capital goods and infrastructure build-out creates first-mover positioning for automated plasma system providers in shipbreaking and structural steel.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms favor low-emission plasma cutting over imported oxy-fuel equipment in European steel service centers.
- Technology convergence with IoT:Real-time cut quality monitoring and predictive maintenance algorithms differentiate equipment offerings in German and Japanese precision metalworking clusters.
Industry Challenges
- CNC programming skill gap:Fabrication shops lack operators capable of nesting optimization and parameter tuning for high-definition plasma systems, slowing adoption in mid-tier contract manufacturers.
- Certification timeline for aerospace:AS9100 and NADCAP accreditation requirements for precision-thickness plasma cutting extend sales cycles by twelve to eighteen months in defense and commercial aviation supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Cutting Machine Market |
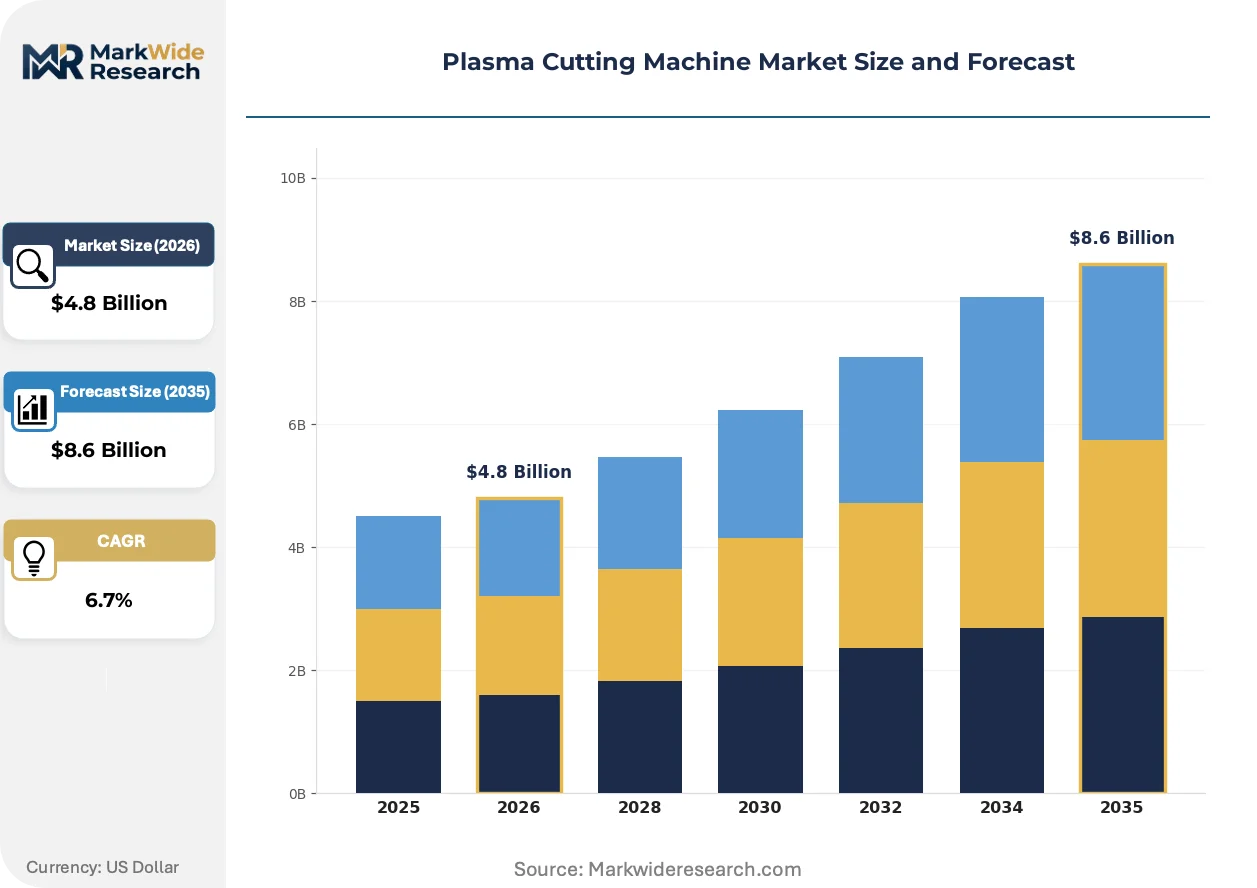
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Mechanized, CNC, Automated Technology: Air Plasma, Hybrid Plasma, Water Plasma, Plasma Arc End User: Manufacturing, Construction, Automotive, Aerospace Installation: Portable, Fixed, Table-Top, Industrial |
| Companies Covered | Messer Cutting Systems, Miller Electric Mfg. LLC, Hypertherm, TRUMPF, Komatsu NTC, ESAB Corporation, Kjellberg Finsterwalde, DAIHEN Corporation, Lincoln Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Cutting Machine Market Emerging Trajectories
Plasma cutting equipment is undergoing a technology refresh driven by digitization of process control, tightening emission compliance, and evolving procurement patterns among metal fabricators.
High-definition plasma systems are digitizing cut process parameters through embedded sensors and edge computing modules. Aerospace manufacturers in Germany and Japan deploy these platforms for real-time kerf width adjustment. The technology is digitizing quality assurance workflows, compressing inspection labor and scrap rates in precision-thickness applications.
REACH substance restrictions in Europe constrain consumable chemistry formulations for electrodes and nozzles. Manufacturers reformulate copper-hafnium alloys to eliminate restricted substances while maintaining arc stability. European fabrication facilities face accelerated compliance timelines, driving preference for suppliers with pre-certified consumable portfolios.
Metal service centers are unbundling equipment purchases from long-term consumables contracts. Buyers in the United States negotiate separate sourcing for torches, electrodes, and shielding gas, pressuring traditional bundled pricing models. This pattern is most visible in independent steel processing facilities across the Midwest and Southeast.
Plasma Cutting Machine Market Segmentation
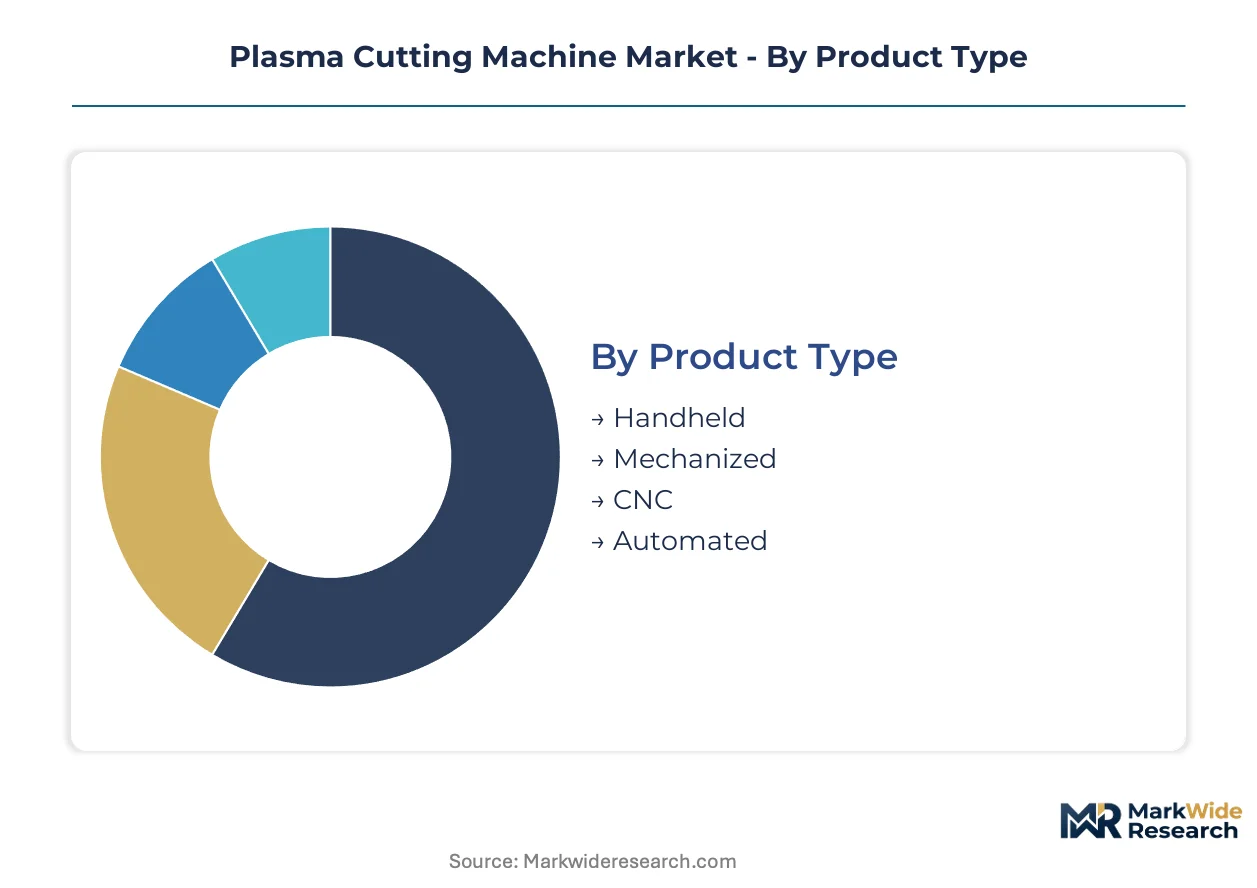
Plasma cutting equipment segments diverge sharply by automation level and power source chemistry, with procurement patterns tracking end-use precision requirements and facility infrastructure constraints. Understanding these divides reveals where margin pools concentrate and which technology transitions are accelerating.
Product Type:
Mature CNC platforms anchor revenue while handheld systems retain niche utility in field service applications.
- CNC:Computer-numerical control architectures integrate motion planning with plasma power modulation for repeatability within 0.1mm tolerance. Automotive stamping plants in Germany and Japan deploy these systems for high-volume blanking operations where scrap reduction justifies capital intensity. Dual carbon mandates from China's MEE accelerate replacement of legacy oxy-fuel lines with CNC plasma in heavy machinery fabrication.
- Automated:Robotic material handling and nesting software eliminate operator intervention across multi-shift operations. Shipbuilders in South Korea specify automated gantries for hull section cutting, driven by labor cost pressures and dimensional accuracy requirements for modular construction. Integration with MES platforms enables real-time production scheduling adjustments.
- Mechanized:Tractor-based or track-mounted systems bridge manual and fully automated workflows for mid-volume fabricators.
- Handheld:Torch-and-power-pack combinations serve maintenance crews and construction sites without fixed infrastructure.
CNC handles the majority of throughput; automated is expanding most quickly as robotics costs decline and fabricators pursue lights-out operation.
Technology:
Cost tiers separate commodity air plasma from precision-engineered hybrid systems with differentiated consumables economics.
- Hybrid Plasma:Multi-gas injection and refined arc constriction deliver superior edge quality on stainless steel and aluminum alloys. Chemical processing equipment manufacturers in the United States specify hybrid systems for ASME pressure vessel fabrication where dross tolerance approaches zero. Reduced secondary grinding labor offsets higher electrode consumption rates.
- Air Plasma:Compressed air as plasma gas and shielding medium minimizes operating cost for carbon steel cutting in price-sensitive contract shops. Midwest steel service centers deploy air plasma for structural shapes where edge bevel requirements are minimal and throughput velocity dominates economics.
- Water Plasma:Submerged or water-injection configurations suppress fume generation and thermal distortion in thick-plate applications.
- Plasma Arc:Conventional transferred-arc systems persist in legacy installations with established maintenance protocols and spare parts inventories.
Air plasma commands volume share in carbon steel processing; hybrid systems are gaining share fastest as alloy grade diversification accelerates across fabrication supply chains.
End User:
Application requirements dictate equipment specification, with aerospace and automotive representing opposite poles of tolerance and volume.
- Automotive:Body-in-white and chassis component production demands cycle times below 30 seconds per blank with statistical process control integration. OEM stamping operations in the United States and Japan specify high-definition plasma for prototype and short-run production where hard tooling economics fail. Electrification programs expand aluminum-intensive platform demand.
- Aerospace:Titanium and nickel alloy cutting for engine components and airframe structures requires kerf width control within 0.05mm. NADCAP-accredited suppliers in Germany deploy precision plasma for near-net-shape roughing prior to machining, compressing material removal requirements. Certification timelines extend procurement cycles substantially.
- Manufacturing:General industrial fabrication spans machinery bases, material handling equipment, and agricultural implements with moderate tolerance requirements.
- Construction:Structural steel processing for commercial and infrastructure projects prioritizes beam and plate cutting speed over edge refinement.
Manufacturing absorbs the highest equipment unit volume; aerospace exhibits the steepest expansion trajectory as titanium consumption climbs in next-generation airframe programs.
Installation:
Customer type and facility permanence determine whether portable or fixed configurations prevail.
- Industrial:Heavy-duty gantries and cutting tables with automated material handling dominate OEM-integrated production lines. Japanese precision metalworking clusters specify industrial-class systems with submerged cutting capability for thick-plate applications in shipbuilding and energy equipment. Foundation requirements and facility layout constraints limit relocation flexibility.
- Fixed:Dedicated shop-floor installations with localized fume extraction and power distribution serve high-volume contract fabricators.
- Portable:Trailer-mounted or skid-based systems enable on-site processing for construction, demolition, and infrastructure maintenance.
- Table-Top:Compact units address educational institutions, prototyping labs, and light-gauge fabrication with limited footprint.
Industrial installations represent the dominant revenue category; portable systems are climbing the fastest as infrastructure maintenance outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE dual carbon mandates anchor the dominant geography, with emission standards forcing equipment replacement across heavy fabrication clusters. Fabricators in Tianjin and Shanghai retrofit production lines to comply with tightening auxiliary power limits.
United States
Automotive stamping plants in Detroit and aerospace suppliers in Wichita drive CNC plasma refresh cycles. EPA emission standards for particulate capture reshape ventilation specifications in Midwest steel service centers. Houston's energy equipment fabricators deploy hybrid systems for pressure vessel production.
Germany
Precision metalworking clusters in Stuttgart and Dortmund demand real-time kerf control for automotive blanking operations. REACH substance restrictions accelerate consumable chemistry reformulation timelines. Bavarian machine builders integrate plasma systems with MES platforms for lights-out production.
South Korea
Shipbuilders in Ulsan and Busan specify automated gantry systems for hull section cutting. MFDS workplace exposure guidelines tighten fume capture requirements in fabrication yards. Daegu's heavy machinery producers adopt robotic nesting to offset labor cost pressures.
Japan
Aerospace suppliers in Nagoya and Osaka deploy precision plasma for titanium roughing prior to machining. METI energy-efficiency standards favor equipment with reduced auxiliary power draw. Chubu region's automotive stamping operations integrate statistical process control for short-run production.
India
Shipbreaking yards in Alang and steel fabricators in Pune create first-mover positioning for automated systems. PLI scheme incentives for capital goods accelerate equipment procurement in structural steel processing. Gujarat's infrastructure build-out expands demand for portable cutting configurations.
Plasma Cutting Machine Market Vendor Landscape
Capability concentration sits with technology-anchored specialists; scale advantage sits with diversified industrial conglomerates. The vendor base stratifies across three tiers: premium system integrators with proprietary torch architectures, mid-market fabricators with regional service networks, and emerging Asian producers competing on equipment cost. Strategic moves center on backward integration into consumables supply and technology licensing partnerships for IoT-enabled cut monitoring.
Within the premium system tier, Hypertherm and ESAB Corporation exemplify technology-anchored positioning through proprietary power source and torch architectures. TRUMPF GmbH occupies a differentiated position bridging laser and plasma modalities for precision metalworking applications. These three entities represent distinct competitive vectors: consumables-integrated economics, high-definition process control, and multi-technology portfolio breadth.
| Leading Market Players |
|---|
| Messer Cutting Systems |
| Miller Electric Mfg. LLC |
| Hypertherm |
| TRUMPF |
| Komatsu NTC |
| ESAB Corporation |
| Kjellberg Finsterwalde |
| DAIHEN Corporation |
| Lincoln Electric |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on copper-hafnium electrode alloys determines both three-tier pricing spreads across premium hybrid systems and regional contract manufacturing footprints. Fabricators in Germany and Japan absorb premium positioning through captive consumables sourcing, while Midwest steel service centers face margin compression from spot-market electrode volatility.
Pricing Analysis
Price spreads between German precision metalworking clusters and Indian shipbreaking yards exceed threefold for equivalent CNC platforms. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified hybrid systems from air plasma commodity units. Cost compression in mid-market mechanized equipment is intensifying because Chinese domestic fabricators expand local production capacity. Independent steel service centers in the US Southeast exhibit highest price sensitivity; Japanese automotive stamping plants show least sensitivity due to scrap-reduction economics.
Supply Chain Analysis
Copper and hafnium feedstock sourcing draws from Chile, Kazakhstan, and Chinese rare earth processing complexes. Torch assembly and power source manufacturing rests on Germany, Japan, and United States engineering clusters. Single-source vulnerability concentrates in proprietary nozzle architectures from Hypertherm and ESAB captive supply networks. Distribution runs through authorized dealer networks for industrial-class systems and direct e-commerce channels for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumables attach rates now exceed hardware margins for CNC plasma platforms, with predictive maintenance subscriptions expanding faster than equipment sales across German and Japanese precision metalworking clusters.
For Market Incumbents: Harden consumables lock-in through proprietary electrode chemistry patents and torch architecture exclusivity. Defend against emerging Asian cost competitors by expanding captive supply of copper-hafnium alloys. Deepen backward integration into hafnium refining to offset commodity volatility from Kazakh and Chinese sources. For New Entrants and Emerging Players: Pursue portable system penetration in India's infrastructure maintenance and Gujarat shipbreaking expansion. Target mechanized tractor-based platforms for mid-volume fabricators in Vietnam and Indonesia lacking fixed-gantry infrastructure. Deploy rental-plus-consumables subscription models to bypass incumbent dealer channel control. For Investors and Strategic Acquirers: The market sits at a technology-refresh phase that favors consumables-integrated specialists over pure equipment vendors. Five-to-ten year viability hinges on IoT-enabled cut quality monitoring differentiation. Signal to watch: AS9100 certification timelines for aerospace suppliers as precision-thickness demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Backward Integration | Captive electrode supply locks in recurring revenue from Korean shipbuilders. |
| IoT-Enabled Cut Monitoring | Real-time kerf adjustment differentiates German aerospace supplier offerings. |
| Hybrid Technology Licensing | Multi-gas arc constriction patents penetrate stainless fabrication in US chemical processing. |
| Regional Service Network Expansion | Authorized dealer density captures Indian PLI scheme infrastructure procurement. |
| Predictive Maintenance Subscriptions | Algorithmic nozzle-wear forecasting reduces downtime for Japanese automotive stamping. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and EPA emission compliance records. Primary interviews engaged plant engineers at automotive stamping operations, aftermarket service heads at industrial distributors, and procurement teams at Korean shipbuilders. Secondary validation drew from USITC import databases, METI energy-efficiency equipment registrations, and REACH substance restriction filings. Bottom-up equipment shipment tallies triangulate against top-down fabrication capacity expansion estimates.
Forecast inputs span CNC mechanized system penetration rates, hybrid technology adoption curves across alloy grades, and consumables replacement cycle frequencies. Segmentation dimensions modeled include automation level, power source chemistry, end-use precision requirements, and regional regulatory stringency. CAGRs derive from equipment replacement cycle analysis and capacity expansion announcements. Industry-specific inputs incorporate China's MEE dual carbon compliance timelines and EU carbon border adjustment implementation patterns.
Sensitivities concentrate around tariff escalations on copper-hafnium alloys, REACH substance restriction expansions, and Chinese domestic equipment export pricing. Forecasts embed assumptions on regulatory enforcement consistency and electrode chemistry substitution feasibility. Cross-checking against IHS Markit metalworking equipment shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Smart Crane Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market