
 Europe Stud Welding Machine Market | 2026-2036
Europe Stud Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stud Welding Machine Market Insights
Digital arc control and real-time weld monitoring is reconfiguring how European fabricators guarantee joint integrity across automated production lines. Taylor Studwelding Systems Limited leverages proprietary inverter technology to sustain high-throughput operations in UK heavy engineering. Köster & Co. GmbH anchors its position through specialized drawn-arc systems for German automotive Tier-1 suppliers. Heinz Soyer Bolzenschweisstechnik GmbH differentiates via compact portable units that navigate on-site construction constraints across Central Europe.
A stud welding machine joins metal fasteners to base materials through controlled electric arc or capacitor discharge, typically achieving pull-out strengths exceeding parent material yield in carbon and stainless steel applications. The equipment serves primarily to create permanent threaded or unthreaded anchor points without reverse-side access, critical for steel-frame construction and vehicle body assembly. Automated machines dominate value capture in European automotive plants, where cycle-time requirements exceed manual throughput thresholds. Capacitor discharge technology leads growth trajectories among portable equipment buyers, driven by reduced spatter and minimal heat-affected zones in thin-gauge aluminum joining. Drawn arc systems retain margin concentration in heavy fabrication, where thick-section structural welding commands premium pricing.
CE marking under the EU Machinery Directive and compliance with EN ISO 14555 weld stud standards shape product certification requirements for equipment sold across member states. Germany's KBA type-approval protocols for automotive production tools create additional compliance layers that filter non-specialized suppliers from OEM supply chains. REACH chemical restrictions on coating formulations further constrain consumable specifications for European-manufactured welding studs. Stakeholders must monitor how the EU AI Act's risk-classification framework will apply to self-adjusting weld parameter algorithms in next-generation automated systems.
Market Dynamics
Automotive OEMs across Germany and France are accelerating stud welding adoption for electric vehicle platform assembly, compressing cycle-time requirements and forcing equipment suppliers to integrate real-time arc monitoring with predictive maintenance algorithms.
Growth Catalysts
- EU Green Deal industrial mandates:Decarbonization targets are accelerating replacement of energy-intensive welding systems with capacitor discharge technology in German automotive clusters.
- Electric vehicle chassis standardization:Precision fastening requirements for aluminum-intensive EV platforms are expanding drawn-arc system deployments across French and Italian OEM supply chains.
- CE marking harmonization:Machinery Directive compliance streamlines cross-border equipment sales, reducing certification duplication costs for mid-tier fabricators in Central Europe.
Market Restraints
- Specialized consumable concentration:REACH chemical restrictions on coating formulations limit qualified stud suppliers to a narrow base of German and Austrian manufacturers.
- Copper and aluminum price volatility:Electrode and stud material costs fluctuate with commodity markets, compressing margins for fixed-price contract manufacturers.
- Substitution by mechanical fastening:Flow-drill screw systems from Swedish automotive suppliers are capturing thin-gauge joining applications previously served by capacitor discharge welding.
Strategic Opportunities
- Polish and Romanian heavy fabrication:Infrastructure investment programs are creating first-time demand for automated drawn-arc systems in shipbuilding and bridge construction.
- EU AI Act risk-classification framework:Self-adjusting weld parameter algorithms in next-generation equipment will qualify for regulatory sandboxes, accelerating R&D amortization.
- Rental and pay-per-weld models:Equipment-as-a-service channels are penetrating Italian construction markets where capex constraints previously blocked automated system adoption.
Industry Challenges
- Certified operator scarcity:EN ISO 14555 weld qualification requirements exceed vocational training capacity in Eastern European manufacturing regions.
- KBA type-approval timelines:German automotive production tool protocols extend validation cycles by 8-14 months, freezing specification changes mid-program.
- Legacy MIG system integration:Retrofitting automated stud welding cells into existing robotic lines requires custom end-effector engineering that strains integrator bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stud Welding Machine Market |
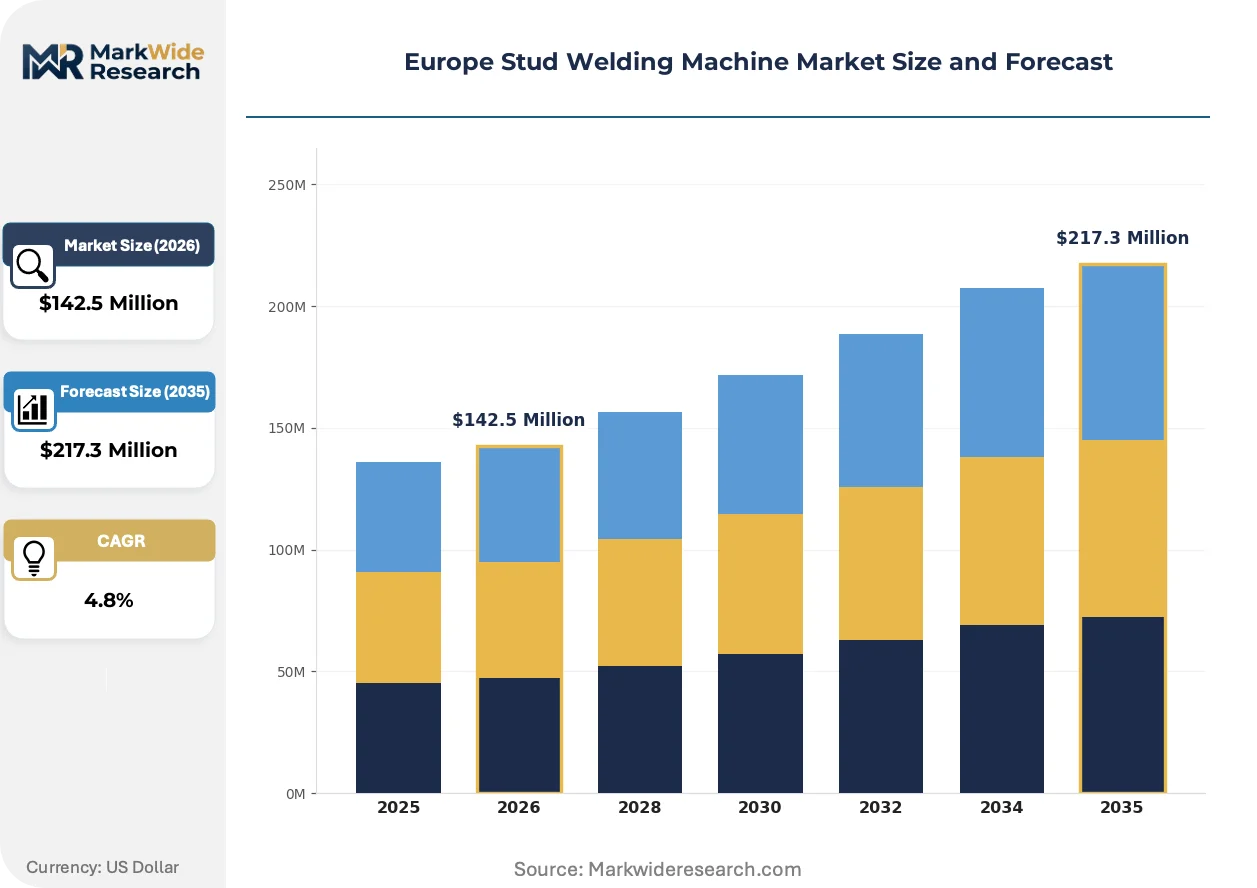
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Machines, Manual Machines, Semi-Automatic Machines, Portable Machines Technology: Capacitor Discharge, Drawn Arc, Short Cycle, Surge End User: Construction, Automotive, Shipbuilding, Manufacturing Application: Flange Assembly, Steel Structures, Rail Tracks, Industrial Equipment |
| Companies Covered | Taylor Studwelding Systems Limited, Köster & Co. GmbH, Bolte GmbH, Köco GmbH, Nelson Stud Welding Inc., Heinz Soyer Bolzenschweisstechnik GmbH, Thomas Welding Systems, CEBORA Welding and Cutting, HBS Bolzenschweiss-Systeme, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stud Welding Machine Market Trends and Innovations
Digital twin architectures and edge-computing weld controllers are compressing the feedback loop between arc ignition and quality verification, fundamentally altering how European fabricators manage joint integrity at production speed.
Digital arc control systems with embedded spectroscopic analysis are virtualizing quality assurance workflows that previously required offline destructive testing. German automotive Tier-1 suppliers are deploying these systems at line speeds exceeding 40 studs per minute. The technology is virtualizing the role of manual weld inspectors, collapsing inspection stations and reallocating floor space to value-add operations.
REACH chemical restrictions on hexavalent chromium coatings are forcing reformulation of welding stud surface treatments across EU member states. ECHA substance evaluation timelines are accelerating supplier consolidation as smaller coating houses exit the compliance burden. Capacitor discharge equipment manufacturers serving thin-gauge aluminum applications face the tightest qualified consumable constraints, prompting backward integration into captive stud production.
Outcome-based equipment leasing is displacing traditional capital purchase models among mid-volume fabricators in Spain and Portugal. Rental providers assume maintenance and certification liability, converting fixed asset burdens into variable production costs. Construction-sector buyers in Iberian markets show the fastest contract velocity, prioritizing operational flexibility over long-term equipment ownership.
Europe Stud Welding Machine Market Segmentation
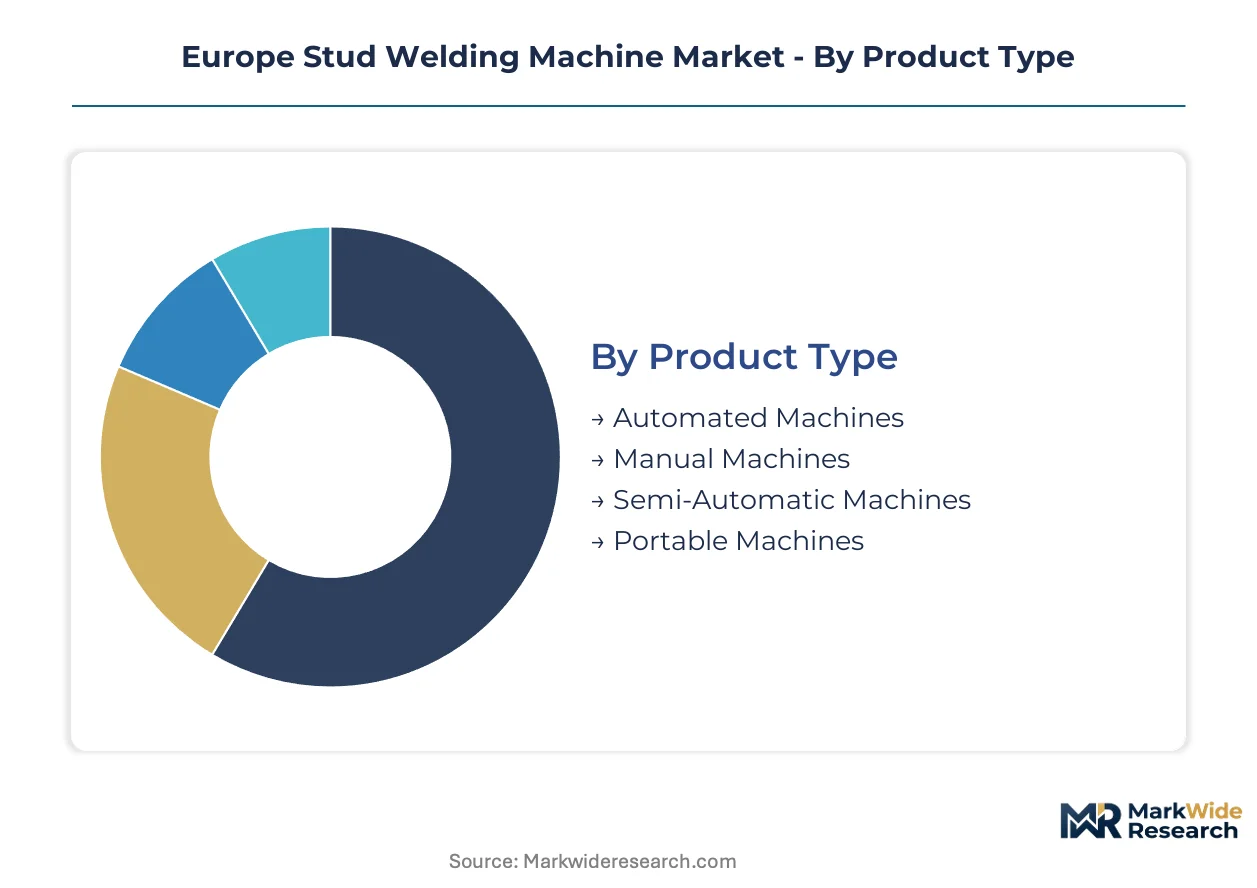
Segmentation in the European stud welding machine market reveals distinct equipment configurations aligned with production scale, material thickness, and regulatory compliance requirements. Understanding these divisions allows suppliers to calibrate R&D investment and distribution strategies against specific buyer economics and application constraints.
Product Type:
Mature automated systems dominate automotive value capture while portable units emerge as the fastest-expanding configuration for on-site construction flexibility.
- Automated Machines:Robotic cells integrate with production line PLCs to deliver cycle times below two seconds per stud in German automotive body shops. German OEMs specify these systems for electric vehicle platform assembly where precision tolerances and traceability requirements exceed manual capability.
- Portable Machines:Battery-powered and lightweight capacitor discharge units enable field welding of aluminum facade elements and steel decking without generator support. Italian and Spanish construction contractors are displacing rented fixed equipment with owned portable systems to reduce project mobilization costs.
- Manual Machines:Hand-held drawn-arc guns serve maintenance operations and low-volume fabrication where capital constraints block automation.
- Semi-Automatic Machines:Operator-fed systems with automatic arc initiation bridge the gap between manual flexibility and automated throughput in mid-tier Polish metalworking shops.
Automated machines handle the majority of throughput; portable machines are climbing the fastest on share.
Technology:
Cost tier stratification separates premium drawn-arc systems from economy capacitor discharge equipment, with application thickness and energy efficiency driving selection.
- Drawn Arc:Controlled arc duration and lift mechanism deliver full fusion penetration in structural steel up to 25mm thickness. German bridge fabricators and offshore wind tower manufacturers specify drawn-arc systems for CE-marked structural connections requiring EN ISO 14555 compliance documentation.
- Capacitor Discharge:Rapid energy release from stored capacitors produces minimal heat-affected zones in thin-gauge aluminum and stainless sheet. French automotive Tier-1 suppliers are displacing resistance welding with capacitor discharge for EV battery tray assembly to meet EU Green Deal energy intensity targets.
- Short Cycle:Reduced arc time variant of drawn-arc technology balances penetration control with cycle speed in medium-thickness applications.
- Surge:High-current impulse welding for specialized refractory metal fastening in aerospace and nuclear applications with limited European deployment.
Drawn arc commands the premium tier on margin; capacitor discharge is expanding most quickly amid aluminum joining demand.
End User:
Customer type concentration centers on automotive OEM procurement while construction sector fragmentation creates distribution complexity.
- Automotive:OEMs and Tier-1 suppliers specify automated drawn-arc and capacitor discharge systems for body-in-white, exhaust, and battery enclosure assembly. German KBA type-approval requirements filter equipment suppliers to those with validated process documentation and spare parts logistics within 24 hours.
- Construction:Steel frame contractors, facade installers, and infrastructure developers deploy portable and semi-automatic equipment across dispersed project sites. Polish and Romanian infrastructure investment programs are creating first-time demand for certified welding systems in bridge and commercial building construction.
- Shipbuilding:Croatian and Romanian yards utilize heavy-duty drawn-arc systems for deck and bulkhead fastening in EU-funded naval and commercial vessel programs.
- Manufacturing:General fabricators and industrial equipment producers represent a price-sensitive segment with mixed technology adoption.
Automotive concentrates procurement value; construction is gaining share fastest through equipment-as-a-service penetration.
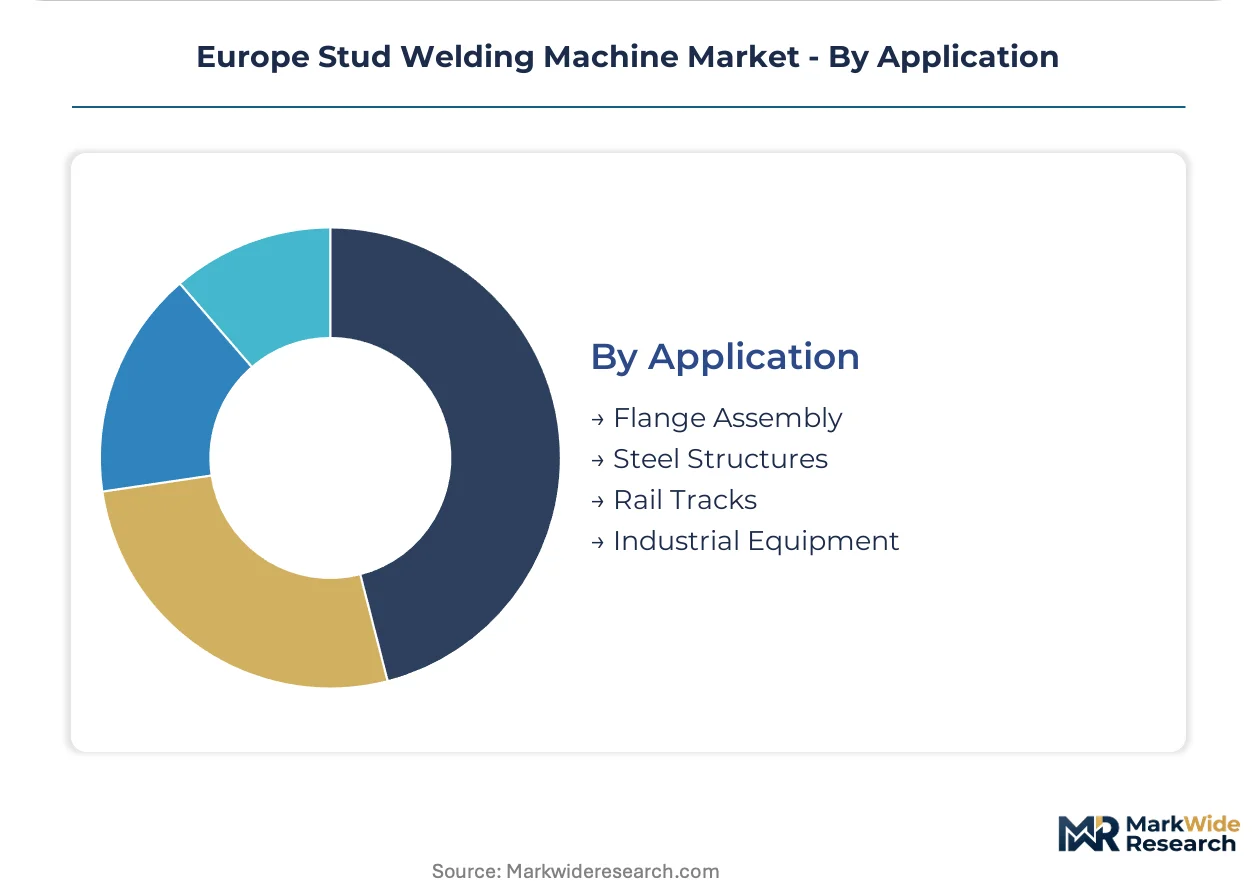
Application:
Volume distribution favors structural steel fabrication while rail infrastructure presents emerging specification opportunities.
- Steel Structures:Commercial buildings, bridges, and industrial facilities require high-strength shear and tension connections in carbon and weathering steel. German and Austrian engineering firms specify automated stud welding for composite steel-concrete deck systems to accelerate construction schedules.
- Flange Assembly:Pipe, valve, and pressure vessel manufacturers utilize precision stud patterns for gasket retention and instrumentation mounting. French nuclear and petrochemical equipment suppliers demand full material certification and weld procedure qualification for flange applications.
- Rail Tracks:fastening systems for signaling, electrification, and platform construction in high-speed and urban rail networks.
- Industrial Equipment:Machinery frames, enclosures, and material handling systems with moderate structural requirements.
Steel structures absorb the dominant equipment deployment; rail tracks represent the steepest expansion trajectory amid EU infrastructure funding activation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates demand in German industrial clusters, while construction-sector fragmentation disperses equipment deployment across Central and Southern European markets. Equipment-as-a-service channels are penetrating Iberian and Italian markets where capital constraints previously blocked automated system adoption.
Germany
KBA type-approval protocols filter equipment suppliers to those with validated process documentation and 24-hour spare parts logistics. The EU Machinery Directive's CE marking requirements shape certification workflows for cross-border equipment sales. Bavarian and Baden-Württemberg automotive clusters deploy automated drawn-arc systems for electric vehicle platform assembly at cycle times below two seconds per stud.
France
French automotive Tier-1 suppliers displace resistance welding with capacitor discharge technology for EV battery tray assembly to meet EU Green Deal energy intensity targets. ECHA substance evaluation timelines accelerate supplier consolidation as smaller coating houses exit REACH compliance burdens. The Auvergne-Rhône-Alpes industrial corridor anchors precision fastening demand for aluminum-intensive chassis components.
United Kingdom
UK heavy engineering fabricators sustain high-throughput operations through proprietary inverter technology integration. The Construction Products Regulation shapes equipment specification for structural steel connections in commercial building projects. Midlands manufacturing clusters deploy automated systems for steel-frame construction and infrastructure metalwork.
Poland
Infrastructure investment programs create first-time demand for automated drawn-arc systems in bridge and commercial building construction. EN ISO 14555 weld qualification requirements exceed vocational training capacity in Eastern European manufacturing regions. Warsaw and Krakow metalworking shops adopt semi-automatic machines to bridge manual flexibility and automated throughput.
Italy
Construction contractors displace rented fixed equipment with owned portable capacitor discharge units to reduce project mobilization costs. Outcome-based equipment leasing converts fixed asset burdens into variable production costs for mid-volume fabricators. Northern Italian engineering districts concentrate demand for battery-powered field welding systems in aluminum facade and steel decking applications.
Europe Stud Welding Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: automotive-validated system integrators with KBA process documentation, portable equipment specialists serving construction mobility requirements, and consumables-integrated suppliers managing REACH-compliant coating supply. Dominant competitive moves include backward integration into captive stud production and geographic expansion through equipment-as-a-service rental channels.
Among UK-based engineering specialists, Taylor Studwelding Systems Limited exemplifies the high-throughput automation archetype. German GmbH-structured fabricators Köster & Co. GmbH and Heinz Soyer Bolzenschweisstechnik GmbH occupy positions spanning drawn-arc system specialization and compact portable unit development. These entities represent the geographic and technical diversification required to serve both automotive OEM validation protocols and on-site construction constraints across Central European markets.
| Leading Market Players |
|---|
| Taylor Studwelding Systems Limited |
| Köster & Co. GmbH |
| Bolte GmbH |
| Köco GmbH |
| Nelson Stud Welding Inc. |
| Heinz Soyer Bolzenschweisstechnik GmbH |
| Thomas Welding Systems |
| CEBORA Welding and Cutting |
| HBS Bolzenschweiss-Systeme |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's container cost dynamics amplify pricing power for German and Austrian consumable suppliers while compressing margins for peripheral equipment fabricators dependent on imported electrode materials. This logistics chokepoint reinforces a three-tier pricing structure across premium, standard, and economy levels, with KBA-validated automotive systems commanding substantial premiums over portable construction units.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper and aluminum indexation dominate long-term automotive supply agreements, insulating Tier-1 suppliers from raw material volatility while transferring commodity risk to equipment vendors. Price differentiation rests on CE certification grade and KBA process documentation depth, with German OEMs showing minimal price sensitivity compared to Iberian construction contractors facing acute capex constraints. Pricing pressure stems from Swedish flow-drill screw substitution in thin-gauge applications, forcing capacitor discharge vendors to bundle maintenance services or sacrifice margin.
Supply Chain Analysis
Contract manufacturing concentrates in German precision engineering clusters and Austrian coating houses qualified under REACH hexavalent chromium restrictions. Electrode production draws from copper rod mills in Poland and specialty steel foundries in Sweden, while capacitor banks source from established European electronics manufacturers. Single-source vulnerability pervades REACH-compliant stud coating capacity, with ECHA substance evaluation timelines accelerating supplier consolidation. Distribution runs through authorized dealer networks for automated systems and direct rental channels for portable equipment in Italian and Spanish construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European stud welding machine market approaches a platform-economics inflection as digital twin architectures and predictive maintenance algorithms create equipment-ecosystem lock-in comparable to industrial software markets. Interoperability between weld controllers and MES/ERP systems is displacing standalone hardware procurement in German automotive clusters.
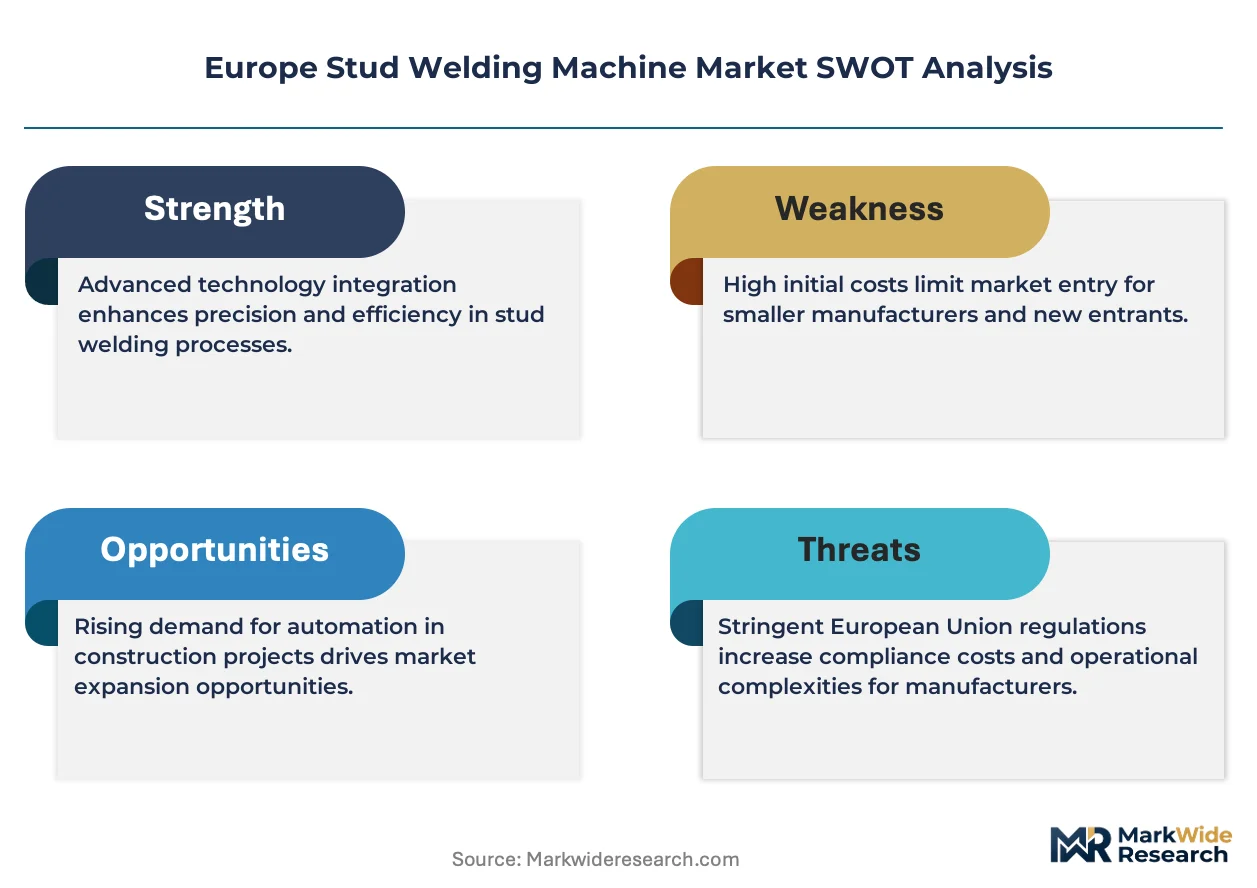
For Market Incumbents: Insulate KBA-validated positions through backward integration into captive stud production, securing REACH-compliant coating capacity before ECHA consolidation eliminates qualified suppliers. Expand equipment-as-a-service rental footprints in Polish and Romanian infrastructure markets to preempt emerging local competitors. Prioritize edge-computing weld controller development to deepen MES integration stickiness against software-centric entrants.
For New Entrants and Emerging Players: Mid-market Polish metalworking shops represent the most penetrable entry point, where semi-automatic machine demand exceeds established vendor service capacity. Portuguese and Spanish construction contractors facing capex constraints present white-space for battery-powered portable system launches with pay-per-weld financing. Partner with Italian equipment rental platforms to bypass direct sales channel establishment costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected welding equipment divisions lacking digital controller roadmaps. Long-term viability centers on software-defined weld parameter autonomy under the EU AI Act risk-classification framework. Monitor ECHA substance evaluation rulings on hexavalent chromium alternatives as inflection signals for consumable supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stud Production | Captive REACH-compliant coating supply secures automotive OEM qualification continuity amid ECHA consolidation. |
| Equipment-as-a-Service Rental Expansion | Variable cost models unlock Polish and Romanian infrastructure markets previously blocked by capex barriers. |
| Digital Twin Controller Development | Edge-computing weld verification collapses inspection stations and reallocates German automotive floor space. |
| KBA Process Documentation Investment | Validated spare parts logistics within 24 hours filters non-specialized suppliers from German OEM supply chains. |
| EU AI Act Regulatory Sandbox Entry | Self-adjusting weld parameter algorithms qualify for accelerated R&D amortization under risk-classification frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM procurement directors, German Tier-1 supplier plant engineers, Polish metalworking shop owners, Italian construction equipment rental managers, and Austrian consumable coating specialists. Secondary validation drew from EU Machinery Directive implementation guidance, ECHA substance evaluation timelines, KBA type-approval documentation, EN ISO 14555 certification records, and German automotive production statistics. Bottom-up equipment shipment data triangulated against top-down manufacturing value-added estimates across the analysis window.
Calibration anchored on historical penetration rates of capacitor discharge versus drawn-arc technologies, with forward projection incorporating EU Green Deal energy intensity mandates and EV platform standardization timelines. Segmentation dimensions spanned automation level, welding technology, end-user industry, and application thickness across the modeling period. CAGRs derived from equipment replacement cycles, infrastructure investment program commitments, and automotive production platform lifecycles. Industry-specific inputs included KBA validation timeline distributions and REACH-compliant consumable supplier survival rates.
Stress conditions across copper and aluminum price volatility, ECHA substance evaluation acceleration, and flow-drill screw substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU AI Act implementation timing and German automotive cluster expansion trajectories. Quarterly review of KBA type-approval queue lengths and ECHA coating substance rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Powered Screed Market
Construction Equipment
Tower Crane Market
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Shot Blasting Machine Market