
 Global Screw Conveyors Market | 2026-2036
Global Screw Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Screw Conveyors Market Outlook
The capital-intensity divergence between integrated foundry operators and assembly-focused fabricators is rotating competitive advantage toward upstream metalworking control. WAMGROUP leverages in-house casting capabilities to sustain margin capture across European food processing installations. KWS Manufacturing Company Ltd. anchors North American mining demand through specialized abrasion-resistant flighting designs. DEMECH India competes on localized stainless steel sourcing and rapid customization for domestic cement and fertilizer plants.
A screw conveyor is a bulk material handling mechanism consisting of a helical flighting mounted on a central shaft within a trough, typically operating at rotational speeds between 20 and 165 RPM to transport powders, granules, and semi-solid materials horizontally or at controlled inclinations. Horizontal conveyors dominate installed base volumes due to their mechanical simplicity and lower energy draw across grain handling and wastewater treatment facilities. Automated technology segments are capturing disproportionate interest from food processing end users seeking traceable, CIP-compatible systems with integrated load cell feedback. Stainless steel material configurations command premium positioning where FDA and EFSA hygiene mandates apply, while carbon steel variants occupy cost-sensitive construction and mining procurement channels.
OSHA machine guarding standards in the United States, EU Machinery Directive 2006/42/EC requirements under CE marking, and India's BIS certification for industrial equipment collectively elevate compliance costs for non-integrated suppliers lacking in-house testing laboratories. REACH substance restrictions on certain surface coatings are redirecting specification trends toward bare stainless finishes in European pharmaceutical and dairy applications. Stakeholders must monitor how evolving carbon border adjustment mechanisms and country-of-origin documentation requirements reshape supplier qualification criteria across multinational procurement frameworks.
Market Dynamics
Capital-intensity divergence between integrated foundry operators and assembly-focused fabricators is rotating competitive advantage toward upstream metalworking control, with stainless steel sourcing and in-house casting capabilities determining margin capture across food processing and mining procurement channels.
Growth Catalysts
- EU Green Deal compliance:REACH substance restrictions on surface coatings redirect specification trends toward bare stainless finishes in European pharmaceutical and dairy applications, expanding addressable premium segments.
- India PLI scheme incentives:Domestic manufacturing subsidies accelerate localized stainless steel production capacity for cement and fertilizer plant installations, reducing import dependency for critical flighting components.
- Abrasion-resistant flighting designs:Specialized hardfacing technologies extend equipment life in bulk mining operations, creating replacement cycle compression and aftermarket service pull-through.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress fabricator margins on fixed-price contracts for FDA-compliant food processing installations.
- European supply concentration:CE marking testing laboratory scarcity in Eastern European markets elevates compliance costs for non-integrated suppliers lacking in-house certification capabilities.
- Pneumatic conveying substitution:Dense-phase pneumatic systems displace screw conveyors in dust-sensitive pharmaceutical applications where cross-contamination risks dominate specification criteria.
Strategic Opportunities
- Indonesia mining expansion:Nickel processing infrastructure investments create demand for corrosion-resistant wet-material handling systems in tropical high-humidity environments.
- Clean-in-place convergence:Integration of automated CIP protocols with load cell feedback systems opens premium positioning in traceable food manufacturing workflows.
- Carbon border adjustment mechanisms:Country-of-origin documentation requirements for steel inputs create qualification barriers that favor suppliers with transparent, auditable supply chains.
Industry Challenges
- Welding certification timelines:ASME Section IX and EN ISO 9606 qualification requirements for stainless steel flighting fabrication extend project delivery schedules by 6-12 weeks.
- Legacy control system integration:Retrofitting analog-era screw conveyors with Industry 4.0 sensor networks demands specialized automation engineering scarce in regional fabricator bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Screw Conveyors Market |
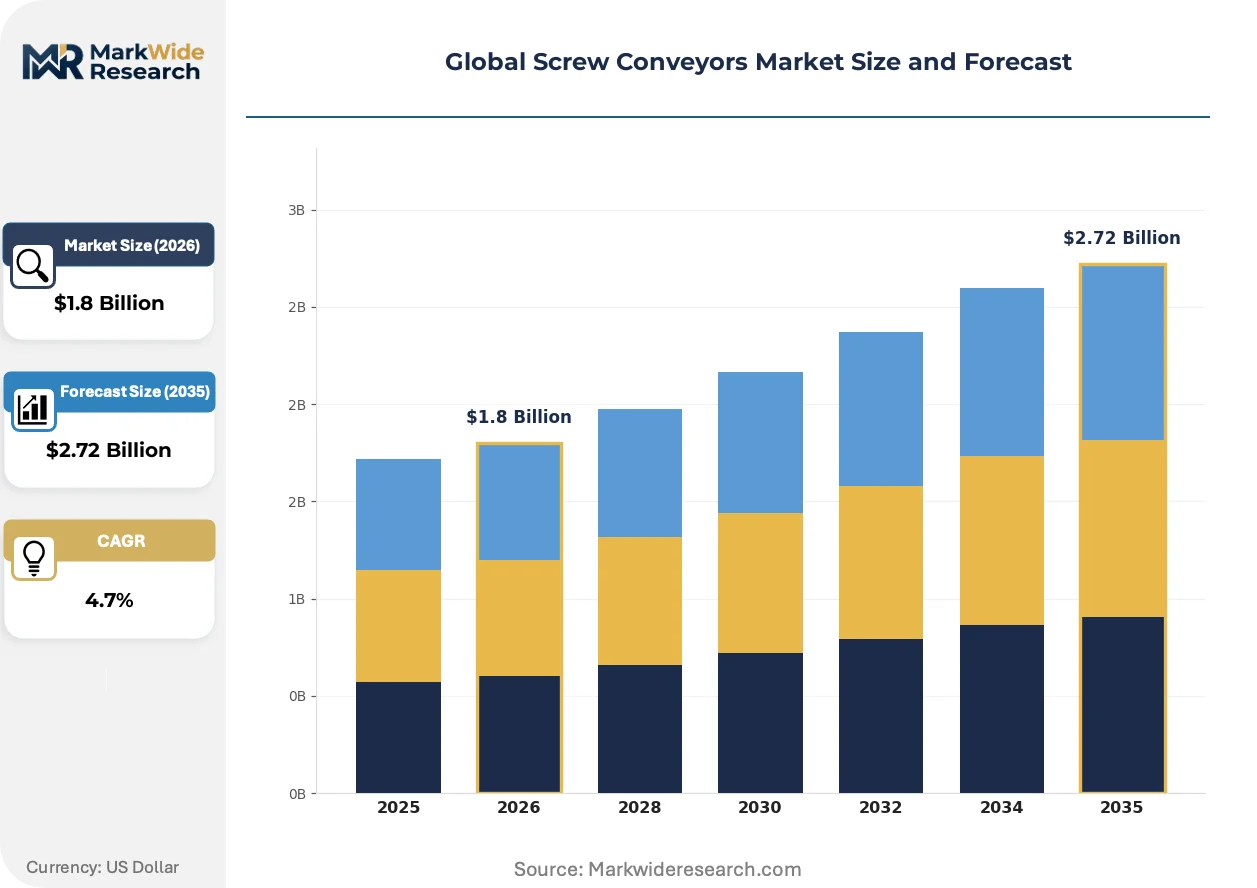
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Conveyors, Horizontal Conveyors, Inclined Conveyors, Archimedean Screws End User: Agriculture, Construction, Food Processing, Mining Material: Stainless Steel, Plastic, Aluminum, Carbon Steel Technology: Conventional, Automated, Modular, Bulk Handling |
| Companies Covered | Screw Conveyor Corporation, Syntron Material Handling, Continental Conveyor Ltd., WAMGROUP, KWS Manufacturing Company Ltd., SPIRAC Engineering Pty Ltd, Martin Sprocket & Gear Inc, DEMECH India, Flexicon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Screw Conveyors Market Strategic Shifts
Digital instrumentation and material science advances are compressing the traditional trade-off between mechanical durability and hygienic design, enabling single-system solutions across previously separated premium and standard procurement tiers.
Modular interchangeable flighting systems is fragmenting the historical split between permanent welded assemblies and disposable segmented designs. Pharmaceutical compounders in Germany and the Netherlands are adopting quick-release polymer flighting for multi-product campaigns. This technology is fragmenting equipment utilization models by enabling same-day product changeovers that previously required dedicated conveyor lines.
REACH substance restrictions on hexavalent chromium surface treatments are eliminating traditional protective coatings from European dairy and infant nutrition equipment specifications. Bare 316L stainless finishes with electropolished surfaces now dominate premium procurement channels. Italian and French OEMs are accelerating in-house passivation capacity to maintain CE marking compliance without third-party coating vendors.
Consolidated procurement frameworks among multinational grain handlers are compressing supplier qualification cycles from 18-month pilot programs to 90-day performance guarantees. Brazilian and Argentine agricultural cooperatives are adopting this compressed evaluation model, displacing traditional relationship-based vendor selection with benchmarked throughput trials and standardized wear-life contracts.
Global Screw Conveyors Market Segmentation
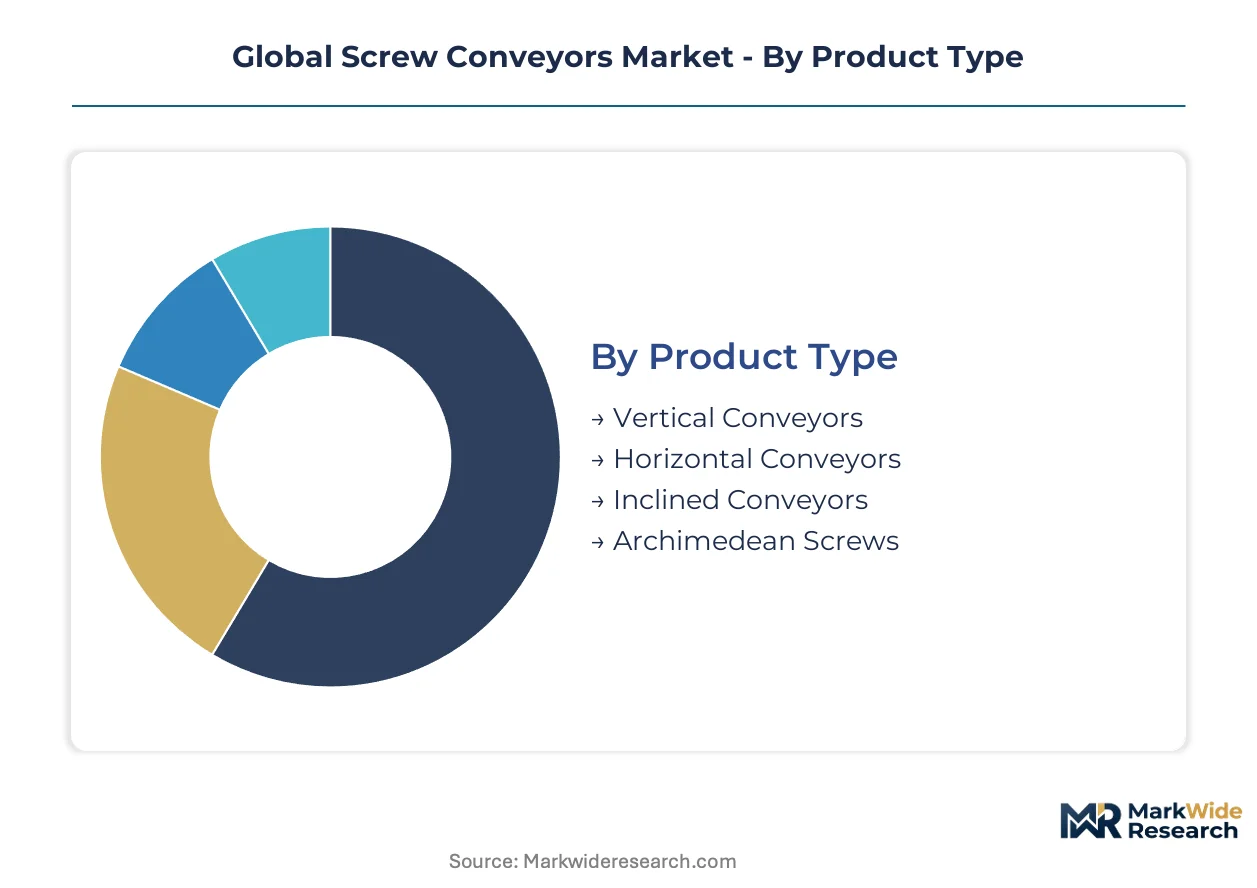
Screw conveyor procurement channels diverge sharply between project-engineered mining systems and catalog-standard agricultural units. Specification complexity and certification requirements determine whether segments flow through distributor networks or direct OEM relationships.
Product Type:
Channel mix varies by mechanical complexity — horizontal units move through agricultural supply houses while vertical and specialized designs require application engineering direct from manufacturers.
- Horizontal Conveyors:These systems employ helical flighting on a central shaft within a U-trough, operating at 20-165 RPM with minimal energy draw. Grain handling cooperatives in Brazil and Argentina concentrate demand here, driven by consolidated procurement frameworks that compress supplier qualification cycles to 90-day performance guarantees.
- Vertical Conveyors:Configured with steep-flight or ribbon-style designs to lift materials against gravity at angles exceeding 45 degrees. Nickel processing infrastructure in Indonesia drives specification for corrosion-resistant wet-material handling in tropical high-humidity environments.
- Inclined Conveyors:Bridge horizontal and vertical applications with controlled elevation changes up to 30 degrees. Cement plants in India deploy these for clinker transport where PLI scheme incentives support localized stainless steel sourcing.
- Archimedean Screws:Open-trough designs for wastewater and low-abrasion slurry applications. Municipal treatment facilities specify these for simplicity and maintenance access.
Horizontal conveyors dominate installed base across grain and wastewater sectors. Vertical configurations are where expansion concentrates as mining depth increases and surface processing infrastructure climbs.
End User:
Margin profiles stratify across end-use sectors — food processing commands premium pricing for FDA and EFSA compliance while construction and mining compete on throughput metrics and wear-life contracts.
- Food Processing:Dairy and infant nutrition manufacturers in Germany and the Netherlands specify bare 316L stainless with electropolished surfaces. REACH substance restrictions on hexavalent chromium coatings eliminate traditional protective finishes, redirecting procurement toward passivation-capable OEMs.
- Mining:Bulk material handling operations demand abrasion-resistant flighting with specialized hardfacing technologies. Replacement cycle compression and aftermarket service pull-through characterize this segment's commercial model.
- Agriculture:Grain handlers and oilseed processors prioritize mechanical simplicity and energy efficiency. Brazilian and Argentine cooperatives benchmark throughput trials against standardized wear-life contracts.
- Construction:Cement and aggregate plants balance capital constraints with continuous-duty requirements. Cost-sensitive procurement channels favor carbon steel variants over stainless configurations.
Mining anchors revenue concentration through high-unit-value engineered systems. Food processing is climbing the fastest as traceability mandates and CIP compatibility expand addressable premium segments.
Material:
Input cost volatility and regulatory compliance requirements determine material selection trajectories across end-use applications.
- Stainless Steel:304 and 316L grades dominate pharmaceutical, dairy, and infant nutrition specifications where FDA and EFSA hygiene mandates apply. Nickel and chromium price swings compress fabricator margins on fixed-price contracts.
- Carbon Steel:Standard grades occupy construction and mining procurement channels where corrosion resistance is secondary to mechanical strength and cost containment.
- Plastic:UHMW and nylon flighting segments serve chemical resistance and low-friction requirements in specialty applications.
- Aluminum:Lightweight construction benefits portable and temporary installations in agricultural and light industrial settings.
Stainless steel commands the steepest premium tier. Carbon steel maintains volume leadership in cost-sensitive procurement channels.
Technology:
Automation intensity separates replacement markets from greenfield specification opportunities across end-use sectors.
- Automated:Integrated load cell feedback and CIP protocols enable traceable food manufacturing workflows. German pharmaceutical compounders adopt quick-release polymer flighting for multi-product campaigns with same-day changeover capability.
- Conventional:Analog control and fixed-speed operation persist in mature agricultural and construction installations where retrofit economics deter upgrade cycles.
- Modular:Interchangeable flighting systems fragment equipment utilization models by eliminating dedicated conveyor lines for batch operations.
- Bulk Handling:Heavy-duty configurations for mining and mineral processing with reinforced troughs and oversized drive components.
Conventional technology dominates legacy installed base. Automated systems are gaining share fastest as food manufacturers consolidate procurement around traceable, benchmarked performance guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German stainless steel fabricators commanding premium positioning for CE-marked food processing systems, while Indian assembly-focused operators compete on compressed delivery timelines for domestic cement and fertilizer procurement channels.
United States
OSHA machine guarding standards and EPA emissions protocols elevate compliance costs for bulk material handling installations across grain terminals and mining operations. The Department of Agriculture's biofuels mandates sustain ethanol plant construction in Iowa and Illinois, driving screw conveyor specification for corn handling and distiller's grains transport. Chicago-based engineering clusters anchor North American abrasion-resistant flighting design capabilities.
Germany
REACH substance restrictions on hexavalent chromium coatings redirect dairy and infant nutrition equipment procurement toward bare 316L stainless finishes with electropolished surfaces. EFSA hygiene mandates and the EU Green Deal's recyclability requirements tighten specification criteria for pharmaceutical compounders in Baden-Württemberg. Bavarian OEMs accelerate in-house passivation capacity to maintain CE marking compliance without third-party coating vendors.
India
PLI scheme incentives for domestic manufacturing accelerate localized stainless steel production capacity for cement and fertilizer plant installations, reducing import dependency for critical flighting components. BIS certification requirements for industrial equipment elevate testing costs for non-integrated suppliers lacking in-house laboratory capabilities. Gujarat and Maharashtra industrial corridors concentrate assembly-focused fabricators competing on rapid customization for domestic procurement channels.
Indonesia
Nickel processing infrastructure investments create demand for corrosion-resistant wet-material handling systems in tropical high-humidity environments. The Ministry of Industry's downstream mineral processing mandates expand smelter construction across Sulawesi and Halmahera. Jababeka and MM2100 industrial estates near Jakarta anchor fabrication capacity serving mining sector procurement.
Brazil
Consolidated procurement frameworks among agricultural cooperatives compress supplier qualification cycles from 18-month pilot programs to 90-day performance guarantees. ANVISA's food safety protocols for grain handling and oilseed processing tighten equipment specification criteria. São Paulo state engineering clusters dominate Latin American screw conveyor distribution networks serving Mercosur agricultural terminals.
Global Screw Conveyors Market Competitive Environment
Concentration sits with integrated foundry operators sustaining margin capture through in-house casting capabilities, while assembly-focused fabricators compete on compressed delivery timelines. The vendor base stratifies across three tiers: upstream metalworking specialists controlling stainless steel sourcing, application-engineering houses anchoring mining sector relationships, and catalog-standard distributors serving agricultural procurement channels. M&A activity concentrates on welding certification capacity and automated CIP protocol integration, while geographic expansion targets Indonesia's nickel processing corridor and India's PLI-subsidized manufacturing zones.
Among European-based integrated operators, WAMGROUP exemplifies upstream metalworking control through captive casting capabilities, while KWS Manufacturing Company Ltd. anchors North American mining demand positioning. DEMECH India occupies the localized fabrication tier competing on rapid customization for domestic cement and fertilizer procurement channels. These three archetypes represent the structural divergence between margin-capturing upstream control and volume-competing assembly operations.
| Leading Market Players |
|---|
| Screw Conveyor Corporation |
| Syntron Material Handling |
| Continental Conveyor Ltd. |
| WAMGROUP |
| KWS Manufacturing Company Ltd. |
| SPIRAC Engineering Pty Ltd |
| Martin Sprocket & Gear Inc |
| DEMECH India |
| Flexicon Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day qualification cycles for agricultural procurement compress inventory buffers to 15-20 days of stainless steel flighting stock, binding pricing power to upstream foundry relationships and spot nickel exposure. Fabricators without captive casting face margin compression when nickel volatility intersects fixed-price mining contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order mining systems from catalog-standard agricultural units by 40-60 percent. Project-based pricing dominates engineered applications where ASME welding certification and abrasion-resistant hardfacing drive cost. Price differentiation rests on certification grade (FDA/CE tiers) and vertical integration into foundry operations. Cost compression in carbon steel variants intensifies as Brazilian grain cooperatives consolidate procurement around benchmarked throughput trials. Food processing buyers show least price sensitivity where EFSA hygiene mandates eliminate lower-grade alternatives.
Supply Chain Analysis
Strategic stockpiling of nickel and chromium alloys prevails among integrated European foundries, while Asian assembly fabricators run lean just-in-time programs. Geographic supply concentration centers on Germany for precision-cast components, India for localized stainless steel fabrication, and China for standard-grade flighting. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and Brazilian iron ore. Single-source vulnerability in specialty hardfacing alloys elevates risk for abrasion-resistant mining specifications. Distribution runs through direct OEM relationships for engineered systems and agricultural supply houses for standard units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is rotating toward consolidated multinational grain handlers and mining operators, compressing supplier margins as qualification cycles fragment relationship-based procurement.
For Market Incumbents: Compound defensive positioning through captive passivation capacity and in-house CE marking laboratories. Pneumatic conveying substitution in pharmaceutical applications threatens screw conveyor specification share. Backward integration into stainless steel casting secures margin capture against nickel price volatility. For New Entrants and Emerging Players: Differentiate on rapid customization timelines for India's PLI-subsidized cement and fertilizer procurement. Indonesia's nickel processing corridor offers the most penetrable geography for corrosion-resistant wet-material systems. Partner with local welding certification bodies to compress project delivery schedules. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because margin capture concentrates with upstream metalworking control. Target assembly-focused fabricators with welding certification gaps and regional mining relationships. Watch carbon border adjustment mechanism implementation as inflection signal for supply chain qualification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | In-house stainless steel casting insulates WAMGROUP-style operators from nickel price volatility. |
| CE Marking Laboratory Investment | Captive testing capacity accelerates European dairy and pharmaceutical equipment compliance. |
| Clean-in-Place Protocol Integration | Automated CIP compatibility opens premium positioning in German traceable food manufacturing. |
| Indonesia Manufacturing Footprint | Local fabrication addresses nickel processing demand in Sulawesi high-humidity environments. |
| Quick-Release Flighting Development | Modular polymer systems enable same-day product changeovers for Dutch pharmaceutical compounders. |
Study Parameters
Cross-validation between primary interviews and secondary trade data anchors the qualitative findings in observable procurement patterns. Plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at grain terminals and mining operations provided operational perspective. Secondary sources include customs records for flighting component trade flows, SEC filings for listed material handling equipment manufacturers, BIS certification registries, and REACH compliance databases. Bottom-up unit economics triangulate against top-down sector spend estimates.
Sensitivity analysis around nickel price bands and PLI subsidy persistence tests forecast stability across the projection horizon. Segmentation dimensions modeled include product type (horizontal, vertical, inclined, Archimedean), end-use sector (food processing, mining, agriculture, construction), material grade (304, 316L, carbon steel), and technology tier (automated, conventional, modular). CAGRs derive from installed base replacement cycles and greenfield capacity announcements. Industry-specific inputs capture abrasion-resistant flighting adoption rates and CIP protocol penetration in dairy applications.
Material uncertainties — nickel and chromium price swings, carbon border adjustment implementation timelines, welding certification backlog extensions — sit outside the modeled envelope. Forecasts reflect assumptions about PLI scheme continuity and REACH substance restriction enforcement. Practitioners should keep alternative scenarios live as EU Green Deal compliance deadlines and Indonesian downstream mineral processing mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Chute Liners Market