
 Indonesia Construction Equipment Market | 2026-2036
Indonesia Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Construction Equipment Market Insights
Capital-intensity divergence between integrated manufacturers and assembly-dependent distributors is bifurcating competitive dynamics across the archipelago. Komatsu Ltd. leverages its captive remanufacturing network in Cibitung to sustain aftermarket revenue streams. Caterpillar Inc. anchors its position through dealer financing programs tied to mining contractor cash-flow cycles. SANY Heavy Industry Co., Ltd. competes aggressively on excavator payload capacity per rupiah deployed.
Construction equipment comprises self-propelled and towed machinery engineered for earthmoving, material handling, and vertical lifting in built-environment and extractive operations, with hydraulic systems typically generating breakout forces exceeding 200 kN in standard-class excavators. Excavators dominate product-type revenue owing to versatility across trenching, demolition, and quarry loading tasks, while hybrid technology gains traction as fuel-cost volatility pressures contractor operating budgets. Mining application volumes outpace residential construction in Kalimantan and Sulawesi, where overburden removal specifications demand 40-ton-class machines with reinforced undercarriages.
Indonesia's Ministry of Industry enforces SNI certification for imported earthmoving equipment, creating compliance barriers for non-certified Asian suppliers. The Ministry of Public Works and Public Housing imposes Bina Marga equipment standards that disqualify machinery lacking specified engine-emission tiers from national infrastructure tenders. BIS-equivalent alignment pressures from bilateral trade frameworks add parallel conformity costs for European and Chinese OEMs. Stakeholders must monitor Nusantara capital zone procurement schedules and evolving domestic content requirements to calibrate assembly-localization decisions.
Market Dynamics
The Indonesian construction equipment sector is contending with a divergence between state-mandated emission compliance and the operational realities of mining contractors in remote provinces. This tension is compressing equipment replacement cycles while elevating total cost of ownership calculations.
Growth Catalysts
- Nusantara Capital Zone Infrastructure:The new capital megaproject in East Kalimantan is generating concentrated demand for earthmoving fleets. Contractors are pre-positioning equipment to secure procurement slots under accelerated construction timelines.
- Bina Marga Specification Alignment:The Ministry of Public Works and Public Housing's technical standards for road-building machinery are filtering equipment eligibility. Manufacturers certifying to these specifications gain preferential access to Trans-Java toll corridor contracts.
- Kalimantan Mining Expansion:Overburden removal intensification at coal and nickel operations is pulling 40-ton-class excavator demand. Fleet operators are expanding rigid dump truck procurement to match extraction volumes.
Market Restraints
- Steel Price Volatility:Input cost swings for high-tensile steel plate are compressing manufacturing margins. Equipment producers face margin pressure when long-term contract pricing collides with spot market surges.
- SNI Certification Barriers:The Ministry of Industry's mandatory national standards for imported earthmoving equipment create compliance friction. Non-certified Asian suppliers encounter extended approval timelines that delay market entry.
- Used Equipment Arbitrage:Low-hour secondhand machines from Australian mining retirements are undercutting new equipment pricing in Sulawesi and Papua. This substitution pressure constrains OEM volume recovery.
Strategic Opportunities
- Papua Infrastructure Gap:Trans-Papua highway segments and mining logistics corridors remain under-equipped. Contractors establishing service depots in Jayapura and Timika can capture first-mover positioning.
- Hybrid Powertrain Adoption:Convergence of hydraulic efficiency improvements with electric assist systems is opening fuel-cost reduction pathways. Fleet operators in Java's high-fuel-price zones are piloting hybrid excavator configurations.
- Remanufacturing Network Expansion:Component rebuild capabilities in Cibitung and Surabaya are creating aftermarket revenue streams. OEMs with captive reman operations can extend customer lifecycle value beyond initial equipment sales.
Industry Challenges
- Hydraulic Technician Scarcity:Specialized maintenance capability for 200 kN+ breakout force systems is concentrated in Java. Remote site operators face extended downtime when component failures require specialist intervention.
- Dual Certification Burden:Alignment between SNI domestic standards and BIS-equivalent bilateral requirements is creating parallel testing costs. European and Chinese OEMs must navigate overlapping conformity procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Construction Equipment Market |
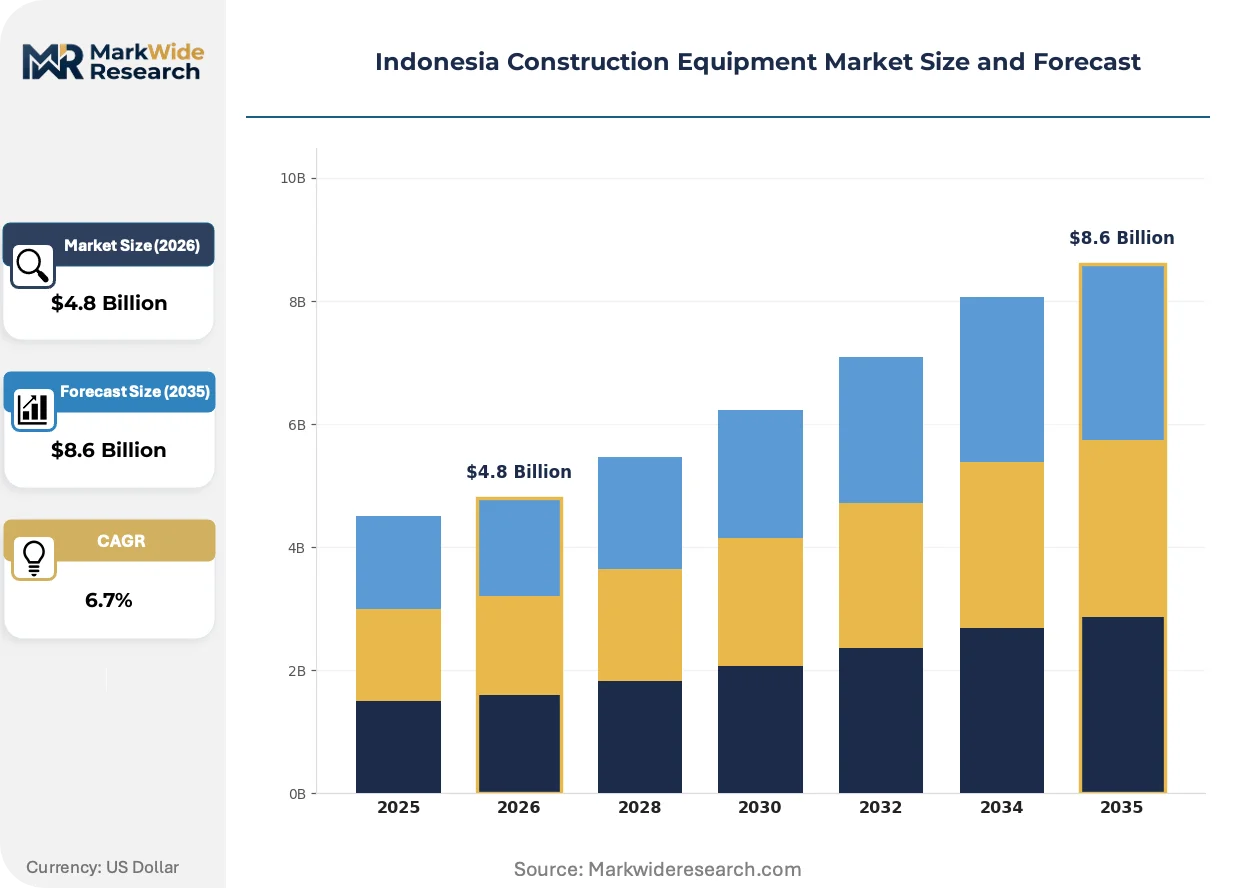
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Loaders Application: Residential Construction, Commercial Construction, Infrastructure Development, Mining End User: Contractors, Government, OEMs, Rental Companies Technology: Electric, Hydraulic, Pneumatic, Hybrid |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., SANY Heavy Industry Co., Ltd., Volvo Construction Equipment, Kobelco Construction Machinery Co., Ltd., Liebherr Group, XCMG Group, Zoomlion Heavy Industry Science & Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Construction Equipment Market Trends and Innovations
Equipment technology in Indonesia is pivoting toward fuel efficiency optimization and remote diagnostics capability. This shift is reshaping how contractors evaluate total ownership economics and how manufacturers structure aftermarket relationships.
Hybrid hydraulic-electric assist systems are bifurcating the excavator market between premium fuel-efficient configurations and conventional diesel platforms. Mining contractors in Kalimantan are piloting hybrid units for overburden removal, drawn by fuel cost volatility in remote logistics zones. The technology is bifurcating competitive positioning between OEMs with integrated powertrain development and those dependent on third-party engine suppliers.
Indonesia's Ministry of Environment and Forestry is tightening emission tier enforcement for equipment deployed in sensitive ecosystems. This regulatory pressure is accelerating engine platform refreshes among state contractors. Road-building fleets serving Bina Marga contracts are most affected, with operators retiring pre-Tier 3 machines to maintain tender eligibility.
Contractor buying committees are consolidating equipment procurement decisions at holding-company level rather than project-site autonomy. This centralization is compressing dealer relationships and favoring direct OEM engagement with national fleet operators. The pattern is most visible among integrated mining contractors in East Kalimantan, where procurement standardization is reducing equipment specification variance across subsidiary operations.
Indonesia Construction Equipment Market Segmentation
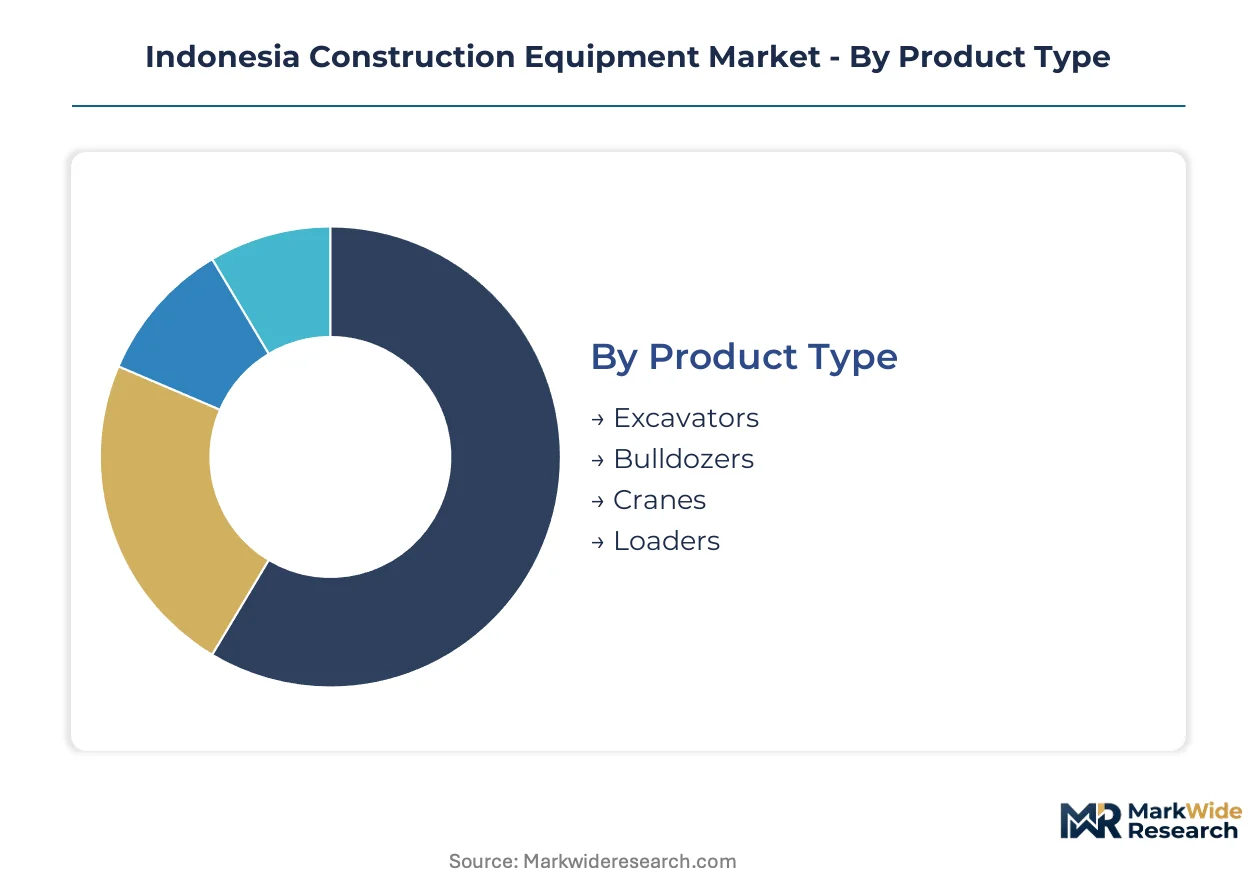
Segmentation in Indonesia's construction equipment market reveals how procurement authority, technology maturity, and application intensity create divergent margin profiles across the archipelago. Equipment suppliers must align certification and service capabilities to the specific compliance and operating conditions governing each segment cluster.
Product Type:
Substitution pressure from used equipment imports and rental fleet expansion is compressing new-unit pricing most severely in standardized machinery categories with shorter asset lifecycles.
- Excavators:Hydraulic systems generating breakout forces exceeding 200 kN dominate trenching, demolition, and quarry loading tasks across Java's Trans-Java corridor and Kalimantan mining zones. Demand concentrates in 40-ton-class units with reinforced undercarriages for overburden removal, where fuel-cost volatility pressures contractor operating budgets toward hybrid configurations.
- Loaders:Wheel and track configurations handle material stockpiling and site preparation with cycle-time efficiency critical to batch-plant throughput. Fleet operators in Nusantara capital zone earthworks are pre-positioning high-payload units to secure procurement slots under accelerated construction timelines.
- Bulldozers:Tracked dozers with elevated sprocket undercarriages perform ripping and grading in road-building applications governed by Bina Marga specifications.
- Cranes:Mobile and crawler configurations serve vertical lifting in commercial high-rise and infrastructure bridge segments, with tower cranes concentrated in Jakarta-Bandung urban corridors.
Excavators anchor the volume base while hybrid-equipped units gain share at the steepest rate across mining contractor fleets.
Application:
Cost-tier stratification separates premium-specification machinery for state-mandated emission compliance from economy-tier equipment serving remote-site extraction with limited regulatory oversight.
- Mining:Overburden removal and mineral extraction in Kalimantan and Papua pull rigid dump truck and large excavator procurement, with fleet expansion tied to nickel and coal output targets. Contractors face extended downtime when hydraulic component failures require specialist intervention from Java-based technicians.
- Infrastructure Development:Trans-Java toll road corridors and Trans-Papua highway segments demand road-building machinery certified to Bina Marga technical specifications, filtering equipment eligibility for state contracts.
- Residential Construction:Compact excavators and mini-loaders serve urban infill and suburban development across Greater Jakarta and Surabaya metropolitan zones.
- Commercial Construction:High-rise and industrial facility builds in Jakarta, Surabaya, and the Nusantara zone deploy tower cranes and concrete placing equipment.
Infrastructure Development commands the premium pricing tier while Mining generates the steepest unit-volume expansion trajectory.
End User:
Customer-type concentration is shifting procurement authority toward holding-company level consolidation, compressing dealer relationships and favoring direct OEM engagement with national fleet operators.
- Contractors:Integrated mining and civil construction operators in East Kalimantan standardize equipment specifications across subsidiary operations, reducing variance and enabling volume-based supplier negotiations. Procurement centralization is eliminating project-site autonomy in equipment selection.
- Government:Ministry of Public Works and Public Housing mandates Bina Marga emission tiers and SNI certification for national infrastructure tenders, disqualifying non-compliant machinery from state contracts.
- Rental Companies:Fleet lessors in Java and Sulawesi absorb demand volatility for contractors avoiding capital commitment, with utilization rates sensitive to construction cycle timing.
- OEMs:Captive equipment deployment supports demonstration, training, and aftermarket service network development in Cibitung and Surabaya remanufacturing hubs.
Contractors dominate current procurement volume while Rental Companies are expanding fleet capacity most aggressively.
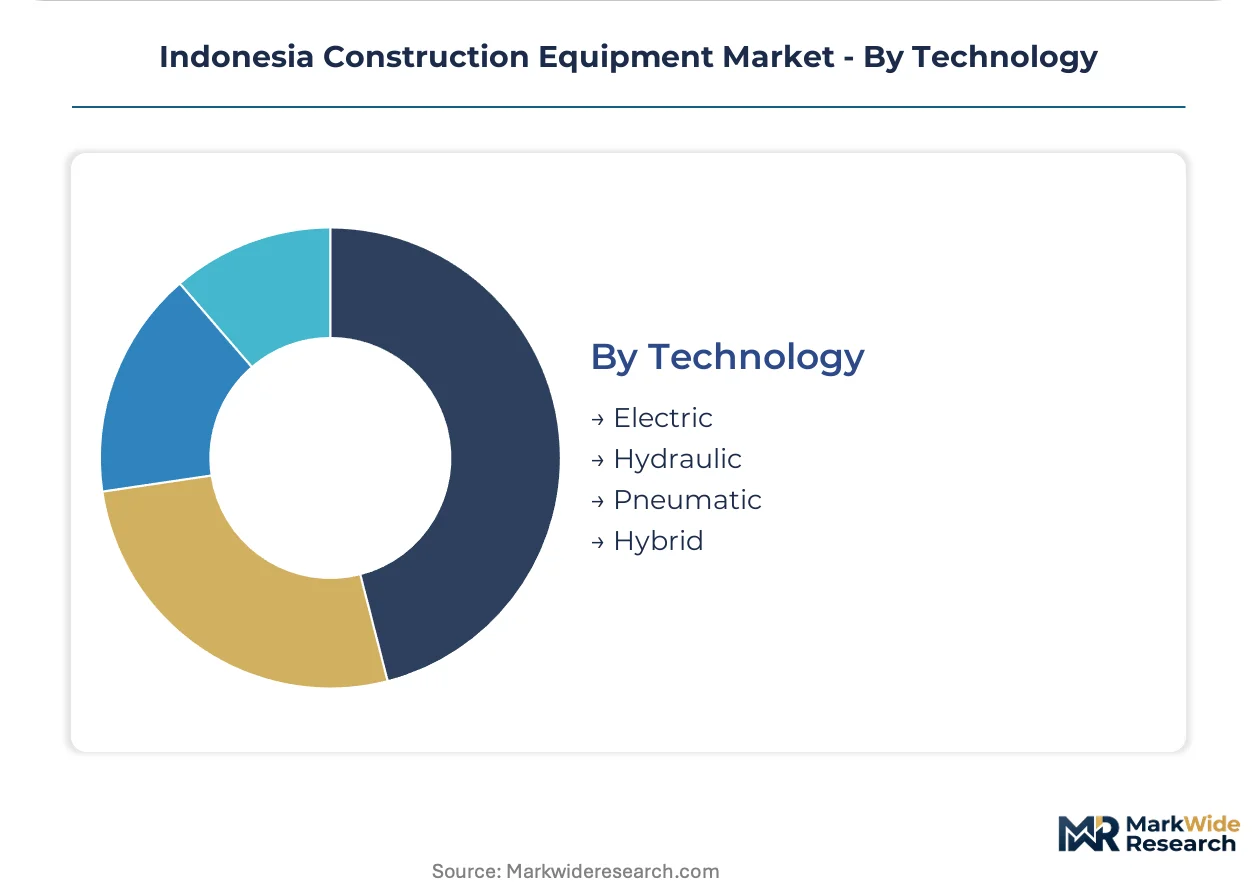
Technology:
Supply concentration in hydraulic component manufacturing limits rapid technology transition, with electric and hybrid powertrains dependent on imported drivetrain assemblies and specialized maintenance capability.
- Hydraulic:Conventional diesel-hydraulic systems remain standard for 40-ton-class excavators and rigid dump trucks in Kalimantan mining, with established technician training and parts availability supporting uptime targets. Fuel-cost volatility pressures operating budgets but infrastructure gaps slow alternative adoption.
- Hybrid:Electric-assist configurations combining hydraulic efficiency with regenerative systems are piloting in Java's high-fuel-price zones, with mining contractors testing units for overburden removal. Technology bifurcation is separating OEMs with integrated powertrain development from third-party engine-dependent assemblers.
- Electric:Battery-powered compact equipment is penetrating urban residential and commercial construction in Jakarta and Surabaya, constrained by charging infrastructure and duty-cycle limitations.
- Pneumatic:Compressed-air systems serve specialized drilling and breaking applications in quarry and tunneling segments with limited penetration in mainstream earthmoving.
Hydraulic technology retains the installed base dominance while Hybrid configurations are climbing the fastest among new-unit procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Java's Trans-Java corridor exceeds Kalimantan's mining zones by a significant margin, reflecting infrastructure contract premiums against extraction-site cost pressures. Equipment procurement in East Kalimantan commands volume scale, while Sulawesi and Papua lag on service network density.
Java
The Trans-Java toll road corridor and Greater Jakarta metropolitan zone drive excavator and loader demand for urban infill and highway expansion. The Ministry of Public Works and Public Housing enforces Bina Marga emission tiers that filter equipment eligibility for state tenders. Surabaya and Bandung industrial clusters concentrate rental fleet operations and remanufacturing service hubs.
East Kalimantan
Nickel and coal overburden removal operations pull 40-ton-class excavator procurement at the steepest rate nationwide. The Nusantara capital zone megaproject accelerates earthmoving fleet pre-positioning under compressed construction timelines. Balikpapan and Samarinda anchor mining contractor procurement centralization and direct OEM engagement models.
Sulawesi
Secondhand equipment arbitrage from Australian mining retirements undercuts new machinery pricing across nickel extraction sites. SNI certification barriers delay market entry for non-certified Asian suppliers seeking to serve Palu and Makassar logistics corridors. The Morowali industrial park concentrates smelter construction demand for heavy-lift cranes and concrete placing equipment.
Papua
Trans-Papua highway segments and remote mining logistics corridors remain chronically under-equipped relative to demand potential. The Ministry of Environment and Forestry tightens emission enforcement for equipment deployed in sensitive ecosystems around Jayapura and Timika. Contractors establishing service depots in these cities capture first-mover positioning on extended downtime risk.
Sumatra
Palm oil plantation expansion and geothermal infrastructure drive mid-size excavator demand across Riau and North Sumatra provinces. Domestic content requirements in bilateral trade frameworks pressure European and Chinese OEMs to calibrate assembly-localization decisions. Medan serves as the primary distribution gateway for equipment serving Sumatra's dispersed extraction and agricultural processing sites.
Indonesia Construction Equipment Market Competitive Landscape
Concentration sits with integrated Japanese and American manufacturers possessing captive remanufacturing networks and dealer financing infrastructure. The vendor base spans three distinct tiers: premium OEMs with full-service ecosystems, mid-tier assemblers competing on payload capacity per rupiah, and emerging Chinese fabricators penetrating on price. Strategic moves center on hybrid powertrain development and aftermarket network expansion into underserved outer islands.
Within the premium integrated tier, Komatsu Ltd. and Caterpillar Inc. exemplify archetypes built around remanufacturing density and captive financing programs respectively. SANY Heavy Industry Co., Ltd. occupies a position representing aggressive payload-capacity positioning against cost-sensitive mining contractors. These three anchors illustrate how competitive differentiation bifurcates between lifecycle service capture and upfront equipment economics.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| SANY Heavy Industry Co., Ltd. |
| Volvo Construction Equipment |
| Kobelco Construction Machinery Co., Ltd. |
| Liebherr Group |
| XCMG Group |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Used equipment arbitrage from Australian mining retirements simultaneously reshapes supply geography toward Sulawesi and Papua ports and compresses new machinery pricing across nickel extraction zones. This substitution dynamic forces OEMs to recalibrate regional pricing strategies against depreciated asset inflows while distributors absorb inventory holding costs in under-served outer islands.
Pricing Analysis
The customization-premium spread between Bina Marga-certified road-building machinery and standard excavator configurations runs wide across Java's state contract corridors. Three-tier pricing structure across premium, standard, and economy levels separates emission-compliant fleets from pre-Tier 3 units and secondhand imports. Price differentiation rests on SNI certification status and after-sales service bundling. Cost compression in economy-tier segments is intensifying because low-hour Australian retirements flood Sulawesi replacement markets. Rental companies exhibit highest price sensitivity; integrated mining contractors in East Kalimantan show lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan container lanes dominate landed equipment economics for Chinese and Korean OEMs serving Jakarta and Surabaya ports. Manufacturing concentration centers on Japan, China, and South Korea for hydraulic systems and engine assemblies. Raw material dependencies span high-tensile steel plate from Chinese mills, hydraulic pumps from Japanese suppliers, and electronic control modules from Korean fabricators. Single-source vulnerability sits with specialized hydraulic component vendors for 200 kN+ breakout force systems. Distribution runs through Cibitung and Surabaya remanufacturing hubs to mining contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's construction equipment sector represents an early-cycle expansion story, with Nusantara capital zone earthworks accelerating fleet pre-positioning ahead of compressed construction timelines.
For Market Incumbents: Compound aftermarket revenue capture by expanding captive remanufacturing capacity in Cibitung and Surabaya to offset new-unit margin compression from used equipment arbitrage. Deepen backward integration into hydraulic component sourcing to reduce single-source exposure from Japanese pump suppliers. Prioritize Bina Marga certification maintenance to defend state contract eligibility against emerging Chinese assemblers. For New Entrants and Emerging Players: Remote site service capability gaps in Papua and Sulawesi present white-space entry points where incumbent technician density remains thin. Target Jayapura and Timika logistics corridors with mobile service units and parts depots to capture first-mover positioning on extended downtime risk. Pursue direct OEM engagement with integrated mining contractors rather than dealer channel dependence to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier assemblers with payload-capacity competitiveness and nascent hybrid powertrain development programs. Long-term viability across the projection horizon favors suppliers with demonstrated SNI certification navigation and assembly-localization flexibility under bilateral trade frameworks. Watch Nusantara procurement schedule acceleration as the inflection signal for fleet expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Development | Fuel-cost volatility in Kalimantan mining zones accelerates electric-assist configuration pilots. |
| Remanufacturing Network Expansion | Captive rebuild capabilities in Cibitung extend customer lifecycle value beyond initial equipment sales. |
| SNI Certification Investment | Ministry of Industry compliance barriers filter non-certified Asian suppliers from state tender eligibility. |
| Direct OEM Engagement Model | Holding-company procurement centralization in East Kalimantan compresses traditional dealer relationships. |
| Outer Island Service Depot Buildout | Jayapura and Timika logistics gaps create first-mover positioning for contractors establishing maintenance presence. |
Research Methodology
Desk research of trade customs records, Ministry of Public Works tender databases, and mining contractor fleet disclosures preceded structured interviews with equipment procurement directors, aftermarket service heads, hydraulic systems engineers, and rental fleet managers. Primary fieldwork across Java, East Kalimantan, and Sulawesi validated secondary estimates of unit deployment patterns and replacement cycle timing. Bottom-up equipment stock estimates triangulated against top-down construction output projections.
Variance decomposition across product type, application intensity, technology tier, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include equipment category, end-use sector, powertrain configuration, and geographic compliance zone. CAGRs were derived from fitted trend lines applied to historical procurement data and projected infrastructure investment schedules. Forecast inputs incorporated Bina Marga specification evolution timelines and Nusantara zone construction phasing.
Forecasts assume regulatory continuity in Ministry of Industry SNI enforcement and Ministry of Public Works Bina Marga emission tier mandates; material policy shifts would require re-modeling. Steel price volatility, used equipment import tariff adjustments, and hybrid technology cost curves represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Smart Crane Market
Construction Equipment
Static Crane Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Street Cleaning Machine Market