
 Global PDC Drill Bits Market | 2026-2036
Global PDC Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Global PDC Drill Bits Market Outlook
Aftermarket service revenue is tilting toward cutter reconditioning and body refurbishment rather than new-bit sales in mature basins. Schlumberger leverages its integrated drilling services portfolio to bundle bit supply with real-time downhole analytics. Baker Hughes Company sustains manufacturing scale through captive polycrystalline diamond compact production facilities in multiple continents. Halliburton anchors its position through direct field engineering support deployed at rig sites across North American shale plays.
Polycrystalline diamond compact drill bits are cutting tools that bond synthetic diamond grit to tungsten carbide substrates under high-pressure, high-temperature conditions, typically achieving hardness values exceeding 4000 HV and operating at rotational speeds up to 300 RPM in hard-rock formations. Their primary industrial purpose is to penetrate abrasive sedimentary and igneous rock sequences in oil and gas well construction while maintaining rate-of-penetration efficiency over extended downhole intervals. Fixed cutter configurations dominate the bit type segment due to their superior durability in interbedded formations, while hybrid designs are gaining traction in geothermal applications where thermal cycling degrades conventional cutters. The 8-12 inch size band concentrates the largest revenue pool, serving standard horizontal wellbore diameters in unconventional oil and gas development.
API Q2 specifications govern material qualification and dimensional tolerances for PDC bits sold into US onshore and offshore markets, while ISO 10424-1 sets international baseline requirements for rotary drilling equipment interoperability. REACH and RoHS frameworks in Europe constrain cobalt and nickel content in matrix body compositions, pushing manufacturers toward alternative binder formulations. Stakeholders must monitor how EPA methane emission regulations and EU Green Deal carbon border adjustments reshape drilling activity levels and bit replacement cycles across their served geographies.
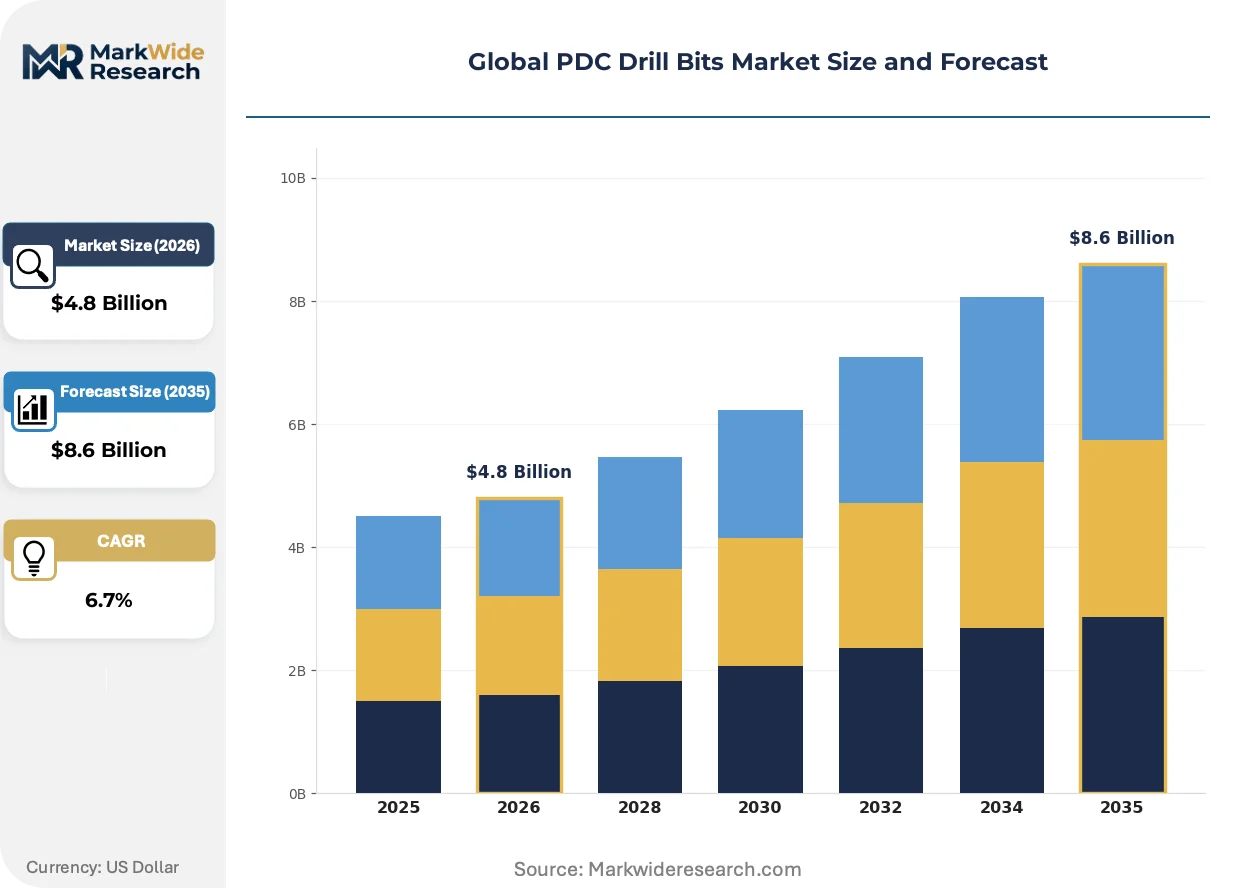
Market Dynamics
Deepwater drilling contractors in the Gulf of Mexico and West Africa are extending laterals into high-pressure, high-temperature formations that exceed the thermal limits of conventional cutter designs. This operational push is forcing rapid iteration in matrix body materials and thermal barrier coatings.
Growth Catalysts
- REACH and RoHS frameworks:European constraints on cobalt and nickel content in matrix body compositions are accelerating alternative binder formulation R&D, opening patent white space for new entrants with tungsten-copper or iron-based binders.
- Horizontal laterals in Texas shale basins:Permian and Eagle Ford operators are standardizing 8-12 inch fixed-cutter configurations for extended-reach wells, creating sustained demand for abrasion-resistant cutter arrays.
- Geothermal energy expansion:Enhanced geothermal systems in Nevada and Utah are deploying PDC bits in crystalline basement formations where thermal cycling previously limited tool life, validating hybrid thermal management designs.
Market Restraints
- Synthetic diamond grit supply concentration:High-pressure, high-temperature synthesis capacity clusters in China and Ireland, creating single-source vulnerability for polycrystalline diamond compact substrate production.
- API Q2 and ISO 10424-1 certification timelines:New bit designs require 18-24 month qualification cycles for offshore deployment, compressing innovation returns and favoring incumbent manufacturers with established testing protocols.
- Tungsten carbide price volatility:Powder metallurgy feedstock costs fluctuate with Chinese export quotas and conflict mineral sourcing restrictions, squeezing margin predictability for matrix body producers.
Strategic Opportunities
- Saudi Aramco unconventional gas program:Jafurah Basin development is importing North American horizontal drilling expertise, creating demand for fixed-cutter bits calibrated to Arabian Peninsula carbonate and shale interbeds.
- Real-time downhole analytics integration:Bit-telemetry convergence with measurement-while-drilling systems enables predictive cutter wear modeling, shifting revenue models toward performance-based contracts.
- EU Green Deal carbon border adjustments:Embedded carbon accounting in drilling equipment imports will favor manufacturers with low-carbon synthesis processes, rewarding European and North American production facilities.
Industry Challenges
- cutter reconditioning technician shortage:Laser cladding and precision grinding skills are concentrated among retiring specialists in Oklahoma and Texas, constraining aftermarket service scaling.
- Legacy rig fleet integration:Older top-drive systems lack the torque and vibration damping required for advanced PDC bit designs, forcing compatibility engineering that delays field trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PDC Drill Bits Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oil & Gas, Water Well, Geothermal, Mining Material: Diamond, Tungsten Carbide, Composite, Steel Bit Type: Fixed Cutter, Roller Cone, Hybrid, Specialty Size: 5-8 Inches, 8-12 Inches, 12-16 Inches, Others |
| Companies Covered | Schlumberger, Baker Hughes Company, Halliburton, National Oilwell Varco, Sandvik AB, Varel International Energy Services, Atlas Copco, Weatherford International, Rockpecker Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PDC Drill Bits Market Strategic Shifts
Material science advances and digital integration are converging to extend bit life in thermally extreme environments while compressing the feedback loop between downhole conditions and surface engineering decisions.
Thermally stable polycrystalline (TSP) cutter technology is hybridizing with conventional PDC substrates to create gradient-hardness interfaces that resist delamination above 350°C. Geothermal developers in Iceland and Indonesia are piloting these configurations in basaltic formations where conventional cutters fail within 50 drilling hours. The structural consequence is a blurring of product category boundaries between oilfield and geothermal tool specifications.
EPA methane emission regulations under the Inflation Reduction Act are tightening fugitive emission standards for drilling operations, indirectly pressuring bit replacement cycles. Operators in the Permian Basin are accelerating bit changes to minimize non-productive time and associated venting events. The 8-12 inch size band is experiencing the most pronounced cycle compression as lateral lengths extend beyond 15,000 feet.
Service unbundling is fragmenting traditional supply relationships. National oil companies in the Middle East are separating bit procurement from integrated drilling contracts, creating direct vendor relationships that bypass oilfield service majors. This pattern is most visible in Abu Dhabi and Kuwait, where ADNOC and KOC are building captive technical evaluation capabilities to assess cutter performance independently.
Global PDC Drill Bits Market Segmentation
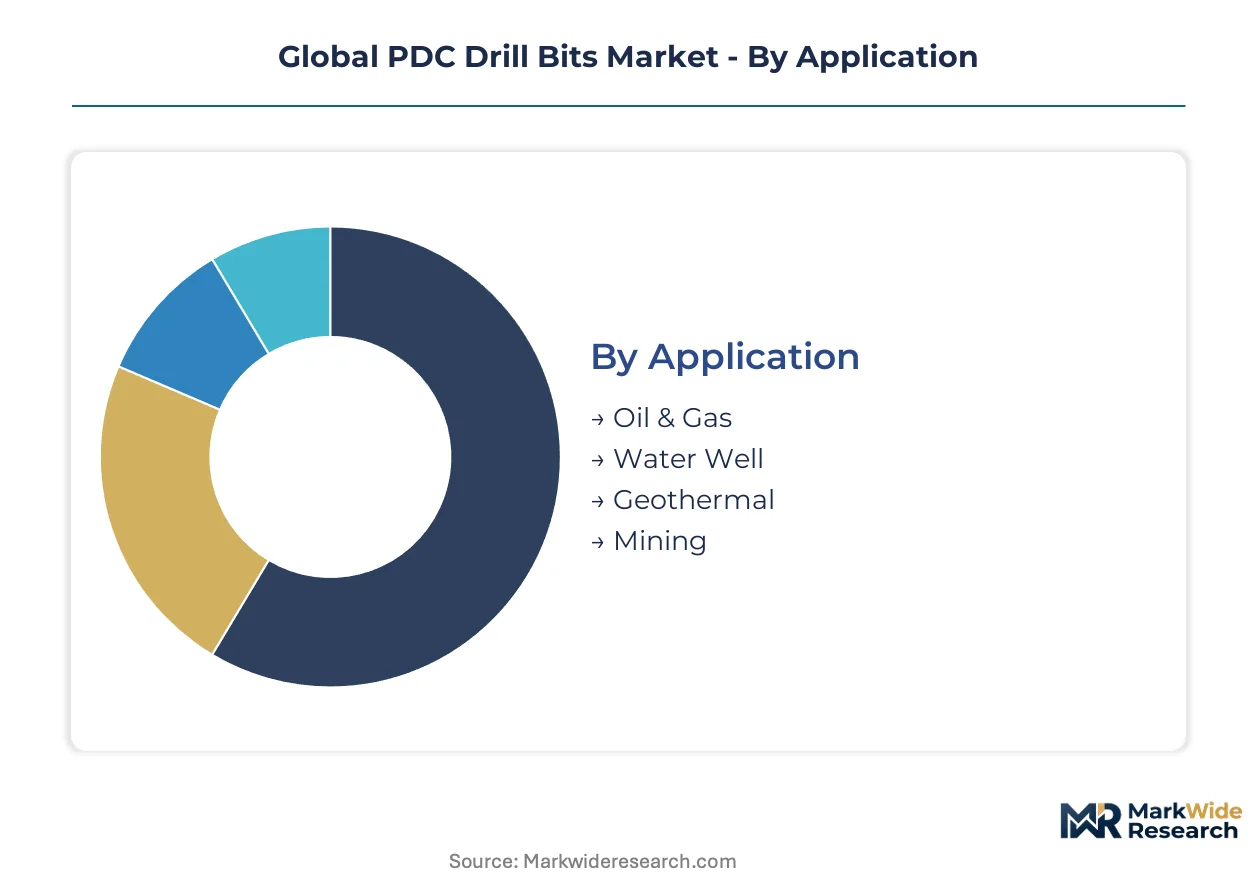
PDC drill bit procurement patterns diverge sharply across application environments, material specifications, and dimensional requirements. Understanding these segment boundaries clarifies why manufacturers maintain parallel product lines despite apparent functional overlap.
Application:
Customer type dictates performance thresholds, replacement cycles, and contractual risk allocation across end-use sectors.
- Oil & Gas:Horizontal laterals in Permian Basin shale formations drive demand for 8-12 inch fixed-cutter arrays rated for abrasive interbedded sequences. Operators prioritize rate-of-penetration consistency over extended single-run longevity to minimize non-productive time during methane-sensitive completion windows.
- Geothermal:Crystalline basement drilling in Nevada and Iceland validates hybrid thermal management designs where thermal cycling above 350°C degrades conventional cutter substrates. Enhanced geothermal systems are expanding addressable formation types previously excluded from PDC economics.
- Water Well:Municipal and agricultural groundwater projects in India and Saudi Arabia favor cost-optimized steel-body configurations for sedimentary overburden penetration.
- Mining:Mineral exploration programs in Western Australia and Chile deploy specialty bits for pre-collar drilling in hard-rock terranes.
Oil & Gas holds installed capacity. Geothermal is rotating up the share rankings.
Material:
Supply concentration and regulatory constraints on binder chemistry differentiate sourcing strategies across substrate categories.
- Diamond:Synthetic polycrystalline diamond compact substrates achieve hardness exceeding 4000 HV through high-pressure, high-temperature synthesis. Synthesis capacity clusters in China and Ireland, creating qualification bottlenecks for new bit designs seeking API Q2 certification.
- Tungsten Carbide:Matrix body compositions rely on powder metallurgy feedstocks subject to Chinese export quota volatility and conflict mineral sourcing restrictions. REACH and RoHS frameworks in Europe are accelerating alternative binder formulation R&D toward tungsten-copper or iron-based systems.
- Composite:Gradient-hardness interfaces combining thermally stable polycrystalline with conventional PDC substrates resist delamination in high-temperature geothermal applications.
- Steel:Forged alloy bodies dominate water well and shallow oilfield segments where thermal exposure remains below 200°C and cost sensitivity prevails.
Diamond maintains premium pricing power. Composite formulations are climbing fastest on unit volume.
Bit Type:
Mechanical configuration determines compatibility with rig torque capacity, vibration damping systems, and formation abrasiveness.
- Fixed Cutter:Dominant configuration for unconventional oil and gas development, with polycrystalline diamond compact arrays bonded to tungsten carbide or steel substrates. Saudi Aramco's Jafurah Basin unconventional gas program is importing North American horizontal drilling expertise calibrated to fixed-cutter performance in carbonate-shale interbeds.
- Roller Cone:Retains relevance in deepwater Gulf of Mexico applications where formation unpredictability and stuck-pipe risk favor tri-cone repairability over PDC single-run economics.
- Hybrid:Combines fixed-cutter efficiency with roller cone reliability in geothermal basaltic formations where thermal cycling and vibration coexist.
- Specialty:Custom-engineered configurations for mining pre-collar work and scientific drilling programs requiring non-standard gauge protection.
Fixed Cutter anchors field deployment. Hybrid designs are gaining traction fastest in thermal applications.
Size:
Borehole diameter directly correlates with lateral length economics and cementing program specifications.
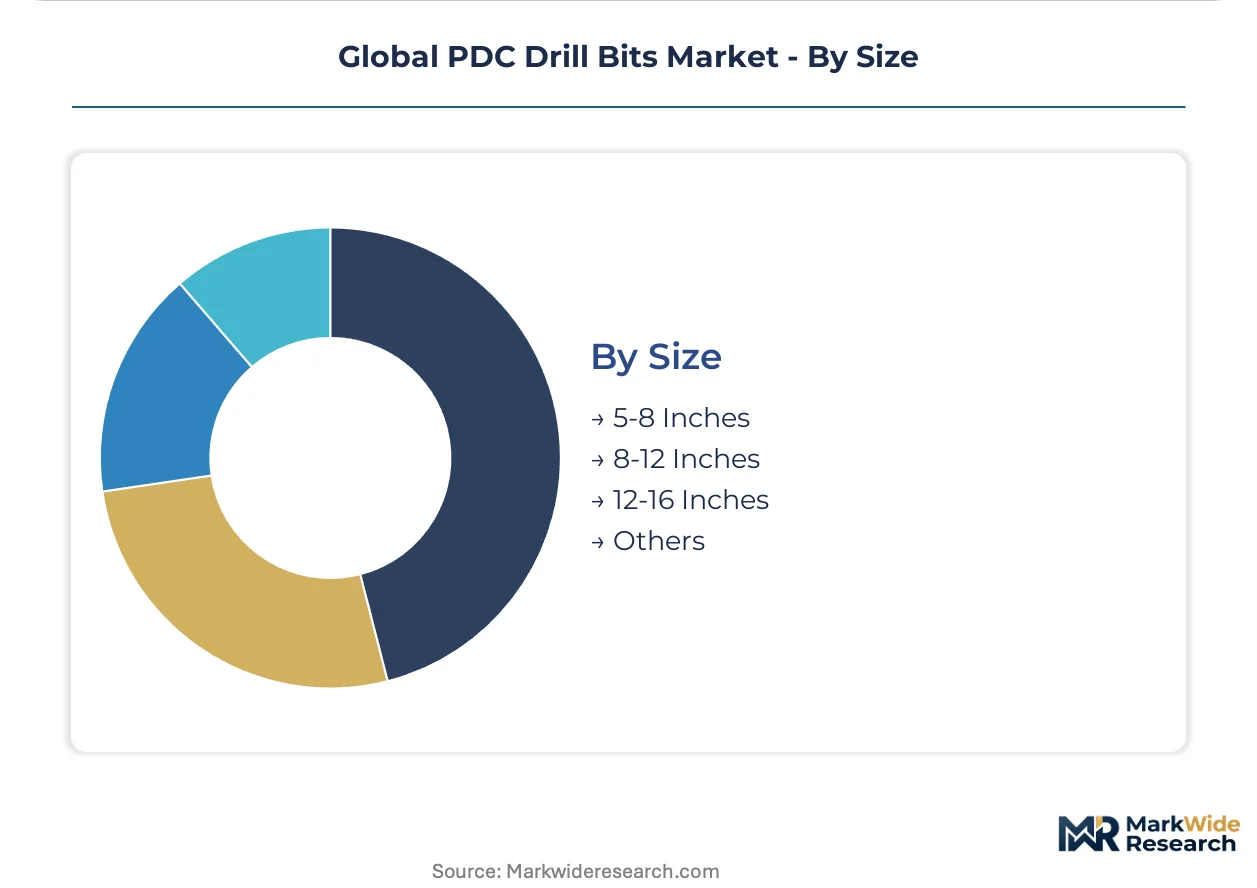
- 8-12 Inches:Concentrates the largest revenue pool, serving standard horizontal wellbore diameters in Texas shale basins. EPA methane emission regulations under the Inflation Reduction Act are compressing replacement cycles in this band as operators minimize non-productive time.
- 5-8 Inches:Slimhole configurations for re-entry drilling and mature field redevelopment where parent-child well interference constrains casing programs.
- 12-16 Inches:Surface and intermediate casing holes in deepwater West Africa developments, requiring enhanced matrix body strength for high-torque top-drive systems.
- Others:Non-standard gauges for scientific coring, geothermal slimholes, and mining exploration where commodity economics tolerate custom engineering premiums.
8-12 Inches commands dominant placement. 5-8 Inches is expanding most quickly on re-entry activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize rate-of-penetration consistency in shale laterals, while Middle Eastern national oil companies emphasize single-run longevity in carbonate formations. European procurement increasingly weighs embedded carbon under EU Green Deal border adjustments.
United States
Permian Basin horizontal drilling drives 8-12 inch fixed-cutter procurement for extended-reach wells exceeding 15,000 feet. EPA methane emission regulations under the Inflation Reduction Act compress bit replacement cycles to minimize non-productive time. Houston anchors manufacturing and field engineering deployment for North American shale plays.
Saudi Arabia
Jafurah Basin unconventional gas development imports North American horizontal expertise calibrated to carbonate-shale interbeds. Saudi Aramco separates bit procurement from integrated drilling contracts, building captive technical evaluation capabilities. Dammam concentrates supply chain infrastructure for Arabian Peninsula drilling programs.
China
Synthetic diamond grit synthesis capacity clusters domestically, creating vertical integration advantages for polycrystalline diamond compact substrate production. MIIT industrial standards govern domestic rotary drilling equipment interoperability. Zhengzhou houses high-pressure, high-temperature synthesis facilities serving Asia-Pacific bit manufacturers.
Norway
North Sea deepwater contractors demand enhanced matrix body strength for high-torque top-drive systems in subsea formations. REACH frameworks constrain cobalt content in binder formulations, accelerating alternative material R&D. Stavanger anchors offshore drilling technology development for harsh environment applications.
Brazil
Pre-salt carbonate drilling programs require hybrid thermal management designs for high-pressure, high-temperature formations. ANVISA-equivalent petroleum regulator standards govern offshore equipment qualification timelines. Rio de Janeiro concentrates deepwater drilling contractor headquarters and technical service capabilities.
Global PDC Drill Bits Market Competitive Environment
Capability concentration sits with integrated oilfield service majors; scale advantage sits with specialized bit manufacturers. The market structures around three tiers: full-service drilling contractors bundling bits with telemetry, standalone bit specialists with captive synthesis capacity, and regional fabricators serving cost-sensitive basins. Dominant competitive moves include backward integration into polycrystalline diamond compact production and unbundling of bit procurement from integrated service contracts.
Within the integrated service tier, Schlumberger, Baker Hughes Company, and Halliburton exemplify archetypes combining bit supply with real-time downhole analytics. These entities occupy positions where drilling performance data feeds iterative cutter design, creating feedback loops unavailable to standalone manufacturers. Regional specialists including Varel International Energy Services and Rockpecker Limited sit within focused fabrication tiers serving discrete geographic markets or application niches.
| Leading Market Players |
|---|
| Schlumberger |
| Baker Hughes Company |
| Halliburton |
| National Oilwell Varco |
| Sandvik AB |
| Varel International Energy Services |
| Atlas Copco |
| Weatherford International |
| Rockpecker Limited |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese synthetic diamond grit synthesis capacity determines both the premium-to-economy pricing spreads across bit tiers and the geographic clustering of matrix body fabrication facilities. Tungsten carbide powder metallurgy feedstock volatility feeds directly into contract structure negotiations, compressing margins for non-integrated manufacturers while rewarding captive synthesis operations.
Pricing Analysis
Long-term offtake agreements dominate procurement between major operators and integrated service providers, insulating volume purchasers from spot-market tungsten carbide fluctuations. Price differentiation rests on API Q2 certification tier and after-sales service bundling, with offshore-qualified bits commanding substantial premiums over onshore-standard configurations. Cost compression in the steel-body economy tier intensifies because of import competition from regional Asian fabricators. National oil companies in the Middle East exhibit lowest price sensitivity due to performance-based contracting priorities, while municipal water well programs in India demonstrate highest sensitivity to unit acquisition costs.
Supply Chain Analysis
Export control regimes on high-pressure, high-temperature synthesis equipment constrain technology transfer to emerging manufacturing bases, reinforcing concentration in China and Ireland. Raw material flows draw from Zhengzhou diamond synthesis clusters, Swedish tungsten carbide powder producers, and German precision grinding equipment suppliers. Single-source vulnerability in polycrystalline diamond compact substrate production creates qualification bottlenecks for new bit designs seeking offshore deployment. Distribution runs through integrated service company logistics networks for oilfield customers, with direct manufacturer relationships gaining share in unbundled procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geothermal energy expansion represents a high-growth disruption, with thermal cycling requirements above 350°C validating hybrid bit designs that blur traditional oilfield-geothermal category boundaries.
For Market Incumbents: Pre-empt service unbundling by national oil companies through captive technical evaluation partnerships that embed proprietary analytics into procurement decisions. Deepen backward integration into polycrystalline diamond compact synthesis to offset tungsten carbide price volatility and defend margin structure against emerging Asian fabricators. For New Entrants and Emerging Players: Alternative binder formulations for REACH-compliant matrix bodies represent the most penetrable entry point, with European geothermal contractors seeking cobalt-reduced solutions. Target direct vendor relationships with ADNOC and KOC procurement teams as integrated drilling contracts fragment. Lead with rapid API Q2 qualification timelines as the go-to-market differentiator against incumbent testing protocols. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape, favoring production facilities with low-carbon synthesis footprints in North America and Europe. Five-to-ten year viability hinges on thermal management technology positions rather than conventional abrasion-resistant portfolios. Monitor EPA methane regulation enforcement intensity as the signal indicating bit replacement cycle compression rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Synthesis | Captive HPHT capacity insulates margin structure from Chinese export quota volatility. |
| Hybrid Thermal Management Product Launch | TSP-PDC gradient interfaces unlock geothermal basaltic formations above 350°C. |
| Real-Time Telemetry Integration Partnership | Bit-MWD convergence enables predictive wear modeling and performance-based contracting. |
| Alternative Binder Formulation R&D Program | Tungsten-copper systems address REACH cobalt constraints and open European procurement channels. |
| Regional Fabrication Footprint Expansion | Dammam and Houston facilities reduce logistics exposure for Middle East and Permian Basin demand. |
Study Parameters
Desk research of API specification documentation, ISO certification registries, and customs trade flow databases preceded structured interviews with drilling contractor procurement directors, bit design engineers at integrated service companies, geothermal project developers, and aftermarket reconditioning technicians. Primary fieldwork across Texas shale plays, North Sea offshore installations, and Saudi unconventional gas sites validated secondary estimates. Bottom-up unit demand modeling and top-down expenditure allocation triangulated market sizing across the analysis window.
Assumptions held fixed include regulatory enforcement timelines for EPA methane standards and EU carbon border adjustments, while oil price bands and drilling rig counts varied across scenarios. Segmentation dimensions modeled comprised application environment, material substrate, bit configuration, and dimensional specification alongside regional regulatory cluster. CAGRs derived from historical replacement cycle patterns and projected lateral length extensions. Forecast inputs incorporated tungsten carbide price indices and geothermal capacity buildout announcements.
Stress conditions across synthetic diamond grit supply disruptions, REACH binder formulation phase-outs, and deepwater drilling activity levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline durations and thermal management technology adoption curves. Material shifts in Chinese export control regimes or EU embedded carbon accounting scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dozer Blade Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Broaching Machine Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Compressed Earth Block Machine Market