
 Hydraulic Press Machine Market | 2026-2036
Hydraulic Press Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Press Machine Market Outlook
China's Jiangsu and Zhejiang provinces is fragmenting as domestic fabricators expand mid-tonnage press capacity for electric vehicle battery tray stamping. Schuler Group GmbH leverages its German engineering base to sustain high-margin large-frame press dominance in European automotive OEM channels. Beckwood Press specializes in custom hydraulic solutions for aerospace composite forming, occupying a defensible niche against standardized Asian imports.
A hydraulic press machine generates compressive force through a hydraulic cylinder driven by a pump-powered fluid system, typically achieving pressing capacities from 10 tons to over 10,000 tons with stroke precision controlled by servo valves and proportional pressure regulation. Its primary industrial purpose is permanent deformation of metals, composites, and powders into engineered shapes through controlled pressure application over defined dwell times. Automotive application leads absolute volume as OEMs and tier-1 suppliers convert stamping lines to hybrid electric-hydraulic systems for aluminum-intensive body-in-white production. Metalworking end users represent the fastest-growing demand pool as small-batch fabricators adopt CNC-integrated hydraulic presses for just-in-time production runs.
OSHA mechanical power press regulations in the United States mandate two-hand controls and point-of-operation guarding, compelling capital replacement of pre-2000 installed machines. CE marking under the EU Machinery Directive enforces documented risk assessments and safety-rated control systems, creating compliance barriers for non-European entrants. China's GB standards administered by SAMR impose hydraulic system pressure testing and structural load certification on domestically sold equipment. Stakeholders must monitor how evolving carbon accounting rules under China's dual carbon goals and the EU Green Deal reshape energy efficiency requirements for hydraulic power units.
Market Dynamics
Servo-hydraulic press architecture is hybridizing with mechanical drive systems to compress cycle times while maintaining forming precision, forcing incumbent suppliers to reengineer core product lines or cede share to hybrid specialists.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory safety-rated control systems and documented risk assessments are compelling European metal fabricators to replace pre-2010 hydraulic presses with compliant equipment.
- Aluminum-intensive EV chassis:Automotive OEMs in Germany and Japan are installing large-frame servo-hydraulic presses for battery tray and structural component stamping at higher tonnage precision.
- Jiangsu-Zhejiang manufacturing cluster:Domestic Chinese fabricators are expanding mid-tonnage press capacity to serve tier-1 electric vehicle suppliers replacing mechanical stamping lines.
Market Restraints
- Specialized servo valve supply:Proportional hydraulic control components concentrate among Japanese and German precision component suppliers, creating input bottlenecks for mid-tier press builders.
- High-alloy steel input costs:Frame-grade castings and forged platens require nickel-chromium-molybdenum steel grades subject to commodity price volatility.
- Mechanical press substitution:High-speed mechanical stamping retains cost advantage for thin-gauge, high-volume production runs in consumer electronics and appliance manufacturing.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Production-linked incentives for advanced automotive parts are attracting hydraulic press investments for domestic EV supply chain localization.
- Composite aerospace forming:Carbon fiber reinforced polymer molding for aircraft structural components requires heated platen hydraulic systems with precise dwell temperature control.
- Retrofit control system upgrades:Digital servo drive retrofits for existing mechanical presses create aftermarket revenue streams without full machine replacement.
Industry Challenges
- Servo-hydraulic control engineering talent:Shortage of engineers proficient in proportional valve tuning and closed-loop force control limits product development velocity for mid-size manufacturers.
- CE marking certification timelines:Third-party notified body assessments for EU Machinery Directive compliance extend product launch cycles by four to eight months.
- Legacy mechanical press integration:Hybrid line configurations require synchronization of disparate control architectures, complicating automotive tier-1 supplier qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Press Machine Market |
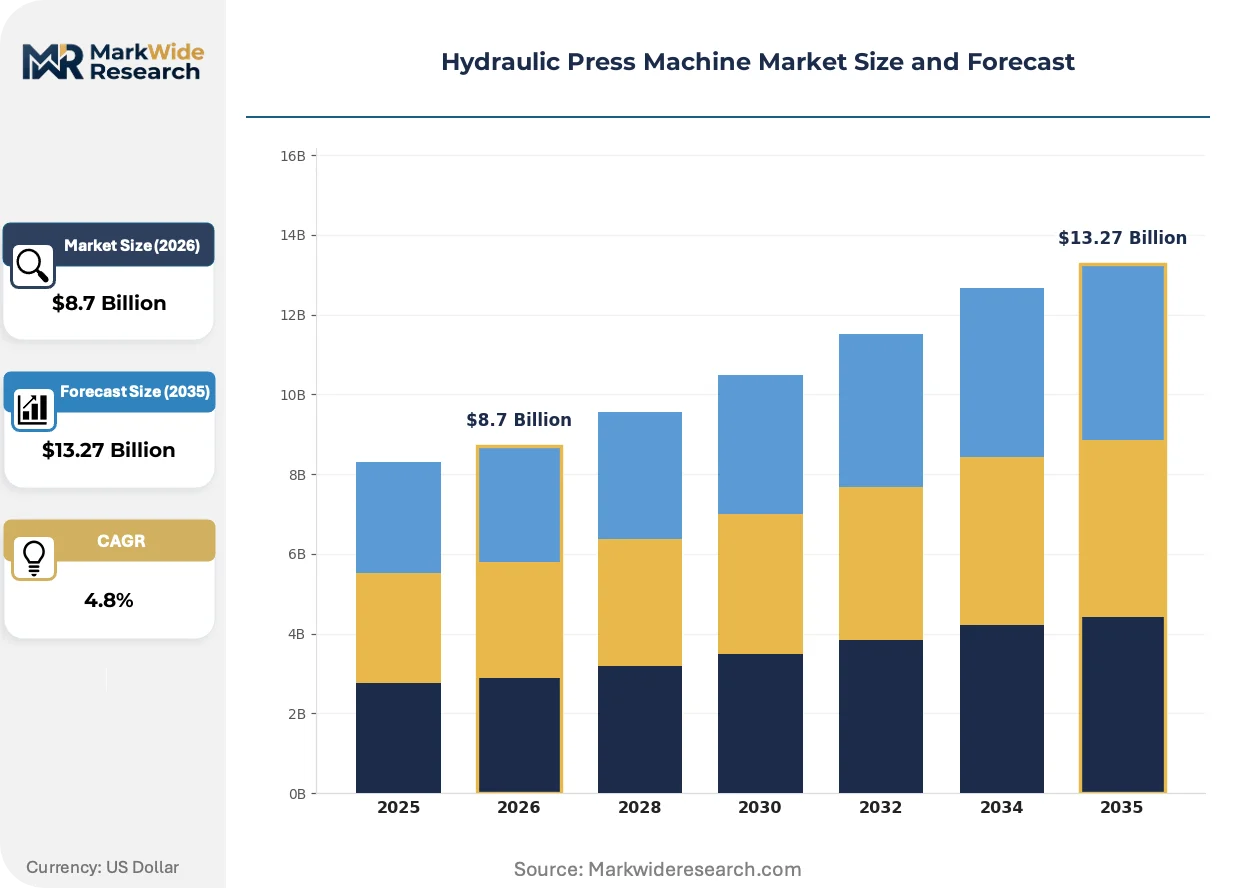
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
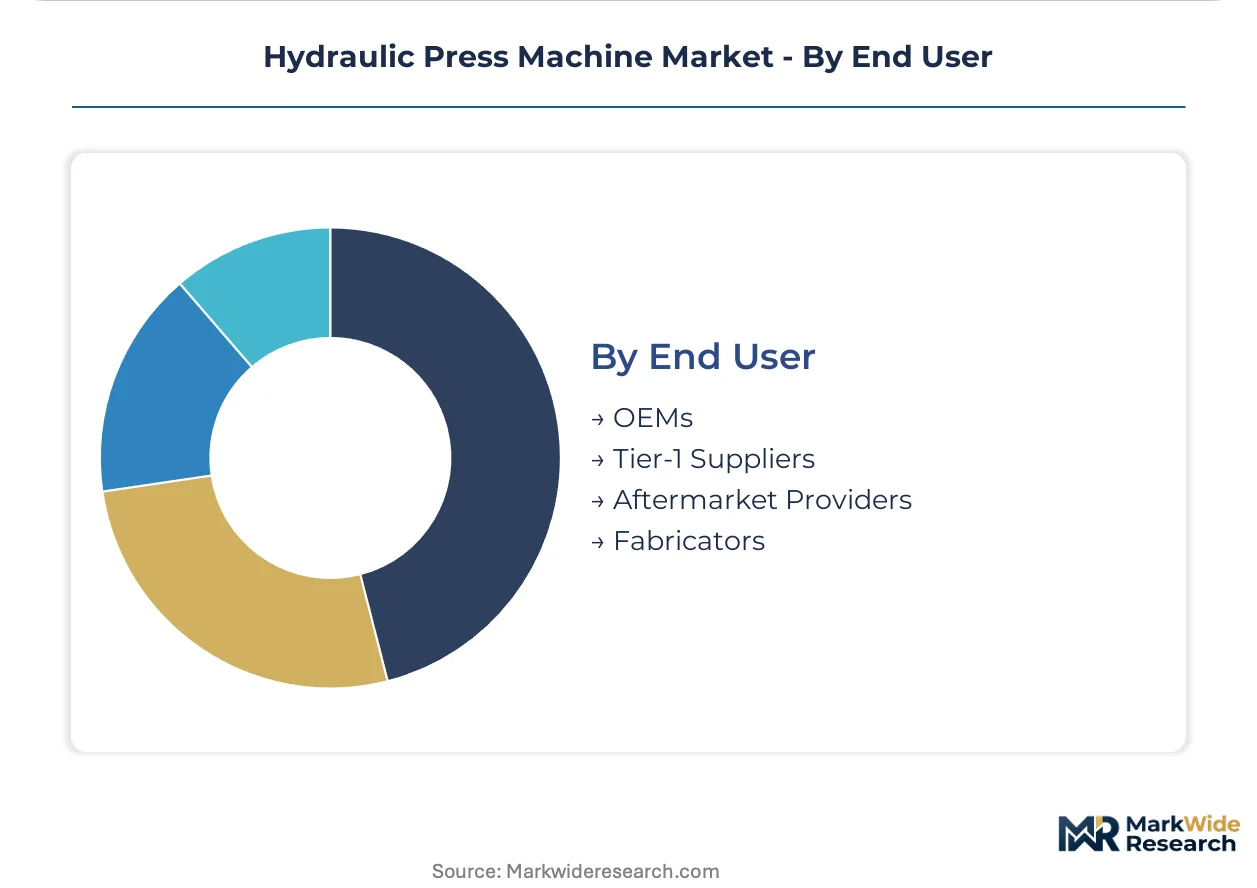
| Segmentation | Product Type: Mechanical, Pneumatic, Electric, Hybrid Application: Automotive, Aerospace, Metalworking, Manufacturing Installation: On-site, Off-site, Mobile, Fixed End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fabricators |
| Companies Covered | Macrodyne Technologies, Dorst Technologies GmbH & Co. KG, Schuler Group GmbH, Greenerd Press & Machine Co., Gasbarre Products, Inc., Beckwood Press, Amino North America Corporation, Pacific Press Technologies, Enerpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Press Machine Market Strategic Shifts
Active energy recuperation and predictive maintenance algorithms are reshaping hydraulic power unit design priorities, while end-users demand shorter reconfiguration times between production runs.
Servo-electric pump drives are hybridizing with traditional hydraulic circuits to capture braking energy and reduce idle power consumption. Tier-1 automotive suppliers in Germany are adopting these systems for aluminum body panel forming. The technology is hybridizing machine architectures previously separated into distinct mechanical and hydraulic categories, compressing the addressable market for pure-play mechanical press vendors.
OSHA mechanical power press standards mandate two-hand trip controls and point-of-operation guarding that pre-2000 installed equipment cannot economically satisfy. Metal stamping shops across the US Midwest are retiring legacy machines rather than retrofitting. Small-batch fabricators in Ohio and Michigan are responding by consolidating purchasing power through equipment leasing cooperatives.
Just-in-time production requirements are compressing batch sizes and press changeover windows. Tier-2 automotive suppliers in China's eastern manufacturing belt are rejecting long-run mechanical press contracts in favor of CNC-integrated hydraulic systems with programmable stroke profiles. This pattern is most visible in battery enclosure stamping, where product mix changes every six to twelve weeks.
Hydraulic Press Machine Market Segmentation
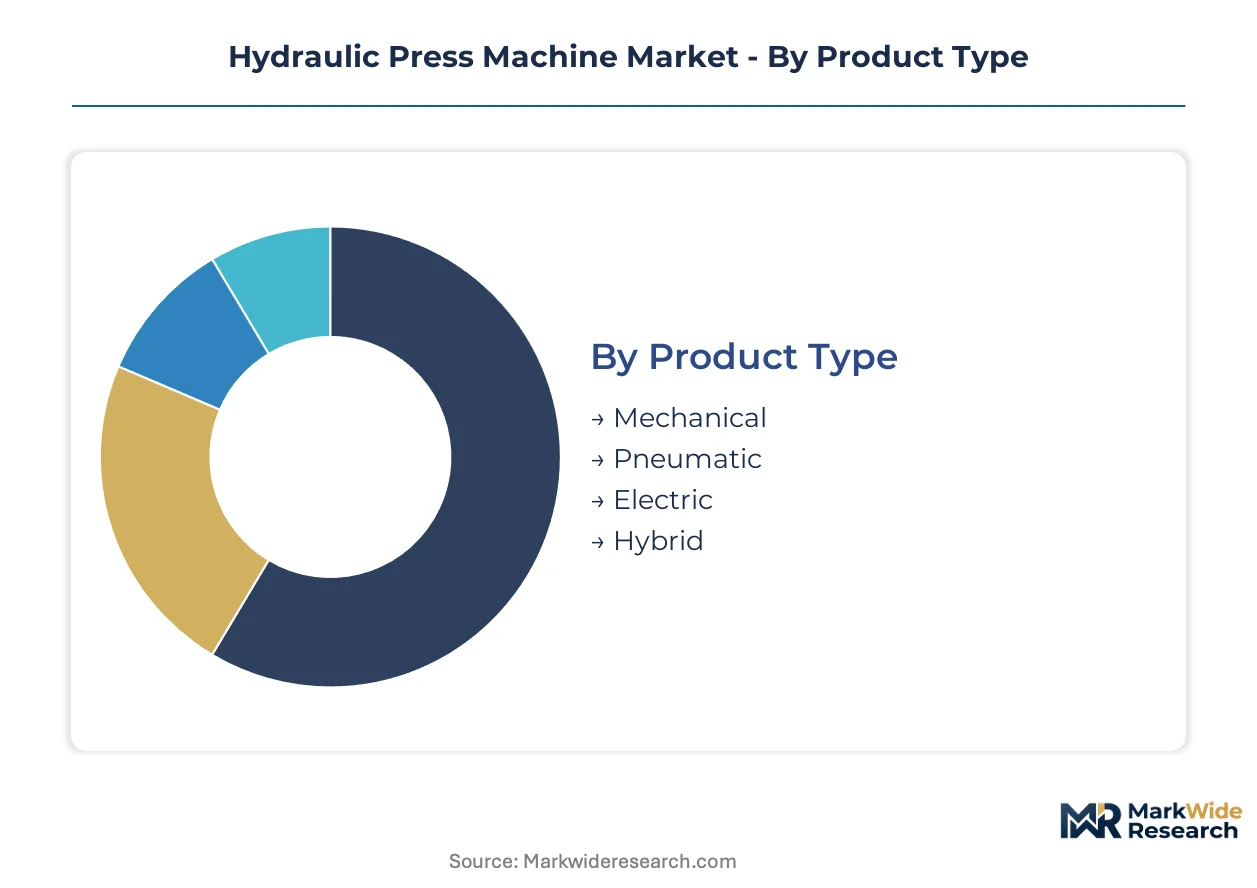
Segmentation reveals how hydraulic press architectures, deployment modes, and customer procurement patterns diverge across precision requirements and regulatory environments. Understanding these divisions exposes where hybrid servo-hydraulic systems displace legacy mechanical platforms and where capital deployment concentrates among automotive OEMs versus metalworking fabricators.
Product Type:
Cost tier determines capital outlay, energy efficiency, and control precision across forming operations.
- Mechanical:Flywheel-driven crank mechanisms deliver high-speed, repetitive strokes for thin-gauge stamping at lower capital cost. German automotive OEMs retain mechanical lines for high-volume body panel runs where speed outweighs precision requirements.
- Hybrid:Servo-electric pump drives married to hydraulic circuits capture regenerative braking energy while maintaining force control. Tier-1 suppliers in Japan and Germany deploy hybrid systems for aluminum-intensive EV chassis forming where energy accounting under EU Green Deal rules shapes procurement decisions.
- Pneumatic:Compressed air systems serve light-tonnage assembly and pressing below 100 tons in cost-sensitive fabrication shops.
- Electric:Direct servo-mechanical drives eliminate hydraulic fluid entirely for cleanroom-compatible precision forming in medical device manufacturing.
Mechanical presses command the established installed base across high-volume stamping operations. The steepest expansion trajectory runs through hybrid architectures as energy recuperation and programmable stroke profiles reshape automotive sourcing specifications.
Application:
End-use sector dictates tonnage requirements, stroke precision, and integration with downstream automation.
- Automotive:Body-in-white stamping, battery tray forming, and structural component production demand 800-10,000 ton servo-hydraulic systems with closed-loop force control. OEMs in Germany and Japan are converting stamping lines to handle aluminum-intensive EV platforms requiring higher tonnage precision than legacy steel stamping.
- Metalworking:Small-batch fabricators in China's Jiangsu and Zhejiang provinces adopt CNC-integrated hydraulic presses for just-in-time production runs with frequent die changes. OSHA mechanical power press compliance deadlines in the US Midwest are accelerating replacement cycles among job shops.
- Aerospace:Heated platen systems with precise dwell temperature control mold carbon fiber reinforced polymer structural components for commercial aircraft programs.
- Manufacturing:General industrial forming spans appliance housings, electrical enclosures, and consumer goods where cycle time and capital efficiency trade off against precision.
Automotive applications anchor capital deployment volumes. Metalworking is gaining share fastest as batch-size compression and regulatory compliance reshape equipment replacement economics.
Installation:
Deployment location and mobility determine foundation requirements, logistics complexity, and operational flexibility.
- Fixed:Permanent foundation-mounted presses dominate large-frame automotive stamping at 2,000+ tons where structural rigidity and vibration damping are non-negotiable. German OEMs install fixed systems in greenfield EV battery enclosure facilities.
- Mobile:Trailer-mounted or skid-based units serve on-site repair, field maintenance, and temporary production capacity in remote mining and energy infrastructure locations.
- On-site:Equipment assembled and commissioned at final location accommodates oversized frame components that exceed transport dimensional limits for complete machines.
- Off-site:Factory-integrated and tested systems arrive as complete units for rapid installation in established manufacturing facilities with adequate receiving infrastructure.
Fixed installations represent the dominant configuration for precision metal forming. Mobile systems are expanding most quickly in energy sector maintenance and infrastructure repair applications.
End User:
Customer type shapes procurement scale, specification complexity, and aftermarket service attachment rates.
- OEMs:Original equipment manufacturers specify large-frame servo-hydraulic systems with integrated automation, predictive maintenance modules, and documented CE marking compliance for EU production facilities. German automotive OEMs consolidate purchasing across multiple stamping plants to extract volume pricing and service commitments.
- Tier-1 Suppliers:Contract manufacturers serving OEM assembly lines require rapid reconfiguration capabilities and qualified supplier status under IATF 16949 quality systems. Suppliers in China's eastern manufacturing belt are replacing mechanical presses to qualify for EV battery enclosure contracts.
- Fabricators:Independent job shops prioritize equipment leasing flexibility and retrofit control upgrades over new machine purchases. Ohio and Michigan fabricators are consolidating purchasing power through equipment leasing cooperatives to address OSHA compliance deadlines.
- Aftermarket Providers:Service organizations and rebuild specialists capture revenue from control system retrofits, hydraulic component replacement, and safety system upgrades for pre-2000 installed equipment.
OEMs concentrate the highest-value procurement decisions. Tier-1 suppliers are climbing the fastest as EV supply chain localization and qualification requirements reshape vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frame-grade castings and forged platens concentrate manufacturing capacity in Germany, Japan, and China's eastern coastal provinces. Servo valve supply chains and precision component engineering anchor in Japanese and German industrial clusters. Regulatory compliance timelines in the United States and European Union are forcing replacement cycles that redistribute demand geographically.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are installing large-frame servo-hydraulic presses for aluminum-intensive EV chassis production. CE marking under the EU Machinery Directive mandates safety-rated control systems and documented risk assessments. The Stuttgart industrial corridor concentrates Schuler Group GmbH engineering capacity and tier-1 supplier qualification activity for battery enclosure stamping.
China
Domestic fabricators in Jiangsu and Zhejiang provinces are expanding mid-tonnage press capacity for electric vehicle battery tray production. GB standards administered by SAMR impose hydraulic system pressure testing and structural load certification on domestically sold equipment. The Yangtze River Delta manufacturing belt is replacing mechanical presses with servo-hydraulic and hybrid systems for precision metal forming.
United States
Metal stamping shops across Ohio and Michigan are retiring legacy machines rather than retrofitting to meet OSHA mechanical power press standards. Two-hand trip controls and point-of-operation guarding requirements compel capital replacement of pre-2000 installed equipment. Small-batch fabricators in the Midwest are consolidating purchasing power through equipment leasing cooperatives.
Japan
Tier-1 automotive suppliers are deploying hybrid electric-hydraulic systems for aluminum body panel forming under METI energy efficiency guidelines. Proportional hydraulic control components concentrate among Japanese precision component suppliers, creating input bottlenecks for mid-tier press builders. The Nagoya industrial region anchors servo valve engineering and closed-loop force control development.
India
Production-linked incentives under the PLI scheme for auto component manufacturing are attracting hydraulic press investments for domestic EV supply chain localization. The national automotive regulator is aligning with international safety standards for machinery certification. Gujarat and Maharashtra are emerging as fabrication hubs for tier-1 supplier qualification under IATF 16949 quality systems.
Hydraulic Press Machine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in valve and control architecture. The vendor base stratifies between large-frame automotive specialists, mid-tonnage custom builders, and precision component suppliers. Three archetypes dominate: German engineering-led system houses, Asian scale-driven fabricators, and North American niche custom specialists. Competitive moves concentrate on hybrid system development and CE marking certification acceleration.
Among German-based engineering houses, Schuler Group GmbH and Dorst Technologies GmbH & Co. KG exemplify the large-frame system integrator archetype, occupying positions defined by automotive OEM channel relationships and documented compliance capabilities. Beckwood Press represents the North American custom specialist tier, sitting within aerospace and composite forming niches that resist commoditization. Macrodyne Technologies anchors the Canadian platform integrator position, reflecting the geographic distribution of heavy-frame engineering capacity across North American industrial corridors.
| Leading Market Players |
|---|
| Macrodyne Technologies |
| Dorst Technologies GmbH & Co. KG |
| Schuler Group GmbH |
| Greenerd Press & Machine Co. |
| Gasbarre Products, Inc. |
| Beckwood Press |
| Amino North America Corporation |
| Pacific Press Technologies |
| Enerpac |
| Others |
Value Chain & Pricing Dynamics
Japanese and German precision component suppliers dominate servo valve production, anchoring margin capture upstream while mid-tier press builders face input bottlenecks that compress their pricing flexibility downstream. This concentration forces system integrators to absorb cost volatility or pass it through to automotive OEMs with long-term contract leverage.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates safety-certified large-frame systems from basic mechanical presses and retrofit control kits. Certification grade and volume scale drive price differentiation, with automotive OEM consolidated purchasing extracting steep discounts. Cost compression in mid-tonnage segments is intensifying because domestic Chinese fabricators are expanding capacity aggressively. Tier-1 automotive suppliers show least price sensitivity due to qualification requirements, while independent job shops in the US Midwest remain most sensitive and consolidate through leasing cooperatives.
Supply Chain Analysis
Export control regimes on precision hydraulic control technology limit flows from Japanese and German engineering clusters to mid-tier builders in emerging manufacturing hubs. Frame-grade castings and forged platens concentrate manufacturing capacity in Germany, Japan, and China's eastern coastal provinces. Nickel-chromium-molybdenum steel grades and proportional hydraulic control components constitute critical input dependencies. Single-source vulnerability runs through Japanese servo valve engineering concentrated in the Nagoya industrial region. Distribution runs through OEM direct procurement for large-frame systems and regional distributor networks for mid-tonnage fabricator sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue streams from control system retrofits and safety upgrades are expanding faster than hardware sales as OSHA compliance deadlines and CE marking requirements force replacement economics across installed bases predating 2000.
For Market Incumbents: Build certification moats around documented EU Machinery Directive compliance and IATF 16949 qualification status. Accelerate hybrid servo-hydraulic development to defend against mechanical press substitution in thin-gauge stamping. Deepen backward integration into servo valve supply relationships to mitigate input bottlenecks from Japanese precision component suppliers. For New Entrants and Emerging Players: Build out heated platen hydraulic system capabilities for aerospace composite forming where Beckwood Press occupies a defensible niche resistant to Asian import commoditization. Target India's PLI scheme auto component manufacturing incentives for domestic EV supply chain localization. Pursue digital servo drive retrofit partnerships with US Midwest equipment leasing cooperatives as a channel entry strategy. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid system development programs requiring servo-electric pump drive engineering and closed-loop force control talent acquisition. Long-term viability favors platform integrators with automotive OEM channel relationships over pure component suppliers. Monitor CE marking certification timeline extensions as an inflection indicator for product launch velocity constraints affecting mid-size manufacturer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Hydraulic Hybrid Development | Captures regenerative braking energy for EU Green Deal compliance in German automotive stamping. |
| CE Marking Certification Acceleration | Compresses four-to-eight month notified body assessment cycles threatening product launch timelines. |
| Retrofit Control System Upgrades | Creates aftermarket revenue from pre-2000 installed bases facing OSHA compliance deadlines. |
| India PLI Scheme Localization | Qualifies tier-1 supplier status under IATF 16949 for domestic EV battery enclosure contracts. |
| Aerospace Heated Platen Specialization | Serves carbon fiber reinforced polymer molding with precise dwell temperature control requirements. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at automotive OEM stamping plants, plant engineers at tier-1 metal fabricators, aftermarket service heads at hydraulic press distributors, and procurement teams at aerospace composite formers. Secondary validation drew from SEC 10-K filings of listed industrial equipment manufacturers, customs and trade data on frame-grade casting imports, SAMR GB standards documentation, and OSHA mechanical power press enforcement records. Bottom-up unit economics triangulated against top-down sector spending estimates.
Calibration anchored installed base retirement schedules to regulatory compliance deadlines and OEM EV platform conversion timelines. Segmentation dimensions modeled include press architecture type, end-use application, installation configuration, and customer procurement archetype. CAGRs were derived from slope analysis of replacement cycle acceleration and greenfield capacity announcements. Energy efficiency accounting under EU Green Deal rules and METI guidelines shaped hybrid system adoption curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic fabricators expanding mid-tonnage capacity or Japanese precision component suppliers restricting servo valve export flows would shift outcomes. Material shifts in EU Machinery Directive enforcement intensity or OSHA penalty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Tray Dryers Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Smart Crane Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Truck Crane Market
Construction Equipment
Used Backhoe Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market