
 Mixed-Mode Chromatography Resin Market | 2026-2036
Mixed-Mode Chromatography Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed-Mode Chromatography Resin Market Intelligence
The gap between premium multimodal ligand platforms and commodity ion exchange offerings is recalibrating procurement strategies across downstream bioprocessing. Bio-Rad Laboratories leverages its long-standing chromatography portfolio to anchor positions in high-throughput screening workflows. Sartorius Stedim Biotech differentiates through integrated single-use systems that embed mixed-mode resins within closed processing architectures. Merck KGaA dominates the supply of pharmaceutical-grade raw materials that feed into resin synthesis, extending control over upstream quality specifications.
Mixed-mode chromatography resin combines multiple separation mechanisms—typically ionic and hydrophobic interactions—within a single beaded matrix, enabling selective capture of proteins under intermediate salt conditions that would fail pure-mode chemistries. These resins serve primarily to reduce downstream purification steps in biologics manufacturing, cutting buffer consumption and column footprint by consolidating capture and intermediate polishing. Ion exchange resins retain the largest installed base due to decades of process validation, yet hydrophobic interaction resins represent the fastest-expanding category as antibody-drug conjugates and bispecifics drive demand for orthogonal selectivity. Among end users, contract manufacturing organizations are deepening resin inventories to service diversified client pipelines, while biopharmaceutical companies concentrate procurement around qualified multimodal platforms to secure regulatory filing continuity.
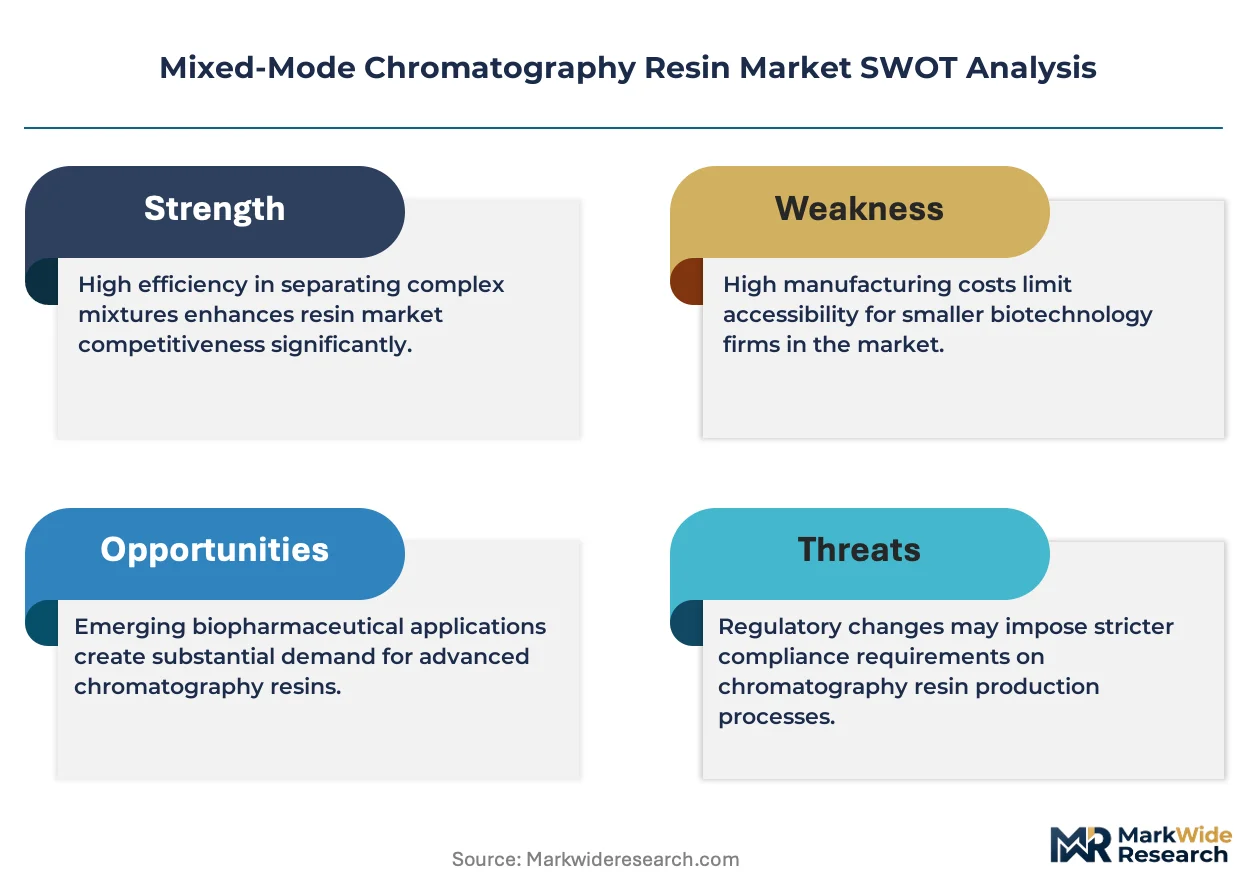
FDA process validation guidance and EMA's ICH Q5A-Q5D standards enforce demonstrable host cell protein clearance, directly elevating mixed-mode resin specifications for commercial biologics. The EU MDR and ISO 13485 traceability requirements further tighten documentation burdens on resin suppliers seeking device or diagnostic adjacency. Stakeholders must monitor how evolving pharmacopeial monographs for chromatographic media reshape qualification protocols before committing to multi-year resin supply agreements.
Market Dynamics
Downstream bioprocessing consolidation is compressing purification train length, forcing resin suppliers to demonstrate step-reduction value under tightening FDA process analytical technology mandates.
Growth Catalysts
- Monoclonal antibody pipeline expansion:Bispecific and antibody-drug conjugate programs in the United States, Germany, and China require orthogonal selectivity that pure-mode chemistries cannot deliver.
- EMA ICH Q5A-Q5D enforcement:Demonstrable host cell protein clearance standards elevate mixed-mode resin specifications for commercial biologics filings.
- Continuous processing adoption:Integrated single-use architectures favor resins operating across broader conductivity windows without intermediate diafiltration.
Market Restraints
- Pharmaceutical-grade agarose supply concentration:Swedish and Japanese suppliers control high-purity bead raw material, exposing purchasers to allocation risk during demand surges.
- Process validation lock-in:Biopharmaceutical companies face regulatory filing discontinuity costs when switching qualified multimodal platforms.
- Protein A affinity substitution:Next-generation synthetic ligands for mAb capture threaten mixed-mode positioning in first-generation antibody processes.
Strategic Opportunities
- Gene therapy vector purification:Adeno-associated virus and lentiviral manufacturing in the United States lacks standardized downstream platforms, creating resin qualification whitespace.
- China NMPA biosimilar pathway:Accelerated approval timelines for trastuzumab and adalimumab copies drive demand for resin platforms with established regulatory dossiers.
- Continuous chromatography integration:Simulated moving bed and periodic counter-current systems require resins with enhanced chemical stability at elevated linear velocities.
Industry Challenges
- Resin lifetime validation under continuous operation:Demonstrating consistent performance across hundreds of cycles demands extended stability data packages that delay commercial deployment.
- Extractables documentation for single-use compatibility:Film and tubing interactions with high-salt elution buffers complicate regulatory submissions for closed-system processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed-Mode Chromatography Resin Market |
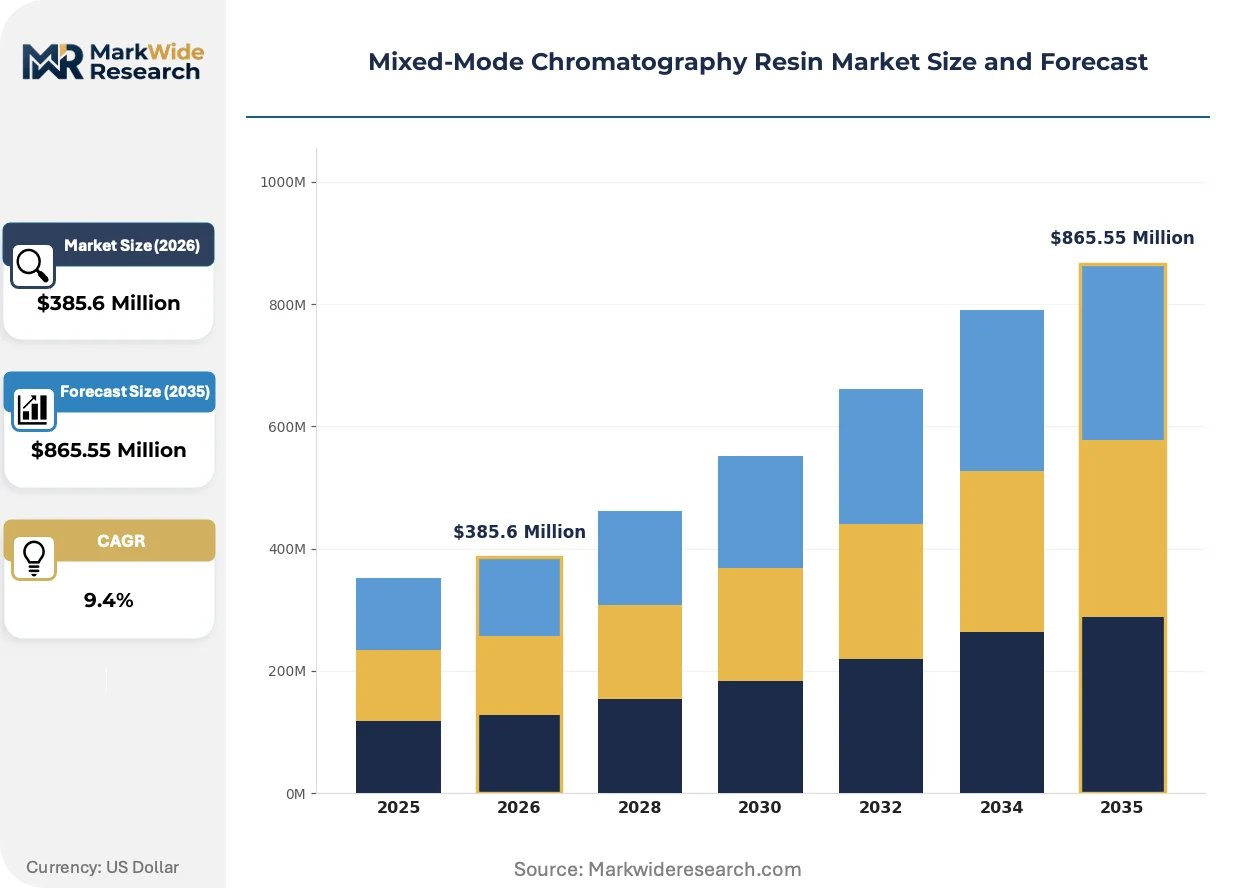
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Affinity Resins, Ion Exchange Resins, Hydrophobic Interaction Resins, Others End User: Biopharmaceutical Companies, Academic Research, Contract Manufacturing Organizations, Industrial Biotechnology Application: Protein Purification, Vaccine Development, Monoclonal Antibody Production, Enzyme Isolation Packaging Type: Vials, Bottles, Bags, Drums |
| Companies Covered | Bio-Rad Laboratories, Sartorius Stedim Biotech, Merck KGaA, Avantor, Repligen Corporation, Cytiva, Tosoh Corporation, Purolite, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed-Mode Chromatography Resin Market Strategic Shifts & Innovations
Multimodal ligand engineering and process intensification are converging to redefine resin performance benchmarks, compressing the gap between capture and polishing functionality.
Multimodal cation exchange resins is modularizing purification workflows by combining hydrophobic and electrostatic retention in a single bead architecture. Contract manufacturing organizations in Massachusetts and North Carolina are adopting these platforms to service diversified client pipelines without process revalidation for each molecule. This convergence is modularizing the traditional three-column mAb train into two-step configurations, reducing facility footprint and buffer hold tank requirements.
EU MDR traceability mandates and ISO 13485 documentation burdens are reshaping supplier qualification protocols. Resin manufacturers must now provide device-history records and change-control notifications that extend through distribution partners. European diagnostic and device-adjacent bioprocessing facilities are responding by consolidating procurement around suppliers with pre-established quality management system certifications.
Buyer concentration around qualified platforms is shortening switching cycles for new molecular formats. Biopharmaceutical companies in California and Basel are demanding resin performance guarantees tied to specific impurity clearance targets rather than generic binding capacity metrics. This specification tightening is most visible in bispecific antibody programs, where heterogeneity profiles require customized multimodal selectivity that off-the-shelf chemistries cannot address.
Mixed-Mode Chromatography Resin Market Segmentation
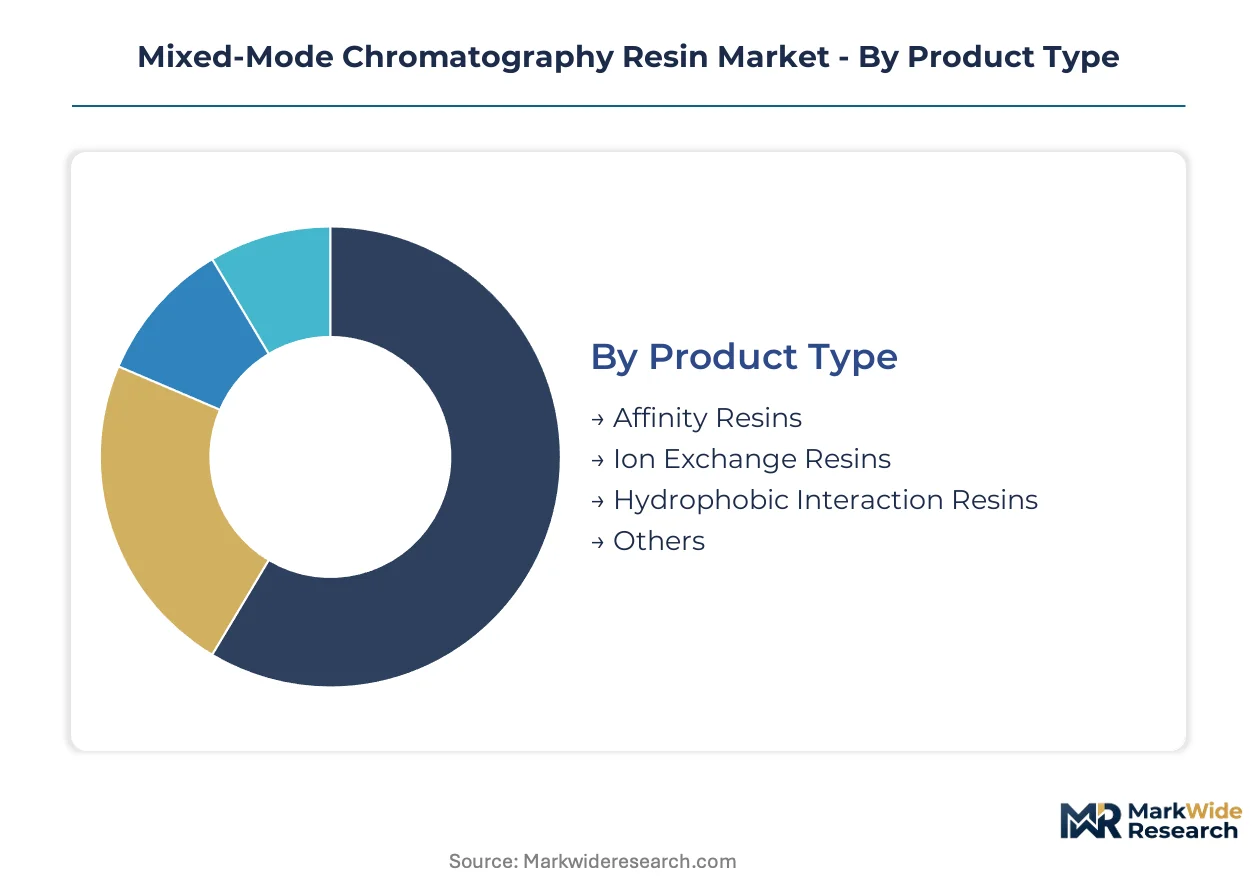
Segmentation in mixed-mode chromatography resin markets reveals how purification workflows diverge across molecule classes and manufacturing scales. Procurement patterns vary sharply between mass-market antibody platforms and emerging gene therapy vectors, reshaping supplier R&D priorities.
Product Type:
Cost tier differentiation separates validated pharmaceutical-grade platforms from exploratory research chemistries.
- Affinity Resins:Protein A and synthetic ligand matrices deliver high-selectivity capture for monoclonal antibodies under low-pH elution conditions. FDA process validation guidance enforces extensive leachables documentation, locking biopharmaceutical companies into multi-year supply agreements with qualified suppliers.
- Ion Exchange Resins:Cation and anion exchange matrices remain the workhorse technology for intermediate polishing steps, operating across broad pH windows with established scale-up protocols. Demand concentrates in Germany and the United States where legacy mAb facilities maintain validated two-column trains.
- Hydrophobic Interaction Resins:Salt-promoted binding enables orthogonal selectivity for antibody-drug conjugates and bispecifics with complex heterogeneity profiles. Contract manufacturing organizations in Massachusetts are deepening inventories to service diversified client pipelines without process revalidation.
- Others:Size exclusion and mixed-mode specialty chemistries address niche applications in viral vector purification.
Ion exchange resins lead volumes today; hydrophobic interaction resins are gaining share fastest.
End User:
Volume scale separates multi-ton biologics manufacturers from gram-scale research operations.
- Biopharmaceutical Companies:Internal manufacturing groups at firms like those in Basel and California concentrate procurement around qualified multimodal platforms to secure regulatory filing continuity across bispecific and ADC programs. EMA ICH Q5A-Q5D standards enforce demonstrable host cell protein clearance, elevating resin specifications for commercial filings.
- Contract Manufacturing Organizations:CDMOs in North Carolina and Massachusetts maintain deep resin inventories to service diversified client pipelines without facility reconfiguration. Continuous processing adoption favors resins operating across broader conductivity windows without intermediate diafiltration.
- Academic Research:University labs prioritize cost efficiency and catalog availability over validation packages.
- Industrial Biotechnology:Enzyme and biofuel producers seek high-capacity platforms for commodity protein recovery.
Biopharmaceutical companies dominate current procurement; contract manufacturing organizations are expanding resin footprints most aggressively.
Application:
Maturity curves separate established antibody workflows from emerging therapeutic modalities.
- Monoclonal Antibody Production:Standardized downstream platforms for IgG1 and IgG4 subclasses have driven decades of process validation, creating high switching costs for incumbent resin chemistries. China NMPA biosimilar pathway acceleration for trastuzumab and adalimumab copies reinforces demand for platforms with established regulatory dossiers.
- Protein Purification:Recombinant protein manufacturing spans therapeutic enzymes to research-grade reagents, with resin selection driven by yield targets and impurity profiles rather than regulatory precedent.
- Vaccine Development:Subunit and conjugate vaccine antigens require resin platforms capable of handling diverse glycosylation patterns and aggregation-prone conformations.
- Enzyme Isolation:Industrial biocatalysis applications prioritize binding capacity and chemical stability over pharmacopeial compliance.
Monoclonal antibody production anchors current demand; vaccine development applications are climbing the fastest as mRNA and viral vector platforms mature.
Packaging Type:
Supply concentration dictates format availability and lead time reliability.
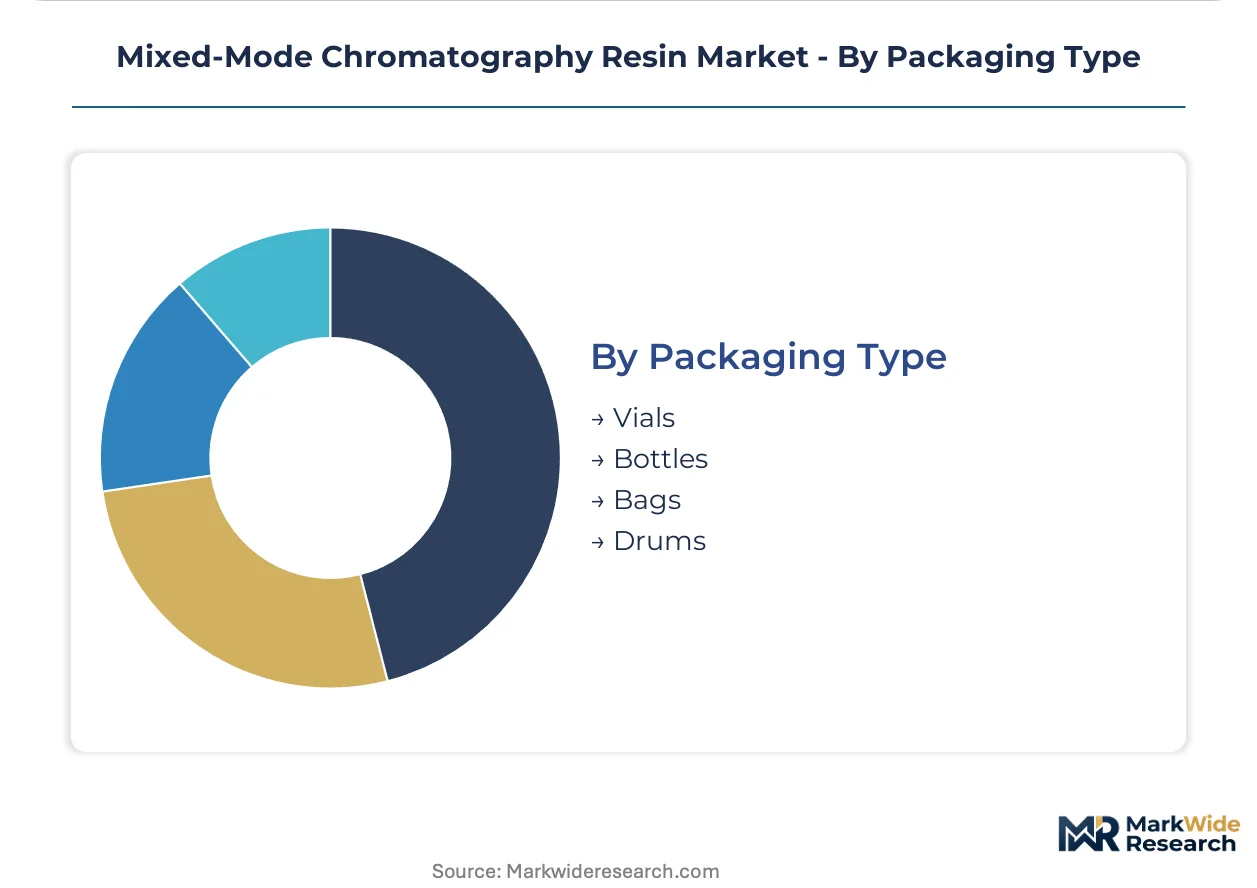
- Drums:Bulk powder and slurry formats serve multi-ton manufacturing campaigns with established logistics infrastructure. Swedish and Japanese suppliers control high-purity agarose bead raw material, exposing drum purchasers to allocation risk during demand surges.
- Bags:Single-use flexible containment aligns with closed-system processing architectures favored by Sartorius Stedim Biotech integrated platforms. Extractables documentation for film and tubing interactions with high-salt elution buffers complicates regulatory submissions.
- Bottles:Mid-scale containers address pilot plant and technology transfer quantities.
- Vials:Small-volume formats support analytical method development and quality control reference standard preparation.
Drums lead procurement volumes today; bags are expanding most quickly alongside single-use system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocessing talent clusters in Basel, Boston, and Shanghai anchor resin demand across three continents. FDA, EMA, and NMPA guidelines on host cell protein clearance reshape procurement priorities in each jurisdiction. Manufacturing scale and regulatory stringency diverge sharply between established antibody hubs and emerging viral vector centers.
United States
Massachusetts and North Carolina contract manufacturing organizations deepen mixed-mode resin inventories to service bispecific antibody pipelines. FDA process analytical technology mandates enforce demonstrable impurity clearance, elevating specifications for commercial biologics filings. Greater Boston biotech clusters drive continuous processing adoption, favoring resins operating across broader conductivity windows.
Germany
Baden-Württemberg and Bavaria host legacy monoclonal antibody facilities maintaining validated two-column purification trains. EMA ICH Q5A-Q5D standards tighten host cell protein documentation burdens, locking manufacturers into qualified multimodal platforms. Basel-adjacent Rhine-Neckar pharmaceutical corridors concentrate procurement around suppliers with pre-established quality management certifications.
China
NMPA accelerated biosimilar pathways for trastuzumab and adalimumab copies drive demand for resin platforms with established regulatory dossiers. Yangtze River Delta biologics manufacturing clusters expand downstream capacity to capture export opportunities. Shanghai and Suzhou facilities prioritize resin qualification whitespace for gene therapy vector purification.
Japan
PMDA enforcement of pharmacopeial monographs for chromatographic media reshapes supplier qualification protocols. Tokyo-Osaka pharmaceutical corridors concentrate demand for high-purity agarose bead raw materials. Japanese suppliers control critical pharmaceutical-grade bead feedstock, exposing regional purchasers to allocation risk during demand surges.
Switzerland
Swissmedic guidelines on process validation continuity secure multi-year resin supply agreements for Basel-headquartered biopharmaceutical companies. Lake Geneva bioprocessing clusters specialize in antibody-drug conjugate manufacturing requiring orthogonal selectivity. Swiss facilities lead adoption of integrated single-use architectures embedding mixed-mode resins within closed processing systems.
Mixed-Mode Chromatography Resin Market Key Industry Players
Capital-heavy resin producers compete with asset-light platform designers across the mixed-mode chromatography value chain. The supplier base consolidates around three tiers: integrated life science conglomerates with captive raw material supply, specialized chromatography houses with deep process validation expertise, and regional bead manufacturers serving cost-sensitive research markets. Dominant competitive moves include backward integration into pharmaceutical-grade agarose production and strategic partnerships to secure continuous bioprocessing qualification data.
Among diversified life science conglomerates, Bio-Rad Laboratories and Merck KGaA occupy positions anchoring high-throughput screening workflows and upstream raw material control respectively. Sartorius Stedim Biotech exemplifies the integrated systems archetype, embedding resin technologies within closed single-use architectures. These three entities represent distinct strategic postures: portfolio breadth, supply chain verticality, and system integration.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Sartorius Stedim Biotech |
| Merck KGaA |
| Avantor |
| Repligen Corporation |
| Cytiva |
| Tosoh Corporation |
| Purolite |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Continuous bioprocessing adoption simultaneously compresses resin cost economics and concentrates supply power among pharmaceutical-grade agarose bead manufacturers. FDA process analytical technology mandates elevate qualification requirements, locking buyers into multi-year contracts with qualified suppliers while Swedish and Japanese feedstock controllers extract premium positioning.
Pricing Analysis
Unbundled resin supply competes against integrated single-use system packages from Sartorius Stedim Biotech and Cytiva. Three-tier pricing structure across GMP-validated, pilot-grade, and research-use-only levels separates biopharmaceutical procurement from academic purchasing. Cost compression in pilot-grade tiers intensifies as Chinese manufacturers expand agarose bead capacity. Contract manufacturing organizations exhibit highest price sensitivity due to client pass-through pressures, while Basel-headquartered innovators accept premium positioning for regulatory filing security.
Supply Chain Analysis
Freight costs for temperature-controlled resin slurry shipments from Sweden and Japan amplify landed cost differentials for North American bioprocessors. High-purity agarose bead production concentrates in Sweden, Japan, and coastal China provinces. Raw material dependencies include pharmaceutical-grade agarose, epichlorohydrin crosslinkers, and multimodal ligand chemistries. Single-source vulnerability in Swedish bead feedstock exposes purchasers to allocation risk during monoclonal antibody demand surges. Distribution runs through authorized distributors with validated cold-chain capabilities to GMP facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in gene therapy vector applications where standardized downstream platforms remain undeveloped, justifying premium capture through qualification partnership models.
For Market Incumbents: Acquire pharmaceutical-grade agarose bead manufacturing assets to secure upstream supply control against Japanese and Swedish feedstock concentration. Bio-Rad Laboratories and Merck KGaA should deepen backward integration into ligand synthesis to defend against synthetic Protein A ligand substitution threats. EMA ICH Q5A-Q5D documentation burdens create switching-cost moats that incumbents can reinforce through pre-validated platform packages. For New Entrants and Emerging Players: Novel multimodal ligand chemistries targeting bispecific antibody heterogeneity profiles offer entry pathways where off-the-shelf resins fail. China NMPA biosimilar acceleration creates whitespace for resin platforms with established regulatory dossiers. Massachusetts and North Carolina contract manufacturing organizations represent the most penetrable customer segment due to diversified pipeline servicing needs. A qualification-data partnership model with emerging gene therapy vector manufacturers bypasses incumbent lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized chromatography houses with deep process validation expertise but limited raw material verticality. Long-term viability hinges on continuous bioprocessing qualification data packages that secure multi-year supply agreements. Acquisition target archetype: mid-cap resin specialists with FDA master file submissions and ISO 13485 certifications. The signal to watch is NMPA biosimilar approval volume as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agarose Bead Production | Captive supply of pharmaceutical-grade feedstock reduces allocation risk from Swedish and Japanese controllers. |
| Gene Therapy Vector Qualification Partnership | Adeno-associated virus manufacturing in Massachusetts lacks standardized platforms, creating first-mover resin positioning. |
| Continuous Chromatography Stability Investment | Simulated moving bed systems require enhanced chemical stability at elevated linear velocities for multi-cycle validation. |
| China NMPA Regulatory Dossier Expansion | Established filings for trastuzumab and adalimumab biosimilar pathways accelerate procurement decisions by Yangtze River Delta facilities. |
| Single-Use Extractables Documentation Program | Film and tubing interaction data with high-salt elution buffers secures closed-system regulatory submissions for Sartorius-integrated platforms. |
Research Approach
Bottom-up biopharmaceutical manufacturing modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with downstream process development scientists, regulatory affairs directors at CDMOs, GMP facility procurement managers, and chromatography R&D heads combined with secondary validation from FDA 483 inspection observations, EMA CHMP assessment reports, USITC trade data, and pharmaceutical company SEC 10-K supply chain disclosures. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices linking monoclonal antibody pipeline counts, gene therapy clinical trial advancement, and biosimilar approval trajectories to resin consumption coefficients drive projection mechanics across the modeling period. Segmentation dimensions include product type, end-user scale tier, application maturity curve, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical validation timelines and process intensification adoption rates. Forecast inputs incorporate continuous bioprocessing penetration assumptions and NMPA biosimilar pathway acceleration parameters.
The model holds under stable FDA and EMA regulatory frameworks; deviation in pharmacopeial monograph revisions or single-use material restrictions would shift resin qualification timelines and demand trajectories. Forecasts reflect documented assumptions regarding host cell protein clearance standards and agarose bead supply concentration. A model refresh is warranted upon material change in China NMPA biosimilar approval velocity or Swedish pharmaceutical-grade agarose export licensing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
PEKK Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
Water-Borne Epoxy Resins Market