
 Liquid Saturated Polyester Resin Market | 2026-2036
Liquid Saturated Polyester Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Saturated Polyester Resin Market Intelligence
Specialty chemical distribution channels serving mid-sized coating formulators is reshaping how liquid saturated polyester resin reaches fragmented end-users across Asia-Pacific and Europe. DSM leverages its backward integration into dicarboxylic acid feedstocks to secure margin stability in saturated resin grades. Allnex GmbH anchors its competitive position through dedicated powder coating resin technology centers in Germany and China. Mitsubishi Chemical Group Corporation dominates supply to Japanese automotive OEM clearcoat programs through just-in-time delivery contracts.
Liquid saturated polyester resin comprises linear polycondensation products of dicarboxylic acids—typically terephthalic acid or isophthalic acid—with diols such as neopentyl glycol, yielding molecular weights between 2,000 and 10,000 Daltons and hydroxyl numbers of 30–60 mg KOH/g for thermosetting crosslink applications. Manufacturers produce these resins through melt polycondensation at 220–260°C under inert atmosphere, followed by solvent thinning or direct extrusion into solid flake for powder coating binders. Coatings applications command the largest value share due to architectural and industrial maintenance demand, while adhesives segments are gaining traction in flexible packaging lamination where saturated polyester chemistry outperforms polyurethane alternatives on heat resistance. Automotive end users sustain premium pricing for low-VOC, high-durability formulations that meet OEM specification sheets, whereas construction sector procurement favors bulk delivery modes to minimize per-kilogram logistics overhead on large infrastructure projects.
EPA VOC regulations under 40 CFR Part 59 restrict solvent-borne coating formulations in architectural and industrial maintenance categories, redirecting formulation investment toward high-solids and powder coating resin platforms. REACH registration requirements and ECHA substance evaluation protocols impose compliance costs on imported resin entering European downstream coating supply chains. ECHA RoHS restrictions on heavy metal catalyst residues further constrain manufacturing process design for polyester polycondensation. Stakeholders must monitor regulatory divergence between California Air Resources Board standards and federal EPA thresholds, as this gap determines whether regional formulation platforms or unified product architectures prove more cost-effective across North American coating customer bases.
Market Dynamics
REACH registration costs and EPA 40 CFR Part 59 VOC limits are forcing coating formulators to consolidate supplier relationships around resin producers with certified low-emission curing platforms, compressing the viable vendor base for liquid saturated polyester resin procurement.
Growth Catalysts
- Automotive OEM powder coating specifications:Clearcoat programs in passenger vehicle manufacturing specify saturated polyester binders for chip resistance and gloss retention, pulling volume through just-in-time supply contracts.
- China coastal manufacturing clusters:Appliance and automotive export production around Shanghai and Ningbo generates concentrated demand for high-solid resin formulations with shortened logistics loops.
- ECHA RoHS catalyst restrictions:Heavy metal residue limits on tin-based polycondensation catalysts favor producers with alternative titanium or zirconium process chemistry, rewarding early compliance investment.
Market Restraints
- Feedstock concentration:Terephthalic acid and isophthalic acid supply concentrates among Asian petrochemical complexes, exposing resin producers to upstream margin capture and freight cost volatility.
- High-solid formulation technical ceiling:Viscosity constraints at hydroxyl numbers below 40 mg KOH/g limit spray application window for industrial maintenance coatings, capping penetration in certain end-uses.
- REACH registration cost barrier:ECHA substance evaluation protocols impose five-figure euro compliance burdens on imported resin entering European downstream supply chains, filtering smaller exporters.
Strategic Opportunities
- Flexible packaging lamination adhesives:Saturated polyester chemistry outperforms polyurethane alternatives on heat seal strength and retort resistance, opening volume in food-contact film applications.
- India industrial coating formalization:BIS certification requirements and organized sector expansion in automotive component manufacturing create demand for specification-grade resin with documented batch consistency.
- UV-curable polyester oligomer convergence:Hybrid formulations combining saturated polyester backbone with acrylate termination address furniture and flooring segments seeking instant cure with polyester durability.
Industry Challenges
- Polycondensation process control expertise:Melt-phase molecular weight targeting at 220–260°C demands experienced reaction engineers, constraining capacity expansion at facilities without legacy polyester production heritage.
- Multi-jurisdiction certification timelines:Simultaneous EPA VOC compliance, REACH registration, and China GB standard alignment extend product launch cycles by 18–24 months for new resin grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Saturated Polyester Resin Market |
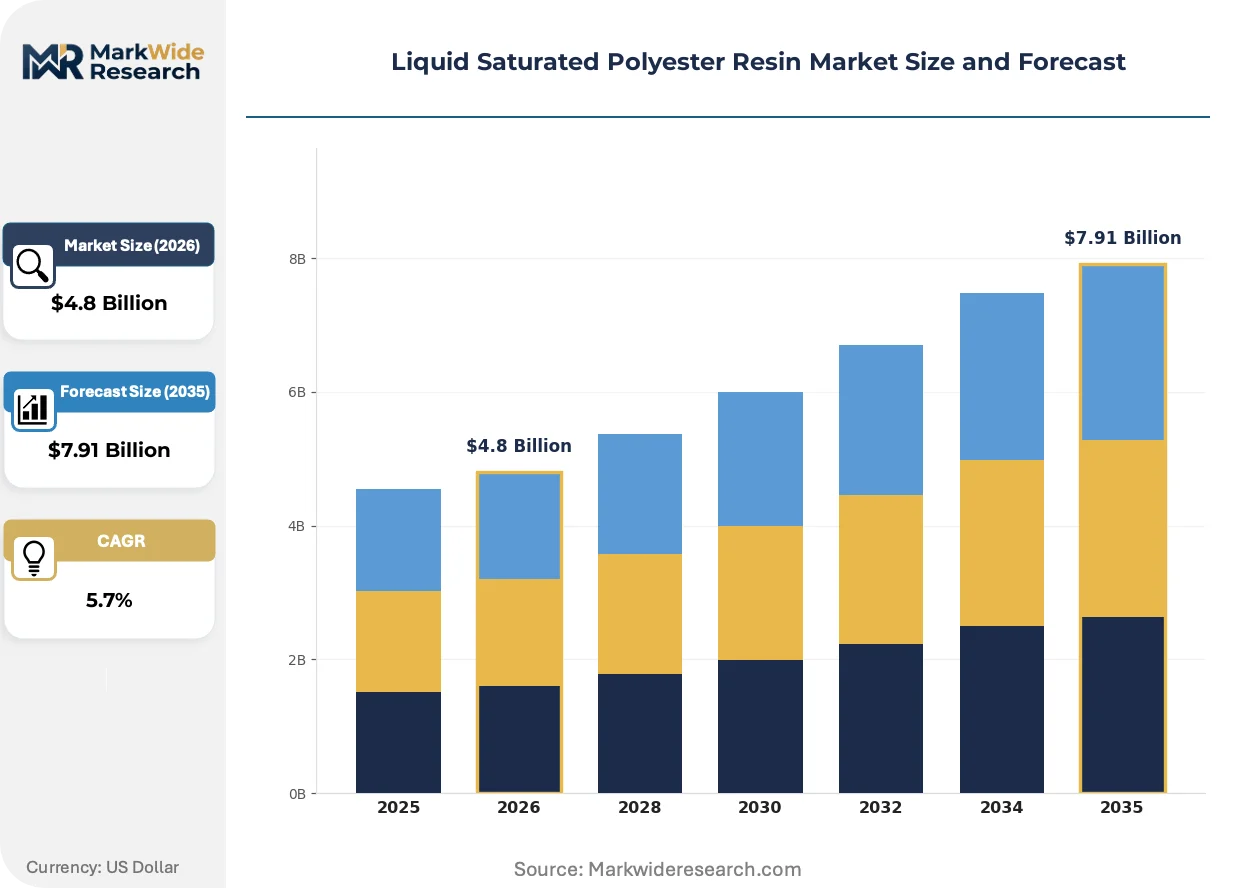
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsaturated, Saturated, Modified, Reinforced Application: Coatings, Adhesives, Composites, Sealants End User: Automotive, Aerospace, Construction, Electronics Delivery Mode: Pre-Packaged, Bulk, Custom Blends, In-Plant |
| Companies Covered | DSM, Hexion, Allnex GmbH, Polynt S.p.A, Mitsubishi Chemical Group Corporation, Arkema, Evonik Industries AG, BASF SE, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Saturated Polyester Resin Market Strategic Shifts & Innovations
Formulation chemistry and curing platform selection are diverging sharply between regional regulatory environments, with resin producers maintaining parallel product architectures rather than unified global grades.
Hybrid polyester-epoxy powder coating binders are migrating from automotive underhood applications into agricultural equipment and construction machinery finishes. Tier-two OEMs in Brazil and Thailand adopt these systems to meet import-market corrosion specifications without investing in separate primer-topcoat lines. The technology is migrating from niche specification toward default selection for export-oriented manufacturing.
EPA 40 CFR Part 59 architectural coating VOC limits are tightening solvent-borne formulation permissible content, redirecting R&D investment toward high-solid liquid polyester and 100% solid powder platforms. Industrial maintenance contractors in California face CARB thresholds below federal EPA minimums, forcing dual inventory strategies or lowest-common-denominator product selection. Formulators serving multi-state project portfolios bear compliance complexity costs that favor larger resin suppliers with regulatory affairs infrastructure.
Specialty chemical distributors serving mid-sized coating formulators are consolidating fragmented end-user access across Asia-Pacific and Southern Europe. These intermediaries aggregate technical service demand and buffer inventory risk, replacing direct mill relationships for formulators below thousand-ton annual offtake. The model concentrates most visibly in India, where state-level tax complexity and payment cycle fragmentation make distributor credit extension essential for market penetration.
Liquid Saturated Polyester Resin Market Segmentation
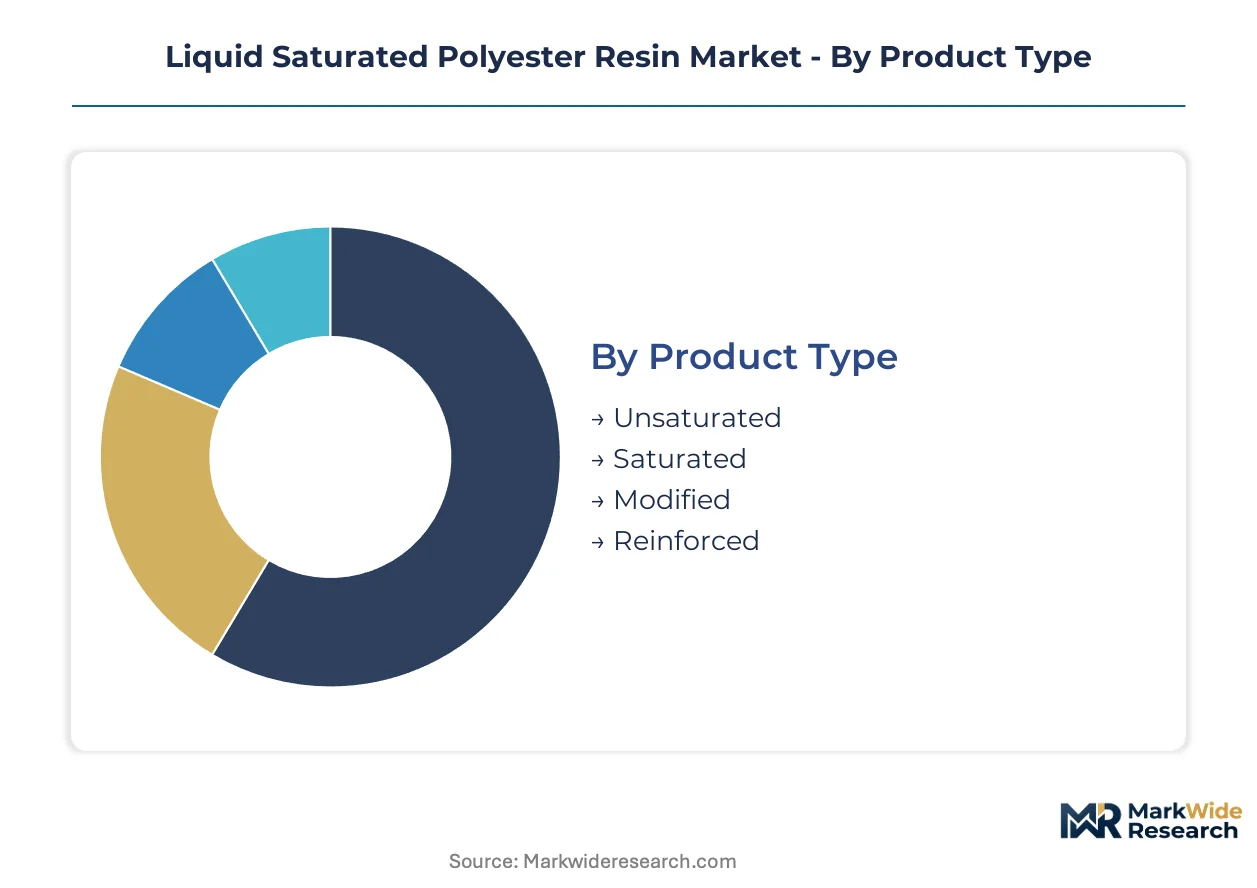
Segmentation in liquid saturated polyester resin markets reflects divergent technical specifications across curing platforms, regulatory compliance tiers, and logistics intensity. Formulators select resin grades based on hydroxyl number ranges, molecular weight distribution, and VOC content thresholds that vary sharply by end-use certification requirements.
Product Type:
Cost tier differentiation separates commodity-grade feedstocks from specification-driven modified systems with premium pricing structures.
- Saturated:Linear polycondensation products of terephthalic or isophthalic acid with neopentyl glycol, yielding hydroxyl numbers of 30–60 mg KOH/g for thermosetting crosslink applications. Powder coating binders in automotive OEM clearcoat programs in Japan and Germany concentrate demand for low-color, narrow-polydispersity grades with just-in-time delivery contracts.
- Unsaturated:Maleic anhydride-modified backbones with reactive vinyl functionality for peroxide-cured gel coats and sheet molding compounds. Marine and corrosion-resistant industrial applications in South Korea and Turkey sustain volume through fiberglass reinforced plastic fabrication clusters.
- Modified:Silicone or fluorine grafting for enhanced weatherability and chemical resistance specifications.
- Reinforced:Pre-dispersed mineral or glass fiber loading for structural composite matrices requiring elevated modulus.
Saturated resins command the established base. The steepest expansion runs through modified grades serving dual-cure and hybrid formulation platforms.
Application:
Application selection determines molecular architecture, with coatings demanding precise viscosity control and adhesives prioritizing heat seal strength retention.
- Coatings:Architectural and industrial maintenance categories dominate volume, with high-solid liquid formulations and 100% solid powder platforms diverging under EPA 40 CFR Part 59 VOC limits and ECHA REACH registration protocols. California CARB thresholds below federal minimums force dual inventory strategies for formulators serving multi-state project portfolios.
- Adhesives:Saturated polyester chemistry outperforms polyurethane alternatives on heat resistance and retort stability in flexible packaging lamination. Food-contact film applications in China and India generate concentrated demand for specification-grade resin with documented batch consistency and BIS certification alignment.
- Composites:Pultrusion and resin transfer molding of structural profiles for construction and transportation sectors.
- Sealants:Elastic recovery formulations for expansion joint and glazing applications in infrastructure projects.
Coatings applications anchor current procurement volumes. Adhesives segments are climbing the fastest as flexible packaging formalizes specification requirements across Asia-Pacific.
End User:
End-user procurement patterns stratify by certification intensity, with automotive and aerospace sustaining premium pricing for documented traceability.
- Automotive:Powder coating specifications for passenger vehicle clearcoats specify saturated polyester binders for chip resistance and gloss retention. Tier-one suppliers in Germany, Japan, and China pull volume through long-term supply contracts with penalty clauses for specification deviation.
- Construction:Bulk delivery modes minimize per-kilogram logistics overhead on large infrastructure projects. Procurement favors regional producers with drum and tanker fleet access rather than specification-grade certification.
- Aerospace:Flame retardancy and smoke toxicity specifications constrain qualified supplier bases to resin producers with AS9100 traceability systems.
- Electronics:Potting compounds and conformal coatings for printed circuit board protection in consumer and industrial equipment.
Construction absorbs the highest tonnage volumes. Aerospace specifications are gaining share fastest as supply chain qualification timelines extend and qualified vendor lists narrow.
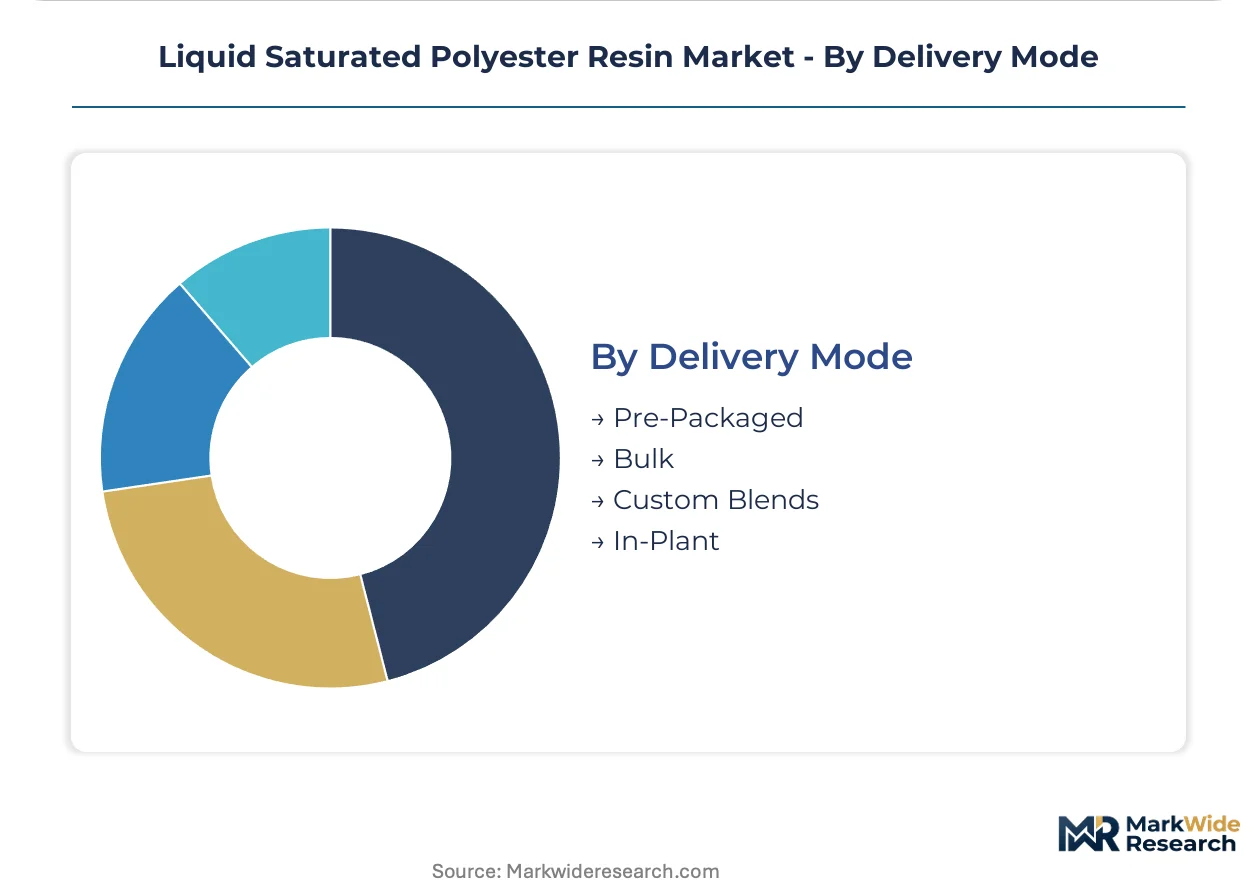
Delivery Mode:
Delivery configuration reflects customer scale and formulation sophistication, with integrated producers favoring direct tanker supply and mid-tier formulators dependent on distributor intermediation.
- Bulk:Tanker and railcar delivery to integrated coating manufacturing sites with in-house thinning and additive compounding capabilities. Coastal manufacturing clusters around Shanghai and Ningbo in China concentrate demand for high-solid resin formulations with shortened logistics loops and reduced working capital requirements.
- Pre-Packaged:Drum and intermediate bulk container formats for mid-sized formulators below thousand-ton annual offtake. Specialty chemical distributors in India and Southern Europe aggregate technical service demand and buffer inventory risk, replacing direct mill relationships where state-level tax complexity and payment cycle fragmentation make distributor credit extension essential.
- Custom Blends:Co-dispersed catalyst packages and tinting bases for just-in-time color matching operations.
- In-Plant:On-site resin manufacturing for captive consumption by multinational coating formulators with backward integration into polycondensation technology.
Bulk delivery commands the established base. Custom blend configurations are expanding most quickly as regional formulators seek to differentiate through rapid color matching and reduced inventory SKU counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese specification-grade supply chains while Chinese coastal producers compete on logistics efficiency and scale. This asymmetry shapes procurement decisions across automotive OEM clearcoat programs and industrial maintenance coatings.
China
Appliance and automotive export manufacturing around Shanghai and Ningbo drives concentrated demand for high-solid resin formulations with shortened logistics loops. MEE enforcement of dual carbon goals tightens emissions standards for polycondensation facilities. Coastal manufacturing clusters are scaling capacity to serve domestic appliance producers and automotive component exporters targeting European and North American OEM specification sheets.
Germany
Automotive OEM clearcoat specifications from BMW, Mercedes-Benz, and Volkswagen pull premium-grade saturated polyester through just-in-time supply contracts with penalty clauses for deviation. ECHA REACH registration protocols and RoHS catalyst restrictions filter smaller importers from downstream coating supply chains. The Rhine-Ruhr industrial corridor anchors powder coating resin technology centers serving specification-grade demand across the EU.
United States
Industrial maintenance contractors in California face CARB VOC thresholds below federal EPA 40 CFR Part 59 minimums, forcing dual inventory strategies for multi-state project portfolios. The Southeast automotive manufacturing belt generates specification-grade demand for chip-resistant clearcoat binders. Texas and Louisiana petrochemical complexes supply terephthalic acid feedstocks to domestic resin producers seeking margin stability against Asian import competition.
Japan
Passenger vehicle manufacturers specify saturated polyester binders for gloss retention and durability in premium clearcoat programs. METI industrial standards and JIS certification requirements constrain qualified supplier bases to producers with documented batch consistency. The Nagoya-Toyota industrial corridor concentrates just-in-time delivery contracts linking resin producers to automotive OEM assembly plants.
India
BIS certification requirements and organized sector expansion in automotive component manufacturing create demand for specification-grade resin with documented traceability. State-level tax complexity and payment cycle fragmentation make distributor credit extension essential for market penetration. The Gujarat and Maharashtra industrial corridors concentrate flexible packaging lamination adhesive demand from food-contact film producers serving domestic and export markets.
Liquid Saturated Polyester Resin Market Key Industry Players
Backward-integrated petrochemical majors and specialty resin specialists split the market along specification-grade versus commodity-volume fault lines. Concentration is moderate, with the top tier capturing automotive OEM certification relationships while mid-tier producers serve industrial maintenance and construction procurement. Three archetypes dominate: European chemical conglomerates with REACH-compliant product architectures, Asian producers leveraging coastal logistics clusters, and Japanese suppliers with just-in-time delivery infrastructure. Competitive moves center on alternative catalyst chemistry for RoHS compliance and dedicated powder coating technology centers in high-growth manufacturing regions.
Among European chemical conglomerates, DSM and Allnex GmbH exemplify the backward-integrated archetype securing feedstock margin stability. DSM leverages its position in dicarboxylic acid production, while Allnex anchors competitive positioning through technology centers in Germany and China. Mitsubishi Chemical Group Corporation occupies the Japanese just-in-time specialist tier, representing supply chain proximity advantages for automotive OEM clearcoat programs. These three entities illustrate how geographic specialization and regulatory compliance infrastructure determine vendor selection in specification-grade segments.
| Leading Market Players |
|---|
| DSM |
| Hexion |
| Allnex GmbH |
| Polynt S.p.A |
| Mitsubishi Chemical Group Corporation |
| Arkema |
| Evonik Industries AG |
| BASF SE |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
The Shanghai-Ningbo coastal freight corridor anchors cost dynamics for liquid saturated polyester resin, with container rates from Asian petrochemical hubs feeding into both supply concentration among dicarboxylic acid producers and downstream price differentiation between specification-grade automotive clearcoat binders and commodity industrial maintenance grades.
Pricing Analysis
The customization-premium spread separates configured-to-order powder coating resins from standard liquid grades, with contract-based long-term offtake dominating automotive OEM procurement while spot purchasing persists in construction bulk delivery. Price differentiation hinges on REACH certification tier and just-in-time logistics integration, with cost compression in commodity grades intensifying due to terephthalic acid feedstock volatility. Automotive clearcoat formulators exhibit the least price sensitivity, while regional industrial maintenance contractors in fragmented European markets drive hardest bargain negotiations.
Supply Chain Analysis
Tariff exposure between China and North American coating formulators dominates supply chain risk assessment for liquid saturated polyester resin. Manufacturing concentrates in China, Germany, and Japan, with production drawing from terephthalic acid, isophthalic acid, and neopentyl glycol feedstocks. Single-source vulnerability persists in tin-free catalyst chemistry compliant with ECHA RoHS restrictions. Distribution runs through specialty chemical distributors aggregating mid-tier formulator demand across India and Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified polycondensation reaction engineers capable of melt-phase molecular weight targeting at 220–260°C represent the critical capability gap constraining capacity expansion, filtering viable producers to those with legacy polyester production heritage.
For Market Incumbents: Harden specification-grade certification moats through dedicated powder coating technology centers in high-growth manufacturing regions, while deepening backward integration into dicarboxylic acid feedstocks to defend margin stability against Asian import competition. Prioritize alternative titanium or zirconium catalyst chemistry investment to preempt ECHA RoHS compliance disruption. For New Entrants and Emerging Players: Mid-tier flexible packaging lamination adhesive producers in India and Southeast Asia represent the most penetrable entry point, given BIS certification formalization and documented batch consistency requirements that filter smaller exporters. Target food-contact film applications with specification-grade resin positioning, leveraging distributor credit extension partnerships to overcome state-level tax complexity barriers. For Investors and Strategic Acquirers: REACH registration cost escalation reshapes the acquisition landscape toward producers with established European downstream coating supply chain relationships and certified low-emission curing platforms. Long-term viability favors backward-integrated specialists with alternative catalyst process chemistry. Monitor EPA 40 CFR Part 59 VOC limit tightening and California CARB divergence as the signal for regional formulation platform consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Catalyst Chemistry Investment | Titanium and zirconium process platforms preempt ECHA RoHS heavy metal restrictions on tin-based polycondensation. |
| Powder Coating Technology Center Expansion | Dedicated facilities in Germany and China anchor specification-grade demand from BMW, Mercedes-Benz, and Volkswagen clearcoat programs. |
| Backward Integration into Dicarboxylic Acids | In-house terephthalic acid production secures margin stability against Asian petrochemical complex pricing volatility. |
| Flexible Packaging Adhesive Grade Development | Heat seal strength and retort resistance specifications outcompete polyurethane alternatives in China and India food-contact film markets. |
| Distributor Credit Extension Infrastructure | Specialty chemical intermediaries buffer inventory risk and aggregate technical service demand for mid-sized coating formulators below thousand-ton offtake. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Interviews with plant managers at polycondensation facilities, procurement leads at downstream automotive OEM coating operations, distribution channel partners in India and Southern Europe, and technical R&D directors at powder coating formulators inform qualitative assessment. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic overlays.
Forecast inputs include grade tier differentiation between saturated, unsaturated, and modified resin architectures; end-use industry segmentation across coatings, adhesives, and composites; and regional production hub classification spanning China coastal clusters, Rhine-Ruhr corridor, and Nagoya-Toyota industrial belt. CAGRs derive from elasticity-adjusted demand projections across the analysis window, incorporating EPA VOC regulatory trajectory and ECHA substance evaluation protocol timelines as structural demand shifters.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, petrochemical feedstock pricing, and currency volatility across Asian export markets would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between liquid and powder coating platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Agar Resin Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
United Kingdom Engineering Plastics Market