
 Lapping and Polishing Films Market | 2026-2036
Lapping and Polishing Films Market Size, Share, and Industry Trends Forecast 2026-2036
Lapping and Polishing Films Market Foresight
Buyer concentration in semiconductor manufacturing is consolidating as foundries scale captive polishing operations for advanced node wafers. 3M leverages its materials science portfolio to sustain dominance in polymeric film substrates for chemical mechanical polishing. Saint-Gobain anchors European supply through specialized silicon carbide formulations serving optical component fabricators. Mipox competes aggressively in East Asian markets with precision-coated diamond films for hard substrate finishing.
Lapping and polishing films are engineered abrasive substrates comprising bonded mineral particles on flexible backings, typically specified by grit size ranging from sub-micron to tens of microns, designed to achieve nanometer-level surface flatness on metals, ceramics, and semiconductor wafers. Diamond films command premium positioning in semiconductor wafer thinning applications where material removal rates and scratch-free surfaces justify higher unit costs. Chemical mechanical polishing technology leads volume adoption in foundries, while ultrasonic polishing gains traction in aerospace component shops processing nickel-based superalloys with complex geometries.
ISO surface roughness standards and SEMI guidelines govern film performance specifications for semiconductor applications, while EPA and REACH frameworks restrict solvent-based coating chemistries and abrasive dust emissions in manufacturing facilities. China's MEE enforces wastewater treatment standards for slurry film production lines, adding compliance costs for regional suppliers. Stakeholders must monitor evolving particulate emission thresholds and substrate recycling mandates as environmental compliance becomes inseparable from production economics.
Market Dynamics
Semiconductor node shrinkage below 3nm is forcing foundries to retool polishing lines for atomic-scale surface control, compressing equipment replacement cycles and concentrating film specification power among captive fab operators.
Growth Catalysts
- Sub-3nm wafer processing:Advanced logic fabs in South Korea and Taiwan are mandating sub-nanometer surface roughness specifications that only precision-coated diamond films can reliably deliver.
- China's dual carbon framework:MEE wastewater standards and GB energy efficiency mandates are accelerating replacement of solvent-based coating lines with aqueous film production systems.
- REACH chemical restrictions:ECHA substance authorizations are eliminating legacy abrasive binders from European optical component supply chains, creating specification premiums for compliant film substrates.
Market Restraints
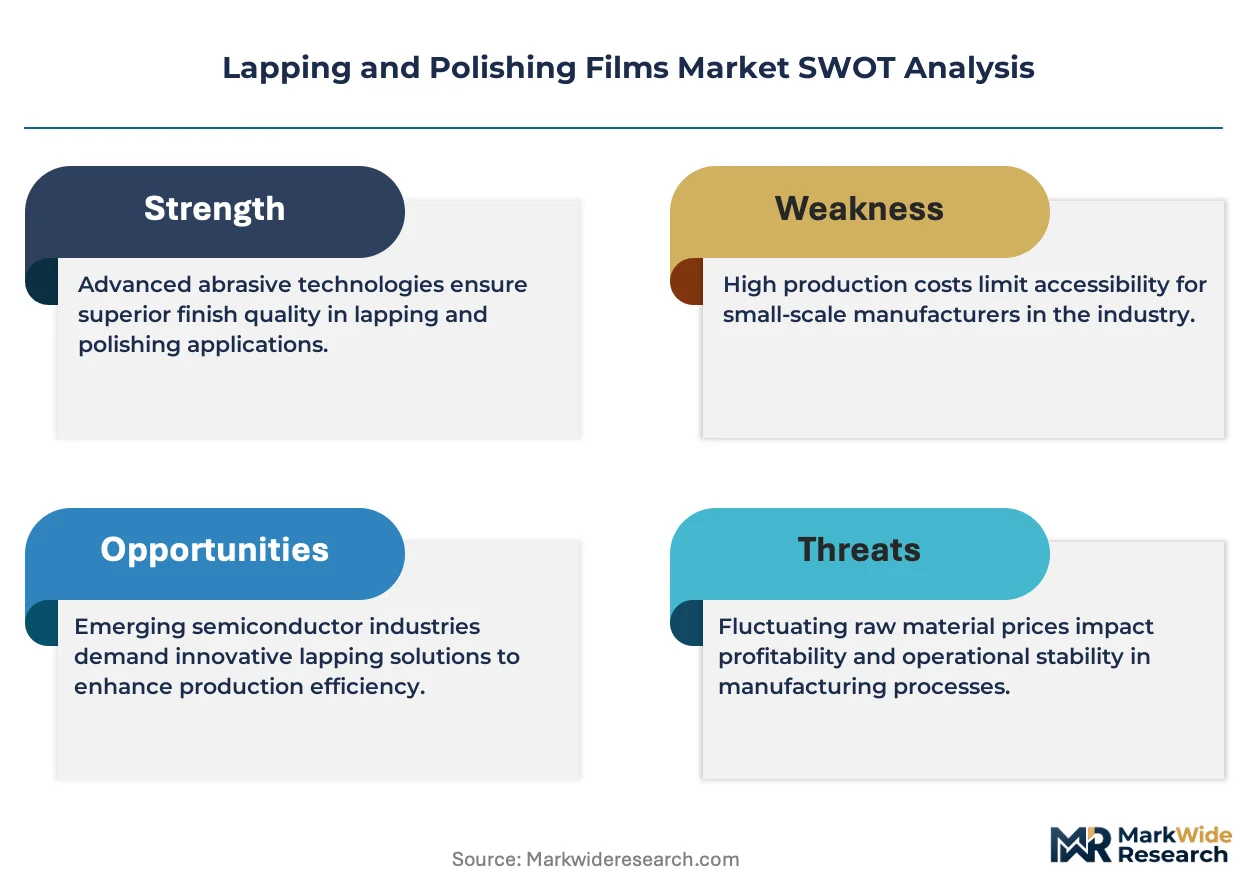
- Petrochemical input volatility:Polymeric film backings depend on polyester and polyimide feedstocks whose pricing tracks crude oil and purified terephthalic acid spot markets.
- East Asian supply concentration:Precision coating capacity clusters in Japan's Kansai region and China's Jiangsu province, exposing buyers to single-source geographic risk.
- Silicon carbide grain substitution:Hard ceramic substrates in aerospace turbine blade finishing are migrating to fixed-abrasive grinding wheels with longer service intervals.
Strategic Opportunities
- India's PLI-linked semiconductor fabs:Gujarat and Karnataka greenfield projects will import initial polishing film volumes before local coating capacity matures.
- Ultrasonic polishing integration:Hybrid systems combining chemical mechanical planarization with megasonic agitation are opening specification windows for compliant intermediate films.
- Film substrate recycling mandates:EU Green Deal circular economy directives will reward suppliers with closed-loop polyester recovery programs.
Industry Challenges
- Thin-film metrology expertise:Nanometer-level surface characterization requires atomic force microscopy and white-light interferometry skills scarce in traditional abrasive coating facilities.
- SEMI S2/S8 compliance timelines:Semiconductor equipment safety certifications demand 18-24 month validation cycles that delay new film product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lapping and Polishing Films Market |
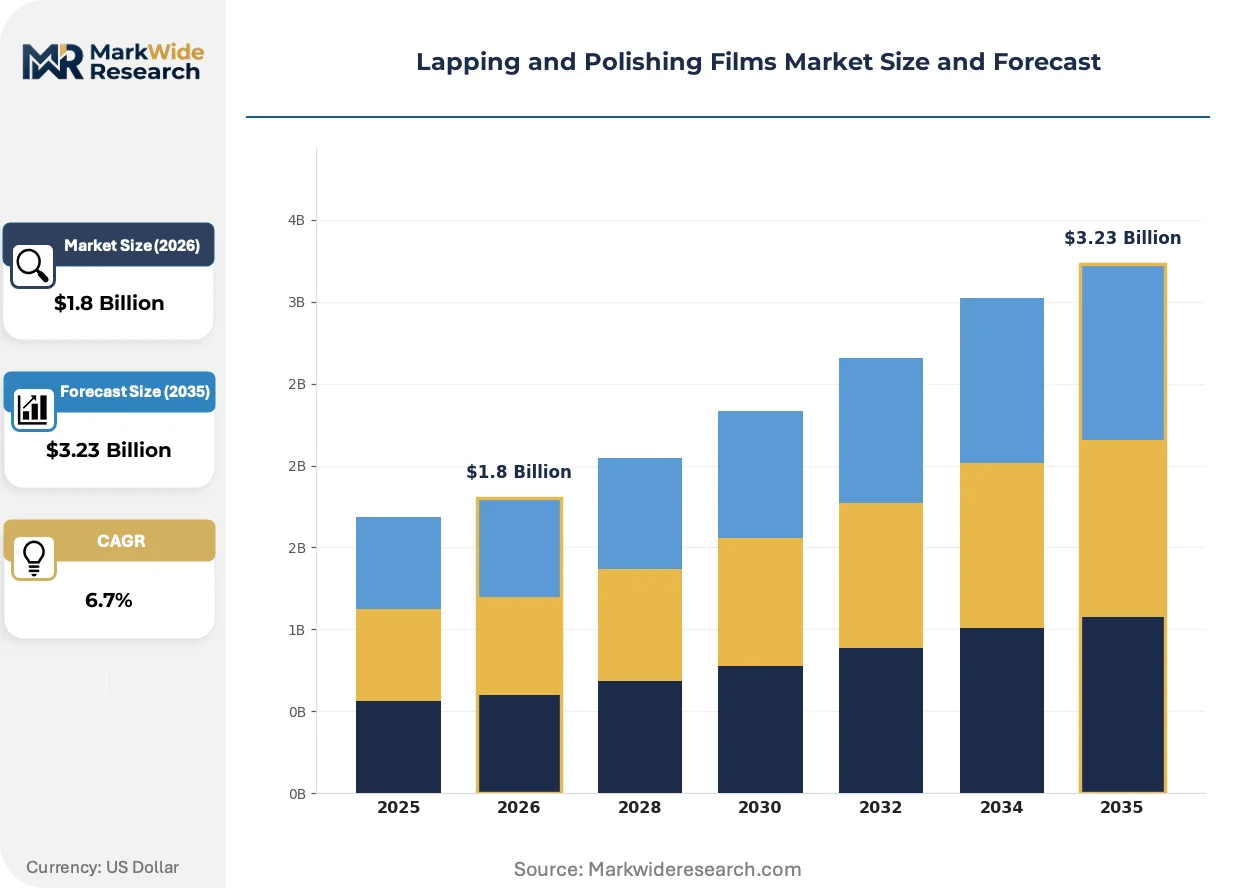
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Films, Silicon Carbide Films, Aluminum Oxide Films, Polymeric Films Application: Optical Components, Semiconductor Manufacturing, Automotive Parts, Aerospace Components End User: Manufacturers, R&D Institutions, Component Suppliers, Service Providers Technology: Mechanical Polishing, Chemical Mechanical Polishing, Ultrasonic Polishing, Electropolishing |
| Companies Covered | 3M, Saint-Gobain, Lapmaster, Mipox, Diagrind, Kemet, Okamoto Machine Tool Works, Tokyo Diamond, Naniwa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lapping and Polishing Films Market Shifts & Advancements
Polishing film technology is bifurcating between ultra-precision semiconductor applications and cost-optimized industrial finishing, with coating chemistry and backing flexibility emerging as the primary axes of differentiation.
Fixed-abrasive diamond films with electroless nickel bonding layers are overtaking resin-bonded alternatives in silicon carbide wafer thinning operations. Power semiconductor fabricators in Japan and Germany are adopting these films for 150mm and 200mm substrate processing. The shift is compressing demand for conventional alumina-based lapping products in hard-material applications.
EPA NESHAP hazardous air pollutant standards are forcing US-based coating facilities to eliminate methylene chloride and perchloroethylene from abrasive slurry formulations. Optical component manufacturers serving defense and aerospace programs are qualifying aqueous-based polyurethane binders as replacements. California's CARB protocols are extending these restrictions to imported film products, reshaping supplier qualification requirements.
Consolidated procurement through fab equipment OEMs is displacing direct film purchasing by individual semiconductor operators. Applied Materials and Tokyo Electron are bundling consumable supply agreements with polishing platform sales. Taiwan's foundry cluster exhibits the most advanced captive integration, with TSMC and UMC negotiating multi-year film supply commitments tied to equipment refresh cycles.
Lapping and Polishing Films Market Segmentation
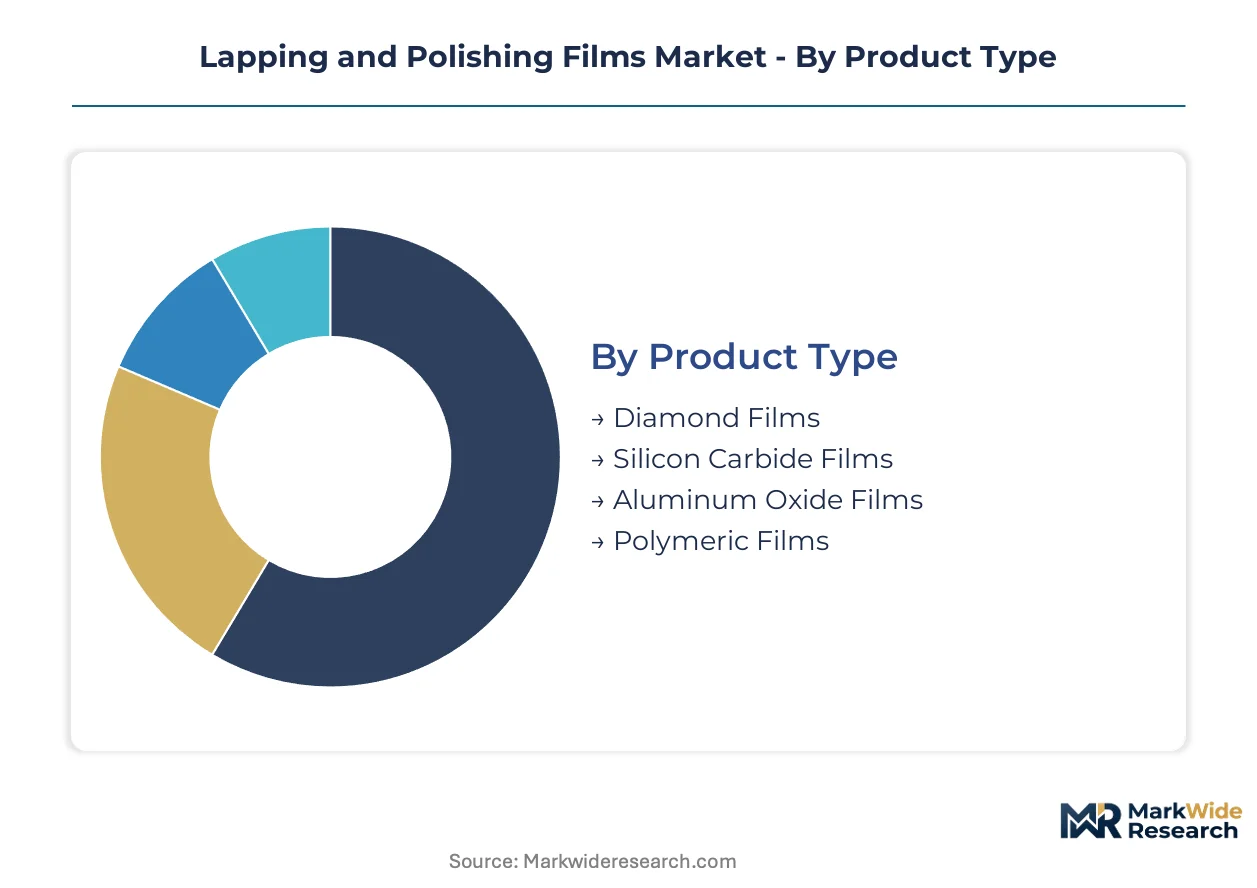
Film specification power concentrates among semiconductor foundries and optical fabricators whose surface roughness tolerances dictate abrasive mineral selection, backing flexibility, and coating chemistry. Segmentation reveals how technology roadmaps and regulatory compliance reshape procurement patterns across precision manufacturing verticals.
Product Type:
Buyers prioritize material removal rate and surface integrity when selecting abrasive mineral systems for specific substrate hardness and geometry requirements.
- Diamond Films:Synthetic or natural diamond particles bonded to polyester or polyimide backings achieve sub-nanometer surface finishes on silicon carbide and sapphire substrates. South Korean power semiconductor fabs specify electroless nickel-bonded diamond films for 150mm wafer thinning operations where scratch-free surfaces command specification premiums.
- Silicon Carbide Films:Green silicon carbide grains in resin or vitrified bonds deliver aggressive stock removal on hard ceramics and tungsten carbide. German optical component manufacturers favor these formulations for lens grinding applications governed by ISO surface roughness standards.
- Aluminum Oxide Films:Fused alumina abrasives on flexible backings serve cost-sensitive metal finishing in automotive and general industrial applications.
- Polymeric Films:Engineered polymer composites without mineral abrasives function as final-stage polishing substrates for delicate surface protection.
Diamond films lead on scale through semiconductor captive consumption; silicon carbide films lead on momentum as optical defense programs qualify aqueous binder replacements for REACH compliance.
Application:
End-use surface flatness specifications range from atomic-scale semiconductor nodes to micrometer-level automotive cosmetic finishes.
- Semiconductor Manufacturing:Chemical mechanical planarization dominates wafer processing with slurry-based films achieving angstrom-level uniformity. Taiwan's foundry cluster consumes the highest film volumes as TSMC and UMC scale sub-3nm production lines with 18-24 month equipment certification cycles.
- Optical Components:Precision lens and prism fabrication demands tight thickness tolerance control across curved geometries. Japanese camera module suppliers specify sub-micron alumina films for smartphone lens arrays requiring transmission clarity.
- Automotive Parts:Powertrain and cosmetic finishing applications prioritize throughput over nanometer precision.
- Aerospace Components:Nickel-based superalloy turbine blades with complex internal cooling passages drive ultrasonic polishing film adoption.
Semiconductor manufacturing leads on scale through fab equipment bundling; aerospace components lead on momentum as hybrid megasonic systems open specification windows.
End User:
Procurement authority varies between captive in-house operations and outsourced finishing service networks.
- Manufacturers:Captive polishing lines at semiconductor foundries and optical fabricators specify films directly or through equipment OEM bundled agreements. Consolidated procurement through Applied Materials and Tokyo Electron displaces direct purchasing at mature fabs.
- R&D Institutions:University and national laboratory facilities drive qualification of experimental coating chemistries and novel abrasive minerals.
- Component Suppliers:Tier-2 and tier-3 parts producers rely on distributor networks for standard film grades.
- Service Providers:Independent job shops process variable substrate mixes with flexible film inventory.
Manufacturers lead on scale through multi-year supply commitments; R&D institutions lead on momentum as aqueous binder development accelerates.
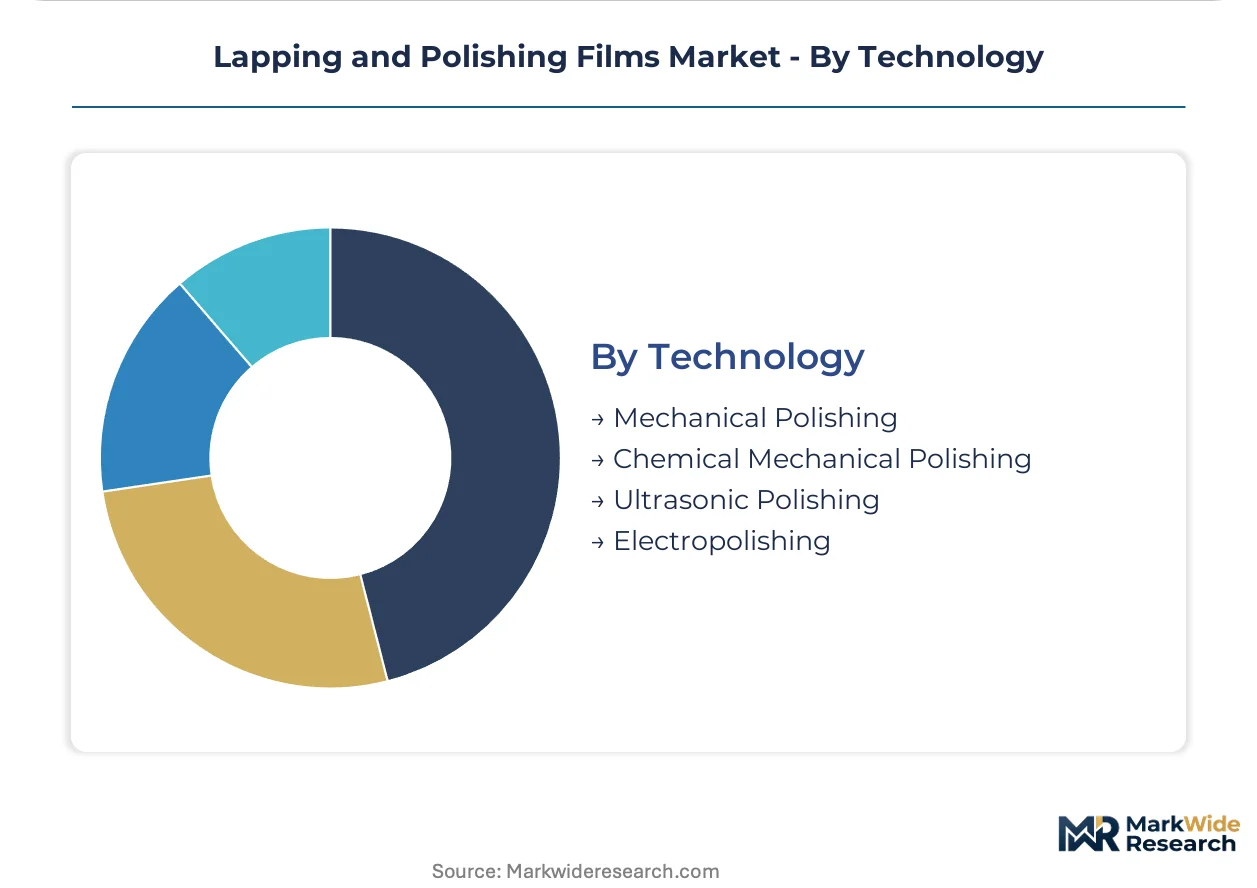
Technology:
Process selection balances material removal rate against surface damage layer depth and geometric complexity.
- Chemical Mechanical Polishing:Synergistic chemical oxidation and mechanical abrasion achieves global planarization on semiconductor wafers. Foundries in Japan and Germany adopt fixed-abrasive diamond films to replace slurry systems in silicon carbide power device processing.
- Ultrasonic Polishing:Megasonic agitation enhances slurry penetration into complex geometries. Aerospace turbine blade manufacturers specify these systems for nickel superalloy finishing where conventional mechanical polishing creates surface cracking.
- Mechanical Polishing:Conventional abrasive contact remains dominant for flat surface finishing with lower precision requirements.
- Electropolishing:Electrolytic material removal serves stainless steel medical device and food equipment applications.
Chemical mechanical polishing leads on scale through semiconductor volume concentration; ultrasonic polishing leads on momentum as megasonic hybrid systems gain aerospace qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision coating specialists cluster in East Asian electronics manufacturing corridors and German optical fabrication zones, with regulatory frameworks in China and the European Union reshaping production economics through environmental compliance mandates.
China
Jiangsu province hosts the densest concentration of aqueous film coating facilities serving domestic semiconductor fabs. MEE wastewater discharge standards and GB energy efficiency mandates are forcing solvent-based production line conversions. Suzhou and Wuxi industrial parks attract precision abrasive suppliers positioning for captive fab demand from SMIC and Hua Hong.
Japan
Kansai region coating specialists supply electroless nickel-bonded diamond films for silicon carbide wafer thinning. METI industrial technology roadmaps prioritize sub-nanometer surface finishing capabilities. Osaka and Kyoto prefectures concentrate legacy abrasive manufacturers transitioning aqueous binder formulations to maintain export competitiveness under REACH-aligned customer specifications.
South Korea
Gyeonggi-do province foundry clusters consume premium diamond films for sub-3nm logic wafer processing. MFDS chemical substance notifications intersect with customer-driven sustainability audits. Samsung and SK Hynix captive polishing operations in Hwaseong and Icheon compress equipment replacement cycles and concentrate specification authority among domestic equipment OEMs.
Taiwan
Hsinchu Science Park anchors the highest film consumption intensity per fab square meter globally. TSMC and UMC multi-year supply commitments tied to Applied Materials and Tokyo Electron equipment bundles displace direct procurement. Tainan and Taichung satellite clusters are qualifying local coating capacity to reduce import dependency for intermediate-precision applications.
Germany
Bavaria and Baden-Württemberg optical component fabricators specify silicon carbide films for defense and aerospace lens grinding. ECHA substance authorizations under REACH are eliminating legacy abrasive binders from supply chains. Zeiss and Leica supplier qualification programs in Oberkochen and Wetzlar create specification premiums for compliant aqueous polyurethane binder systems.
Lapping and Polishing Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers, creating a bifurcated structure where materials science breadth confronts abrasive coating depth. The market organizes around three strategic archetypes: multinational diversified industrials with polymer substrate capabilities, regional precision coating specialists with mineral bonding expertise, and equipment-integrated consumable suppliers leveraging platform bundling. Consolidation pressure intensifies through fab equipment OEM captive supply agreements and aqueous coating line investments requiring capital scale.
Among diversified materials conglomerates, 3M and Saint-Gobain exemplify archetypes combining polymer science portfolios with abrasive application expertise. 3M represents the polymeric film substrate specialist position, while Saint-Gobain anchors European supply through silicon carbide formulation heritage. Focused specialists including Mipox, Lapmaster, and Kemet occupy positions defined by precision mineral coating depth rather than substrate breadth, with Mipox exemplifying the East Asian diamond film competitor archetype.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Lapmaster |
| Mipox |
| Diagrind |
| Kemet |
| Okamoto Machine Tool Works |
| Tokyo Diamond |
| Naniwa |
| Others |
Supply & Pricing Matrix
Precision coating technicians in Japan's Kansai region command wage premiums that compress margins on electroless nickel-bonded diamond films, widening spreads between premium semiconductor-grade and economy industrial formulations. Labor-cost differentials between Japanese specialists and Jiangsu province aqueous coating facilities translate into pricing-tier stratification across diamond, silicon carbide, and alumina film categories.
Pricing Analysis
Bundled equipment-consumable agreements through Applied Materials and Tokyo Electron dominate semiconductor procurement, while unbundled spot purchasing persists in automotive and general industrial channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO surface roughness certification grades and volume scale commitments. Cost compression in economy alumina films is intensifying because Chinese aqueous coating capacity expansion floods industrial segments. Tier-2 component suppliers exhibit highest price sensitivity; captive foundry operators with multi-year equipment bundles show least.
Supply Chain Analysis
Polyester and polyimide substrate supply rests on Japanese and South Korean petrochemical producers, with purified terephthalic acid feedstock tracking crude oil benchmarks. Synthetic diamond grit draws from Russian and Chinese superabrasive manufacturers; electroless nickel bonding chemistry sources from German specialty chemical houses. Single-source vulnerability concentrates in Kansai-region precision coating equipment. Distribution runs through fab equipment OEM captive agreements for semiconductor grades, industrial distributors for automotive and aerospace segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lapping and Polishing Films Market functions as a stable compounder anchored by irreversible semiconductor node shrinkage that perpetuates equipment refresh cycles and consumable demand.
For Market Incumbents: Deepen aqueous binder formulation expertise to preempt REACH-aligned customer qualification requirements in European optical supply chains. Expand captive coating capacity in Jiangsu province industrial parks to capture China's domestic fab buildout. Silicon carbide grain substitution in aerospace turbine applications threatens resin-bonded film demand; electroless nickel bonding investments defend positioning.
For New Entrants and Emerging Players: Launch via distributor partnerships serving India's PLI-linked semiconductor fabs in Gujarat and Karnataka before local coating capacity matures. Target intermediate-precision optical component applications where Zeiss and Leica supplier qualification programs create specification premiums for compliant aqueous polyurethane systems. Ultrasonic polishing film integration into hybrid megasonic systems offers the most penetrable specification window.
For Investors and Strategic Acquirers: Fab equipment OEMs represent the most active acquirer in this space, consolidating consumable supply agreements alongside polishing platform sales. Five-to-ten year viability hinges on aqueous coating chemistry transitions and sub-3nm surface finishing capability depth. Acquisition target archetype: regional precision coating specialists with mineral bonding expertise and established SEMI S2/S8 certification timelines. Monitor EPA NESHAP enforcement expansion to imported film products as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Line Conversion | MEE wastewater standards and REACH compliance eliminate solvent-based production economics. |
| Electroless Nickel Bonding Investment | Power semiconductor fabricators in Japan and Germany adopt fixed-abrasive diamond films for silicon carbide processing. |
| India Distribution Partnership | Gujarat and Karnataka greenfield fabs import initial volumes before local coating capacity matures. |
| Closed-Loop Polyester Recovery | EU Green Deal circular economy directives reward suppliers with substrate recycling programs. |
| Hybrid Megasonic System Qualification | Aerospace turbine blade manufacturers specify ultrasonic polishing films for nickel superalloy finishing. |
Research Methodology
Multiple input streams — primary interviews with precision coating facility managers, semiconductor fab procurement directors, and optical component quality engineers; secondary validation through SEMI equipment shipment data, EPA NESHAP enforcement records, and customs trade statistics — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations with aqueous binder R&D specialists, industrial distributor category managers, and METI technology roadmap officials informed coating chemistry transition assumptions. SEC filings from diversified materials conglomerates and regional abrasive manufacturer disclosures supplied capacity and margin benchmarks.
Historical volume trajectories were cross-referenced against panel input from equipment OEM consumable strategists and foundry operations executives. Segmentation dimensions modeled encompass abrasive mineral type, backing substrate chemistry, application precision tier, and regional regulatory compliance cluster across the projection horizon. CAGRs were derived from equipment replacement cycle compression rates and aqueous coating line conversion timelines. Forecast inputs incorporated SEMI wafer fab capacity announcements and China's dual carbon policy enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical feedstock price spikes or accelerated silicon carbide substitution in aerospace applications. Forecasts reflect documented assumptions regarding node shrinkage cadence and environmental compliance phase-in schedules. Abrasive dust emission threshold revisions, substrate recycling mandate acceleration, and geopolitical disruption to Japanese polyester supply constitute specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Tools Market
Abrasives
Grinding Wheels Market
Abrasives
Liquid Sandpaper Market
Abrasives
Artificial Abrasives Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
North America Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
RDP Powder Market
Abrasives
Abrasive Cloth Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Boron Carbide Bulletproof Plate Market
Abrasives
Fine Sandpaper Market
Abrasives
Tungsten Carbide Market
Abrasives
New Zealand Abrasives Market
Abrasives
Coated Abrasives Market
Abrasives
Non-Woven Abrasives Market