
 Ethylene Acrylic Acid (EAA) Copolymers Market | 2026-2036
Ethylene Acrylic Acid (EAA) Copolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Acrylic Acid (EAA) Copolymers Market Foresight
China's petrochemical corridor is reshaping regional supply availability for acid-functional polyolefins. ExxonMobil leverages integrated polyethylene feedstock positions to sustain cost-competitive EAA output across Asia-Pacific. Dow Chemical anchors North American supply through Gulf Coast steam-cracker proximity, while Arkema SA specializes in high-acid-content grades for niche bonding applications.
Ethylene acrylic acid copolymers are thermoplastic resins synthesized via high-pressure free-radical polymerization, typically containing 3–20% acrylic acid by weight to deliver controlled adhesion and barrier performance. These materials function primarily as tie-layer adhesives in multilayer packaging structures and as heat-seal coatings demanding metal adhesion. Low-density grades dominate volume flows in flexible packaging laminates where puncture resistance and seal integrity command premium placement. Film applications represent the fastest-expanding consumption vector, driven by downgauging trends in food-contact pouches that demand thinner yet stronger barrier layers.
FDA food-contact notifications and EU REACH chemical registration requirements govern monomer migration limits and compositional disclosure for EAA copolymers entering consumer packaging. China's GB standards and evolving MEE environmental compliance protocols are tightening volatile organic compound thresholds at downstream coating operations. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification roadmaps with end-user procurement mandates.
Market Dynamics
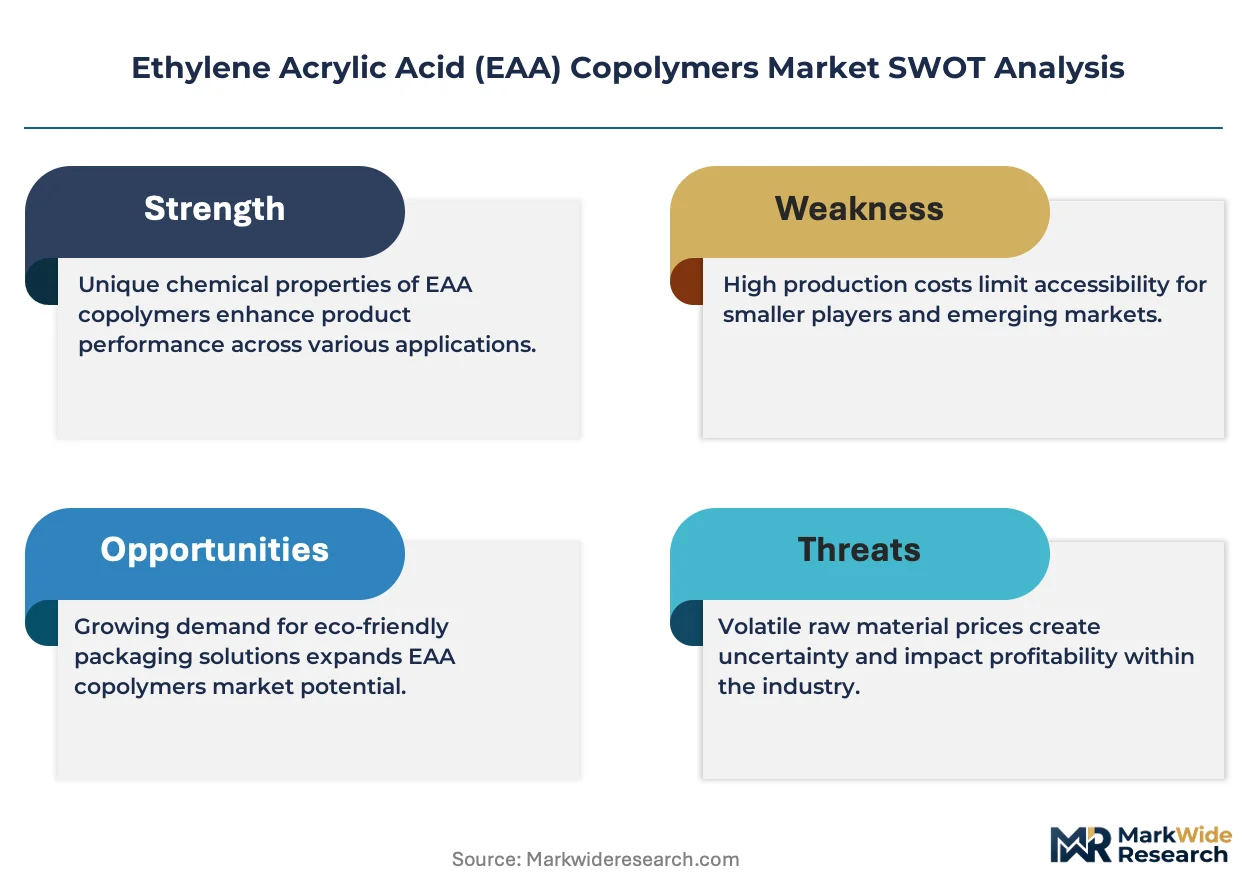
High-pressure free-radical polymerization capacity is consolidating along Asia-Pacific ethylene corridors, compressing margin structures for merchant-grade EAA suppliers dependent on spot feedstock procurement.
Growth Catalysts
- Flexible packaging downgauging:Meat and dairy pouch converters in China are specifying thinner EAA tie-layers to reduce material intensity while maintaining oxygen barrier performance.
- REACH purity mandates:ECHA registration requirements for adhesive-grade resins are filtering out low-purity competitors, concentrating procurement among certified polymer suppliers.
- Film extrusion scaling:Domestic Chinese extruders are expanding multilayer blown film lines, pulling acid-functional polyolefin volumes away from import-dependent converters.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Northeast Asia swing with crude differentials, transmitting cost instability to EAA contract pricing.
- High-acid grade supply concentration:Arkema SA and specialty resin houses control >80% of >15% acrylic acid content grades, creating procurement bottlenecks for niche bonding applications.
- Polyethylene ionomer substitution:DuPont's Surlyn and equivalent zinc-neutralized alternatives are capturing heat-seal coating share where metal adhesion requirements moderate.
Strategic Opportunities
- India packaging industrialization:FSSAI food-contact compliance investments by domestic converters are creating first-mover advantages for EAA suppliers establishing local compounding partnerships.
- Recyclable monomaterial structures:CEFLEX design guidelines are incentivizing all-polyethylene pouch architectures where EAA tie-layers replace incompatible adhesive chemistries.
- EV battery pouch films:Aluminum-laminated cell encapsulation is emerging as a high-barrier application for acid-functional polyolefin heat-seal layers in Korea and Japan cell manufacturing.
Industry Challenges
- Migration testing capacity:FDA food-contact notification protocols require specialized analytical chemistry capabilities that smaller compounders struggle to resource.
- Multilayer coextrusion integration:Converters retrofitting legacy lines for seven-layer structures face downtime and scrap rate spikes during EAA tie-layer calibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Acrylic Acid (EAA) Copolymers Market |
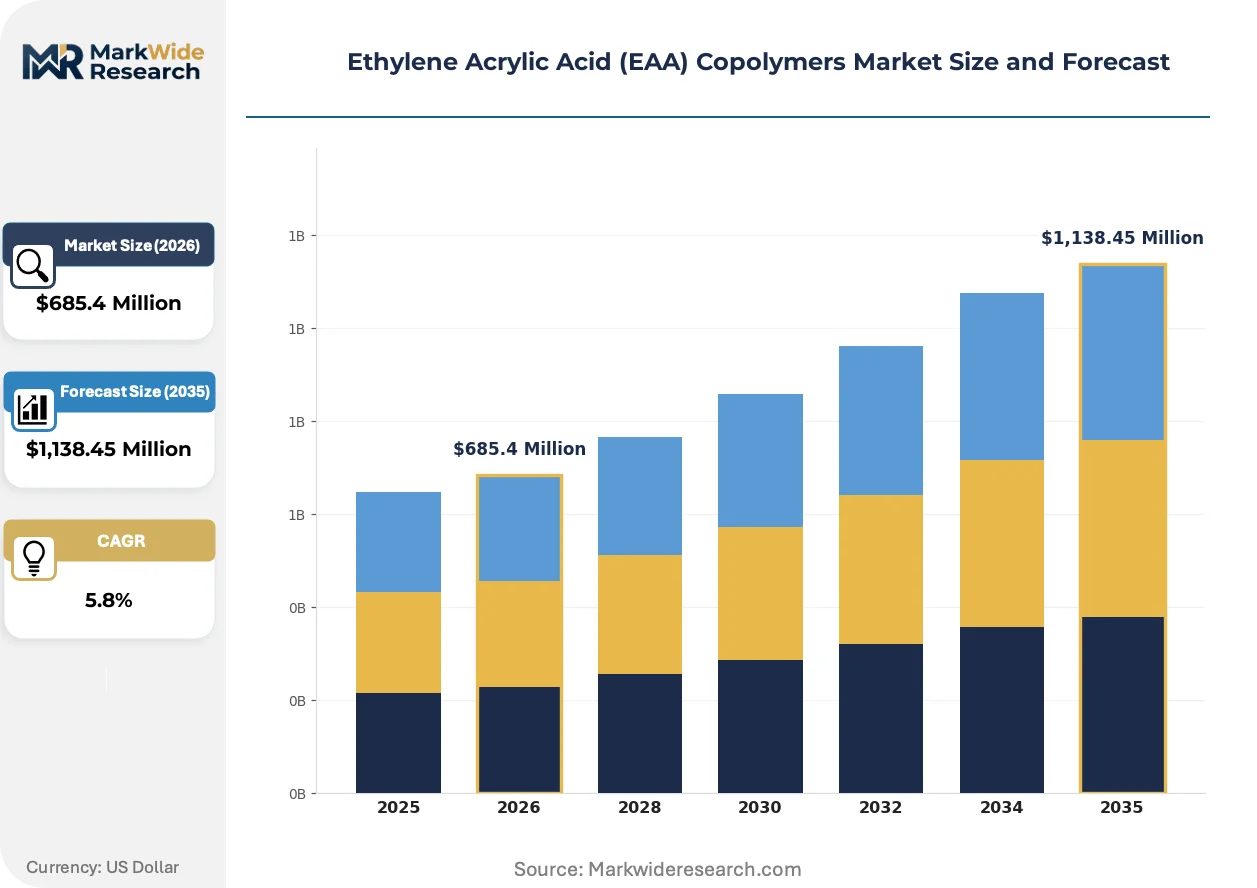
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density, High Density, Medium Density, Copolymer Blends Application: Adhesives, Coatings, Films, Packaging End User: Automotive, Consumer Goods, Construction, Electronics Form: Granules, Powders, Sheets, Liquid Solutions |
| Companies Covered | ExxonMobil, Evonik Industries AG, The Dow Chemical Company, DuPont, Mitsui Chemicals Inc., Arkema SA, LyondellBasell, Honeywell International Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Acrylic Acid (EAA) Copolymers Market Shifts & Advancements
Reactive extrusion and acid-anhydride grafting technologies are compressing the performance gap between commodity polyolefins and specialty copolymers, forcing EAA producers to defend premium positioning through certification depth rather than intrinsic properties alone.
Metallocene-catalyzed ethylene-acrylic acid copolymers with narrow molecular weight distribution are rendering obsolete conventional tubular-reactor grades in high-speed form-fill-seal operations. Japanese and Korean food converters are specifying these materials for 600+ pouches-per-minute lines where seal-initiation temperature consistency determines throughput. The shift is compressing demand for legacy high-pressure autoclave output that cannot meet tight MWD specifications.
EU REACH Article 33 substance disclosure requirements are forcing downstream laminators to document acrylic acid monomer residuals across multilayer film stacks. German and French packaging houses are now requiring full SCIP database registration from EAA suppliers, adding compliance overhead that favors integrated resin-to-film producers over merchant compounders. The regulatory drag is most acute in medical device pouch applications where EFSA migration limits intersect with MDR technical documentation mandates.
Direct mill procurement of acid-functional polyolefins is displacing distributor intermediation among top-quartile flexible packaging groups. North American and European converters with annual EAA volumes exceeding 500 metric tons are negotiating frame contracts with ExxonMobil and Dow Chemical, extracting price transparency and technical service commitments that smaller competitors cannot match. The channel compression is visible in Gulf Coast and Rotterdam chemical trading hubs where distributor inventories of adhesive-grade resins have thinned.
Ethylene Acrylic Acid (EAA) Copolymers Market Segmentation
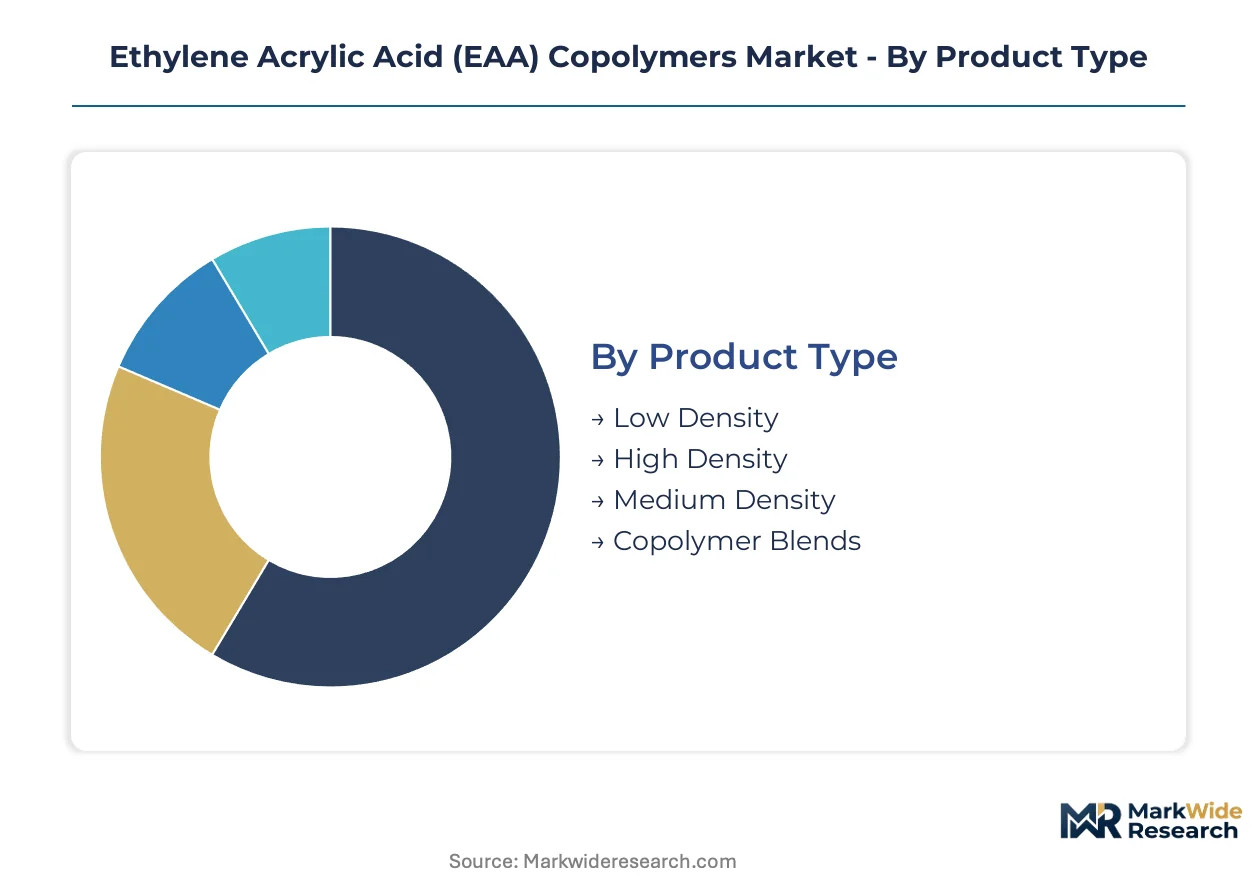
EAA copolymer specifications diverge sharply across end-use requirements, with density grades, application forms, and customer industries each imposing distinct performance thresholds. Procurement patterns in this market track directly to these technical boundaries, as converters select resin architectures optimized for specific barrier, adhesion, or processing demands.
Product Type:
Density gradients define the use-case spectrum, ranging from flexible packaging laminates requiring puncture resistance to rigid industrial applications demanding structural integrity.
- Low Density:These grades contain 3–10% acrylic acid by weight and deliver superior heat-seal initiation temperatures for multilayer food pouches. Chinese meat and dairy packaging converters are scaling procurement of these materials for downgauged barrier structures where seal integrity cannot compromise.
- High Density:Formulations with 15–20% acrylic acid content provide aggressive metal adhesion for aluminum-laminated battery pouch films. Korean and Japanese EV cell manufacturers are specifying these grades for high-barrier encapsulation layers in lithium-ion cell assembly.
- Medium Density:Intermediate acid-content resins balance processability with adhesion performance for general-purpose tie-layer applications.
- Copolymer Blends:Custom-formulated alloys with ionomers or other polyolefins target niche bonding requirements in automotive interior assemblies.
Established volume favors Low Density; emerging adoption favors High Density.
Application:
Functional roles segment by the interface requirements of the substrate system, from structural bonding to surface modification.
- Films:Blown and cast film extrusion consumes the majority of EAA volume, with seven-layer coextrusion lines in China and Southeast Asia pulling resin for barrier meat packaging. Downgauging trends are compressing tie-layer thicknesses while demanding equivalent oxygen transmission performance.
- Adhesives:Hot-melt and solvent-borne formulations leverage acid functionality for polar substrate bonding in automotive panel lamination. REACH compliance costs are filtering out uncertified compounders from European procurement lists.
- Coatings:Extrusion-coated layers on paper and foil substrates serve flexible packaging applications where heat-seal response must align with high-speed form-fill-seal equipment.
- Packaging:Direct-form applications include stand-up pouches and lidding films where EAA functions as both sealant and contamination barrier.
Film extrusion commands the largest share; adhesive formulations are climbing the fastest as automotive lightweighting intensifies.
End User:
Customer industries impose divergent certification and performance regimes, from food-contact migration limits to automotive flame-retardancy standards.
- Consumer Goods:Food packaging converters dominate procurement, with FSSAI compliance investments in India and FDA notification requirements in the United States shaping supplier qualification protocols. Flexible pouch demand for ready-to-eat meals is pulling acid-functional polyolefin volumes.
- Automotive:Interior trim bonding and underhood applications require thermal stability and plasticizer resistance that high-acid grades deliver. German and Japanese OEMs are specifying EAA tie-layers for instrument panel lamination to replace solvent-based adhesives.
- Electronics:EV battery pouch film applications are emerging as a specialized consumption vector in Korea and Japan cell manufacturing corridors.
- Construction:Geomembrane and roofing membrane applications utilize EAA for adhesion to concrete and metal substrates in waterproofing systems.
Consumer Goods anchors current demand; Electronics represents the steepest expansion trajectory.
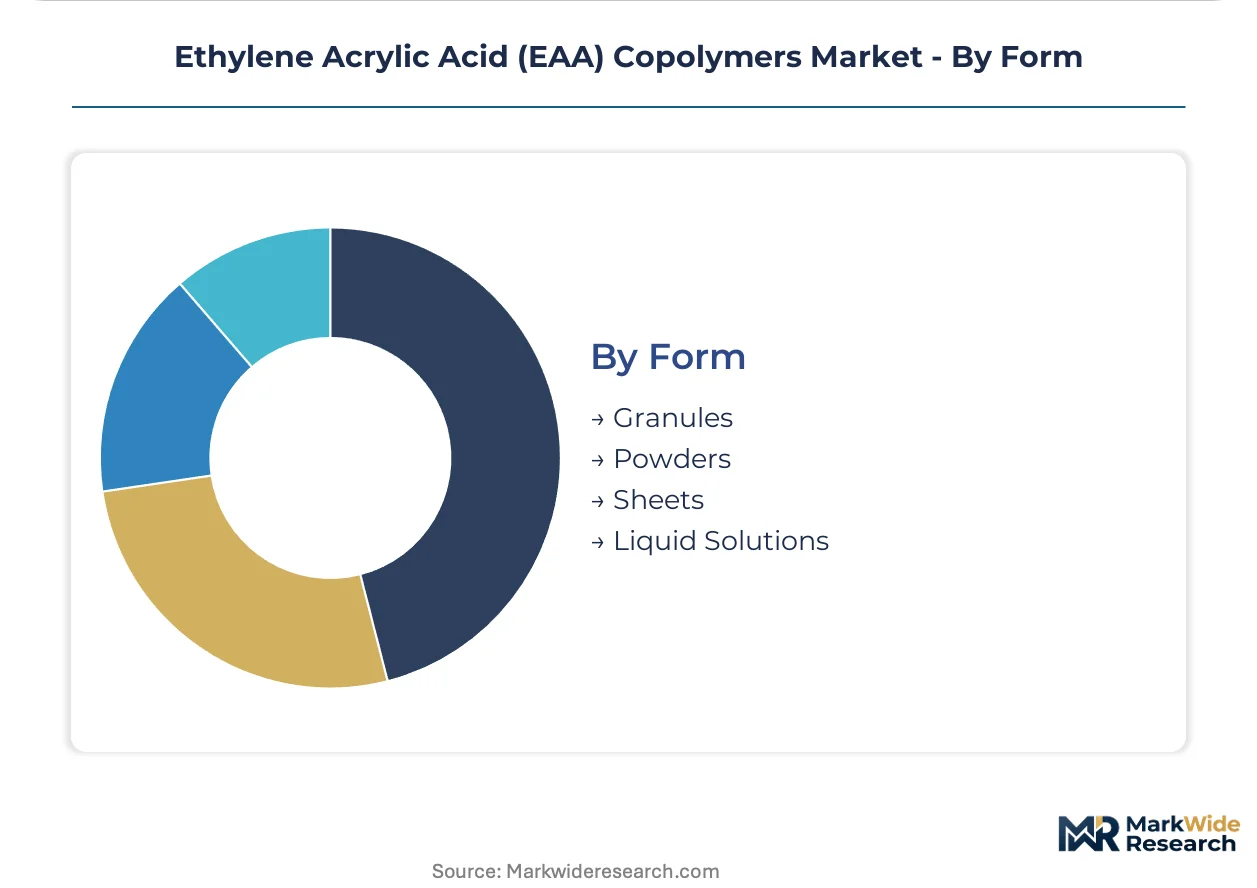
Form:
Physical presentation determines processing infrastructure compatibility and supply chain economics.
- Granules:Standard pellet form for extrusion and injection molding operations dominates merchant resin shipments. Direct mill procurement by large converters is compressing distributor margins for granule volumes.
- Powders:Micronized grades enable rotational molding and powder coating applications where melt flow control is critical.
- Sheets:Calendered or extruded sheet stock serves thermoforming operations for medical device tray applications requiring EFSA migration compliance.
- Liquid Solutions:Dispersions and emulsions target coating and adhesive formulations where solvent-free processing is mandated by MEE environmental protocols in China.
Granule supply concentrates among integrated producers; liquid solutions are gaining share fastest as VOC regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes EAA copolymers predominantly for multilayer food packaging films, while the United States and Germany allocate larger shares to automotive bonding and industrial adhesive formulations, creating divergent specification requirements across major demand centers.
China
Domestic film extruders in the Yangtze River Delta are scaling seven-layer blown film capacity for meat and dairy pouches. GB standards and MEE environmental protocols are tightening VOC thresholds at downstream coating operations. Shanghai and Jiangsu province converters are pulling acid-functional polyolefin volumes away from import-dependent supply chains.
United States
Flexible packaging converters in the Midwest and Southeast are expanding procurement for high-barrier food pouches under FDA food-contact notification requirements. The EPA and OSHA govern workplace exposure limits at compounding facilities. Gulf Coast steam-cracker proximity anchors North American supply concentration near Houston and Lake Charles petrochemical corridors.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are specifying EAA tie-layers for instrument panel lamination to replace solvent-based adhesives. REACH Article 33 substance disclosure requirements and ECHA registration mandates are filtering out uncertified resin suppliers. The Cologne-Düsseldorf-Ruhr industrial cluster hosts specialized laminators demanding full SCIP database registration.
Japan
EV battery pouch film applications are emerging as a specialized consumption vector among Korean and Japanese cell manufacturers. METI industrial standards govern material qualification for lithium-ion cell encapsulation. The Kansai region around Osaka anchors demand for high-acid-content grades in electronics applications.
South Korea
Battery cell producers in the Busan-Ulsan corridor are specifying aluminum-laminated encapsulation layers for lithium-ion assembly. MFDS and METI-aligned technical specifications govern barrier performance thresholds. Daegu-Gyeongbuk region converters are scaling heat-seal coating capacity for regional EV supply chains.
Ethylene Acrylic Acid (EAA) Copolymers Market Competitive Landscape
Capability concentration sits with specialty resin houses controlling high-acid formulations; scale advantage sits with integrated petrochemical majors leveraging captive ethylene feedstock. The market structures around three tiers: global diversified chemicals with polymer divisions, regional polyolefin specialists with compounding expertise, and niche adhesive-grade formulators serving medical and electronics qualification requirements. Competitive dynamics center on backward integration into ethylene supply and certification depth for food-contact and battery-film applications.
Within the integrated petrochemical tier, ExxonMobil and Dow Chemical exemplify scale-driven positioning through Gulf Coast and Rotterdam corridor proximity to steam-cracker networks. Arkema SA occupies a specialist position concentrated in high-acid-content grades for niche bonding applications. Mitsui Chemicals Inc. represents the Asia-Pacific regional archetype with Japanese industrial qualification depth.
| Leading Market Players |
|---|
| ExxonMobil |
| Evonik Industries AG |
| The Dow Chemical Company |
| DuPont |
| Mitsui Chemicals Inc. |
| Arkema SA |
| LyondellBasell |
| Honeywell International Inc. |
| BASF SE |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta petrochemical corridor compresses margin structures for merchant-grade suppliers, transmitting feedstock cost volatility into downstream contract negotiations. Chinese domestic extruders leverage integrated ethylene positions to extract price transparency that import-dependent converters cannot match.
Pricing Analysis
Asia-Pacific spot premiums over Gulf Coast contract benchmarks have widened as naphtha-cracker margins swing with crude differentials. Contract-based long-term offtake dominates procurement above 500 metric tons annually, while spot transactions serve smaller compounders lacking frame agreements. Price differentiation separates FDA-notified food-contact grades from industrial adhesive tiers, with certification depth commanding 15-20% premiums. Cost compression in standard low-density grades is intensifying because Chinese domestic capacity expansion outpaces demand growth. Mid-size flexible packaging converters exhibit highest price sensitivity; battery film specialists show lowest.
Supply Chain Analysis
Export-control regimes on high-pressure polymerization technology limit capacity transfers to non-aligned manufacturing zones, constraining supply diversification. Production concentrates in the United States, China, and Germany, with South Korea and Japan anchoring specialty high-acid grades. Feedstock draws from ethylene derived via naphtha cracking and ethane feedstock flexibility at integrated complexes. Single-source vulnerability concentrates in >15% acrylic acid content grades where Arkema SA and two Japanese houses control qualified supply. Distribution runs through direct mill procurement displacing distributor intermediation among top-quartile converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and migration-testing certification programs are expanding faster than base resin volumes, creating recurring-revenue layers that compound customer switching costs.
For Market Incumbents: Insulate qualified supply positions by deepening backward integration into captive ethylene production and accelerating REACH-compliant grade registration ahead of ECHA enforcement waves. Polyethylene ionomer substitution from DuPont Surlyn and zinc-neutralized alternatives threatens heat-seal coating share; defend through FDA notification depth and seven-layer coextrusion technical support that commodity substitutes cannot replicate. For New Entrants and Emerging Players: Pursue India's FSSAI compliance gap as domestic converters industrialize food-contact packaging capacity without established EAA supplier relationships. The most penetrable white-space sits in medium-density tie-layer grades for general-purpose laminates where certification barriers are lower than high-acid battery film tiers. A compounding partnership with established film extruders offers faster qualification than greenfield resin production. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because regulatory divergence between FDA, REACH, and China's GB standards fragments supply qualification in ways that favor incumbents with analytical chemistry infrastructure. Acquisition targets should display SCIP database registration capability and existing food-contact notification portfolios. The signal to watch is battery cell manufacturer qualification timelines for aluminum-laminated pouch films in Korea and Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Gulf Coast and Rotterdam steam-cracker proximity secures cost-competitive monomer supply against naphtha volatility. |
| REACH-Compliant Grade Registration | ECHA certification filters out low-purity competitors, concentrating procurement among registered polymer suppliers. |
| Technical Service Contract Expansion | Migration-testing and coextrusion calibration support deepens customer switching costs beyond commodity resin supply. |
| India Compounding Partnership | FSSAI compliance investments by domestic converters create first-mover positioning without greenfield resin investment. |
| Battery Film Qualification Investment | EV cell manufacturer certification for aluminum-laminated encapsulation opens high-margin specialty grade demand. |
Research Methodology
Operator-level perspectives from polymer plant managers, flexible packaging procurement leads, film extrusion technical directors, and regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with customs trade data, ACC and Cefic industry reports, SEC 10-K resin segment disclosures, and FDA food-contact notification databases. Bottom-up grade-by-grade volume builds triangulated against top-down ethylene derivative consumption models.
Scenario-bracketing around feedstock cost volatility and regulatory enforcement intensity framed the projection horizon. Segmentation dimensions modeled include density grade tier, end-use industry application, packaging format, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating downgauging trends and substitution coefficients. Industry-specific inputs encompass multilayer coextrusion line capacity expansion schedules and EV battery cell manufacturing qualification timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price differentials, naphtha-cracker operating rates, or Chinese domestic capacity commissioning would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and substitution technology performance gaps. Material shifts in REACH Article 33 disclosure mandates or FDA migration limit revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Conductive Polymers Market