
 Hydrophobic Solvents Market | 2026-2036
Hydrophobic Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophobic Solvents Market Analytics
Aftermarket solvent recovery and reclamation services is reconfiguring margin pools away from virgin product sales across the hydrophobic solvents value chain. ExxonMobil Corporation leverages its integrated refining and petrochemical infrastructure to sustain cost advantages in hydrocarbon-grade production. BASF SE anchors European supply through its Ludwigshafen complex, while Dow Inc. competes on specification breadth across coatings and adhesives segments.
Hydrophobic solvents are non-polar or low-polarity organic liquids that resist mixing with water, typically exhibiting dielectric constants below 15 and water solubility under 0.1 g/100 mL at standard conditions, manufactured via catalytic reforming, alkylation, or fractional distillation of petroleum feedstocks to serve as reaction media, extraction agents, and formulation carriers in industrial processes. Hydrocarbon-type products dominate volume due to their cost structure and compatibility with legacy paint and cleaner formulations, while ketone grades command premium positioning in pharmaceutical extraction where residual moisture tolerance is critical. The coatings end-use industry occupies the largest share of value demand, though agrochemical formulation represents the fastest-growing application as crop protection chemistry shifts toward emulsifiable concentrate systems.
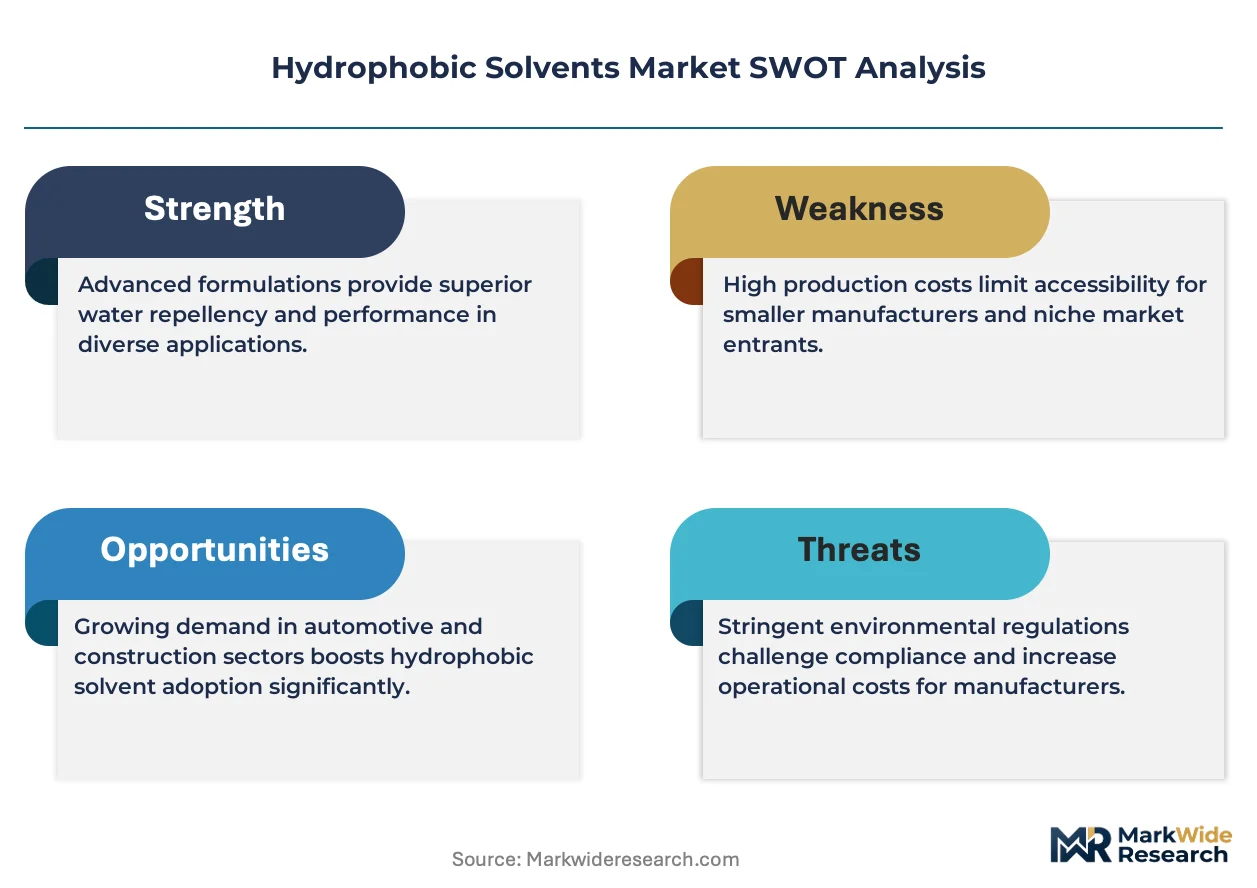
EPA hazardous air pollutant standards under NESHAP and EU REACH registration requirements constrain formulation chemistry choices and drive substitution toward lower-toxicity hydrophobic solvent grades. FDA oversight of residual solvent limits in pharmaceutical manufacturing, alongside OSHA permissible exposure limits for workplace chemical handling, further shapes product specifications and end-use market access. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualify alternative solvent systems before compliance deadlines tighten.
Market Dynamics
Specialty coatings manufacturers in Germany and the United States face mounting pressure to reformulate around EPA NESHAP and EU REACH volatile organic compound limits, forcing rapid substitution of legacy hydrophobic solvent grades and reshaping procurement specifications across automotive and aerospace supply chains.
Growth Catalysts
- EU REACH registration requirements:Stricter substance authorization timelines are compelling formulators to qualify higher-purity hydrophobic solvent grades, expanding addressable market for premium hydrocarbon and ketone products.
- Emulsifiable concentrate systems:Agrochemical manufacturers are accelerating adoption of hydrophobic carriers for crop protection chemistry, creating new volume demand from pesticide formulation facilities.
- Ludwigshafen production cluster:Integrated petrochemical infrastructure in Germany enables just-in-time solvent supply to continental European coatings plants, reducing working capital burdens for downstream customers.
Market Restraints
- Crude oil price volatility:Naphtha and reformate feedstock costs fluctuate with Brent crude benchmarks, compressing margin predictability for hydrocarbon-grade solvent producers.
- Mid-Continent supply concentration:Fractional distillation capacity clusters along the US Gulf Coast and Rotterdam-Antwerp corridor, exposing buyers to hurricane and labor disruption risks.
- Aqueous cleaner substitution:Water-based degreasing formulations are displacing hydrophobic solvents in metal finishing applications where moisture tolerance permits.
Strategic Opportunities
- India agrochemical formulation:CDSCO registration pathways for crop protection products are opening demand for import-grade hydrophobic carriers among domestic pesticide blenders.
- Pharmaceutical residual solvent limits:FDA oversight of Class 2 and Class 3 solvent thresholds is creating specification premiums for ultra-low moisture ketone grades in active pharmaceutical ingredient extraction.
- Solvent recovery services:Aftermarket reclamation infrastructure is emerging as a recurring revenue channel, decoupling supplier economics from virgin product volume.
Industry Challenges
- Cross-jurisdictional compliance:Divergent OSHA permissible exposure limits and EU workplace chemical directives force dual-track qualification of solvent grades, extending product development timelines.
- Legacy formulation integration:Paint and adhesive manufacturers face technical friction when substituting hydrophobic carriers into established resin systems, requiring reformulation validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophobic Solvents Market |
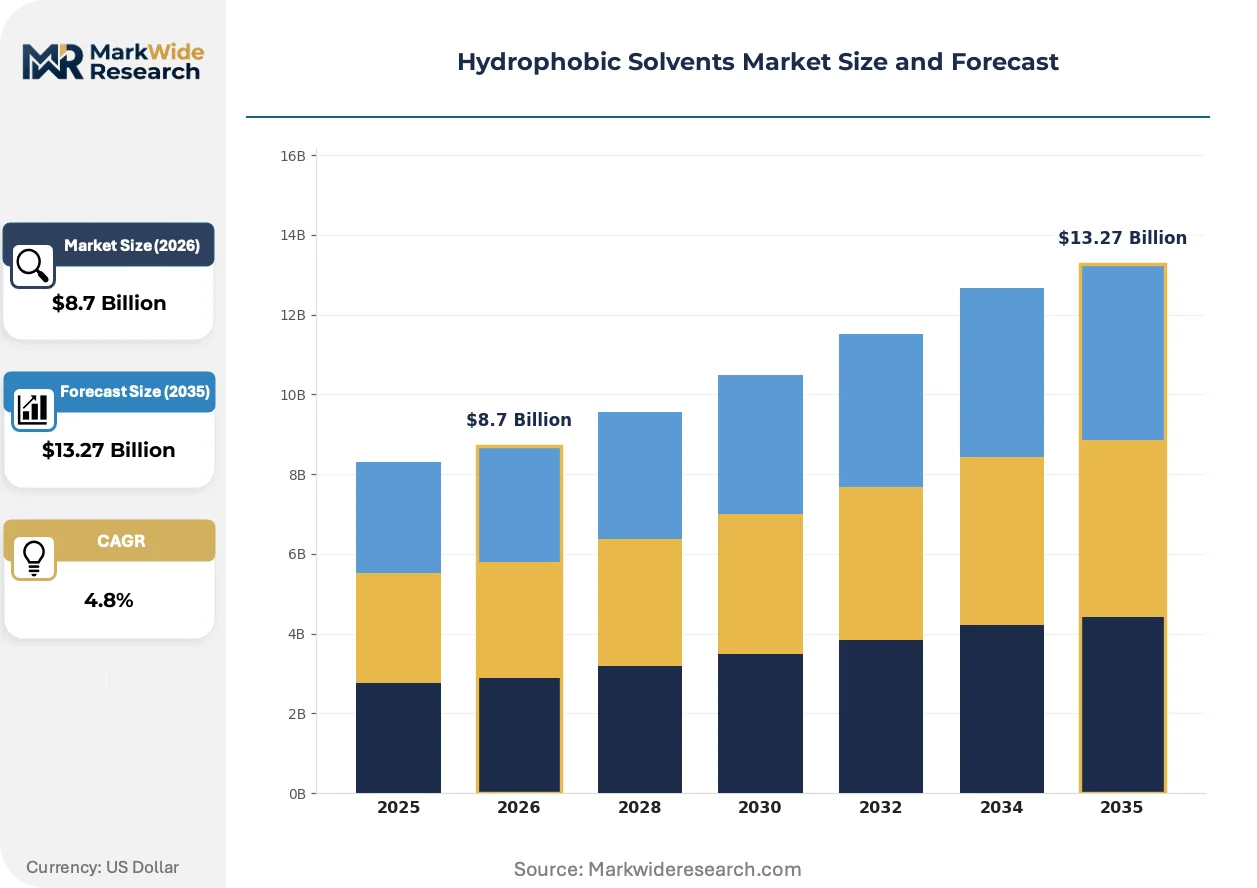
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohols, Ketones, Ethers, Hydrocarbons End Use Industry: Coatings, Adhesives, Pharmaceuticals, Agrochemicals Application: Paints, Cleaners, Extraction, Industrial Solvents Form: Liquid, Solid, Concentrate, Aqueous |
| Companies Covered | ExxonMobil Corporation, Shell plc, Phillips 66, SK Geocentric Co., Ltd., Calumet, Inc., BASF SE, Dow Inc., LyondellBasell Industries Holdings B.V., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophobic Solvents Market Evolving Landscape
Process analytical technology is digitizing quality assurance workflows across hydrophobic solvent production, while regulatory frameworks on both sides of the Atlantic tighten residual limits and workplace exposure thresholds. These forces are compressing specification tolerances and accelerating substitution cycles.
Inline near-infrared spectroscopy is digitizing real-time moisture and purity monitoring during fractional distillation operations. Specialty coatings plants in Germany and the United States are deploying these systems to certify incoming solvent lots against tightening EPA and EU REACH specifications. The technology is digitizing supplier-customer data exchange, compressing batch release timelines from days to hours.
EU REACH authorization requirements for Substances of Very High Concern are forcing reformulation of legacy paint strippers and industrial degreasers. The regulation is redirecting procurement toward lower-toxicity hydrocarbon grades and oxygenated solvent alternatives. Coatings manufacturers in France and Italy are accelerating qualification programs to lock in compliant supply chains before 2027 sunset dates.
Specification-driven procurement is consolidating buyer power among tier-one automotive OEMs and aerospace primes. These customers now mandate solvent certificates of analysis with every delivery, displacing spot-market purchasing. The shift is most visible in Germany, where BASF and Dow direct-account relationships dominate supply to Volkswagen and Airbus tier networks.
Hydrophobic Solvents Market Segmentation
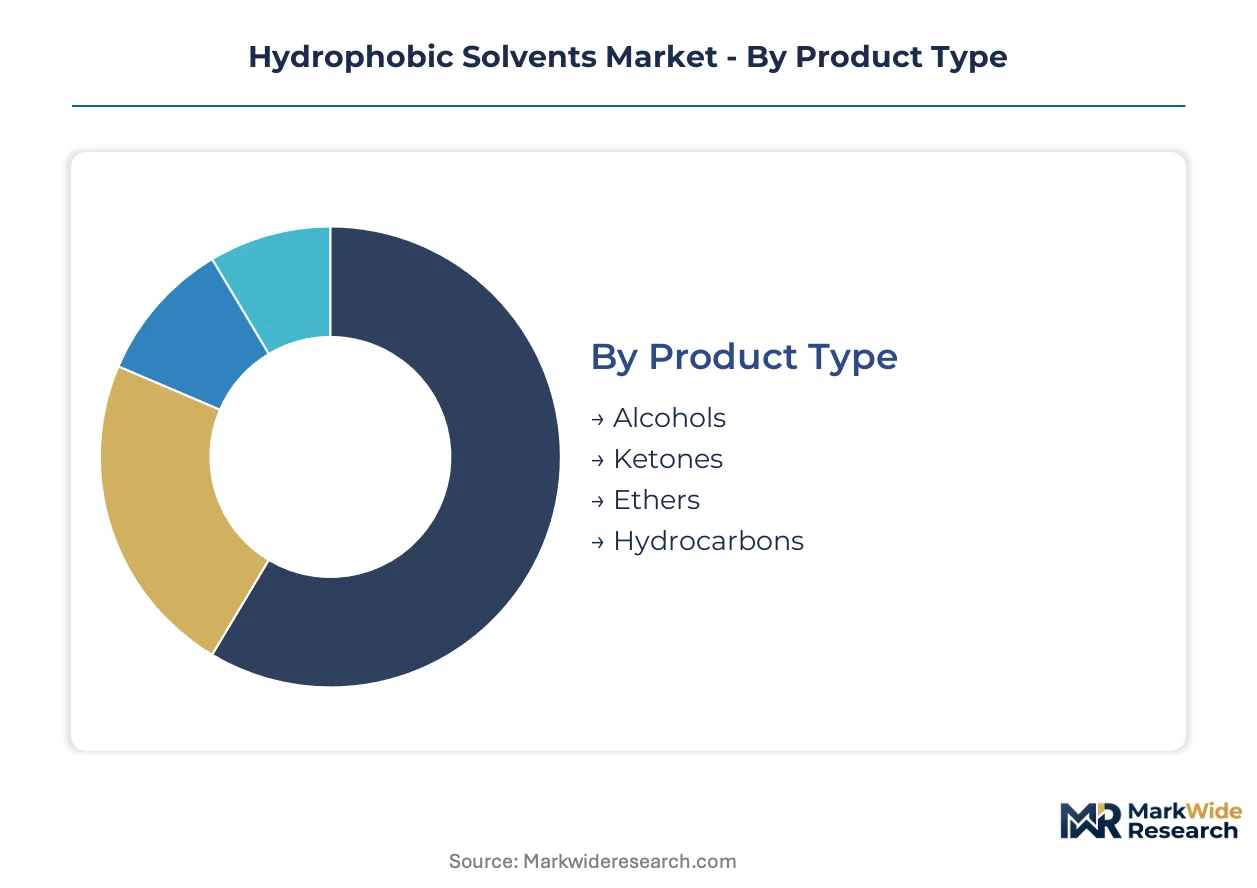
Hydrophobic solvent procurement patterns diverge sharply across product chemistry and end-use specifications, with coatings formulators and pharmaceutical extractors imposing incompatible purity thresholds. Understanding these segment boundaries clarifies where margin pools concentrate and where substitution risks threaten incumbent positions.
Product Type:
Mature hydrocarbon grades dominate volume throughput, while oxygenated alternatives carve out premium positioning through regulatory compliance advantages.
- Hydrocarbons:Petroleum-derived aliphatic and aromatic fractions serve as the workhorse carriers for industrial coatings and degreasing formulations. Demand concentrates most acutely in German automotive OEM supply chains, where BASF and Dow direct-account relationships lock in specification continuity despite REACH authorization pressures.
- Ketones:Acetone, methyl ethyl ketone, and methyl isobutyl ketone offer superior moisture tolerance and controlled evaporation profiles. Pharmaceutical manufacturers in the United States prize these grades for active pharmaceutical ingredient extraction under FDA residual solvent limits.
- Alcohols:Long-chain aliphatic alcohols provide intermediate polarity for specialty adhesive formulations.
- Ethers:Glycol ether variants command niche positions in high-performance coatings where flow control is critical.
Hydrocarbons retain volume leadership; ketones hold the steepest expansion curve.
End Use Industry:
Application-driven specification tiers separate commodity volume plays from value-capture opportunities in regulated environments.
- Coatings:Automotive and aerospace primers, topcoats, and specialty finishes consume the largest share of hydrocarbon-grade solvents. EPA NESHAP volatile organic compound limits are forcing rapid qualification of lower-aromatic alternatives in United States manufacturing plants.
- Pharmaceuticals:Extraction and crystallization processes demand ultra-low moisture ketone and ether grades with certificates of analysis for every lot. FDA oversight of Class 2 and Class 3 residual solvent thresholds creates specification premiums that sustain margin pools.
- Agrochemicals:Emulsifiable concentrate systems for crop protection chemistry represent the most rapidly climbing application as formulation shifts away from aqueous suspensions.
- Adhesives:Pressure-sensitive and structural bonding formulations rely on hydrocarbon carriers for tack control and open-time management.
Coatings anchors absolute demand; agrochemicals is expanding most quickly.
Application:
Functional role determines purity requirements and regulatory exposure, separating commodity cleaners from specification-critical extraction media.
- Extraction:Pharmaceutical and natural product isolation processes require solvent grades with documented purity profiles and traceability chains. FDA residual solvent limits and EU REACH registration requirements impose dual qualification burdens on suppliers serving multinational drug manufacturers.
- Paints:Architectural and industrial coating formulations prioritize cost efficiency and compatibility with legacy resin systems. German coatings plants are deploying inline near-infrared spectroscopy to certify incoming lots against tightening EU REACH specifications.
- Cleaners:Metal degreasing and precision cleaning applications face displacement pressure from aqueous alternatives where moisture tolerance permits.
- Industrial Solvents:General-purpose process media serve as reaction carriers and diluents across chemical manufacturing.
Paints maintains the broadest installed base; extraction commands the highest specification premiums.
Form:
Physical state and concentration level dictate logistics economics and customer working capital requirements across the value chain.
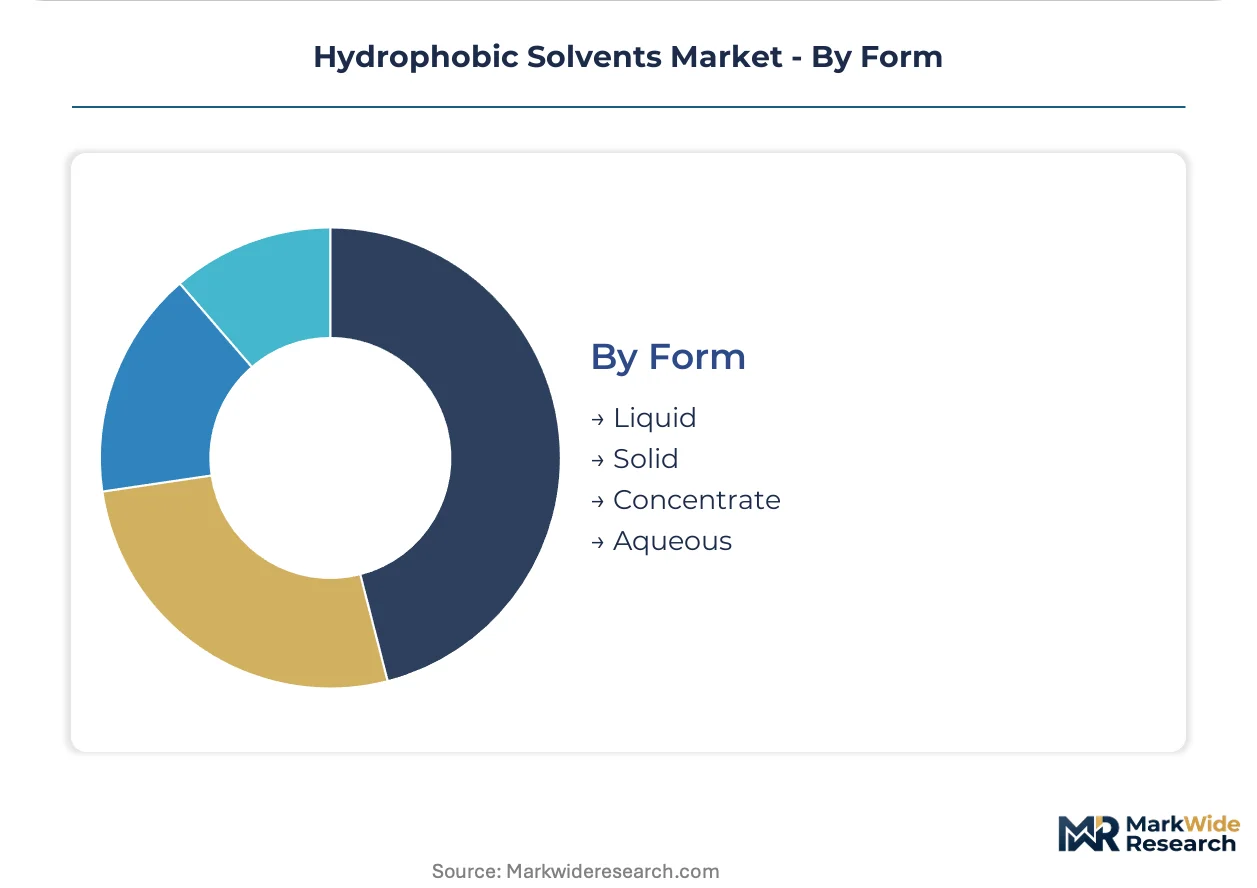
- Liquid:Bulk tanker and drum deliveries of neat solvents dominate commercial flow, enabling just-in-time supply to integrated coatings plants. The Ludwigshafen production cluster in Germany exemplifies this model, with pipeline connections reducing inventory burdens for downstream formulators.
- Concentrate:High-strength formulations for dilution at point of use reduce transport costs and packaging waste for high-volume consumers.
- Aqueous:Pre-emulsified or partially miscible blends bridge hydrophobic performance with reduced volatile organic compound emissions.
- Solid:Encapsulated or adsorbed solvent systems serve specialized delivery applications in controlled-release formulations.
Liquid form captures the dominant share of commercial volume; concentrate is gaining share fastest through sustainability-driven logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany exhibit the lowest price elasticity due to specification rigor in automotive coatings, while Indian agrochemical formulators remain acutely sensitive to landed cost fluctuations in import-grade ketone carriers.
Germany
Automotive OEM supply chains in Stuttgart and Munich drive specification-critical demand for high-purity hydrocarbon grades. EU REACH authorization timelines for Substances of Very High Concern are compelling formulators to pre-qualify alternative solvent systems before 2027 sunset dates. The Ludwigshafen chemical complex anchors continental European supply, with pipeline connections enabling just-in-time delivery to coatings plants across the Rhine-Neckar metropolitan region.
United States
Pharmaceutical extraction operations in New Jersey and North Carolina sustain premium demand for ultra-low moisture ketone grades under FDA residual solvent limits. EPA NESHAP hazardous air pollutant standards are forcing rapid substitution of legacy aromatic solvents in automotive refinishing applications. Gulf Coast fractional distillation capacity clusters around Houston and Port Arthur, exposing supply chains to hurricane disruption risks during peak storm seasons.
India
Domestic pesticide blenders in Maharashtra and Gujarat are accelerating procurement of hydrophobic carriers for emulsifiable concentrate formulations. CDSCO registration pathways for crop protection products are opening formal import channels for ketone and hydrocarbon grades previously sourced through informal mechanisms. The Mumbai-Pune industrial corridor is emerging as the primary formulation hub, with warehousing infrastructure expanding to accommodate just-in-time solvent inventories.
China
Coatings manufacturers in the Yangtze River Delta are absorbing displaced volume from aqueous cleaner substitution in metal finishing applications. NMPA oversight of pharmaceutical manufacturing is tightening documentation requirements for solvent traceability in active pharmaceutical ingredient production. The Shanghai chemical industry zone is consolidating fractional distillation capacity to capture economies of scale in hydrocarbon-grade output.
Japan
Specialty adhesive formulators in Osaka and Nagoya maintain steady demand for long-chain aliphatic alcohols with precise evaporation profiles. METI industrial chemical regulations are aligning domestic solvent classifications with emerging EU REACH substance categories. The Chubu region's petrochemical infrastructure is upgrading analytical capabilities to certify moisture content below 50 ppm for pharmaceutical-grade ketone exports.
Hydrophobic Solvents Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing catalytic reforming and fractional distillation assets; scale advantage sits with regional blenders serving formulation industries with lower specification thresholds. The market structures around three tiers: multinational energy majors with backward integration into naphtha feedstocks, European chemical conglomerates with REACH-registered product portfolios, and Asian petrochemical groups expanding ketone capacity for pharmaceutical extraction. Dominant competitive moves include geographic expansion into Indian agrochemical formulation and portfolio diversification toward solvent recovery services.
Within the integrated petrochemical tier, ExxonMobil Corporation and Shell plc represent archetypes of feedstock-advantaged producers with Gulf Coast and Rotterdam refining infrastructure. BASF SE anchors the European specialty tier through its Ludwigshafen complex, while Dow Inc. occupies a position spanning both commodity hydrocarbon and specification ketone segments. SK Geocentric Co., Ltd. exemplifies the Asian expansion vector, with Korean petrochemical infrastructure positioning for pharmaceutical-grade ketone export growth.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Phillips 66 |
| SK Geocentric Co., Ltd. |
| Calumet, Inc. |
| BASF SE |
| Dow Inc. |
| LyondellBasell Industries Holdings B.V. |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp pipeline corridor channels naphtha feedstock costs directly into German coatings plant procurement budgets, compressing margin buffers for formulators while enabling integrated producers to sustain price premiums through just-in-time delivery guarantees.
Pricing Analysis
Aftermarket solvent recovery services now capture lifetime value exceeding virgin product margins across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade ketones with FDA certificates of analysis from industrial hydrocarbon carriers. Cost compression in standard-grade hydrocarbons is intensifying because aqueous cleaner substitution erodes volume demand in metal finishing. Indian agrochemical blenders exhibit the highest price sensitivity due to import dependency, while German automotive OEM supply chains absorb premiums for REACH-registered specification continuity.
Supply Chain Analysis
Naphtha and reformate feedstock sourcing draws from integrated refining complexes clustered along the US Gulf Coast, Rotterdam-Antwerp corridor, and the Ludwigshafen chemical hub. Catalytic reforming capacity, fractional distillation towers, and REACH registration documentation form the critical input triad. Single-source vulnerability concentrates in hurricane-exposed Texas and Louisiana infrastructure. Distribution runs through direct-account relationships with tier-one coatings manufacturers, displacing spot-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional distillation expertise and REACH registration capabilities have consolidated among a narrowing cohort of integrated petrochemical majors, leaving mid-scale formulators dependent on external supply relationships.
For Market Incumbents: Pre-empt aqueous substitution threats in metal finishing by accelerating solvent recovery service deployment. Lock in Ludwigshafen pipeline access to defend just-in-time delivery advantages against Rotterdam-Antwerp competitors. Pursue backward integration into catalytic reforming capacity to insulate margin structures from naphtha price volatility. For New Entrants and Emerging Players: Pursue CDSCO-registered import channels serving Maharashtra and Gujarat pesticide blenders as the most penetrable demand pocket. Target pharmaceutical-grade ketone segments where FDA residual solvent limits sustain specification premiums unavailable to commodity hydrocarbon producers. Lead with analytical certification capabilities rather than volume scale to bypass incumbent logistics advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fractional distillation assets and dormant REACH registrations. Long-term viability hinges on regulatory compliance infrastructure rather than feedstock access alone. Watch for EU authorization timeline acceleration as the inflection signal for premium-grade demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Reforming | Captures naphtha margin and secures feedstock supply for German coatings customers. |
| Solvent Recovery Service Infrastructure | Converts single-transaction chemical sales into recurring revenue streams with higher retention. |
| REACH Registration Portfolio Expansion | Pre-qualifies alternative grades before sunset deadlines force customer reformulation. |
| CDSCO Import Channel Establishment | Opens formal supply pathways to Indian agrochemical blenders previously served informally. |
| Inline Analytical Technology Deployment | Compresses batch release timelines from days to hours for specification-critical coatings plants. |
Research Methodology
Cross-validation between primary interviews with plant managers at coatings facilities and secondary validation through customs trade data anchors the qualitative findings. Procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors at fractional distillation complexes provided operational perspective. SEC 10-K filings, Cefic solvent market reports, and EPA NESHAP regulatory filings supplied quantitative benchmarks. Bottom-up volume estimates triangulated against top-down value projections derived from feedstock consumption patterns.
Calibration against historical capacity utilization rates and REACH registration timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hydrocarbon versus oxygenated chemistry grades, coatings versus pharmaceutical versus agrochemical end-use industries, and liquid versus concentrate physical forms. CAGRs emerged from regression analysis of feedstock cost pass-through elasticity and specification premium persistence. Crude oil price volatility bands and EU authorization timeline scenarios provided scenario-specific forecast inputs.
Sensitivities concentrate around Brent crude benchmark fluctuations, hurricane disruption frequency in Gulf Coast infrastructure, and EU REACH Substances of Very High Concern list expansion. Forecasts reflect documented assumptions about feedstock cost pass-through rates and regulatory timeline adherence. Cross-checking against EIA petrochemical feedstock consumption data and Cefic solvent trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Solvent Evaporation Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Fluid Neutralizing Market
Solvents
Tetraethyl Benzene Market
Solvents
Global Solvent Dyes Market
Solvents
1, 1-Difluoroethane Market
Solvents
Chlorobenzene Market
Solvents
Solvent Cement Market
Solvents
Sugar Dissolvers Market
Solvents
Hydrocarbon Solvents Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Benzylamine Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
3-Butylene Glycol Market