
 Germany Engineering Plastics Market | 2026-2036
Germany Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Engineering Plastics Market Foresight
Bavaria's polymer compounding expansion is fragmenting the traditional supply map for high-performance resins. BASF SE leverages its Ludwigshafen Verbund site to sustain captive feedstock integration across polyamide chains. Covestro AG anchors polycarbonate supply into Munich-area automotive tier ones. LANXESS AG specializes in glass-filled compounds for under-the-hood thermal management.
Germany engineering plastics comprise thermoplastic polymers engineered to withstand mechanical stress, chemical exposure, and temperatures typically exceeding 150°C, produced via continuous polymerization or batch condensation with precise molecular weight control. These materials serve primarily as metal substitutes in precision components requiring dimensional stability under cyclic loading. Polyamide dominates volume flows into automotive underhood and powertrain applications where heat resistance commands premium positioning. Polycarbonate captures margin pools in optical-grade electrical insulation for Bavarian electronics fabricators. Thermoplastic elastomers represent the fastest-expanding product class as medical device OEMs in Tuttlingen specify soft-touch overmolding grades.
Germany's Federal Environment Agency enforces Packaging Act recyclability quotas that force reformulation of filled engineering grades for circular compatibility. REACH compliance through ECHA anchors substance restriction protocols affecting flame-retardant additive packages in electrical applications. KBA vehicle type-approval rules propagate through OEM supply chains, mandating crash-performance validation of polymer structural members. Stakeholders must monitor how EU Green Deal carbon-border adjustments reshape cost structures for imported base resins versus domestic polymerization.
Market Dynamics
Germany's engineering plastics sector confronts a structural squeeze between circular-economy mandates from the Federal Environment Agency and automotive OEMs' relentless lightweighting targets for powertrain components.
Growth Catalysts
- Packaging Act amendments:Recyclability quotas for technical thermoplastics are forcing compounders to redesign filled grades, opening specification windows for bio-based polyamides in Bavarian precision engineering corridors.
- Automotive lightweighting:Tier-one suppliers around Munich and Ingolstadt are expanding orders for glass-filled structural polymers to meet KBA crash-performance validation for polymer structural members.
- Thermal management demands:Under-the-hood applications require heat-resistant compounds, pulling specialty polyamide and PPS grades into EV battery housing and powertrain modules.
Market Restraints
- Caprolactam feedstock volatility:Polyamide 6 supply chains remain exposed to benzene derivative pricing swings, compressing margin predictability for compounders without captive petrochemical integration.
- REACH substance restrictions:ECHA protocols on halogenated flame retardants are eliminating incumbent additive packages, forcing costly reformulation cycles for electrical insulation grades.
- Metal substitution limits:High-load bearing applications in chassis and suspension systems retain steel and aluminum due to fatigue-performance gaps in fiber-reinforced thermoplastics.
Strategic Opportunities
- Medical device overmolding:Tuttlingen OEMs are specifying soft-touch TPE grades for surgical instrument handles, creating a premium niche outside automotive price pressure.
- Circular material-as-a-service:Closed-loop takeback programs for automotive production scrap offer margin recovery through recompounding, aligned with EU Green Deal carbon-border adjustment mechanisms.
- Optical-grade polycarbonate:Bavarian electronics fabricators are qualifying high-clarity grades for LED housings and display components, displacing acrylic in heat-critical applications.
Industry Challenges
- Compounder talent scarcity:Formulation chemistry expertise for multi-material recycling streams is concentrating at legacy Ludwigshafen and Leverkusen sites, constraining regional expansion.
- Validation timeline compression:KBA type-approval cycles for new polymer structural members now overlap with platform development windows, squeezing testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Engineering Plastics Market |
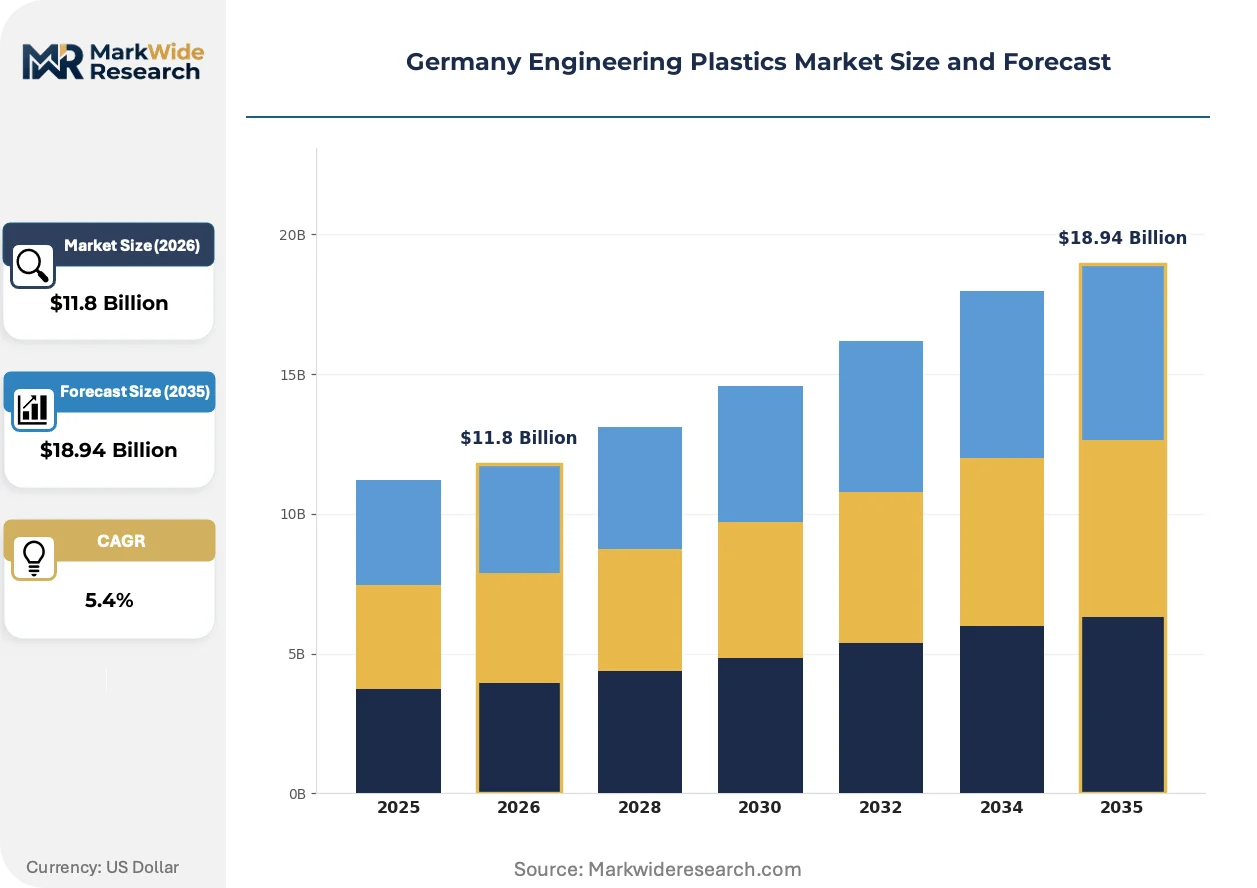
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polyoxymethylene, Thermoplastic Elastomers Application: Automotive Components, Electrical Insulation, Industrial Equipment, Consumer Goods End User: Aerospace, Electronics, Medical Devices, Packaging Manufacturing Stage: Injection Molding, 3D Printing, Extrusion, Blow Molding |
| Companies Covered | BASF SE, Covestro AG, Evonik Industries AG, LANXESS AG, Celanese Corporation, DuBay Polymer GmbH, BARLOG Plastics GmbH, Röchling Engineering Plastics SE & Co. KG, Equipolymers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Engineering Plastics Market Shifts & Advancements
Digital thread integration across polymerization and compounding operations is compressing specification-to-production cycles, while regulatory chemistry constraints and buyer consolidation reshape competitive positioning.
Real-time rheology monitoring via in-line spectroscopy is digitizing batch consistency control for high-performance polyamide chains. Automotive tier-one suppliers in Baden-Württemberg are mandating digital certificates of analysis for every lot, eliminating manual quality documentation. This digitizing of specification compliance is compressing supplier qualification timelines from months to weeks.
REACH authorization requirements for persistent organic pollutants are eliminating legacy brominated flame retardant systems from electrical housing applications. Compounders must validate phosphorus-nitrogen alternatives through ECHA's substitution roadmap, extending R&D cycles. Bavarian connector manufacturers are absorbing these compliance costs into long-term supply agreements to lock in qualified material streams.
Consolidated procurement desks at major automotive OEMs are unbundling material specification from molding process control, forcing compounders to assume downstream technical liability. Munich-area purchasing groups now demand total-cost-of-ownership modeling that incorporates scrap rates and energy consumption. This behavioral shift is most pronounced in EV platform launches where polymer selection directly impacts battery pack thermal runaway containment certification.
Germany Engineering Plastics Market Segmentation
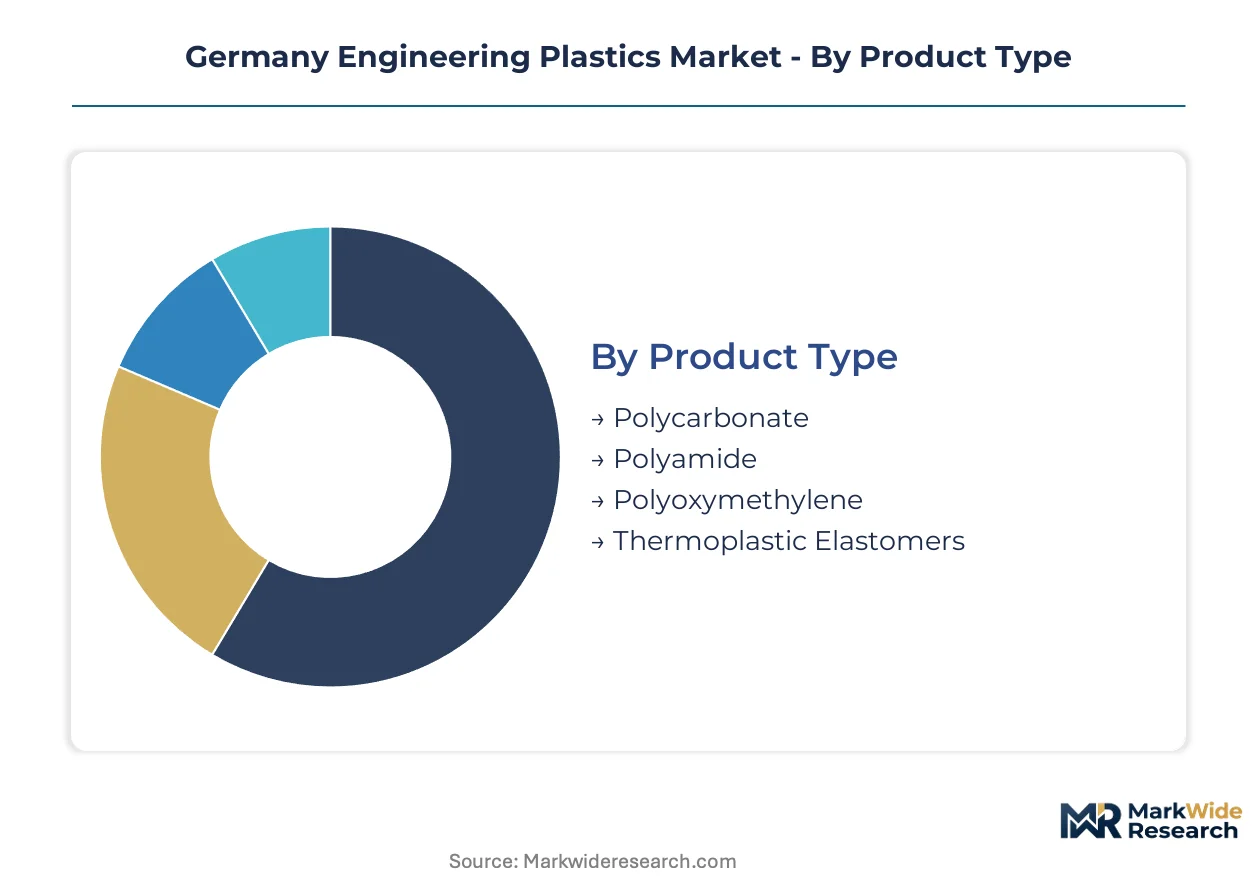
Engineering plastics in Germany fragment across technical specifications, processing methods, and end-use performance thresholds. Each segmentation axis reveals distinct margin structures and qualification barriers that compounders must navigate.
Product Type:
Material selection spans rigid structural polymers through flexible elastomeric systems, each commanding different specification intensity and captive supply relationships.
- Polyamide:Semi-crystalline polymers built from caprolactam or hexamethylenediamine precursors deliver thermal resistance above 150°C for under-the-hood automotive modules. Bavarian powertrain suppliers specify glass-filled grades for EV battery housings where KBA crash-validation applies.
- Polycarbonate:Amorphous thermoplastics with optical clarity and inherent flame resistance serve precision electronics fabricators around Munich. LED housing applications displace acrylic where heat dissipation requirements exceed 80°C continuous service.
- Polyoxymethylene:High-crystallinity acetal resins provide low-friction surfaces for precision gearing and conveyor systems in Baden-Württemberg industrial automation clusters.
- Thermoplastic Elastomers:Block copolymer structures combining rubber elasticity with thermoplastic processability enable soft-touch overmolding for Tuttlingen surgical instrument manufacturers.
Established volume favors polyamide; emerging adoption favors thermoplastic elastomers.
Application:
Demand concentrates where metal substitution delivers measurable weight reduction without sacrificing dimensional stability under cyclic mechanical stress.
- Automotive Components:Structural members, underhood thermal management modules, and interior trim systems absorb the majority of compounder capacity. Tier-one suppliers around Ingolstadt mandate lot-level digital certificates of analysis to compress qualification timelines.
- Electrical Insulation:Connector housings, relay bases, and circuit breaker components require flame-retardant formulations meeting ECHA substitution roadmaps for halogen-free systems.
- Industrial Equipment:Conveyor bearings, pump housings, and pneumatic cylinder bodies exploit wear resistance and chemical inertness in process industries.
- Consumer Goods:Power tool housings and appliance components prioritize cost-optimized formulations with adequate impact resistance for domestic appliance OEMs.
Specification intensity peaks in automotive; margin recovery concentrates in electrical insulation.
End User:
Buyer consolidation and regulatory exposure vary sharply across terminal markets, dictating contract structures and technical liability allocation.
- Electronics:Bavarian connector and LED manufacturers drive optical-grade polycarbonate demand with tight tolerance requirements for miniaturized components.
- Medical Devices:Tuttlingen surgical instrument clusters specify sterilization-resistant grades with biocompatibility documentation under EU MDR.
- Aerospace:Tier-two suppliers for cabin interiors and secondary structures require flame-smoke-toxicity certification beyond standard automotive protocols.
- Packaging:Technical thermoplastics for reusable industrial containers face Federal Environment Agency recyclability quotas under Packaging Act amendments.
Procurement consolidation dominates electronics; qualification barriers peak in medical devices.
Manufacturing Stage:
Processing technology selection determines scrap rates, energy intensity, and the feasibility of closed-loop material recovery.
- Injection Molding:High-pressure cavity filling enables complex geometries with tight dimensional tolerances for automotive structural members. Munich-area molders integrate real-time rheology monitoring to eliminate manual quality documentation.
- Extrusion:Continuous profile production serves cable insulation and pipe applications with lower per-part energy consumption than cyclic processes.
- 3D Printing:Fused filament fabrication and selective laser sintering of engineering-grade powders enable low-volume prototyping and spare part production for legacy industrial equipment.
- Blow Molding:Hollow part formation for fluid reservoirs and ducting leverages melt strength in polyamide and polycarbonate grades.
Process control digitization advances fastest in injection molding; additive adoption remains experimental for production volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caprolactam-based polymerization clusters concentrate along the Rhine-Neckar and Upper Bavaria industrial belts, with compounder capacity tracking automotive OEM assembly footprints. Federal Environment Agency regulations propagate through state-level environmental ministries, creating heterogeneous enforcement intensity across Germany's federal structure.
Bavaria
Precision engineering corridors around Munich and Ingolstadt absorb glass-filled polyamide grades for EV battery housings and powertrain modules. KBA crash-performance validation requirements compress supplier qualification timelines for tier-one automotive fabricators. Ingolstadt-based molders integrate real-time rheology monitoring to eliminate manual quality documentation.
Baden-Württemberg
Industrial automation clusters in Stuttgart and Mannheim specify low-friction acetal resins for precision gearing and conveyor systems. REACH authorization protocols through ECHA eliminate legacy brominated flame retardants from electrical housing applications. Tuttlingen surgical instrument manufacturers drive soft-touch TPE demand for sterilization-resistant overmolding grades.
North Rhine-Westphalia
Chemical production integration at Ludwigshafen and Leverkusen sites sustains captive feedstock control across polyamide and polycarbonate chains. Packaging Act recyclability quotas force reformulation of filled engineering grades for circular compatibility. Leverkusen-based compounders concentrate formulation chemistry expertise for multi-material recycling streams.
Hesse
Frankfurt-Rhine-Main logistics hubs distribute optical-grade polycarbonate to Bavarian electronics fabricators for LED housing applications. EU Green Deal carbon-border adjustment mechanisms reshape cost structures for imported base resins versus domestic polymerization. Darmstadt-area research institutes anchor materials characterization protocols for medical device biocompatibility documentation.
Germany Engineering Plastics Market Competitive Landscape
Integrated petrochemical conglomerates and specialized compounders split the market along feedstock control and formulation agility fault lines. BASF SE and Covestro AG anchor the consolidated tier through Verbund-site integration and polycarbonate supply dominance respectively. LANXESS AG occupies the specialty-compounder position with glass-filled thermal management grades. Competitive moves concentrate on captive feedstock security and circular-material service model development.
Within the integrated-chemicals archetype, BASF SE and Covestro AG exemplify scale-driven positioning through Rhine-Neckar production clustering. LANXESS AG represents the specialty-compounder tier focused on application-specific formulation. Evonik Industries AG sits within the high-performance materials segment with additive and specialty resin capabilities. Celanese Corporation anchors multinational polymer technology transfer into German automotive supply chains.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Evonik Industries AG |
| LANXESS AG |
| Celanese Corporation |
| DuBay Polymer GmbH |
| BARLOG Plastics GmbH |
| Röchling Engineering Plastics SE & Co. KG |
| Equipolymers |
| Others |
Supply & Pricing Matrix
Caprolactam polymerization capacity clusters along the Rhine-Neckar corridor anchor margin pools downstream in Bavarian automotive compounding. This feedstock concentration grants integrated producers pricing leverage over non-captive compounders serving Munich-area tier-one suppliers.
Pricing Analysis
REACH authorization protocols through ECHA dictate the pricing tier structure for flame-retardant engineering grades. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant halogen-free formulations from legacy brominated systems and commodity unfilled grades. Cost compression in standard-tier polyamide compounds is intensifying because benzene derivative volatility transmits directly from caprolactam producers. Electronics fabricators exhibit lowest price sensitivity due to qualification lock-in, while packaging converters face acute margin pressure from Federal Environment Agency recyclability mandates.
Supply Chain Analysis
Benzene and caprolactam feedstocks draw from Belgian and Dutch petrochemical complexes, with adipic acid for polyamide 66 chains sourcing from German and French producers. Key dependencies include caprolactam monomer, glass fiber reinforcement from Luxembourg and Belgium, and phosphorus-based flame retardants from Chinese suppliers. Single-source vulnerability concentrates in optical-grade polycarbonate precursors where Covestro's Leverkusen site dominates European supply. Distribution runs through Ludwigshafen and Munich hub-and-spoke networks to Baden-Württemberg molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's engineering plastics market functions as a defensive-moat sector where regulatory entrenchment through REACH and KBA validation creates prohibitive switching costs for qualified suppliers.
For Market Incumbents: Harden captive feedstock positions through backward integration into caprolactam or long-term offtake agreements with Rhine-Neckar polymerization sites. Expand compounding capacity in Ingolstadt corridor to compress logistics costs for Munich-area automotive tier ones. ECHA's phasedown of halogenated flame retardants threatens incumbent additive packages; accelerate phosphorus-nitrogen formulation R&D to maintain specification leadership.
For New Entrants and Emerging Players: Pursue medical device overmolding niches in Tuttlingen where EU MDR biocompatibility documentation creates qualification barriers favoring agile specialists. Target thermoplastic elastomer grades for surgical instrument handles, a segment isolated from automotive pricing pressure. Establish direct technical service relationships with midsize OEMs bypassing consolidated procurement desks at major automotive groups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compounders holding KBA-validated automotive grades but lacking feedstock integration. Long-term viability hinges on circular-material service model development aligned with EU Green Deal carbon-border mechanisms. Watch for inflection in automotive platform standardization decisions that consolidate polymer specifications across EV battery housing programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive feedstock control insulates margin from benzene derivative volatility at Ludwigshafen-scale sites. |
| Circular Material-as-a-Service Launch | Closed-loop takeback programs recover automotive production scrap through recompounding aligned with Packaging Act mandates. |
| Halogen-Free Formulation Investment | ECHA substitution roadmap compliance secures electrical insulation qualification for Bavarian connector manufacturers. |
| Real-Time Rheology Monitoring Deployment | In-line spectroscopy eliminates manual quality documentation for Ingolstadt molders under KBA validation timelines. |
| TPE Medical Grade Qualification | Soft-touch overmolding certification for Tuttlingen surgical instruments opens premium niche outside automotive price pressure. |
Research Methodology
Desk research of customs trade data, Cefic polymer production statistics, and KBA vehicle type-approval filings preceded structured interviews with compounder plant managers, automotive tier-one procurement leads, Bavarian electronics fabricator technical directors, and medical device OEM quality managers. Primary fieldwork validated secondary estimates through bottom-up capacity surveys and top-down demand reconciliation across end-use segments.
Assumptions held fixed include REACH authorization timelines, EU Green Deal carbon-border implementation scope, and KBA crash-performance validation protocols; variables included automotive platform launch schedules and caprolactam feedstock pricing trajectories. The analytical framework modeled volume and value across product type, application, end user, and manufacturing stage dimensions throughout the forecast period. CAGRs derived from segmented growth rate reconciliation against macroeconomic drivers and industry-specific capacity expansion announcements.
Sensitivities concentrate around ECHA substance restriction acceleration, automotive OEM platform consolidation decisions, and benzene derivative price volatility transmission. Cross-checking against Cefic polymer consumption statistics and federal environment ministry enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
PEKK Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
APAC Polyethylene Terephthalate Market