
 Poly Propylene Glycol Market | 2026-2036
Poly Propylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Propylene Glycol Market Intelligence
Technical service contracts for custom polyol blending and on-site formulation support is shifting how value gets captured in polypropylene glycol supply relationships. BASF leverages its Ludwigshafen integrated site to sustain captive propylene oxide feedstock economics. Dow anchors North American flexible foam supply through its Freeport, Texas, propylene oxide derivatives complex. Mitsui Chemical differentiates in Asia-Pacific with specialized low-monol PPG grades for high-resilience automotive seating.
Polypropylene glycol comprises propylene oxide oligomers with molecular weights spanning 400 to 4,000 g/mol, manufactured via base-catalyzed or double-metal-cyanide catalyzed ring-opening polymerization of propylene oxide, functioning primarily as polyol building blocks for polyurethane synthesis and as surfactant intermediates. Liquid PPG dominates volume throughput due to its handling efficiency in continuous polyurethane slabstock and molded foam operations, while gel and foam formulations command premium positioning in wound-care and thermal insulation applications where viscosity control and cell structure precision determine performance. Cosmetic and pharmaceutical applications represent the fastest-expanding demand channel as formulators replace petroleum-derived emollients with PPG-based alternatives that meet stricter dermal safety thresholds.
EPA New Chemicals Program reviews govern PPG derivative introductions in US industrial applications, while REACH registration obligations under ECHA mandate full toxicological dossiers for polyol imports into European Union member states. China's SAMR enforces GB standards for polyurethane raw materials used in domestic appliance and construction end products. Stakeholders must track evolving per- and polyfluoroalkyl substance restrictions that could displace certain PPG co-surfactants in textile processing and food-contact applications.
Market Dynamics
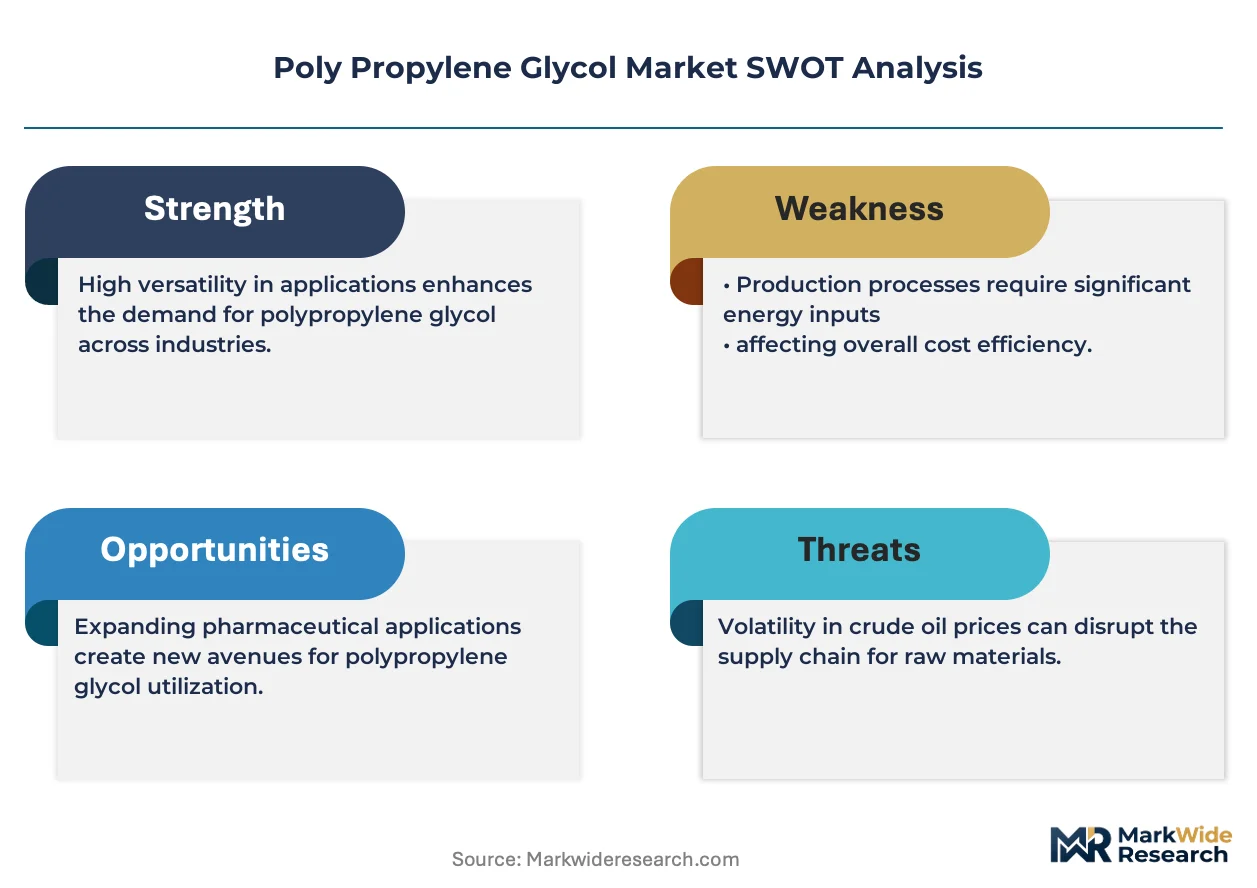
Propylene oxide feedstock concentration among integrated petrochemical complexes is redistributing margin capture toward upstream operators, forcing downstream polyol blenders to defend position through formulation service contracts and technical support bundling.
Growth Catalysts
- REACH chemical registration:European ECHA mandates for full toxicological dossiers are redirecting formulation chemistry toward lower-emission catalyst systems, expanding demand for specialized PPG grades.
- Building insulation standards:Tightened thermal performance codes in residential and commercial construction are accelerating polyurethane foam procurement for spray-applied and boardstock insulation systems.
- Automotive seating clusters:Concentrated flexible foam production in China, Germany, and the United States sustains steady polyol offtake from tier-one seating suppliers.
Market Restraints
- Propylene oxide supply concentration:Captive production economics at Ludwigshafen and Freeport create dependency on a narrow supplier base for merchant market participants.
- PFAS restriction trajectory:Evolving per- and polyfluoroalkyl substance limits under EPA New Chemicals Program and state-level analogs threaten displacement of PPG co-surfactants in textile processing.
- Base-catalyzed process limitations:Molecular weight distribution control constraints in conventional alkoxylation limit high-performance grade yields relative to double-metal-cyanide alternatives.
Strategic Opportunities
- China dual carbon goals:SAMR enforcement of GB standards for polyurethane raw materials creates preference for low-emission polyol formulations in domestic appliance manufacturing.
- Cosmetic emollient substitution:Formulators replacing petroleum-derived alternatives with PPG-based compounds that meet stricter dermal safety thresholds represent an expanding demand channel.
- Double-metal-cyanide catalyst convergence:Advanced catalysis combining narrow polydispersity with reduced monol content enables penetration into high-resilience automotive seating specifications.
Industry Challenges
- Alkoxylation operator certification:Specialized reactor handling and pressure vessel qualifications create recruitment friction for continuous process facilities.
- REACH dossier compilation timelines:Extended toxicological study requirements delay market entry for novel PPG derivative formulations in European Union member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Propylene Glycol Market |
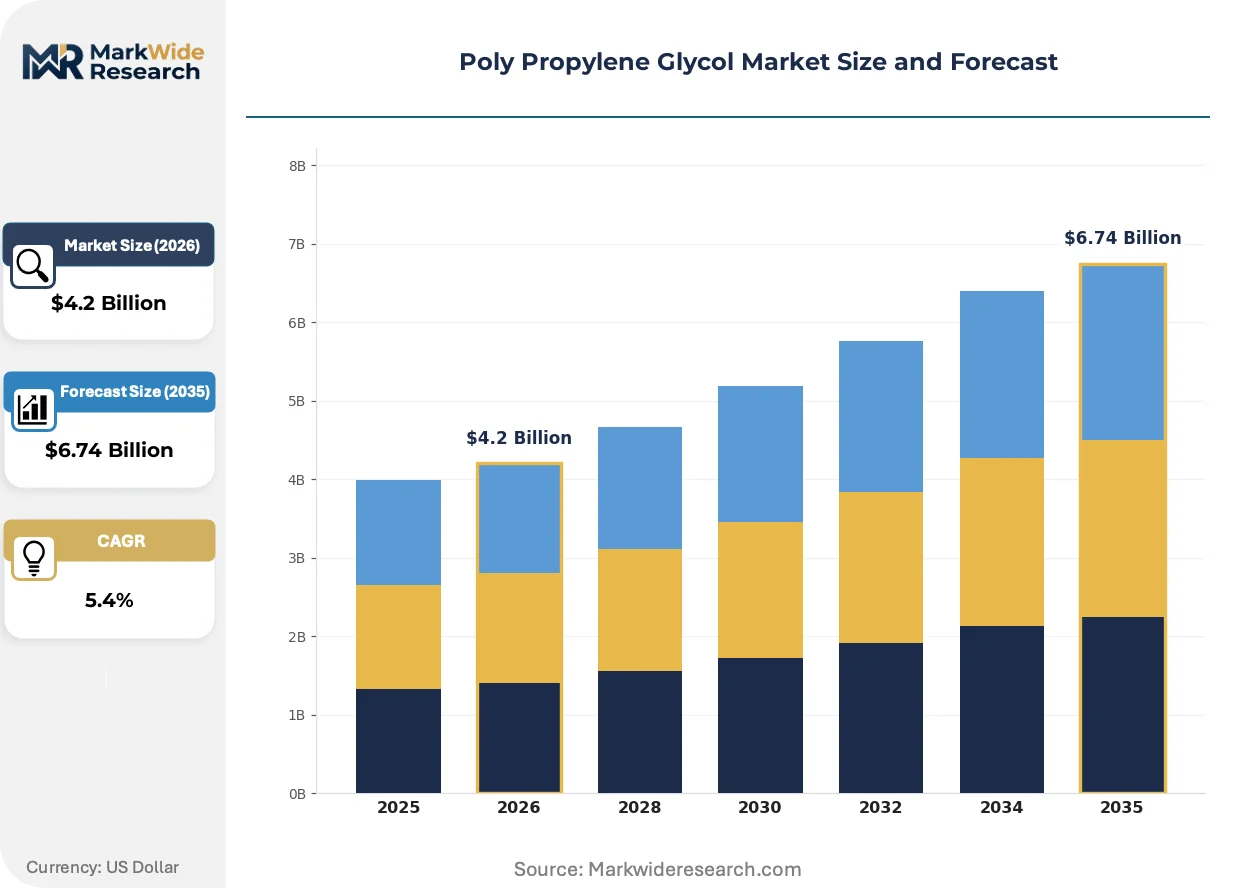
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.74 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid, Solid, Gel, Foam Application: Cosmetics, Pharmaceuticals, Food, Textile End User: Manufacturers, Suppliers, Distributors, Retailers Packaging Type: Bottles, Drums, Bags, Totes |
| Companies Covered | KKPC, BASF, Dow, AGC, Covestro, Ineos, Sanyo Chemical, Mitsui Chemical, Jiangsu Haian Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Propylene Glycol Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward catalyst systems that compress emission profiles while maintaining reactivity windows, with technical service contracts emerging as the primary mechanism for value capture differentiation.
Double-metal-cyanide catalyzed ring-opening polymerization is rewriting molecular architecture possibilities for propylene oxide oligomers. Tier-one automotive seating manufacturers are adopting low-monol PPG grades at accelerating rates for high-resilience foam specifications. This catalytic advance is compressing the performance gap between commodity polyols and specialty grades, enabling broader substitution in molded foam operations.
REACH registration obligations under ECHA now mandate full substance dossiers including persistent, bioaccumulative, and toxic assessments for polyol imports. Industrial consequence includes extended pre-market testing timelines and elevated compliance expenditures for non-integrated suppliers. Flexible foam compounders in Germany and neighboring member states are responding by consolidating supplier relationships toward pre-registered integrated producers.
Technical service contracts bundling custom polyol blending with on-site formulation support are displacing transactional procurement in large-volume polyurethane operations. Molded foam and slabstock producers are substituting spot purchasing with multi-year supply agreements incorporating joint development clauses. This pattern concentrates in North American automotive seating clusters where just-in-time delivery requirements favor embedded technical support.
Poly Propylene Glycol Market Segmentation
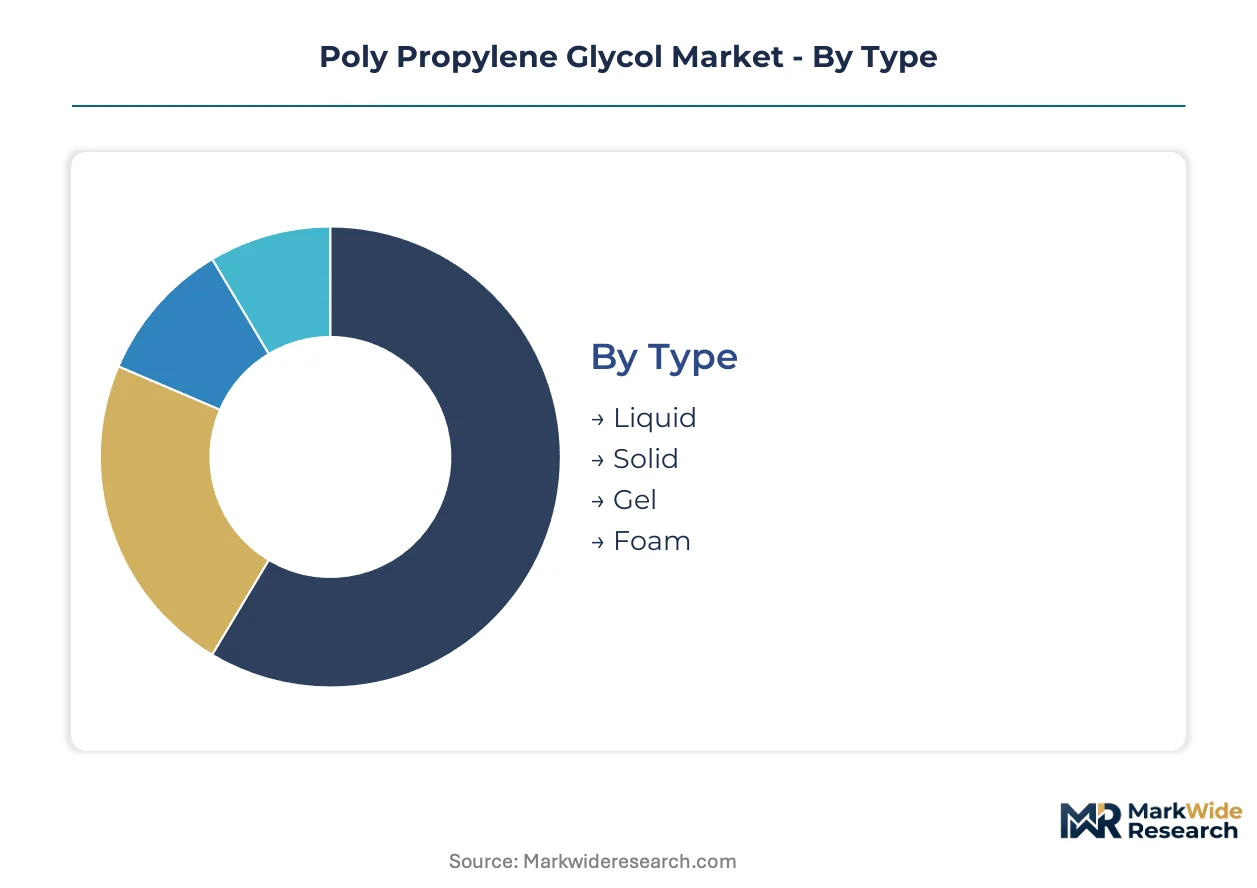
Polypropylene glycol procurement decisions pivot on handling characteristics for continuous foam operations, viscosity specifications for cosmetic formulations, and regulatory compliance thresholds across pharmaceutical applications. Buyers prioritize supply security and technical service bundling over commodity pricing in concentrated automotive and construction channels.
Type:
Material handling efficiency in automated polyurethane production lines drives format selection more than unit cost differentials.
- Liquid:Propylene oxide oligomers in fluid form enable continuous dosing in slabstock and molded foam operations without pre-melting infrastructure. Demand concentrates in automotive seating clusters across Germany, China, and the United States where just-in-time delivery requirements favor pumpable feedstocks.
- Solid:Crystalline or waxy PPG grades suit batch cosmetic compounding and pharmaceutical tablet binding where precise weight measurement outweighs throughput speed. Formulators in personal care applications favor solid formats for reduced shipping volumes and extended shelf stability.
- Gel:Semi-solid consistencies serve wound-care dressings and topical drug delivery matrices requiring controlled release kinetics.
- Foam:Pre-expanded cellular structures command premium positioning in thermal insulation and medical cushioning where cell structure precision determines performance.
Volume sits with Liquid; growth tilts toward Gel.
Application:
End-use regulatory exposure shapes formulation chemistry choices and supplier qualification requirements.
- Cosmetics:PPG-based emollients replace petroleum-derived alternatives as formulators respond to stricter dermal safety thresholds under FDA and EU Cosmetics Regulation frameworks. This segment is expanding most quickly as clean-label positioning drives ingredient substitution in skincare and haircare.
- Pharmaceuticals:Excipient-grade PPG must meet USP-NF monograph specifications for oral and parenteral drug delivery systems, creating qualification barriers for non-GMP suppliers.
- Food:Limited direct food-contact approvals restrict PPG use to processing aids and equipment lubricants rather than intentional additives.
- Textile:Spin finishes and fabric softeners employ PPG co-surfactants, though evolving PFAS restrictions threaten displacement in fiber processing applications.
Cosmetics captures the steepest expansion trajectory; Pharmaceuticals anchors value concentration.
End User:
Supply chain position determines technical service intensity and contract structure preferences.
- Manufacturers:Integrated polyurethane foam producers and cosmetic compounders source bulk PPG under multi-year technical service agreements bundling custom blending with on-site formulation support.
- Suppliers:Merchant polyol distributors serve mid-volume processors lacking alkoxylation infrastructure or REACH registration capabilities.
- Distributors:Regional chemical handlers manage inventory for smaller compounders in fragmented construction and appliance segments.
- Retailers:Direct-to-consumer channels remain minimal, limited to specialty cosmetic ingredient suppliers and laboratory chemical vendors.
Manufacturers dominate offtake; Distributors show the fastest contract volume growth.
Packaging Type:
Shipment scale and handling automation compatibility shape container selection in procurement specifications.
- Bottles:Laboratory and pilot-scale cosmetic formulators purchase sub-liter quantities for R&D and small-batch production.
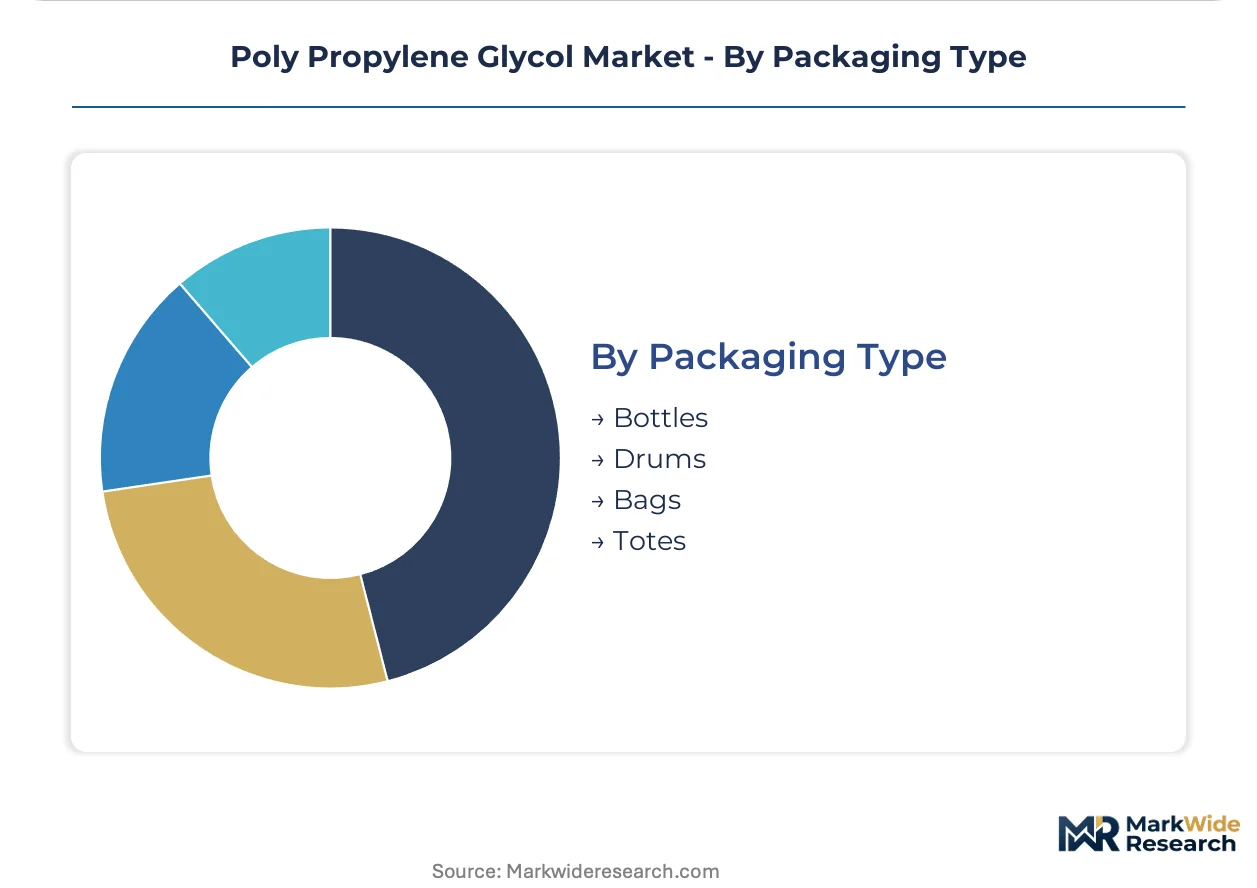
- Drums:Standard 200-liter steel drums serve mid-volume polyurethane processors and pharmaceutical compounders with moderate throughput requirements.
- Bags:Flexible intermediate bulk containers reduce return logistics for solid PPG grades in construction adhesive applications.
- Totes:Intermediate bulk containers with integrated heating elements enable liquid PPG handling in seasonal climates without drum decanting infrastructure.
Drums maintain volume leadership; Totes gain share fastest in automotive cluster supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in integrated petrochemical corridors while consumption disperses across automotive clusters and construction zones. China consumes the largest volumes for flexible foam and appliance insulation. Germany and the United States anchor polyurethane formulation demand through tier-one automotive seating supply chains.
China
SAMR enforcement of GB standards for polyurethane raw materials accelerates procurement of low-emission polyol formulations. The country's dual carbon goals redirect investment toward catalyst systems with compressed emission profiles. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces process bulk PPG volumes for domestic appliance and automotive seating exports.
Germany
REACH registration obligations under ECHA mandate full toxicological dossiers for polyol imports, extending qualification timelines for non-integrated suppliers. Ludwigshafen operates as the dominant integrated production site with captive propylene oxide feedstock economics. Automotive seating compounders in Baden-Württemberg and Lower Saxony consolidate supplier relationships toward pre-registered producers with embedded technical service capabilities.
United States
EPA New Chemicals Program reviews govern PPG derivative introductions in industrial applications, creating pre-market testing requirements for novel formulations. Freeport, Texas anchors North American flexible foam supply through propylene oxide derivatives complexes. Southeast automotive assembly corridors in Tennessee and Kentucky sustain steady polyol offtake from just-in-time seating suppliers.
Japan
METI industrial standards shape procurement specifications for high-resilience automotive seating grades with narrow polydispersity requirements. Osaka-based chemical specialists differentiate through low-monol PPG production for premium foam specifications. Kansai region manufacturing clusters supply tier-one seating manufacturers with specialized polyol blends meeting JIS quality benchmarks.
South Korea
MFDS pharmaceutical regulations establish qualification barriers for excipient-grade PPG used in oral and parenteral drug delivery systems. Seoul Capital Area cosmetic formulators replace petroleum-derived emollients with PPG-based alternatives meeting stricter dermal safety thresholds. Busan-Ulsan petrochemical corridors process propylene oxide feedstocks for regional polyurethane foam and surfactant intermediate production.
Poly Propylene Glycol Market Key Industry Players
Capital-heavy producers compete with asset-light formulators across distinct value capture zones. Integrated petrochemical complexes with captive propylene oxide supply dominate upstream margin capture, while downstream blenders defend position through technical service bundling and custom formulation contracts. The competitive terrain separates into three archetypes: integrated multinational chemical conglomerates, regional polyol specialists with alkoxylation assets, and formulation service providers lacking captive feedstock. Capacity expansion at existing integrated sites and multi-year technical service agreements represent the dominant competitive moves reshaping supply relationships.
Among integrated multinational chemical conglomerates, BASF SE and Dow occupy positions exemplifying upstream control combined with downstream formulation reach. Covestro AG represents the specialized polyurethane systems house archetype, bridging polyol production with end-use application development. Mitsui Chemicals, Ltd. anchors the Asia-Pacific specialist tier, with its company name indicating Japanese origin and chemical industry positioning. Jiangsu Haian Petrochemical occupies a regional producer role within China's Yangtze River Delta manufacturing corridor. These named entities collectively illustrate how geographic concentration of propylene oxide assets and regulatory pre-registration status determine competitive positioning across the three major demand regions.
| Leading Market Players |
|---|
| KKPC |
| BASF |
| Dow |
| AGC |
| Covestro |
| Ineos |
| Sanyo Chemical |
| Mitsui Chemical |
| Jiangsu Haian Petrochemical |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals gate qualified supply access and premium-tier pricing power, filtering polyol producers through low-emission catalyst compliance while concentrating margin capture among pre-certified integrated operators serving automotive seating and construction insulation channels.
Pricing Analysis
Margin tightening in standard-grade polyols reflects propylene oxide feedstock concentration at Ludwigshafen and Freeport, where captive production economics compress merchant market participation. Three-tier pricing structure across high-purity low-monol, standard flexible foam, and commodity industrial grades tracks molecular weight precision and REACH pre-registration status. Cost compression accelerates in textile processing segments as PFAS restriction trajectories threaten PPG co-surfactant displacement. Automotive seating compounders show lowest price sensitivity due to just-in-time technical service bundling, while construction adhesive blenders exhibit highest spot-market responsiveness.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker shipments and heated tote container logistics shape procurement specifications for seasonal climate operations across Germany, China, and the United States. Raw material supply rests on propylene oxide monomer, double-metal-cyanide catalyst systems, and specialized alkoxylation reactor infrastructure concentrated in Yangtze River Delta and Gulf Coast petrochemical corridors. Single-source vulnerability from propylene oxide supply concentration at integrated complexes creates qualification barriers for non-captive blenders. Distribution runs through multi-year technical service agreements bundling custom polyol blending with embedded formulation support at automotive cluster locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polypropylene glycol sector sits in a catalysis-transition phase, with double-metal-cyanide systems displacing legacy base-catalyzed alkoxylation for narrow polydispersity automotive grades.
For Market Incumbents: Hedge against propylene oxide supply concentration risk by securing alternative feedstock arrangements through joint development clauses in technical service contracts. BASF and Dow anchor positions through Ludwigshafen and Freeport captive economics; regional blenders must defend margin position through formulation IP rather than commodity scale. Capacity addition in Asia-Pacific automotive clusters offers geographic diversification against REACH dossier compilation delays. For New Entrants and Emerging Players: Low-monol PPG technology-first wedge opens penetration paths into high-resilience automotive seating specifications where Mitsui Chemical currently differentiates. White-space concentrates in cosmetic emollient substitution channels where petroleum-derived ingredient replacement accelerates under FDA and EU Cosmetics Regulation thresholds. Go-to-market through specialized wound-care gel formulations bypasses polyurethane foam incumbent concentration. For Investors and Strategic Acquirers: REACH registration completion timelines extending beyond standard qualification windows is the leading indicator that pre-registered integrated producers will consolidate supply relationships toward embedded technical service bundling. Long-term viability favors asset-light formulators with alkoxylation assets and established automotive OEM qualification over pure merchant traders. Signal to monitor: automotive seating compounders consolidating supplier panels to sub-three-source structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock economics at Ludwigshafen and Freeport lock in margin capture against merchant volatility. |
| Double-Metal-Cyanide Catalyst Conversion | Narrow polydispersity production enables premium positioning in high-resilience automotive seating specifications. |
| REACH Pre-Registration Investment | ECHA toxicological dossier completion secures European market access ahead of extended qualification timelines. |
| Technical Service Contract Expansion | Embedded formulation support at automotive clusters displaces transactional procurement in just-in-time operations. |
| Cosmetic Emollient Channel Development | PPG-based alternatives capture substitution demand from petroleum-derived ingredients under tightening dermal safety thresholds. |
Research Approach
Document review covered customs and trade flow databases, SEC 10-K filings, ECHA registration dossiers, and industry association technical reports, complemented by interviews with polyurethane foam plant managers, automotive seating procurement leads, cosmetic formulator R&D directors, and regional chemical distribution channel partners. Primary fieldwork across China, Germany, and the United States validated secondary data through bottom-up capacity assessments and top-down demand triangulation.
Cross-referencing historical alkoxylation capacity expansion patterns against expert panel input on catalyst transition timelines shaped the analytical framework across the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from propylene oxide derivative demand elasticity, automotive production cluster forecasts, and construction insulation code adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene oxide supply disruption or accelerated PFAS restriction enforcement scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Global Polyethylene Glycol Market