
 EVA Foam Market | 2026-2036
EVA Foam Market Size, Share, and Industry Trends Forecast 2026-2036
EVA Foam Market Foresight
The gap between conventional foam molding and advanced extrusion techniques is narrowing as manufacturers pursue tighter cell structures and lighter weights. Zotefoams leverages nitrogen expansion technology to produce ultra-low density grades for medical and aerospace segments. Trocellen anchors European supply through vertically integrated slabstock and roll operations across Italy and Germany. Armacell competes in technical insulation by combining EVA cores with specialized facings for HVAC and refrigeration systems.
Ethylene-vinyl acetate foam consists of a closed-cell copolymer structure with vinyl acetate content typically ranging from 5% to 40%, manufactured through compression molding, extrusion, or autoclave expansion processes that yield controlled density and resilience. The material serves primarily as a lightweight cushioning, thermal insulation, and impact absorption medium across consumer goods and industrial applications. Crosslinked EVA commands premium positioning in athletic footwear midsoles where energy return specifications drive material selection. Low density grades dominate volume in packaging and consumer goods where cost efficiency outweighs performance thresholds. Specialty grade formulations are capturing margin pools in medical device cushioning and automotive interior applications where certification barriers limit supplier entry.
REACH in Europe and GB standards under SAMR in China govern volatile organic compound emissions and restricted substance limits in foam production, compelling reformulation investments among compounders and fabricators. The US EPA and California Air Resources Board impose additional testing protocols for indoor air quality applications, filtering market access for uncertified imports. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualify alternative chemistries before compliance deadlines tighten.
Market Dynamics
Footwear brands are compressing product development cycles to capture energy return specifications, forcing compounders to qualify crosslinked grades faster than historical certification timelines allow.
Growth Catalysts
- REACH threshold tightening:European ECHA mandates on volatile organic compound emissions are accelerating reformulation investments, opening qualification slots for compliant compounders ahead of 2027 enforcement windows.
- Midsole cushioning specifications:Athletic footwear OEMs are embedding EVA into premium energy return platforms, pulling material volumes into performance tier supply chains.
- Nitrogen expansion processes:Ultra-low density production methods are unlocking medical device and aerospace cushioning applications previously reserved for higher-cost foams.
Market Restraints
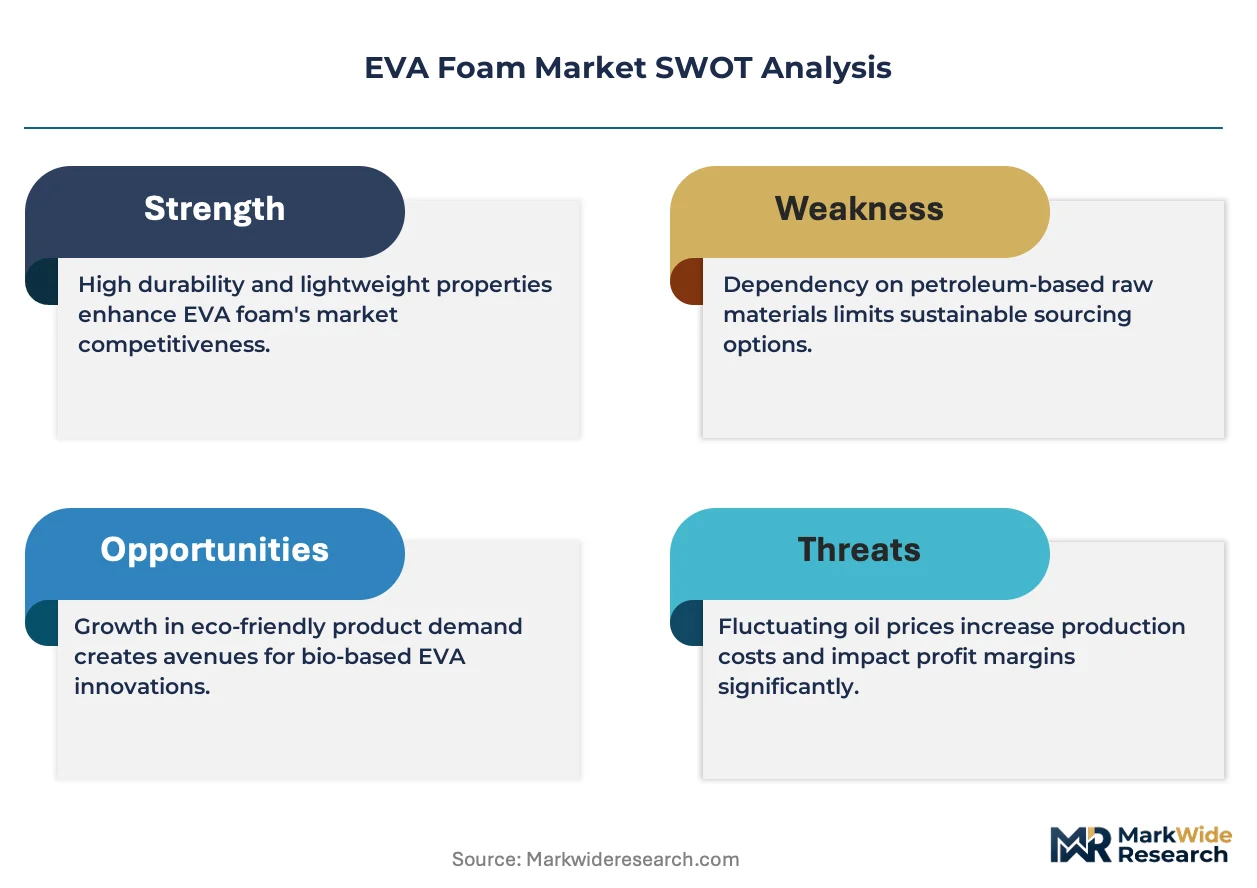
- Ethylene feedstock volatility:Crude-linked ethylene pricing swings compress margin predictability for slabstock producers operating on quarterly contract structures.
- Crosslinked grade supply concentration:Domestic Chinese production capacity expansion is capturing volume share, constraining export opportunities for European and North American compounders.
- Polyurethane substitution in thermal insulation:Polyisocyanurate foams with higher R-values are displacing EVA in cold chain packaging specifications.
Strategic Opportunities
- Automotive interior certification:OEMs are qualifying low-emission foam grades for headliner and pillar trim applications, creating margin pools behind VDA 278 and SAE J3077 test protocols.
- Direct-to-fabricator digital channels:Specialty distributors are bypassing traditional regional distributors to serve medical device manufacturers with cut-to-shape EVA components.
- GB standard alignment:SAMR harmonization with international volatile organic compound test methods is reducing dual-certification burdens for exporters targeting Chinese medical packaging segments.
Industry Challenges
- Cell structure engineering talent:Nitrogen expansion process optimization requires polymer scientists with autoclave operation experience, a skill set concentrated among legacy aerospace foam producers.
- Legacy compression molding asset stranding:Fabricators with sunk capital in conventional slabstock equipment face retrofit costs to achieve density tolerances demanded by medical device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EVA Foam Market |
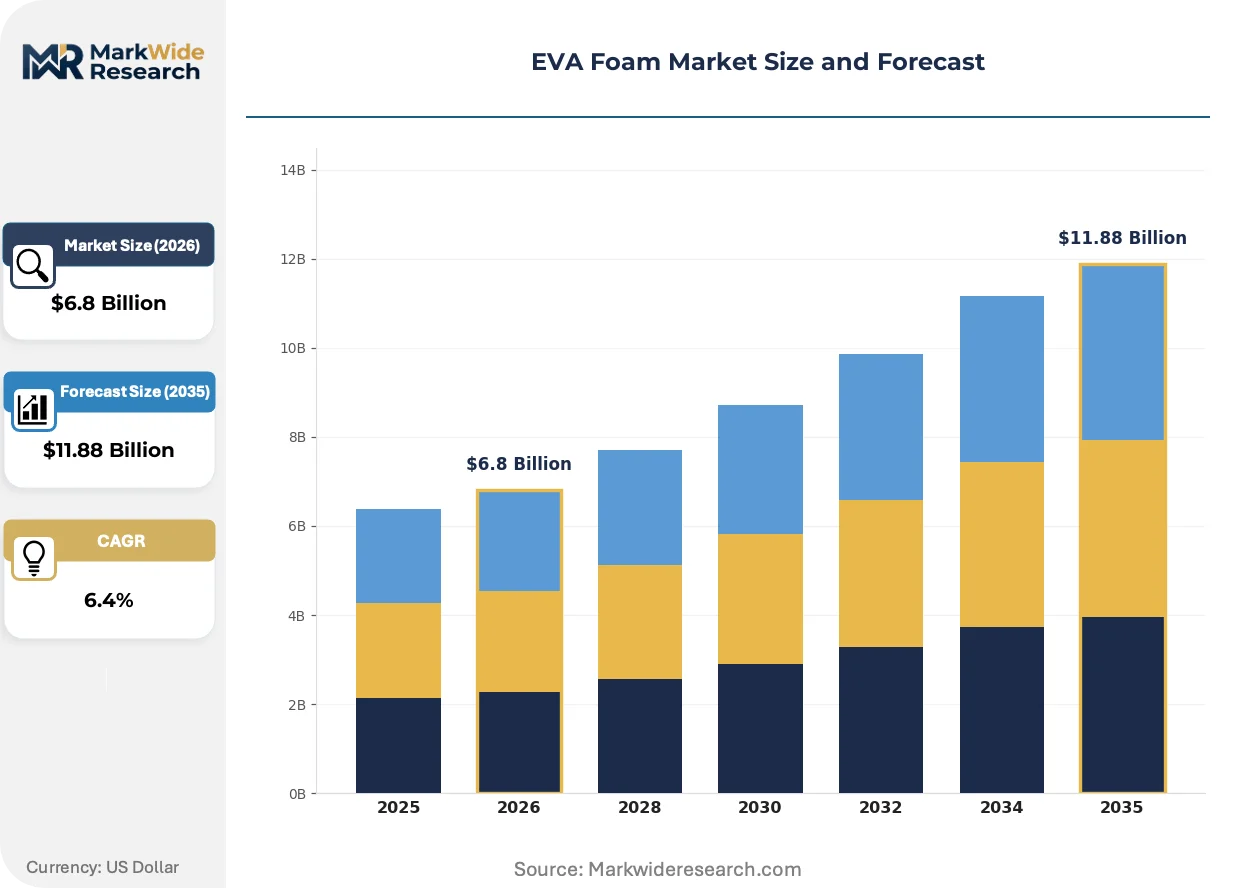
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-crosslinked EVA, Crosslinked EVA, Foam Sheets, Extruded Foam Application: Shoe Manufacturing, Sports Equipment, Insulation, Packaging End User: Manufacturers, Retailers, Distributors, OEMs Grade: Low Density, Medium Density, High Density, Specialty Grade |
| Companies Covered | Primacel, Trocellen, Ultralon Foam, Fujian Sansd Plastic, Chi Meng, Zotefoams, Foam Creations, Sansd (Jiangsu) Environmental Tech, Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EVA Foam Market Shifts & Advancements
Process intensification and regulatory chemistry shifts are compressing the performance gap between commodity and specialty grades, redrawing competitive boundaries across end-use verticals.
Supercritical nitrogen expansion technology is rendering obsolete conventional chemical blowing agent methods in medical cushioning applications. Device manufacturers are qualifying autoclave-expanded grades for surgical positioning pads and orthotic inserts. The shift is compressing supplier margins in standard density segments while creating captive demand for certified cleanroom production lines.
EPA testing protocols under the Toxic Substances Control Act are expanding formaldehyde emission screening to foam components in indoor air quality applications. Furniture and bedding OEMs are demanding third-party certification to California Air Resources Board standards as a condition of supplier qualification. The burden falls heaviest on import-dependent fabricators lacking in-house emissions testing infrastructure.
Specification-driven procurement is consolidating buyer power among athletic footwear brands with dedicated materials engineering teams. Smaller footwear OEMs are losing access to premium crosslinked grades as compounders prioritize volume commitments from strategic accounts. The concentration is most visible in China where domestic brands with captive compounding relationships are securing allocation priority over export-focused traders.
EVA Foam Market Segmentation
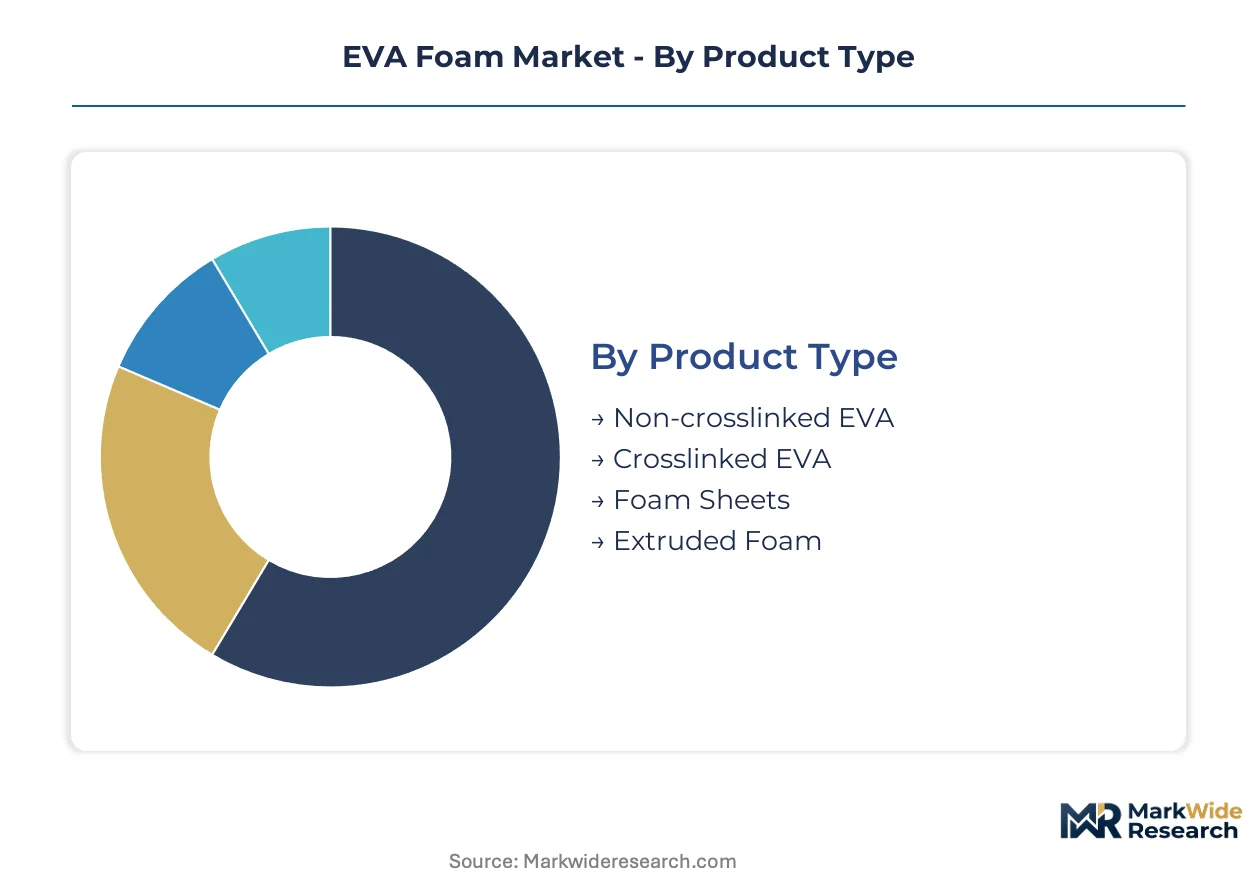
EVA foam segmentation reflects divergent technical requirements across cushioning, insulation, and protective packaging applications. Material density, crosslinking degree, and cell structure precision determine supplier qualification barriers and margin capture potential in each vertical.
Product Type:
The use-case spectrum spans commodity slabstock for general cushioning to precision-expanded grades for medical and aerospace specifications where nitrogen autoclave processes command premium positioning.
- Crosslinked EVA:Irradiated or peroxide-crosslinked copolymer structures deliver superior compression set resistance and energy return. Athletic footwear OEMs in China and Vietnam specify crosslinked grades for performance midsole platforms, pulling compounder capacity toward certified production lines.
- Non-crosslinked EVA:Thermoplastic copolymers processed through conventional compression molding offer lower cost and faster cycle times. Packaging fabricators in Germany and Italy concentrate procurement here for disposable protective inserts where resilience specifications remain modest.
- Foam Sheets:Slabstock and roll formats serve lamination and die-cutting operations across automotive interior and consumer goods sectors.
- Extruded Foam:Continuous profile production yields consistent cell structures for weathersealing and gasketing applications in construction and transportation.
The dominant share belongs to Non-crosslinked EVA, while Crosslinked EVA is closing the gap fastest.
Application:
Volume concentration tracks divergent performance thresholds, with footwear demanding energy return optimization and insulation requiring thermal resistance certification.
- Shoe Manufacturing:Midsole cushioning specifications from Nike, Adidas, and domestic Chinese brands drive crosslinked grade qualification. Energy return testing protocols now filter supplier access to premium tier supply chains.
- Sports Equipment:Protective padding for helmets, mats, and guards utilizes medium-density formulations. Certification to ASTM F355 impact standards governs material selection for North American and European team sports equipment.
- Insulation:HVAC and refrigeration systems specify EVA cores with specialized facings. Polyisocyanurate substitution pressure is strongest in cold chain packaging where R-value benchmarks dominate procurement.
- Packaging:Low-density grades dominate electronics and consumer goods protective applications. Cost efficiency outweighs performance thresholds, concentrating supply among high-volume Chinese slabstock producers.
Shoe Manufacturing commands the largest volume position, though Insulation faces the steepest competitive pressure from alternative foam chemistries.
End User:
Procurement authority concentrates differently across direct manufacturing consumption versus distribution-mediated supply chains.
- OEMs:Direct material qualification by automotive and medical device manufacturers imposes certification burdens that filter supplier pools. VDA 278 and SAE J3077 protocols govern automotive interior foam selection.
- Manufacturers:Fabricators with in-house cutting and laminating operations source slabstock for conversion to finished components. REACH compliance documentation requirements are tightening qualification standards.
- Distributors:Regional stock-and-serve operations bridge compounders to smaller fabricators lacking direct supplier relationships.
- Retailers:Private label brands and aftermarket channels procure finished foam goods through indirect supply chains with limited technical specification input.
OEMs exercise the tightest specification control, while Manufacturers represent the broadest addressable base.
Grade:
Density stratification aligns with performance tier pricing, from commodity packaging grades to certified cleanroom production for medical applications.
- Specialty Grade:Ultra-low density nitrogen-expanded foams for surgical positioning pads and orthotic inserts. Autoclave operation expertise concentrates among legacy aerospace foam producers in the US and UK.
- Low Density:Commodity grades for packaging and consumer goods where cost efficiency dominates procurement decisions. Chinese domestic production capacity expansion is capturing volume share.
- Medium Density:General cushioning applications across sports equipment and automotive trim where balanced compression and resilience specifications apply.
- High Density:Structural and load-bearing applications requiring dimensional stability under sustained mechanical stress.
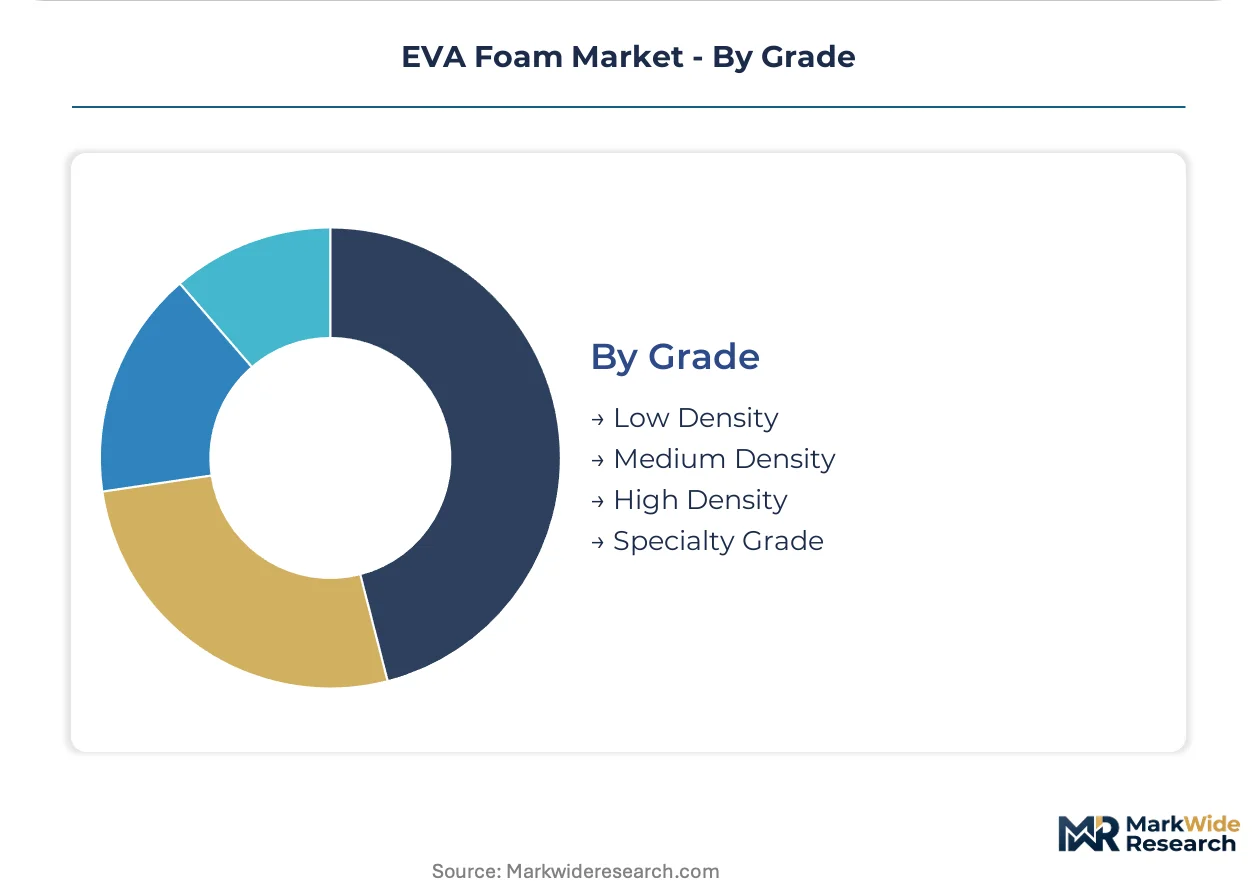
Low Density holds the volume lead, though Specialty Grade is expanding most quickly as medical device OEMs qualify cleanroom production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese slabstock producers export crosslinked grades to Vietnam and Indonesia where footwear OEMs operate midsole fabrication lines. European compounders ship specialty nitrogen-expanded foams to US medical device clusters under EPA-certified cleanroom protocols.
China
Domestic footwear brands like Anta and Li-Ning specify crosslinked EVA for energy return platforms, pulling compounder capacity toward certified production. SAMR enforces GB standards on volatile organic compound emissions that align with international test methods. The Yangtze River Delta hosts expanding autoclave operations serving medical packaging exporters.
United States
Medical device OEMs in Minneapolis and Boston qualify ultra-low density grades for surgical positioning pads. EPA testing protocols under the Toxic Substances Control Act govern formaldehyde emission screening for indoor air quality applications. Zotefoams anchors nitrogen expansion expertise from its Kentucky operations serving aerospace cushioning contracts.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify low-emission foam grades for headliner applications under VDA 278 protocols. ECHA REACH mandates on chemical content thresholds compel reformulation investments ahead of 2027 enforcement windows. Trocellen operates vertically integrated slabstock and roll production across Italy and Germany for HVAC insulation facings.
Vietnam
Nike and Adidas contract manufacturers compress product development cycles to capture energy return specifications from Chinese compounders. The country's national standards body works toward harmonization with international volatile organic compound test methods. Ho Chi Minh City industrial zones concentrate die-cutting and lamination operations for export-bound footwear components.
Japan
Automotive interior suppliers in the Nagoya and Osaka regions qualify medium-density grades for pillar trim under SAE J3077 protocols. METI oversees chemical substance management aligning with REACH principles for export market access. Kyushu hosts specialty fabricators serving orthotic insert demand from an aging demographic.
EVA Foam Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three identifiable tiers. Integrated compounders with captive resin supply command pricing power in crosslinked grade segments. Regional fabricators with sunk compression molding assets face retrofit costs to meet medical device density tolerances. Strategic moves concentrate on autoclave capacity expansion and direct-to-fabricator digital channel development.
Within the nitrogen expansion specialist tier, Zotefoams and Trocellen exemplify divergent geographic anchoring strategies. Zotefoams occupies a position tied to US aerospace and medical certification requirements. Trocellen represents European vertical integration into slabstock and roll formats. Among Chinese compounders, Fujian Sansd Plastic and Chi Meng sit within the domestic capacity expansion wave capturing footwear midsole volumes.
| Leading Market Players |
|---|
| Primacel |
| Trocellen |
| Ultralon Foam |
| Fujian Sansd Plastic |
| Chi Meng |
| Zotefoams |
| Foam Creations |
| Sansd (Jiangsu) Environmental Tech |
| Armacell |
| Others |
Supply & Pricing Matrix
Chinese autoclave overcapacity in crosslinked grades is compressing spot pricing for slabstock exports while simultaneously accelerating supplier qualification timelines for footwear compounders seeking volume commitments. This utilization dynamic rewards integrated producers with captive ethylene supply and strains margin structures for European fabricators dependent on merchant resin purchases.
Pricing Analysis
Cost-plus contracts indexed to ICIS ethylene benchmarks dominate procurement between compounders and footwear OEMs, with quarterly adjustments passing through feedstock volatility. Three-tier pricing structure across premium crosslinked, standard medium-density, and economy packaging grades reflects certification burden and cell structure precision. Cost compression in low-density segments is intensifying because Chinese domestic capacity expansion outpaces Vietnam and Indonesia demand absorption. Packaging fabricators exhibit highest price sensitivity, while medical device OEMs prioritize cleanroom certification over unit cost.
Supply Chain Analysis
Extended payment terms reaching 90 days from Nike and Adidas contract manufacturers are forcing Chinese compounders to utilize supply-chain finance facilities anchored in Shenzhen and Hong Kong banking networks. Manufacturing concentrates in China, Vietnam, and Germany, with raw material sourcing drawing from Saudi ethylene crackers, South Korean VAM suppliers, and German peroxide initiator producers. Single-source vulnerability pervades nitrogen expansion equipment, where autoclave fabrication rests on two US and UK specialists. Distribution runs through regional slabstock distributors in Italy and North Carolina serving die-cutting fabricators without direct compounder relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for density optimization and cut-to-shape programming are expanding faster than commodity slabstock sales, creating recurring-revenue pools that compounders can capture through embedded engineering support.
For Market Incumbents: Insulate crosslinked grade margins by securing captive ethylene supply through backward integration into Yangtze River Delta steam cracker networks, while accelerating REACH-compliant reformulation ahead of ECHA enforcement windows. Polyisocyanurate substitution in cold chain packaging represents the most acute substitution threat requiring defensive certification investment in HVAC-facing product lines. For New Entrants and Emerging Players: Mid-tier automotive interior fabricators in Eastern Europe represent the most penetrable entry point, as these manufacturers lack direct relationships with nitrogen expansion specialists and face VDA 278 compliance gaps. Orthotic insert demand from Japan's aging demographic offers secondary white-space with lower certification barriers than surgical positioning pads. A cut-to-shape digital channel bypassing traditional distributors provides the cleanest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among nitrogen expansion specialists with multi-year aerospace cushioning contracts and attached technical service agreements. Five-to-ten year viability favors compounders with demonstrated autoclave operation expertise and medical device qualification track records. The signal to watch is footwear OEM consolidation of supplier panels, which would trigger acquisition premiums for remaining independent crosslinked grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Zotefoams and Trocellen are adding nitrogen expansion lines to capture medical device and aerospace certification premiums. |
| REACH-Compliant Reformulation | European compounders must reformulate blowing agent chemistries ahead of ECHA volatile organic compound threshold tightening. |
| Direct-to-Fabricator Digital Channel | Specialty distributors are bypassing regional stock-and-serve operations to serve medical device manufacturers with precision-cut components. |
| Backward Integration into Ethylene Supply | Chinese producers are securing captive feedstock through Yangtze River Delta cracker joint ventures to compress slabstock costs. |
| Automotive Interior Certification Investment | Compounders are qualifying low-emission grades under VDA 278 and SAE J3077 protocols for headliner and pillar trim supply. |
Research Methodology
Cross-validation between primary interviews with foam compounders, footwear procurement directors, and medical device materials engineers and secondary sources including customs trade data, ECHA regulatory filings, and SEC 10-K disclosures anchors the qualitative findings. Bottom-up triangulation against top-down ethylene demand modeling validates volume estimates. Primary fieldwork encompassed plant managers at nitrogen expansion facilities, distribution channel partners in Italy and Germany, and technical R&D directors at crosslinked grade specialists.
Calibration against historical capacity utilization rates and ethylene price elasticity informs the projection framework across the analysis window. Segmentation dimensions modeled include crosslinking degree, density tier, end-use vertical, and regional production hub. CAGRs derive from regression analysis of ethylene feedstock cost pass-through rates and footwear OEM volume commitment patterns. Industry-specific inputs encompass autoclave capacity expansion timelines and REACH compliance cost curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, European natural gas pricing, and Chinese export tax policy would shift the trajectory. Forecasts reflect documented assumptions regarding ethylene supply elasticity and footwear brand consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Global Water-Based Resins Market