
 Global Polyamide Market | 2026-2036
Global Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyamide Market Outlook
Aftermarket service revenue for engineering-grade stock shapes is narrowing as original equipment manufacturers tighten specifications and shift volume to compounders with certified recycling streams. BASF SE leverages its integrated caprolactam chain in Europe to sustain margin capture from captive raw material supply. Ascend Performance Materials anchors its position through backward integration into adiponitrile, while Arkema differentiates via specialty PA11 derived from castor oil chemistry.
Polyamides are thermoplastic polymers characterized by repeating amide linkages along the backbone, with PA6 and PA66 representing the dominant commercial grades distinguished by six-carbon versus dual-six-carbon monomer structures and melting points ranging from 220°C to 265°C. These materials serve primarily as metal replacements in load-bearing components requiring fatigue resistance, chemical stability, and dimensional precision under thermal stress. Among product types, PA66 commands the largest volume pool in automotive under-hood applications where heat aging resistance is non-negotiable, while PA6 dominates textile fiber and film extrusion on cost efficiency. The high-performance grade segment captures disproportionate margin in electronics and medical tubing where dimensional stability under continuous service temperature defines qualification.
REACH registration requirements in Europe, EPA emissions standards for lightweighting in the United States, and China's GB standards for automotive material recyclability collectively elevate compliance costs and favor suppliers with certified life-cycle documentation. The EU Green Deal and associated carbon border adjustments are reshaping sourcing decisions for European automotive OEMs and their Tier-1 suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
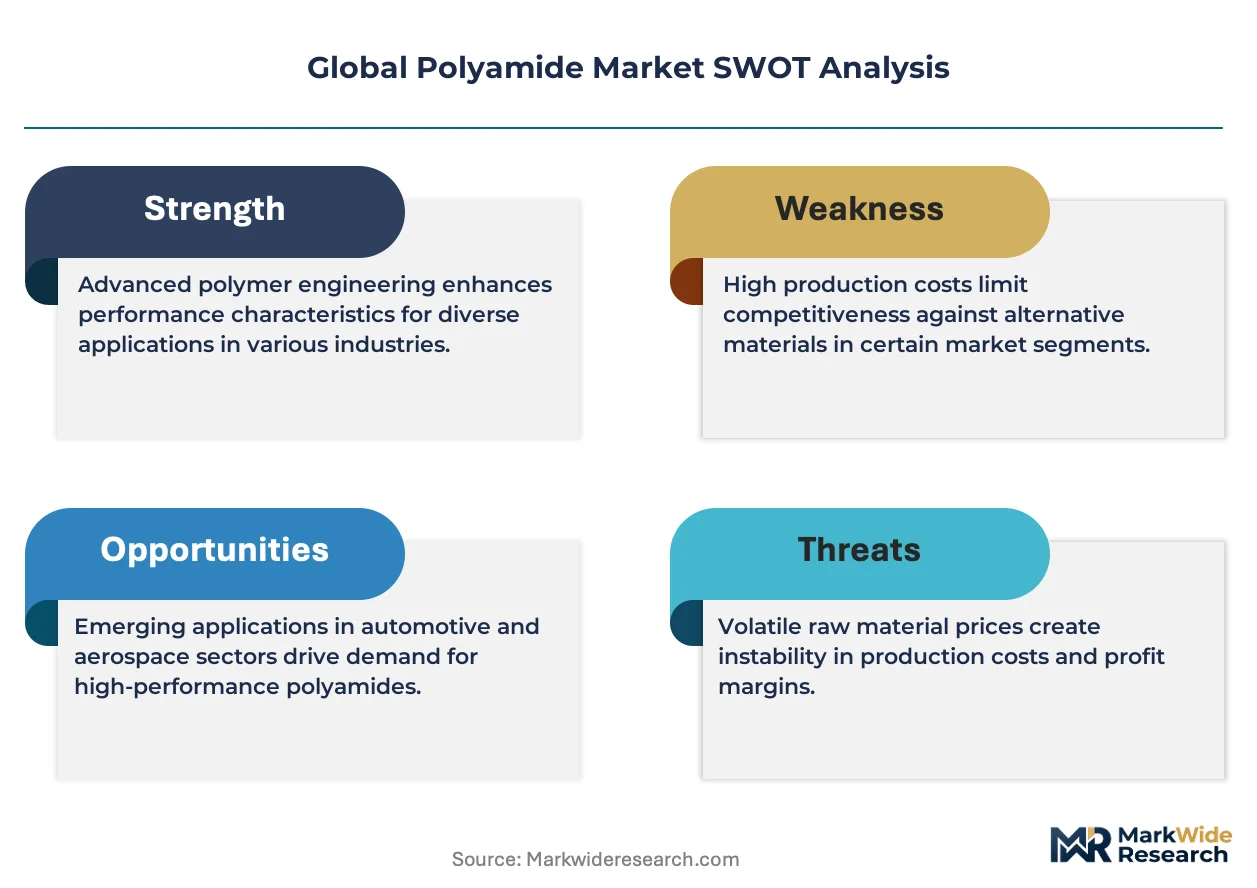
Automotive electrification is compressing qualification timelines for heat-stabilized grades while REACH and EU Green Deal mandates force recyclability certification into procurement specifications, creating divergence between suppliers with verified circular streams and commodity producers.
Growth Catalysts
- Automotive Electrification:Battery thermal management systems require PA66 grades with continuous service temperatures above 150°C, pulling volume from metal housings and coolant lines into polymer substitution.
- EU Green Deal Carbon Border Adjustments:European automotive OEMs now require life-cycle documentation for imported compounds, advantaging European producers with integrated caprolactam chains and certified recycling streams.
- Adiponitrile Supply Diversification:New capacity additions in China and the United States are reducing historical dependence on single-source supply chains for PA66 precursor chemicals.
Market Restraints
- Caprolactam Price Volatility:Benzene and cyclohexane feedstock swings transmit directly into PA6 production economics, compressing margins for non-integrated compounders without captive raw material supply.
- China Concentration Risk:Over 60% of global PA6 polymerization capacity sits in Chinese provinces where energy rationing and environmental inspections trigger unplanned output curtailments.
- High-Performance Polymer Substitution:Polyphenylene sulfide and polyether ether ketone are displacing PA66 in connector applications above 200°C continuous service temperature.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for electric vehicle component manufacturing are creating demand for engineering-grade compounds with localized compounding and technical service support.
- Bio-Based PA11 Expansion:Castor oil-derived specialty grades command 3-4x commodity pricing in medical tubing and pneumatic brake lines where oil resistance and dimensional stability overlap.
- Chemical Recycling Infrastructure:Pyrolysis and depolymerization investments in Germany and the Netherlands are enabling food-contact rerecycling streams that mechanical recycling cannot achieve.
Industry Challenges
- Automotive Qualification Timelines:OEM validation cycles for new compound grades extend 18-24 months, locking out reformulation responses to sudden regulatory shifts like REACH SVHC candidate list updates.
- Compounder Technical Talent Scarcity:Formulation chemists with expertise in glass fiber coupling chemistry and heat stabilizer synergies are concentrated at incumbent suppliers, constraining new entrant scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyamide Market |
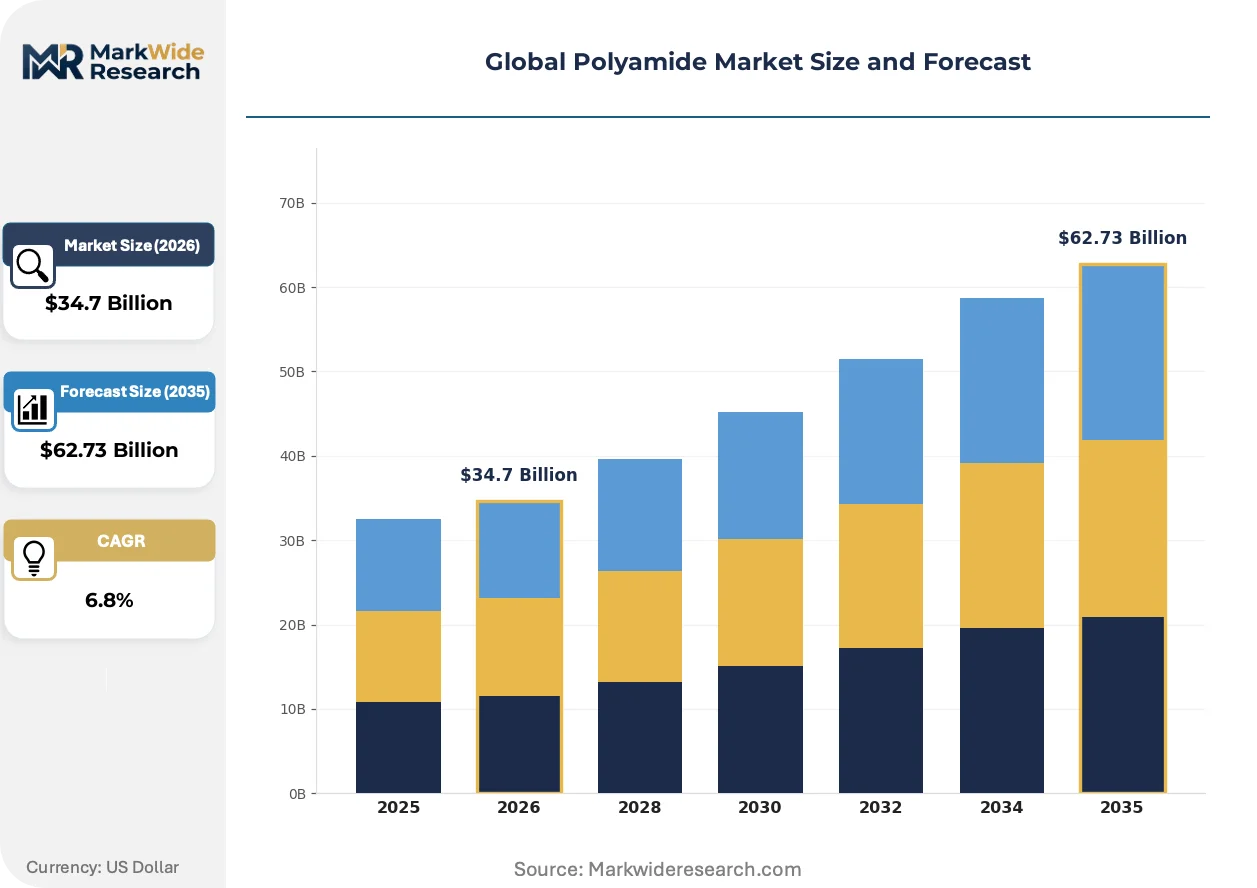
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA6, PA66, PA12, PA11 Grade: Standard, High-Performance, Specialty, Engineering Application: Automotive, Consumer Goods, Textiles, Electronics End User: Tier-1 Suppliers, OEMs, Manufacturers, Retailers |
| Companies Covered | BASF SE, Ascend Performance Materials, Arkema, Evonik Industries AG, LANXESS, DuPont, Toray Industries, Inc., Domo Chemicals, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyamide Market Strategic Shifts
Material science advances and regulatory stringency are converging to separate qualified suppliers from commodity producers, with circularity documentation becoming as critical as performance specifications in procurement decisions.
Glass fiber-reinforced PA6 compounds with 50% recycled content are collapsing the price premium between virgin and circular grades in automotive under-hood applications. Tier-1 suppliers in Germany and the United States have accelerated adoption since 2023. The technology is collapsing the historical three-tier pricing structure that separated certified recycling streams from mechanical regrind and virgin resin.
REACH authorization requirements for monomer residuals and additive packages are tightening disclosure thresholds for compounds entering European medical and food-contact applications. ECHA's 2024 updates to SVHC candidate listing have forced reformulation of legacy heat stabilizer packages containing certain metal salts. Medical tubing extruders serving the European market are consolidating supply bases to compounders with full formulation transparency and third-party certification.
Automotive OEMs are unbundling compound specification from volume contracting, separating technical qualification from commercial procurement to introduce second-source requirements for critical safety components. This bifurcation is compressing incumbent supplier margins while creating entry points for qualified regional compounders in Mexico and Eastern Europe. The pattern is most visible in connector and brake line applications where dual-source mandates now dominate RFQ structures.
Global Polyamide Market Segmentation
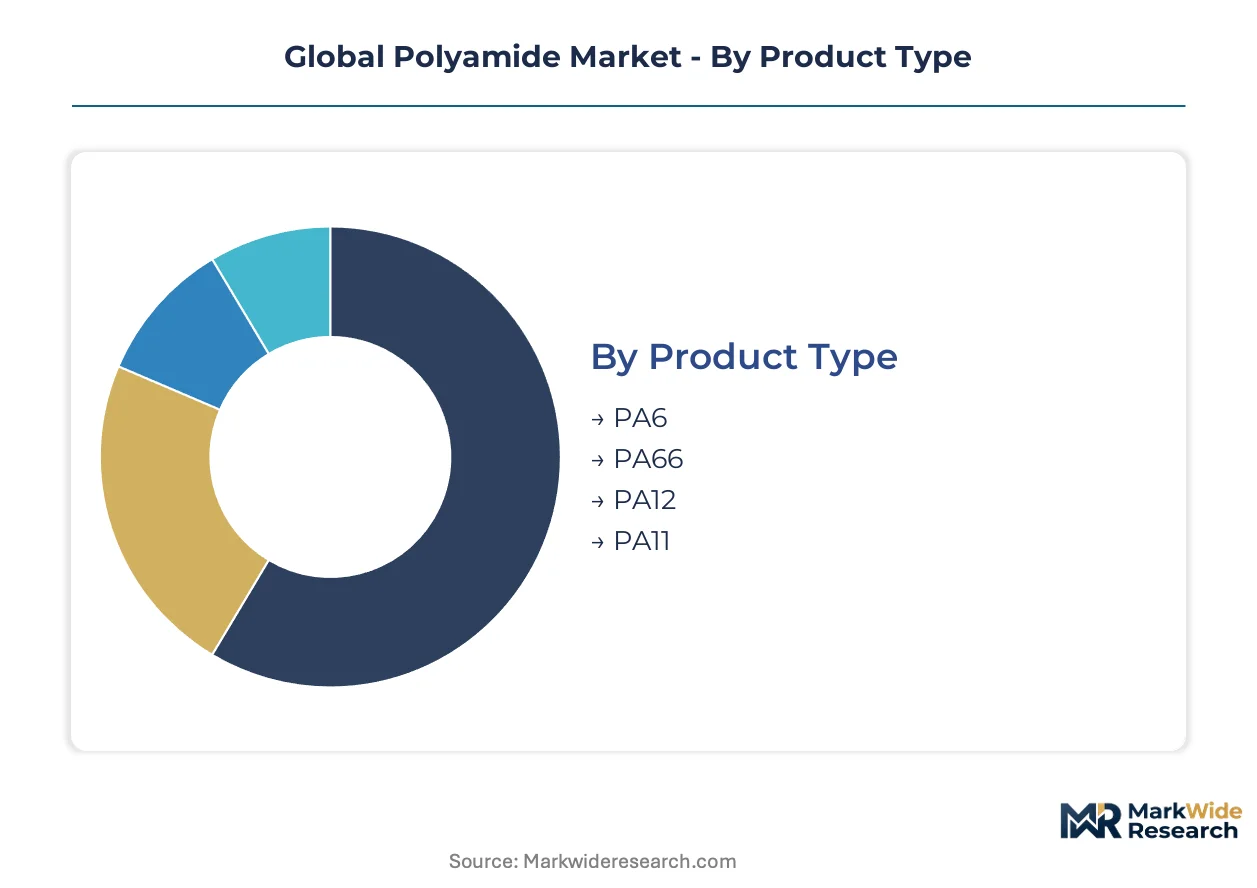
Polyamide procurement cycles vary dramatically across product types, with commodity grades turning over monthly while specialty qualifications lock in for years. Understanding these velocity differentials helps suppliers align inventory and technical service investments with actual decision rhythms.
Product Type:
PA6 cycles fastest due to textile fiber spot-market trading, while PA66 and bio-based grades carry 18-24 month automotive qualification timelines that freeze specifications.
- PA6:Six-carbon lactam-based polymer with melting points near 220°C. Textile fiber demand in Zhejiang Province and carpet yarn extrusion in the southeastern United States drive spot-market liquidity. Caprolactam price volatility transmits directly into compound economics, squeezing non-integrated producers when benzene feedstocks spike.
- PA66:Dual-six-carbon adipic acid-hexamethylenediamine structure delivering 265°C melting point and superior heat aging resistance. Battery thermal management systems in German and US Midwest automotive clusters are pulling volume from metal into polymer for coolant modules and connector housings where continuous service temperature exceeds 150°C.
- PA12:Twelve-carbon monomer delivers lowest moisture absorption and excellent chemical resistance for fuel lines and pneumatic tubing.
- PA11:Castor oil-derived biopolymer with 40% lower carbon footprint than petroleum-based alternatives, commanding specialty pricing in medical and offshore applications.
PA6 dominates installed base. PA66 is where expansion concentrates.
Grade:
Cost tiers separate commodity compounders from specialists, with certification documentation becoming the primary price differentiator rather than base resin alone.
- Standard:Unfilled or minimally modified grades for bulk textile and packaging film. Volume concentrates in Chinese state-owned polymerization assets where energy costs determine marginal production economics.
- High-Performance:Glass fiber-reinforced and heat-stabilized formulations for under-hood automotive and electrical connectors. REACH SVHC compliance and full formulation transparency now gate European medical and food-contact qualification, separating certified compounders from commodity suppliers.
- Specialty:Custom color-matched and laser-markable grades for consumer electronics housings.
- Engineering:Metal-replacement compounds with 50% glass loading for structural automotive components.
Standard grades capture volume throughput. High-Performance is climbing the fastest on electrification demand.
Application:
Customer types fragment technical service requirements, with automotive demanding embedded engineers while textiles run on specification sheets alone.
- Automotive:Metal substitution in powertrain, thermal management, and structural components. OEM unbundling of specification from volume contracting has introduced dual-source mandates for brake lines and connectors, compressing incumbent margins while opening entry points for qualified regional compounders in Mexico and Eastern Europe.
- Consumer Goods:Power tool housings and sporting equipment requiring impact-modified formulations.
- Textiles:Carpet fiber and industrial yarn where PA6 cost efficiency dominates over performance specifications.
- Electronics:Connector bodies and circuit breaker housings where flame retardancy and dimensional stability under solder reflow temperatures define qualification.
Automotive anchors revenue per ton. Electronics is gaining share fastest on miniaturization trends.
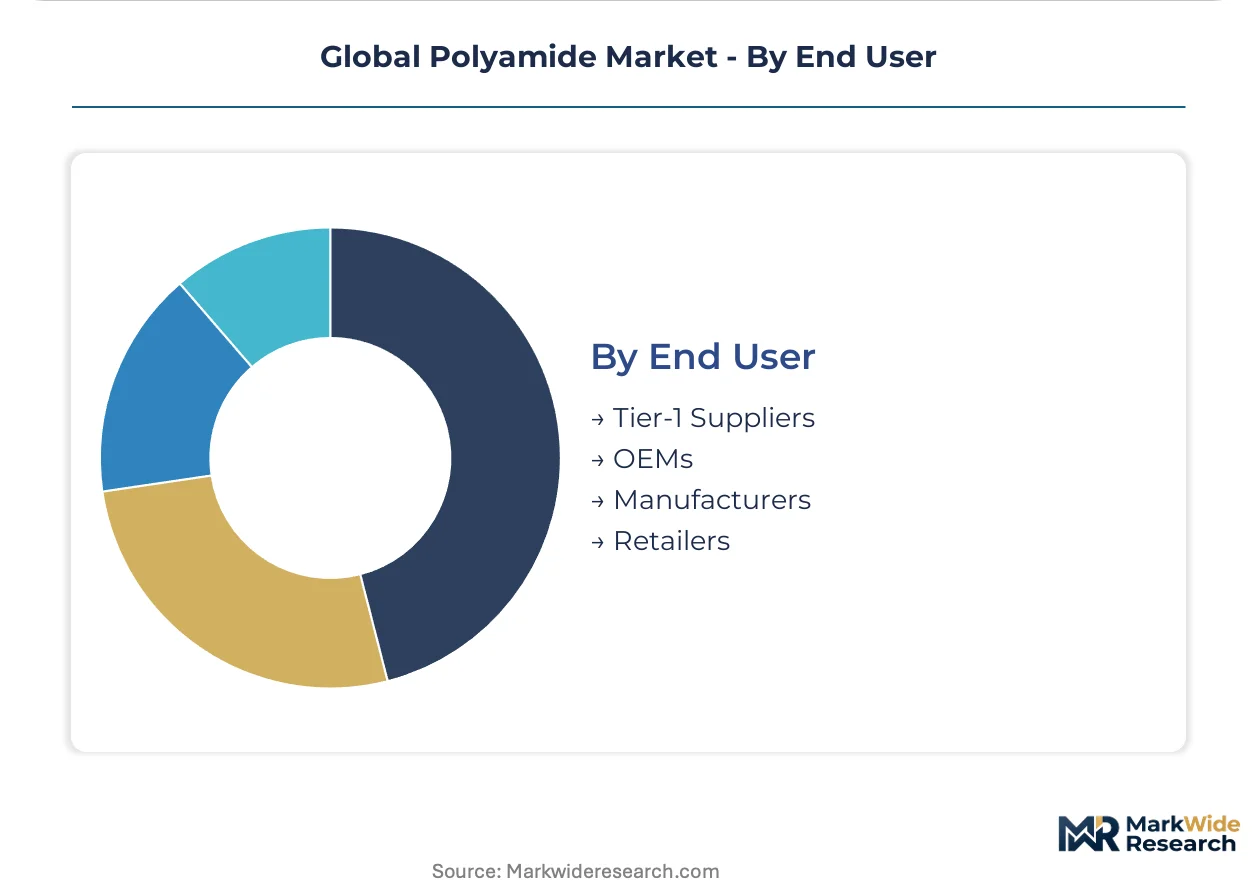
End User:
Supply concentration varies sharply by tier, with OEMs consolidating to compounders with certified recycling streams while retailers fragment across distributors.
- Tier-1 Suppliers:Delphi, Bosch, and Continental-level component integrators with 24-36 month qualification pipelines and mandatory second-source requirements. These stakeholders now require life-cycle documentation under EU Green Deal carbon border adjustments, advantaging European producers with integrated caprolactam chains.
- OEMs:Volkswagen, Ford, and BYD-level vehicle assemblers setting compound specifications that cascade through supply chains.
- Manufacturers:Mid-size processors without captive compounding capability, dependent on distributor technical support.
- Retailers:Spot buyers of standard grades through merchant distribution.
Tier-1 Suppliers dominate specification authority. OEMs are where sustainability compliance investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Zhejiang Province trade PA6 fiber on weekly spot contracts, while German automotive OEMs lock PA66 specifications through 36-month qualification pipelines that ignore price swings entirely.
China
PA6 polymerization capacity clusters in Jiangsu and Zhejiang provinces where textile fiber demand absorbs over half of domestic output. GB standards for automotive material recyclability now mandate life-cycle documentation for compounds entering EV supply chains. The Yangtze River Delta concentration faces recurring output curtailments from provincial energy rationing and environmental inspections.
Germany
Battery thermal management systems at Volkswagen and BMW pull heat-stabilized PA66 grades for coolant modules and connector housings. EU Green Deal carbon border adjustments now require Tier-1 suppliers to document cradle-to-gate emissions for imported compounds. The BASF integrated caprolactam complex in Ludwigshafen anchors European supply security for captive raw material users.
United States
EPA emissions standards for lightweighting accelerate metal-to-polymer substitution in powertrain components across Midwest automotive clusters. Adiponitrile capacity expansion in Texas and Louisiana reduces historical dependence on Asian precursor imports. Ascend Performance Materials anchors domestic PA66 supply through backward integration into adiponitrile production.
India
PLI scheme incentives for electric vehicle component manufacturing create demand for engineering-grade compounds with localized compounding support. BIS certification requirements for automotive materials are tightening disclosure thresholds for heat stabilizer packages. Tamil Nadu and Maharashtra automotive corridors concentrate new Tier-1 supplier investments seeking proximity to Hyundai, Tata Motors, and Mahindra assembly plants.
Japan
METI guidelines for sustainable manufacturing are pushing electronics OEMs toward bio-based PA11 in connector applications. High-performance polymer demand from semiconductor equipment manufacturers concentrates in the Nagoya industrial corridor. Toray Industries anchors domestic specialty grade development for medical tubing and pneumatic brake lines.
Global Polyamide Market Competitive Environment
Integrated petrochemical majors and specialty compounders split the market into divergent margin structures. The supplier base concentrates around three strategic archetypes: European producers with captive caprolactam chains, North American adiponitrile-integrated compounders, and Asian polymerization assets serving spot textile markets. Dominant competitive moves include backward integration into precursor chemicals and certification investment for circular recycling streams.
Within the integrated European tier, BASF SE exemplifies producers leveraging Ludwigshafen-scale caprolactam production to sustain margin capture from captive raw material supply. Ascend Performance Materials occupies a parallel position in North America through upstream control over adiponitrile. Arkema represents the specialty vector, differentiating via castor oil-derived chemistry rather than petroleum-based commodity grades.
| Leading Market Players |
|---|
| BASF SE |
| Ascend Performance Materials |
| Arkema |
| Evonik Industries AG |
| LANXESS |
| DuPont |
| Toray Industries, Inc. |
| Domo Chemicals |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
Zhejiang Province's PA6 polymerization capacity concentration gives integrated producers leverage over spot-market compounders when caprolactam feedstocks spike. German automotive OEMs ignore these swings entirely, locking PA66 specifications through 36-month qualification pipelines that prioritize heat-aging certification over unit economics.
Pricing Analysis
Aftermarket service revenue for engineering-grade stock shapes drives lifetime value capture, though OEM unbundling of specification from volume contracting is compressing this stream. Three-tier pricing structure across certified recycling, mechanical regrind, and virgin resin tiers separates compounders with full formulation transparency from commodity suppliers. Pricing pressure stems from glass fiber-reinforced PA6 compounds with 50% recycled content collapsing historical premiums between circular and virgin grades. Tier-1 automotive suppliers show least price sensitivity due to mandatory dual-source requirements, while textile fiber spot buyers in Zhejiang Province trade on weekly benzene-linked volatility.
Supply Chain Analysis
Extended payment terms from Tier-1 automotive suppliers strain working capital for non-integrated compounders lacking supply-chain finance facilities. Feedstock supply concentrates in China, Germany, and the United States, with adiponitrile capacity expansion in Texas and Louisiana reducing historical Asian import dependence. Raw material dependencies rest on benzene and cyclohexane for PA6, adipic acid-hexamethylenediamine for PA66, and castor oil derivatives for PA11. Single-source vulnerability in Chinese provincial energy rationing triggers unplanned output curtailments. Distribution runs through direct technical service relationships for automotive qualifications and merchant distribution for textile spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification represents an early-cycle expansion story, with battery thermal management systems pulling volume from metal housings into heat-stabilized polymer grades as OEMs compress qualification timelines.
For Market Incumbents: Build certification moats around REACH SVHC-compliant heat stabilizer packages and third-party circularity documentation. Defensive moves center on captive caprolactam integration at Ludwigshafen-scale complexes and pyrolysis infrastructure investments in Germany and the Netherlands. Threats from polyphenylene sulfide substitution above 200°C service temperatures demand R&D prioritization of glass fiber coupling chemistry advances. Channel control through embedded technical service teams at Tier-1 supplier locations locks out reformulation responses to regulatory shifts. For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra automotive corridors offer underpenetrated demand for localized compounding with PLI scheme tailwinds. White-space targets include engineering-grade compounds for Hyundai and Tata Motors supply chains seeking BIS-certified domestic alternatives to imported PA66. Medical tubing extruders in Europe present secondary entry points where full formulation transparency gates qualification. Go-to-market angle should emphasize 18-24 month qualification support bundled with carbon border adjustment documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with certified recycling streams and long-term automotive qualification lock-ins. Long-term viability across the analysis window favors upstream-integrated specialists with backward control over adiponitrile or caprolactam rather than commodity polymerization assets. Acquisition target archetype: regional compounders with dual-source mandates already secured at brake line and connector applications. Signal to watch is ECHA SVHC candidate list expansion forcing legacy heat stabilizer reformulation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Ascend Performance Materials anchors North American PA66 supply security through Texas and Louisiana capacity. |
| Chemical Recycling Infrastructure Buildout | Pyrolysis investments in Germany and Netherlands enable food-contact rerecycling streams beyond mechanical limits. |
| Long-term Supply Agreement with Tier-1s | Delphi and Bosch-level contracts with life-cycle documentation requirements lock out commodity competitors. |
| Joint Venture for Bio-Based PA11 Expansion | Arkema's castor oil-derived chemistry commands 3-4x commodity pricing in medical tubing applications. |
| Capacity Expansion in India | Localized compounding in Tamil Nadu corridors captures PLI scheme incentives for EV component manufacturing. |
Study Parameters
The analysis maps PA6 textile fiber spot markets, PA66 automotive qualification pipelines, PA11 bio-based specialty grades, and high-performance compound tiers, each validated through plant managers at polymerization facilities, procurement leads at Tier-1 automotive suppliers, distribution channel partners in merchant distribution networks, and technical R&D directors at compounders. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated producers, and ECHA SVHC candidate list updates. Bottom-up volume builds from polymerization capacity and qualification pipelines triangulated against top-down automotive production and textile fiber demand estimates.
Assumptions held fixed include REACH SVHC disclosure thresholds, EU Green Deal carbon border adjustment implementation timelines, and GB standards for automotive material recyclability enforcement patterns. Variables tested across the projection horizon encompass benzene-cyclohexane feedstock volatility, Chinese provincial energy rationing frequency, and high-performance polymer substitution rates above 200°C. Segmentation dimensions modeled span product type, grade tier, end-use industry, and regional production hub. CAGRs derived from qualification pipeline velocity differentials and spot-market trading liquidity patterns. Industry-specific inputs include automotive electrification content-per-vehicle trajectories and adiponitrile capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned polymerization assets or Gulf Coast adiponitrile producers would shift outcomes. Forecasts reflect assumptions about regulatory enforcement continuity, feedstock supply stability, and qualification timeline compression limits. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
PA66 Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
PET Foam Market