
 Amorphous Polyolefin Market | 2026-2036
Amorphous Polyolefin Market Size, Share, and Industry Trends Forecast 2026-2036
Amorphous Polyolefin Market Analytics
Asset-light leasing models for polymer production infrastructure is reconfiguring competitive entry barriers, allowing mid-scale compounders to access reactor capacity without capital-heavy ownership. Evonik Industries leverages its specialty chemicals heritage to dominate high-purity grades for medical and electronics applications. Eastman Chemical Company anchors North American supply through backward integration into feedstock streams and proprietary hydrogenation technology. Liaoyang Liaohua Qida Chemicals competes on cost-optimized copolymer output serving regional packaging converters.
Amorphous polyolefins constitute non-crystalline ethylene-propylene copolymers and terpolymers with glass transition temperatures typically below -20°C, manufactured via Ziegler-Natta or metallocene catalysis to deliver tackiness, flexibility, and moisture resistance in adhesive and sealant formulations. The elastomers segment leads volume consumption due to pervasive use in pressure-sensitive adhesives and asphalt modification, while the copolymers category captures expanding margin pools from metallocene-grade products serving automotive interior bonding and flexible packaging laminates. Blends and additives occupy narrower but defensible positions where formulators seek tailored rheology or UV stabilization.
EPA regulations on volatile organic compound emissions from adhesive operations and REACH restrictions on hazardous substance content in imported articles shape product development priorities and market access conditions for suppliers targeting North America and Europe. China's GB standards on food-contact materials and SAMR quality certifications further segment export eligibility. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned certification investments.
Market Dynamics
Automotive OEMs in China, Germany, and the United States are accelerating hot-melt adhesive adoption for electric vehicle battery pack sealing and lightweight interior bonding, compressing formulation windows and forcing raw material qualification cycles.
Growth Catalysts
- REACH Phase-In Substances:ECHA's rolling candidate list restrictions on SVHCs in imported articles push European formulators toward certified amorphous polyolefin grades that bypass hazardous substance declarations, expanding addressable demand for compliant copolymers.
- Hot-melt adhesive volume:Pressure-sensitive tape manufacturers serving e-commerce logistics hubs in Zhejiang Province and the Rhine-Ruhr corridor are substituting solvent-based systems with reactive polyolefin formulations to eliminate drying stages and cut energy costs.
- Metallocene catalysis:Narrow polydispersity indices enabled by single-site catalyst systems allow precise rheology tuning for medical device laminates, opening specification windows that Ziegler-Natta grades cannot satisfy.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker operating rates in the US Gulf Coast and Middle East swing with olefin demand cycles, transmitting price instability to copolymer producers lacking backward integration into refinery streams.
- Reactor concentration:Commercial-scale solution polymerization capacity clusters with multinational petrochemical complexes in Belgium, Singapore, and Texas, limiting compounder access for mid-volume specialty orders.
- Performance ceiling:Amorphous polyolefins exhibit upper service temperature limits around 80°C, excluding them from under-hood automotive applications where polyamide and polyester hot-melts dominate.
Strategic Opportunities
- India packaging conversion:FSSAI food-contact material registrations and BIS quality certifications remain underpenetrated for imported specialty grades, creating first-mover advantage for suppliers establishing local technical service presence.
- Solar encapsulant films:POE-APO blend formulations for photovoltaic module edge sealing offer moisture ingress protection superior to EVA, with module assemblers in Vietnam and Malaysia testing qualification batches.
- EU Green Deal procurement:Public tender scoring criteria now weight bio-based content and recyclability, advantaging suppliers with mass-balance certified copolymers over conventional petroleum-derived competitors.
Industry Challenges
- Metallocene catalyst sourcing:Patent thickets around constrained-geometry catalyst architectures limit licensee flexibility, forcing compounders into single-supplier dependencies for medical-grade polymer production.
- SAMR registration timelines:China's GB 4806 food-contact material compliance testing requires 12-18 month validation cycles for new copolymer grades, delaying revenue recognition from formulation wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amorphous Polyolefin Market |
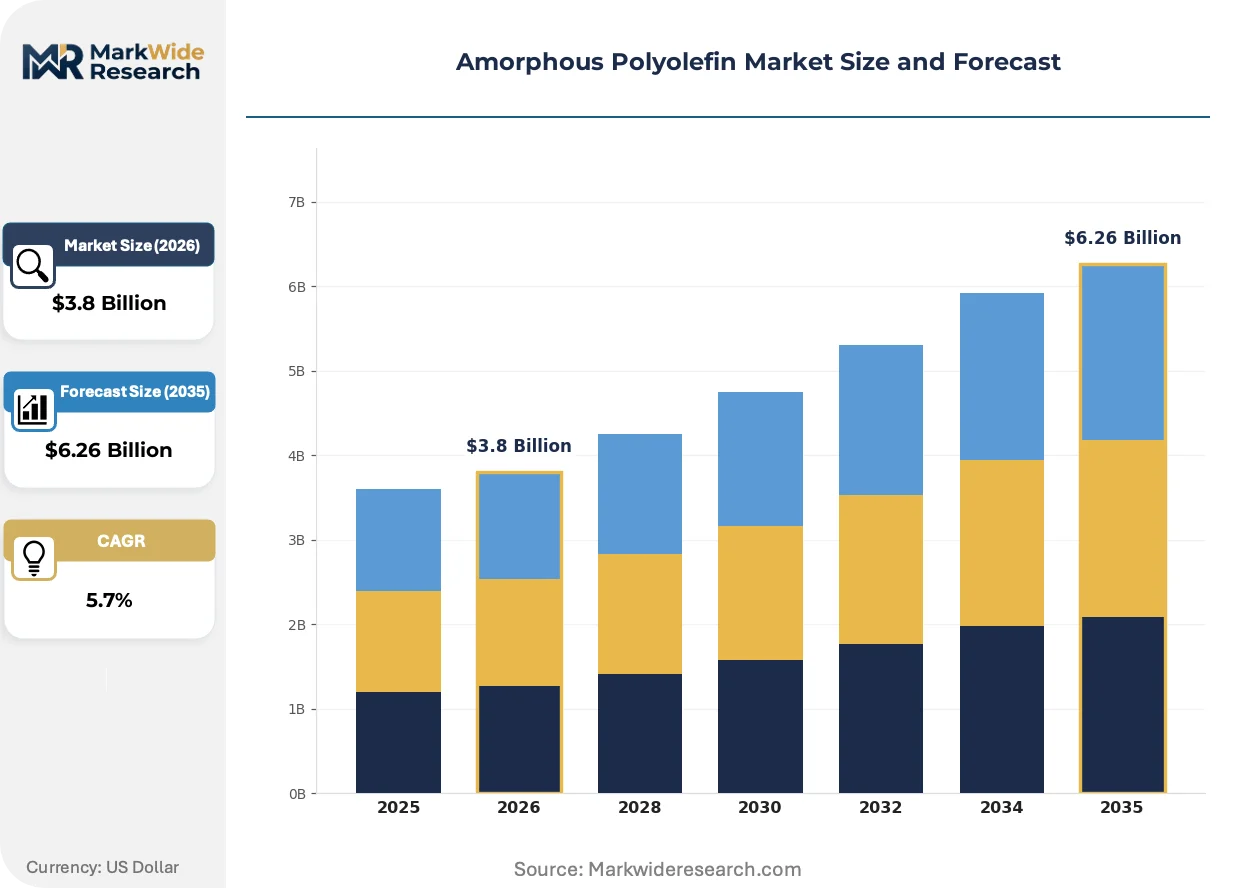
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastomers, Copolymers, Blends, Additives End Use Industry: Adhesives, Packaging, Automotive, Construction Packaging Type: Flexible Packaging, Rigid Containers, Films, Labels Application: Sealants, Coatings, Thermal Insulation, Electrical Insulation |
| Companies Covered | Evonik Industries, Eastman Chemical Company, REXtac LLC, Liaoyang Liaohua Qida Chemicals, ExxonMobil, H.B. Fuller, Henkel, Arkema, Soltex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amorphous Polyolefin Market Evolving Landscape
Formulation science is pivoting from commodity copolymer supply toward engineered rheology systems, with catalyst technology and regulatory compliance emerging as the primary axes of supplier differentiation.
Metallocene-grade amorphous polyolefins deliver precise molecular weight distribution control for low-odor, low-color adhesive applications. Medical device manufacturers in Germany and Switzerland are specifying these grades for transdermal patch laminates where extractables profiles must satisfy ISO 10993 biocompatibility protocols. The technology is migrating from premium medical niche positions into standard packaging adhesives as catalyst licensing costs decline.
REACH Annex XIV authorization requirements for diisocyanate-containing polyurethane adhesives are accelerating substitution timelines across European furniture and construction assembly operations. Formulators face 2025 deadlines for worker exposure training and substitution planning where feasible alternatives exist. Hot-melt polyolefin systems capture share in edge-banding and profile-wrapping applications where polyurethane previously dominated.
Buyers in China's eastern manufacturing corridor are consolidating adhesive procurement through platform distributors rather than direct mill relationships. Packaging converters in Suzhou and Dongguan now specify performance parameters and compliance certifications through third-party trading platforms, compressing supplier sales cycles and standardizing grade specifications. This channel shift is most visible in mid-volume electronics assembly accounts where technical service intensity previously favored direct supply relationships.
Amorphous Polyolefin Market Segmentation
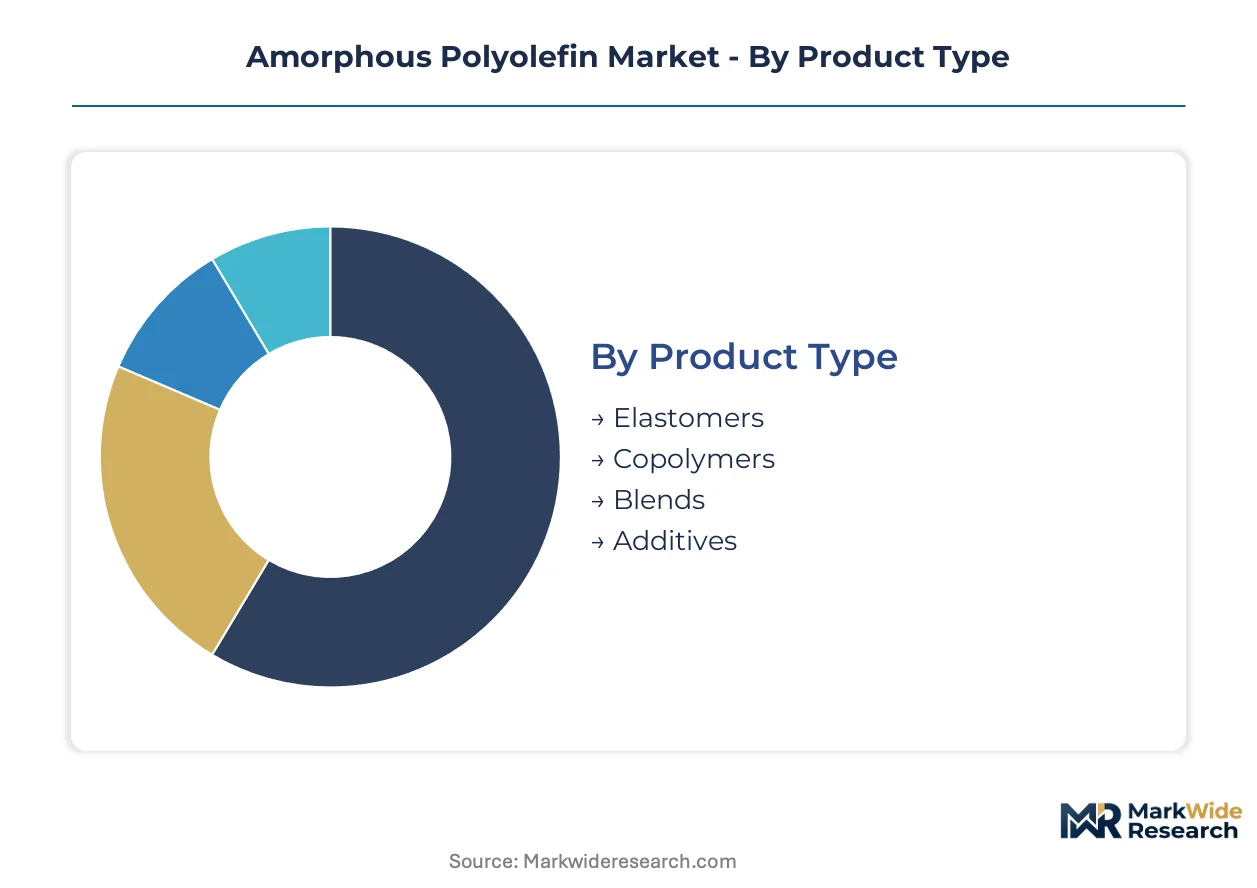
Segmentation in amorphous polyolefins reveals divergent margin structures and qualification cycles across product chemistry and end-use application. Buyers prioritize tack performance, regulatory certification, and supply security differently depending on whether they serve automotive OEMs or packaging converters.
Product Type:
Cycle times vary sharply: elastomer grades turn inventory monthly for adhesive compounders, while metallocene copolymers face 6-12 month qualification windows for medical laminates.
- Elastomers:Non-crystalline ethylene-propylene copolymers and terpolymers with glass transition temperatures below -20°C, manufactured via Ziegler-Natta catalysis. Pressure-sensitive adhesive manufacturers in Germany's Rhine-Ruhr corridor and China's Zhejiang Province consume volume grades for tape backing and label stock, driven by e-commerce logistics expansion and solvent-free formulation mandates from ECHA's SVHC restrictions.
- Copolymers:Metallocene-catalyzed grades with narrow polydispersity indices enabling precise rheology control. Automotive OEMs in Germany, the United States, and China specify these for electric vehicle battery pack sealing and lightweight interior bonding, where formulation windows compress and raw material qualification cycles accelerate.
- Blends:Tailored rheology systems combining amorphous polyolefins with tackifying resins or plasticizers for specific adhesion profiles.
- Additives:UV stabilizers, antioxidants, and process aids that extend service life in outdoor construction applications.
Elastomers dominate installed base. Copolymers are where expansion concentrates.
End Use Industry:
Cost tiers separate commodity adhesive applications from medical and electronics specifications requiring extractables testing and biocompatibility protocols.
- Adhesives:Hot-melt and pressure-sensitive formulations serving packaging, hygiene, and industrial assembly. Pressure-sensitive tape manufacturers in Zhejiang Province and the Rhine-Ruhr corridor substitute solvent-based systems with reactive polyolefin formulations to eliminate drying stages and cut energy costs, responding to EPA volatile organic compound regulations and REACH hazardous substance restrictions.
- Packaging:Flexible laminate bonding and sealant layers for food-contact applications. China's GB 4806 standards and SAMR quality certifications segment export eligibility, with 12-18 month validation cycles for new copolymer grades delaying revenue recognition.
- Automotive:Lightweight interior bonding and battery pack sealing for electric vehicles. OEMs in China, Germany, and the United States accelerate hot-melt adhesive adoption, compressing formulation windows and forcing raw material qualification cycles.
- Construction:Asphalt modification and roofing membrane applications where moisture resistance and low-temperature flexibility matter.
Adhesives command the broadest volume footprint. Automotive represents the steepest expansion trajectory.
Packaging Type:
Customer type divides the segment: multinational food brands demand mass-balance certified grades for EU Green Deal procurement scoring, while regional converters prioritize unit cost.
- Flexible Packaging:Laminates and pouches for food and consumer goods. Converters in Suzhou and Dongguan consolidate procurement through platform distributors, compressing supplier sales cycles and standardizing grade specifications.
- Rigid Containers:Injection-molded and thermoformed packaging with sealant layers.
- Films:Cast and blown films for protective and functional barriers. Photovoltaic module assemblers in Vietnam and Malaysia test POE-APO blend formulations for solar encapsulant edge sealing, where moisture ingress protection exceeds EVA performance.
- Labels:Pressure-sensitive face stocks and release liners.
Flexible packaging anchors current demand. Films are climbing the fastest.
Application:
Supply concentration shapes access: sealant and coating formulations draw from distributed compounder networks, while thermal and electrical insulation grades cluster with specialty polymer producers.
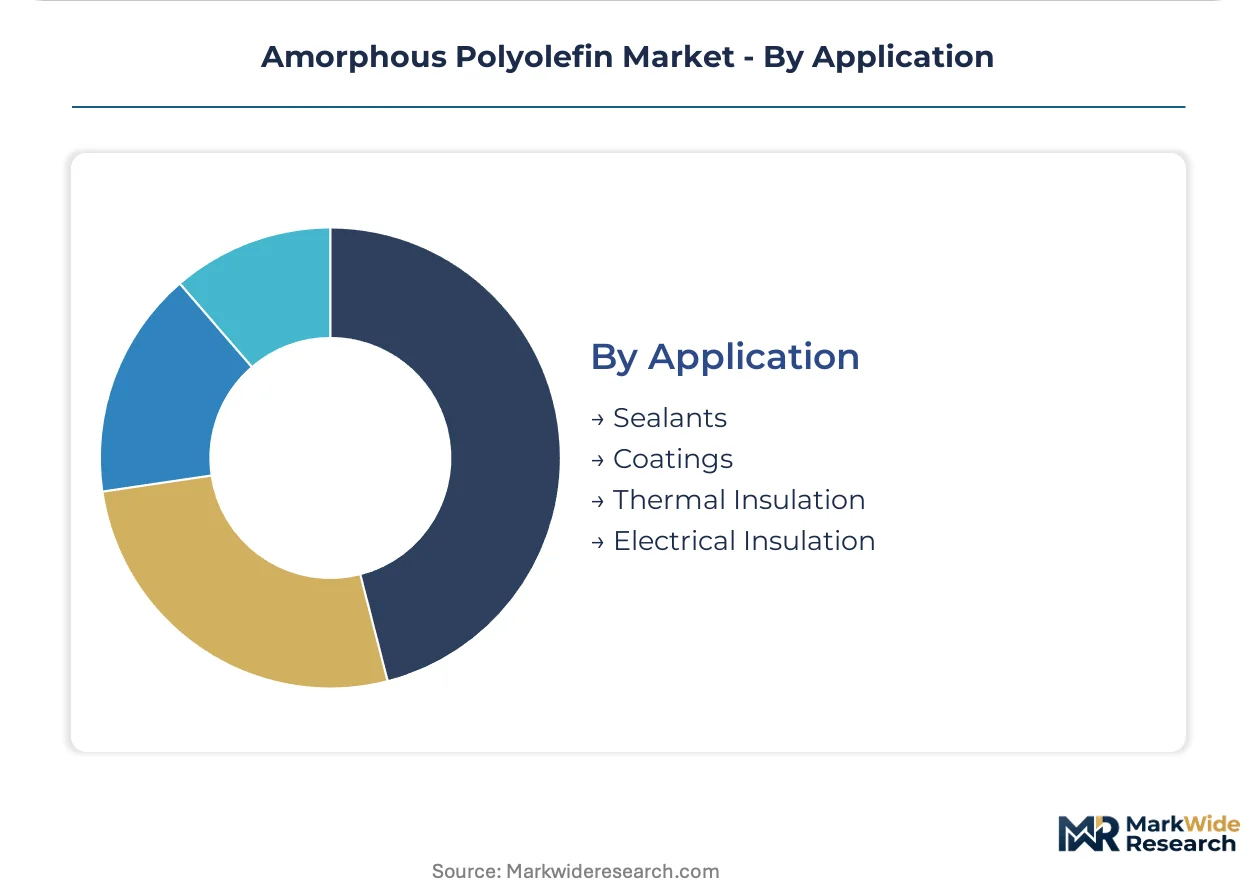
- Sealants:Gap-filling and joint-sealing formulations for construction and transportation. REACH Annex XIV authorization requirements for diisocyanate-containing polyurethane adhesives accelerate substitution timelines across European furniture and construction assembly operations, with hot-melt polyolefin systems capturing share in edge-banding and profile-wrapping applications.
- Coatings:Protective and functional layers applied via hot-melt or solution processes.
- Thermal Insulation:Low-thermal-conductivity barriers for building and industrial equipment.
- Electrical Insulation:Wire and cable jacketing, capacitor films, and electronic component protection.
Sealants hold the largest installed base. Electrical insulation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in amorphous polyolefins concentrate in three trade corridors: Asia-Pacific manufacturing hubs importing specialty metallocene grades, European formulators sourcing compliant copolymers under REACH restrictions, and North American compounders balancing domestic elastomer production against Asian packaging-grade imports.
China
Packaging converters in Suzhou and Dongguan drive consumption of cost-optimized copolymers for flexible laminate bonding. SAMR's GB 4806 food-contact material standards impose 12-18 month validation cycles that filter out non-compliant imports. The Yangtze River Delta electronics assembly cluster tests metallocene-grade adhesives for smartphone component bonding.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify narrow-polydispersity copolymers for electric vehicle battery pack sealing. ECHA's rolling REACH candidate list on SVHCs pushes formulators toward certified grades that bypass hazardous substance declarations. The Rhine-Ruhr corridor hosts pressure-sensitive tape manufacturers substituting solvent systems with reactive polyolefin formulations.
United States
Hot-melt adhesive compounders serving e-commerce logistics hubs seek low-VOC formulations under EPA emissions regulations. FDA evolving guidance on food-contact polymers tightens material certification requirements for packaging applications. Texas and Louisiana petrochemical complexes anchor domestic elastomer production with backward-integrated feedstock access.
India
FSSAI food-contact material registrations and BIS quality certifications remain underpenetrated for imported specialty grades, creating first-mover opportunities. Maharashtra and Gujarat packaging converters consolidate procurement through distributors rather than direct mill relationships. Technical service presence in Mumbai and Ahmedabad determines supplier access to mid-volume electronics accounts.
Japan
Medical device manufacturers in the Kanto region specify low-odor, low-color metallocene grades for transdermal patch laminates under ISO 10993 biocompatibility protocols. METI industrial standards shape qualification requirements for electronics adhesive applications. Osaka-based formulators blend amorphous polyolefins with tackifying resins for precision rheology control.
Amorphous Polyolefin Market Competitive Landscape
On the supply side, the industry is consolidating around three capability tiers: multinational petrochemical majors with captive catalysis technology, regional compounders leveraging asset-light leasing models for reactor access, and specialty chemical houses dominating high-purity grades for regulated applications. Strategic archetypes include backward-integrated feedstock controllers, metallocene catalyst licensees, and cost-optimized copolymer producers serving regional packaging clusters. Competitive moves concentrate on technology licensing partnerships and geographic expansion through distributor platform relationships.
Within the premium-grade tier, Evonik Industries and Eastman Chemical Company exemplify positioning around regulatory compliance and specialty application expertise. Evonik leverages its specialty chemicals heritage to occupy positions in medical and electronics specifications where extractables testing and biocompatibility protocols create qualification barriers. Eastman anchors North American supply through proprietary hydrogenation technology and captive feedstock integration. Liaoyang Liaohua Qida Chemicals sits within the cost-optimized regional producer archetype, serving Chinese packaging converters with volume-focused copolymer output.
| Leading Market Players |
|---|
| Evonik Industries |
| Eastman Chemical Company |
| REXtac LLC |
| Liaoyang Liaohua Qida Chemicals |
| ExxonMobil |
| H.B. Fuller |
| Henkel |
| Arkema |
| Soltex |
| Others |
Value Network & Pricing Analysis
Belgium's Antwerp-Rotterdam petrochemical cluster concentrates solution polymerization capacity for amorphous polyolefins, granting integrated producers leverage over mid-volume specialty orders and compressing margins for non-integrated compounders. This geographic concentration shapes how pricing power flows downstream to automotive OEMs and packaging converters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Metallocene-catalyzed medical grades command premiums based on ISO 10993 biocompatibility certification and narrow polydispersity indices, while Ziegler-Natta elastomers trade at commodity benchmarks. Cost compression in standard copolymer tiers intensifies because propylene feedstock volatility transmits from US Gulf Coast naphtha crackers. Regional packaging converters in China's eastern manufacturing corridor exhibit highest price sensitivity, whereas German medical device manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
Export control regimes on constrained-geometry metallocene catalyst architectures limit technology licensing flows, fragmenting supply security for medical-grade polymer production. Manufacturing concentrates in Belgium, Singapore, and Texas, with propylene monomer and hydrogenation catalysts as critical inputs. Single-source vulnerability runs through patent-thicketed catalyst suppliers, exposing compounders to supply interruption. Distribution runs through platform distributors in China's Suzhou-Dongguan corridor and direct mill relationships for high-specification automotive and medical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amorphous polyolefins represent a high-growth disruption as metallocene catalysis displaces conventional Ziegler-Natta systems, with REACH Annex XIV diisocyanate restrictions accelerating polyurethane substitution timelines.
For Market Incumbents: Entrench regulatory certification moats by deepening backward integration into hydrogenation technology and captive feedstock streams. Prioritize capacity expansion in Texas and Louisiana to offset propylene volatility exposure. Defend against Asian cost-optimized producers by embedding technical service teams within German automotive OEM qualification cycles. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated FSSAI food-contact registration segment before multinational distributors consolidate channel control. Target Maharashtra and Gujarat packaging converters through platform partnerships rather than direct mill relationships. Leverage asset-light reactor leasing models to bypass capital barriers in specialty copolymer production. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallocene catalyst licensees with medical-grade certification pipelines over commodity elastomer producers. Long-term viability hinges on mass-balance certification capabilities for EU Green Deal procurement scoring. Watch ECHA's rolling SVHC candidate list expansions as the primary inflection signal for substitution-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Technology | Eastman Chemical's proprietary hydrogenation anchors North American supply security against propylene volatility. |
| Metallocene Catalyst Licensing Partnership | Patent-thicketed constrained-geometry architectures limit licensee flexibility and create single-supplier dependencies. |
| Mass-Balance Certification Program | EU Green Deal procurement scoring now weights bio-based content, advantaging certified copolymers. |
| Platform Distributor Expansion | China's Suzhou-Dongguan packaging converters consolidate procurement through third-party trading platforms. |
| Medical-Grade Qualification Pipeline | ISO 10993 biocompatibility protocols create extractables testing barriers for transdermal patch laminates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC petrochemical division filings, and ECHA REACH registration databases. Interviews with adhesive compounder procurement leads, automotive OEM platform engineers, medical device regulatory affairs directors, and catalyst technology licensors informed demand-side validation. Bottom-up volume modeling triangulates against top-down capacity assessments across Belgium, Singapore, and Texas production hubs.
Forecast inputs span grade tier segmentation by catalysis type, end-use industry clustering across automotive interior bonding and flexible packaging laminates, and regional regulatory framework divergence between REACH, EPA VOC rules, and China's GB 4806 standards. CAGRs derive from production capacity expansion schedules, substitution elasticity estimates for polyurethane displacement, and qualification cycle duration assumptions across medical and automotive specification windows.
Sensitivities concentrate around propylene feedstock price volatility, ECHA SVHC list expansion timing, and SAMR registration timeline compression. Forecasts reflect documented assumptions on catalyst licensing cost trajectories and platform distributor channel share gains. Material shifts in EU Green Deal procurement scoring weights or metallocene patent cliff acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market