
 Water-Borne Epoxy Resins Market | 2026-2036
Water-Borne Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Epoxy Resins Market Analytics
Marine coating contractors are rotating away from solvent-heavy systems toward water-borne alternatives that cut volatile organic compound emissions during vessel maintenance cycles. BASF SE leverages its European formulation network to supply shipyards with compliant resin systems. Dow Chemical Company anchors North American production through integrated epoxy intermediates capacity. Huntsman Corporation specializes in high-performance marine grades that withstand saltwater immersion and thermal cycling.
Water-borne epoxy resins are aqueous dispersions of epoxy polymers, typically formulated with epoxy equivalent weights between 450 and 2500 g/eq, that cure through polyamine or polyamide hardeners to form adherent, chemically resistant films without volatile organic solvent carriers. Their primary purpose centers on protective coatings and bonded assemblies where worker safety regulations and air-quality mandates restrict solvent emissions. Coatings command the largest value pool across product types, driven by infrastructure refurbishment and industrial maintenance cycles. Adhesives represent the fastest-expanding category as automotive lightweighting programs specify bonded joints in place of mechanical fasteners. Composite Materials occupy a premium niche where aerospace tier-one suppliers demand certified prepreg-compatible resin matrices.
EPA air-quality standards and OSHA workplace exposure limits in the United States compel coating applicators to shift formulation chemistries toward water-borne systems or face permitting restrictions and penalty liabilities. REACH registration requirements and the EU Green Deal industrial emissions framework in Europe block non-compliant imports and redirect procurement toward certified low-VOC resin suppliers. Stakeholders must monitor evolving state-level VOC rules in California and New York alongside potential amendments to TSCA Section 6 chemical risk evaluations that could restrict legacy epoxy precursors.
Market Dynamics
Marine coating contractors face a structural pivot as EPA and OSHA exposure mandates force solvent-to-water formulation conversions across US shipyards, compressing legacy supply chains while opening certified low-VOC channels.
Growth Catalysts
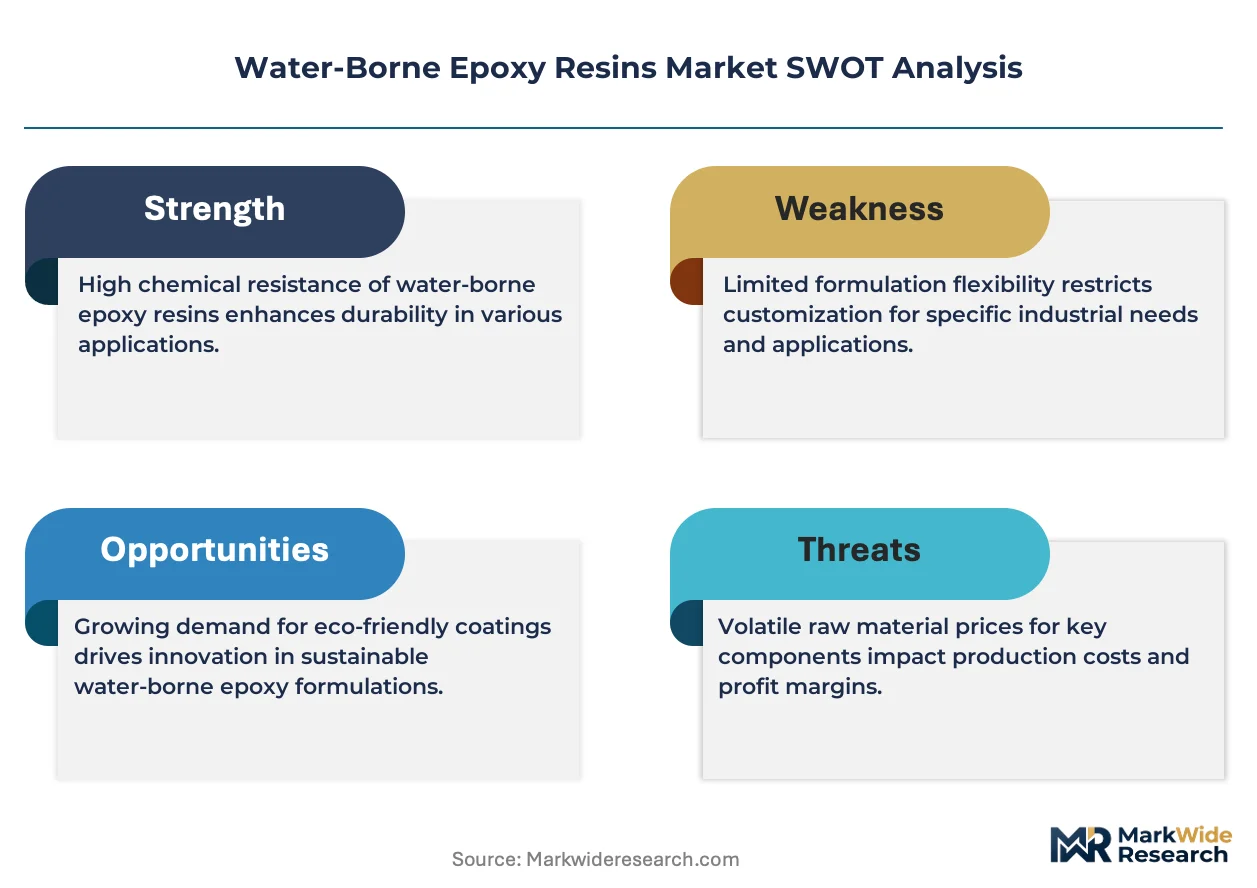
- EU Green Deal industrial emissions framework:REACH-registered water-borne systems now dominate European procurement for vessel refurbishment, blocking non-compliant imports from Asian suppliers.
- Automotive lightweighting specifications:Bonded joint designs in electric vehicle platforms specify water-borne epoxy adhesives to replace mechanical fasteners in chassis assembly.
- China's dual carbon goals:MEE enforcement in Jiangsu and Shandong provinces redirects shipyard coating contracts toward aqueous dispersion technologies.
Market Restraints
- Epichlorohydrin feedstock volatility:Propylene-derived intermediate costs swing with crude oil indices, squeezing formulation margins for mid-tier resin producers.
- Cure kinetic limitations:Extended drying windows in humid climates restrict water-borne systems from high-throughput industrial coating lines serving automotive OEMs.
- Solvent-borne hybrid persistence:Legacy 2K polyurethane-epoxy blends retain performance advantages in immersion service, slowing full displacement in deep-sea applications.
Strategic Opportunities
- Wind turbine blade manufacturing:Vacuum infusion processes for offshore turbine composites specify certified low-VOC resin matrices to meet German TÜV certification.
- California Air Resources Board amendments:Proposed Suggested Control Measure expansions would mandate water-borne systems for pleasure craft maintenance in Los Angeles and San Diego counties.
- Digital coating specification platforms:Shipyard procurement teams in Hamburg and Rotterdam now source compliant resins through integrated compliance-verification marketplaces.
Industry Challenges
- Formulation chemist shortage:Expertise in aqueous dispersion stabilization and amine-adduct design concentrates at legacy European and Japanese resin houses.
- Cross-border certification lag:Marine coating approvals from Lloyd's Register and DNV require 18-24 month validation cycles for new water-borne product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Epoxy Resins Market |
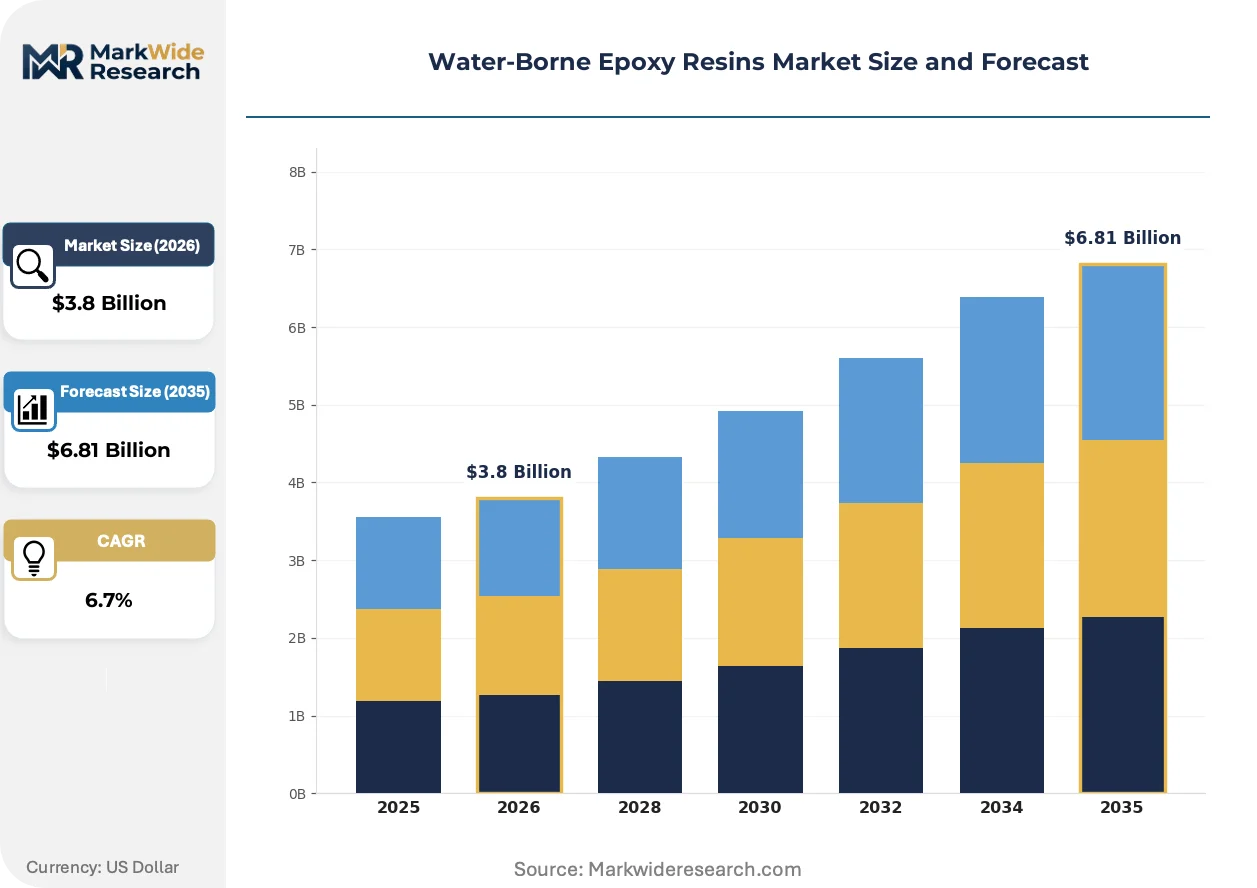
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Sealants, Composite Materials Application: Construction, Automotive, Marine, Aerospace End User: Manufacturers, Contractors, Architects, Engineers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Chemical Company, Huntsman Corporation, Hexion Inc., Allnex GmbH, Aditya Birla Chemicals Ltd., DIC Corporation, Olin Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Epoxy Resins Market Evolving Landscape
Formulation science is splitting along performance-grade lines as marine contractors demand faster-cure systems while infrastructure buyers prioritize extended pot-life materials. This divergence reshapes R&D allocation and production asset configuration.
Self-crosslinking acrylic-modified epoxy dispersions are bifurcating the protective coatings segment. These hybrid systems deliver single-component convenience with two-component durability, attracting municipal bridge maintenance contractors seeking reduced waste and simplified inventory. The technology is compressing demand for conventional polyamide-cured water-borne epoxies in ambient-cure infrastructure applications.
REACH authorization timelines for bisphenol A derivatives are tightening supply security for epoxy resin precursors. ECHA's 2024-2025 substance evaluation wave flags additional epoxy building blocks for restriction screening, forcing formulators to validate alternative diphenolic structures. European industrial maintenance coating buyers are accelerating qualification of bisphenol F and hydrogenated bisphenol A-based aqueous systems to preempt supply interruption.
Shipyard coating contractors now specify resin systems through integrated compliance platforms that automate VOC certification verification against state-level rules. Digital procurement channels displace traditional distributor relationships in Hamburg, Rotterdam, and Singapore port clusters. This behavior concentrates purchasing power among platform-enabled buyers capable of real-time regulatory validation.
Water-Borne Epoxy Resins Market Segmentation
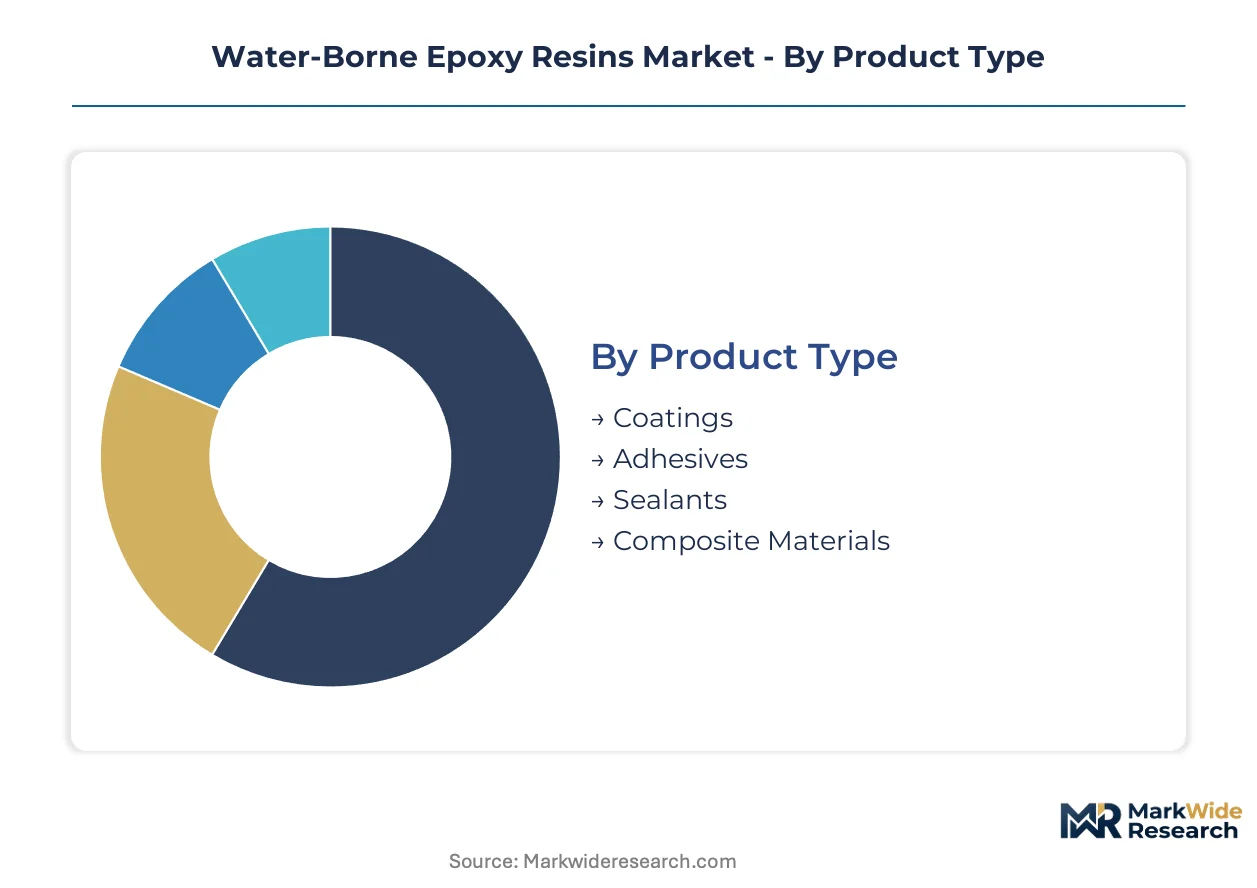
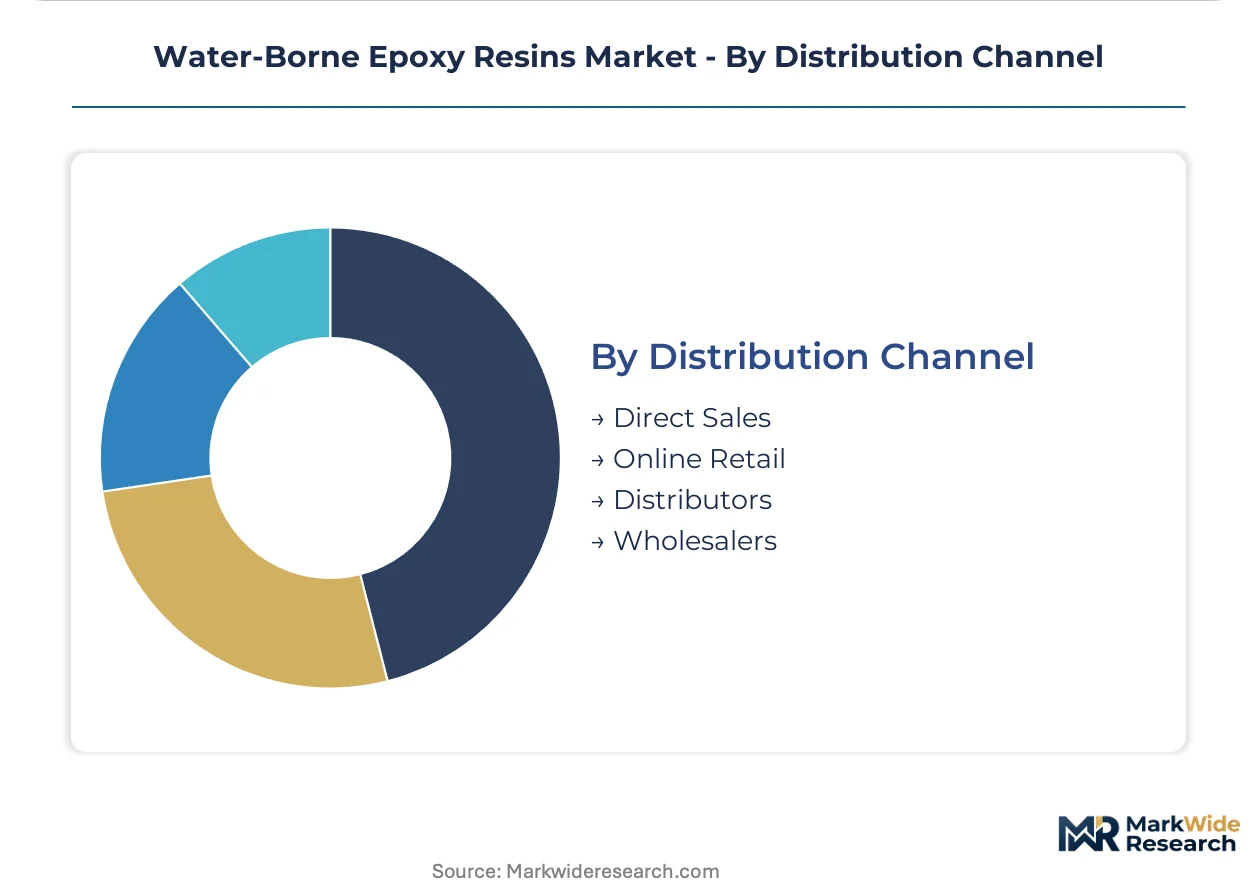
Water-borne epoxy resin procurement channels diverge sharply by segment, with marine contractors sourcing through certified distributors while automotive OEMs negotiate direct supply agreements. Understanding these channel dynamics illuminates margin capture and compliance verification requirements across the value chain.
Product Type:
Channel mix varies dramatically by product chemistry, with coatings flowing through distributor networks and adhesives increasingly sold direct to automotive tier suppliers.
- Coatings:Aqueous dispersions with epoxy equivalent weights between 450 and 2500 g/eq cure through polyamine or polyamide hardeners to form adherent, chemically resistant films. Marine coating applicators in Hamburg and Rotterdam source these through compliance-verification marketplaces that automate VOC certification against EU Green Deal requirements.
- Adhesives:Formulations engineered for bonded joint designs in electric vehicle chassis assembly deliver structural integrity without mechanical fasteners. Automotive lightweighting programs in Germany and China specify these systems through direct procurement channels with resin houses.
- Sealants:Elastomeric water-borne systems provide flexible waterproofing for infrastructure joints and building envelopes.
- Composite Materials:Certified prepreg-compatible resin matrices serve aerospace tier-one suppliers demanding TÜV-compliant low-VOC formulations for vacuum infusion processes.
Coatings dominate installed base. Adhesives are where expansion concentrates.
Application:
Cost tier stratification separates premium marine grades from standard construction formulations, with price points scaling to performance certification requirements.
- Construction:Municipal bridge maintenance contractors favor self-crosslinking acrylic-modified epoxy dispersions for single-component convenience with two-component durability. Ambient-cure infrastructure applications in the United States face EPA air-quality compliance deadlines.
- Automotive:Electric vehicle platforms specify water-borne epoxy adhesives to replace mechanical fasteners in chassis assembly, with procurement running through integrated supplier networks.
- Marine:Shipyard refurbishment programs in China and Germany concentrate procurement for saltwater immersion and thermal cycling resistance.
- Aerospace:Prepreg-compatible resin matrices require 18-24 month validation cycles from Lloyd's Register and DNV for new water-borne product families.
Marine commands premium pricing tiers. Automotive is climbing the fastest.
End User:
Customer type determines specification authority and technical support intensity, with architects driving material selection early in project cycles.
- Manufacturers:Wind turbine blade producers and automotive OEMs specify certified low-VOC resin matrices through long-term supply agreements with formulation houses.
- Contractors:Marine coating applicators face structural pivots as EPA and OSHA exposure mandates force solvent-to-water conversions across US shipyards.
- Architects:Building envelope designers increasingly specify aqueous systems for LEED compliance and worker safety during application.
- Engineers:Infrastructure project teams validate performance data against extended pot-life requirements for large-scale concrete protection.
Contractors control near-term volume. Manufacturers drive technology roadmaps.
Distribution Channel:
Supply concentration shapes channel power, with digital platforms displacing traditional relationships in port clusters.
- Direct Sales:Automotive and aerospace OEMs negotiate captive supply agreements with BASF SE, Dow Chemical Company, and Huntsman Corporation for qualified resin systems.
- Online Retail:Small-scale maintenance contractors access standard-grade formulations through digital marketplaces with embedded compliance documentation.
- Distributors:Regional networks serve construction contractors with technical service support for ambient-cure application guidance.
- Wholesalers:Volume aggregation points supply mid-tier resin producers facing epichlorohydrin feedstock volatility.
Distributors retain construction sector share. Direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites the Netherlands' position as Europe's water-borne epoxy resin distribution hub, with dedicated tank storage and blending facilities serving North Sea shipyard clusters.
United States
Shipyard refurbishment programs in Norfolk and Pascagoula drive demand for saltwater-immersion-grade formulations. EPA air-quality standards and OSHA workplace exposure limits compel coating applicators toward low-VOC systems. Gulf Coast petrochemical corridors supply epoxy intermediates to marine contractors facing permitting restrictions.
Germany
Wind turbine blade manufacturing in Bremerhaven and Rostock specifies certified resin matrices for vacuum infusion processes. REACH registration requirements and the EU Green Deal industrial emissions framework block non-compliant imports. Hamburg shipyards source compliant systems through integrated compliance-verification marketplaces.
China
Jiangsu and Shandong province shipyards concentrate procurement for vessel maintenance cycles under MEE enforcement of dual carbon goals. Yangtze River Delta chemical parks produce aqueous dispersion technologies for domestic coating applicators. Qingdao and Shanghai port clusters redirect contracts toward low-VOC formulations.
Japan
Automotive lightweighting programs in Toyota City and Yokohama specify water-borne epoxy adhesives for electric vehicle chassis assembly. METI industrial emissions guidelines tighten solvent-borne alternatives across manufacturing sectors. Nagoya-based formulation houses supply bonded joint designs to tier-one suppliers.
South Korea
Ulsan shipyard complexes demand high-performance marine grades with thermal cycling resistance for offshore vessel construction. Korean Industrial Standards certification requirements favor REACH-registered aqueous systems. Busan port procurement teams validate VOC compliance through digital specification platforms.
Water-Borne Epoxy Resins Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing integrated epoxy intermediates capacity. The vendor base splits between European formulation specialists with REACH-registered product families and Asian producers serving cost-sensitive construction segments. Two strategic archetypes dominate: vertically integrated resin houses controlling feedstock supply, and technology licensors specializing in aqueous dispersion stabilization. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure marine coating approvals.
Among Germany-based diversified chemical producers, BASF SE and Evonik Industries AG exemplify the integrated archetype with European formulation networks. Dow Chemical Company anchors North American production through captive epoxy intermediates supply. Huntsman Corporation occupies a position within the high-performance specialty tier.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Huntsman Corporation |
| Hexion Inc. |
| Allnex GmbH |
| Aditya Birla Chemicals Ltd. |
| DIC Corporation |
| Olin Corporation |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Epichlorohydrin substitution for bio-based glycerol derivatives is redirecting feedstock procurement toward Southeast Asian oleochemical processors while compressing margin structures for European resin houses tethered to propylene naphtha crackers. This displacement simultaneously erodes legacy cost advantages in Germany and the Netherlands while rewarding integrated producers with captive glycerin supply.
Pricing Analysis
Volume-discount tiering structures separate certified marine grades from standard construction formulations, with shipyard procurement aggregators capturing 15-20 point spreads over spot buyers. Price differentiation centers on REACH registration status and Lloyd's certification depth, with German and South Korean buyers showing lowest sensitivity due to specification rigidity. Cost compression in mid-tier construction resins is intensifying because Chinese aqueous dispersion capacity is flooding Asian spot markets. Small-scale maintenance contractors in California and New York exhibit highest price sensitivity, migrating to digital marketplaces for transparent benchmark visibility.
Supply Chain Analysis
Inventory lead times for epoxy intermediates have elongated from six to ten weeks as Yangtze River Delta chemical parks face MEE environmental compliance audits. Geographic supply concentration centers on China, Germany, and the United States, with Jiangsu province and Gulf Coast petrochemical corridors anchoring dispersion production. Raw material dependencies draw from propylene derivatives, bisphenol A feedstocks, and specialty amine hardeners. Single-source vulnerability sits with epichlorohydrin supply from integrated propylene oxide producers. Distribution runs through compliance-verification marketplaces in Rotterdam, Hamburg, and Singapore port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne epoxy resin demand follows vessel refurbishment cycles, with shipyard maintenance backlogs in China and Germany signaling trough-to-peak transition momentum.
For Market Incumbents: Shield formulation margins by deepening captive glycerol-epichlorohydrin integration before bio-based feedstock premiums compress. Secure Lloyd's Register and DNV certification renewals ahead of 18-month validation windows to block Asian entrants from marine coating specifications. Prioritize aqueous dispersion stabilization R&D to offset formulation chemist scarcity at legacy European houses. For New Entrants and Emerging Players: Anchor in automotive adhesive white space, where electric vehicle platform specifications are proliferating faster than incumbent capacity expansion in China and Germany. Target wind turbine blade manufacturing segments requiring TÜV-certified low-VOC matrices with limited qualified supplier pools. Lead with digital compliance documentation to bypass distributor relationships in Rotterdam and Singapore procurement channels. For Investors and Strategic Acquirers: REACH authorization timelines for bisphenol A derivatives reshape the acquisition landscape by stranding non-diversified precursor portfolios. Five-to-ten year viability favors resin houses with validated bisphenol F and hydrogenated bisphenol A aqueous systems. Target mid-tier European formulators with REACH-registered product families and marine coating approvals. Watch ECHA substance evaluation announcements as inflection signals for precursor supply security repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Supply | Captive bio-based feedstock access insulates margin compression from propylene volatility. |
| Marine Certification Fast-Track Program | Accelerated Lloyd's Register validation compresses 18-month approval cycles for new entrants. |
| Digital Compliance Platform Integration | Automated VOC verification against CARB and EU Green Deal rules displaces distributor relationships. |
| Automotive Adhesive Capacity Expansion | Dedicated production lines for EV chassis bonding capture lightweighting specification momentum. |
| Alternative Diphenolic R&D Investment | Bisphenol F and hydrogenated bisphenol A systems preempt REACH restriction supply interruption. |
Research Methodology
A standing panel of marine coating procurement directors, automotive Tier 1 adhesive specifiers, shipyard compliance officers, and epoxy formulation chemists provided ongoing calibration across primary interview rounds. Secondary validation drew from customs trade data, ACC and Cefic chemical industry reports, EPA air-quality enforcement records, and ECHA REACH registration databases. Bottom-up segment sizing triangulated against top-down chemical production capacity estimates.
Consistency checks validated volume and value outputs against EIA petrochemical feedstock indices, Yangtze River Delta chemical park production disclosures, and German TÜV certification issuance rates. The analytical framework modeled segmentation across product chemistry tiers, end-use industry verticals, regional regulatory clusters, and distribution channel structures. CAGRs derived from trend extrapolation of shipyard refurbishment cycles, automotive platform rollout schedules, and wind turbine installation pipelines.
Material uncertainties — epichlorohydrin feedstock volatility, ECHA authorization timeline acceleration, MEE enforcement intensity in Jiangsu province — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and substitution technology maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Acrylic Polymer Emulsion Market