
 Nonchlorinated Polyolefins Market | 2026-2036
Nonchlorinated Polyolefins Market Size, Share, and Industry Trends Forecast 2026-2036
Nonchlorinated Polyolefins Market Outlook
Single-source reliance on chlorinated polyolefin feedstock is decoupling from procurement blueprints as formulators diversify resin baskets. Mitsui Chemicals anchors Asian supply through captive metallocene catalyst production. Eastman Chemical Company differentiates via amorphous polyolefin technology for hot-melt adhesive grades. BASF SE leverages polymer blend expertise to serve European automotive tier-1 specifications.
Nonchlorinated polyolefins comprise hydrogenated hydrocarbon polymers synthesized via Ziegler-Natta or metallocene catalysis, exhibiting densities below 0.91 g/cm³ and glass transition temperatures ranging from -70°C to -20°C depending on comonomer content. These materials function primarily as adhesion promoters, tie-layer resins, and compatibilizers in multilayer structures where polar substrates interface with nonpolar polyolefin matrices. Polypropylene grades command the dominant volume position owing to their compatibility with automotive interior lamination protocols, while polymer blends represent the fastest-expanding category as compounders seek single-resin solutions for mixed-polarity substrates. Extrusion technology occupies the largest installed base for nonchlorinated polyolefin processing, though injection molding is gaining share in medical device component fabrication where USP Class VI compliance is required.
EPA oversight under TSCA Section 5 governs new chemical introductions of modified polyolefin architectures in the United States, while REACH Annex XVII restrictions on chlorinated substance content continue reshaping European adhesive formulations. ECHA substance evaluation protocols are extending scrutiny to residual catalyst traces in polymer grades destined for consumer goods contact. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation penalties that erode margin pools.
Market Dynamics
REACH Annex XVII restrictions on chlorinated substance content are forcing automotive adhesive formulators across Germany, France, and Italy to rebuild resin baskets around hydrogenated hydrocarbon polymers. This regulatory compression is decoupling supply chains from legacy chlorinated feedstock dependencies.
Growth Catalysts
- Automotive lightweighting mandates:Tier-1 suppliers in Germany's manufacturing corridor are specifying nonchlorinated polyolefins for interior lamination protocols to meet EU fleet emission targets.
- REACH substance restrictions:ECHA evaluation protocols on residual chlorinated content are redirecting formulation demand toward metallocene-catalyzed hydrogenated alternatives.
- Medical device compliance:USP Class VI certification requirements for injection-molded components are pulling resin selection toward nonchlorinated grades with validated biocompatibility profiles.
Market Restraints
- Metallocene catalyst supply concentration:Asian producers control captive catalyst production, creating input dependency for European compounders.
- Amorphous polyolefin cost premium:Hot-melt adhesive grades require specialized hydrogenation equipment, elevating capital intensity versus conventional chlorinated resins.
- Property gap in high-temperature bonding:Glass transition temperatures capped near -20°C limit deployment in underhood automotive applications where chlorinated alternatives retain performance.
Strategic Opportunities
- Polymer blend innovation:Single-resin solutions for mixed-polarity substrates are capturing share as compounders seek to simplify multilayer structure inventories.
- Indian automotive expansion:PLI scheme incentives for domestic manufacturing are creating specification windows for imported nonchlorinated tie-layer resins.
- Eco-design regulation alignment:EU Green Deal product passport requirements are favoring materials with verifiable halogen-free content for consumer goods contact.
Industry Challenges
- Residual catalyst trace management:ECHA substance evaluation protocols are extending scrutiny to metallocene residues in grades destined for food-contact applications, requiring analytical method investments.
- Multilayer coextrusion reconfiguration:Adhesive laminators must retool die designs and temperature profiles when substituting hydrogenated resins for chlorinated incumbents with different rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonchlorinated Polyolefins Market |
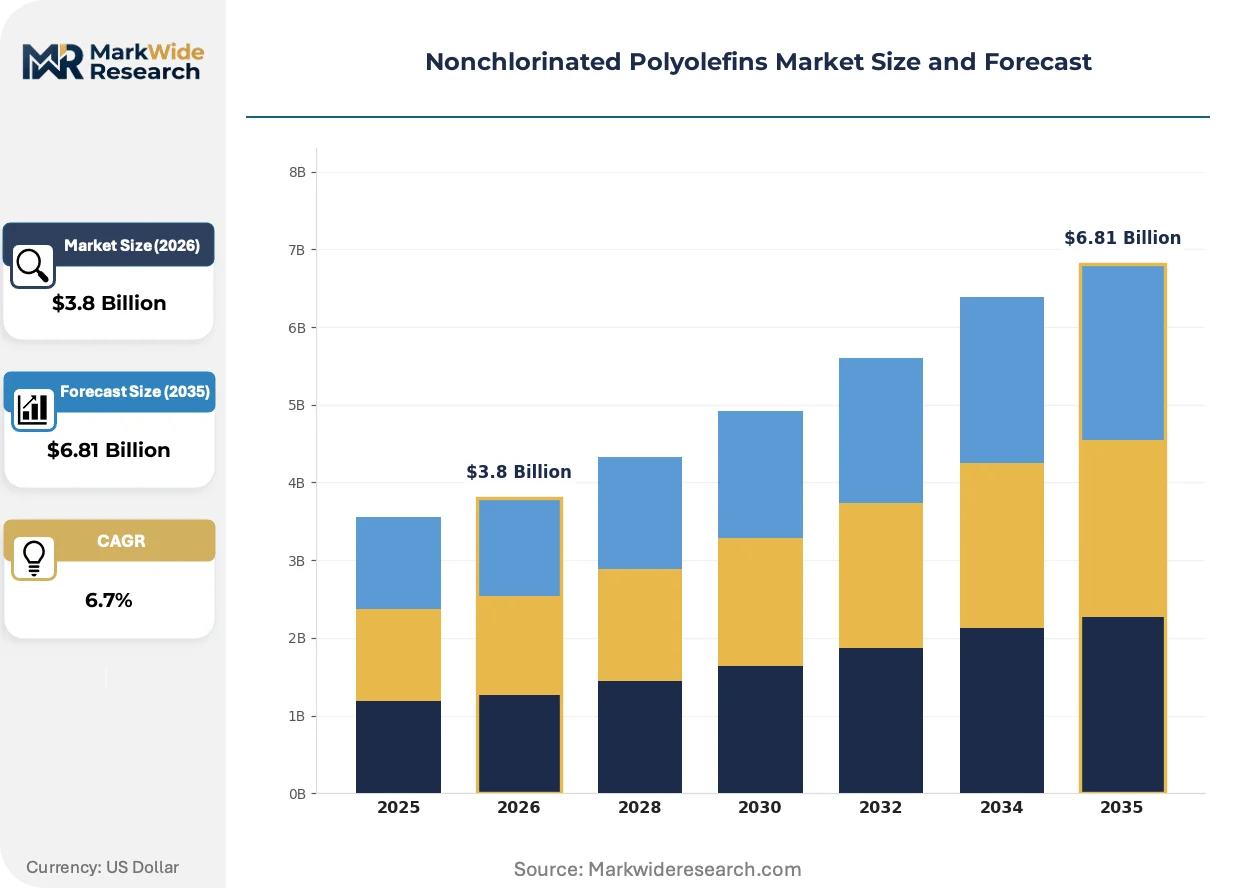
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polybutylene, Polymer Blends Application: Adhesives, Coatings, Sealants, Films End User: Aerospace, Automotive Suppliers, Consumer Goods, Medical Devices Technology: Extrusion, Injection Molding, Blow Molding, Thermoforming |
| Companies Covered | Mitsui Chemicals, Toyobo Co., Ltd., Eastman Chemical Company, BASF SE, Advanced Polymer, Inc., Nippon Paper Industries Co., Ltd., ExxonMobil, Dow Chemical Company, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonchlorinated Polyolefins Market Strategic Shifts
Formulation chemistry is pivoting toward single-resin architectures that eliminate primer layers. Three developments are compressing the competitive window for traditional multi-step bonding processes.
Metallocene-catalyzed polypropylene elastomers are expanding into automotive interior lamination stacks. Tier-1 suppliers in Stuttgart and Wolfsburg are validating these grades for dashboard and door panel substrates. The technology is compressing cycle times by eliminating surface oxidation pretreatment steps previously required for polar adhesion.
ECHA substance evaluation protocols under REACH are extending scrutiny to residual catalyst traces in polymer grades. This regulatory pressure is forcing compounders to invest in analytical certification and supply chain documentation. Medical device and food-contact segments are responding fastest, locking in validated resin sources ahead of formal restriction timelines.
Buyers are consolidating resin specifications across mixed-polarity substrate portfolios. Procurement teams at major automotive OEMs are reducing approved vendor lists from multi-resin solutions to single hydrogenated polyolefin platforms. This concentration is most visible in Germany's supplier ecosystem, where tier-1 laminators face margin compression unless they qualify for preferred supplier status.
Nonchlorinated Polyolefins Market Segmentation
Segmentation in nonchlorinated polyolefins reveals how certification requirements fragment procurement strategies across end-use verticals. Medical device and automotive specifications demand validated biocompatibility and REACH-compliant documentation that consumer goods segments rarely require.
Product Type:
FDA 21 CFR 177.1520 compliance for food-contact polyolefins and USP Class VI certification for medical-grade hydrogenated resins create tiered approval burdens that compounders must navigate before specification.
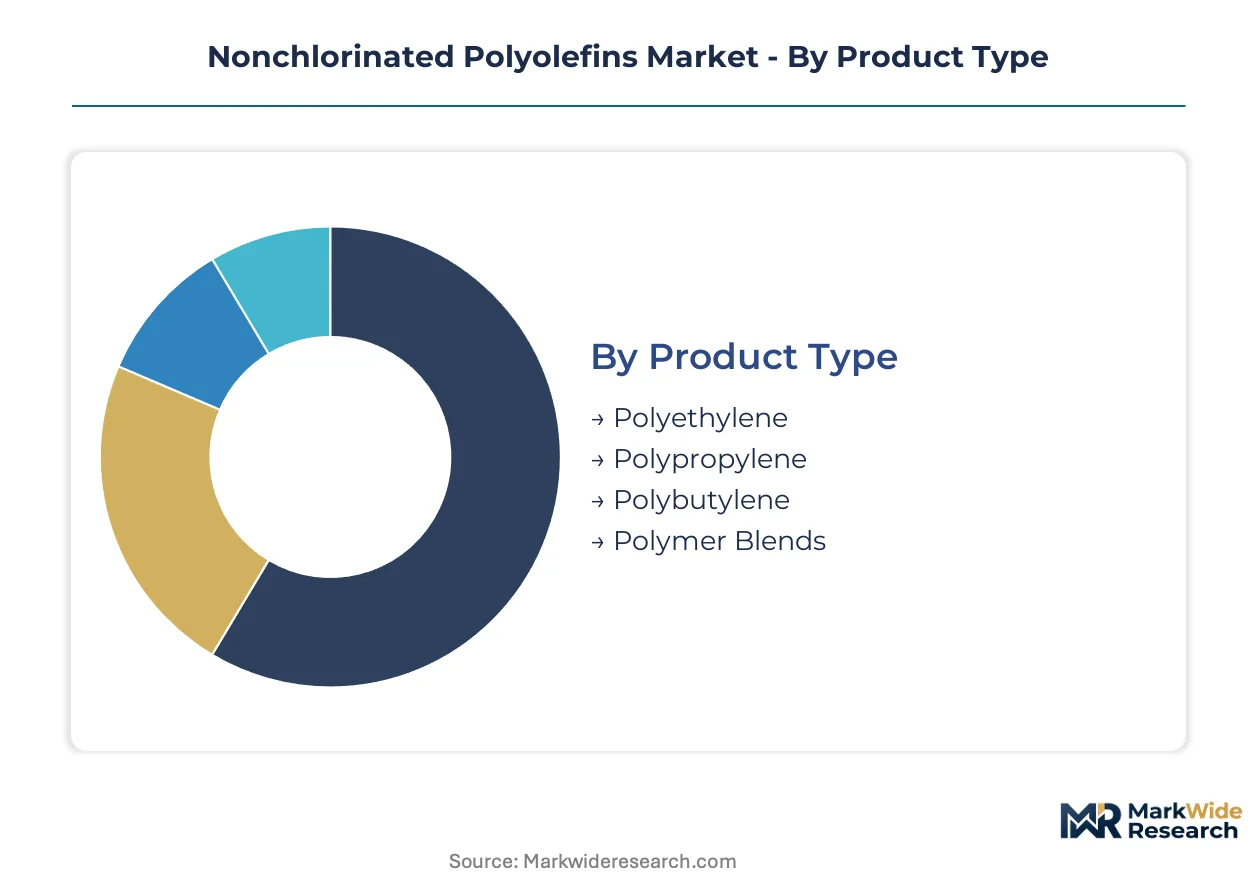
- Polyethylene:Low-density grades synthesized via metallocene catalysis achieve densities below 0.91 g/cm³ with glass transition temperatures near -70°C. Demand concentrates in German automotive interior lamination where REACH Annex XVII restrictions on chlorinated alternatives have forced tier-1 suppliers to rebuild resin baskets around hydrogenated feedstocks.
- Polypropylene:Elastomeric copolymers dominate volume through compatibility with dashboard and door panel substrates in Stuttgart and Wolfsburg manufacturing corridors. ECHA substance evaluation protocols on residual catalyst traces are pushing compounders toward validated supply chains with documented metallocene residue controls.
- Polybutylene:Semi-crystalline grades serve specialized sealant applications requiring intermediate flexibility between polyethylene and polypropylene performance envelopes.
- Polymer Blends:Single-resin solutions for mixed-polarity substrates are capturing procurement consolidation as automotive OEMs reduce approved vendor lists.
Polypropylene sits at the top of the volume ranking, with polymer blends climbing the fastest.
Application:
Cost stratification across application segments mirrors the capital intensity of downstream formulation equipment and the certification documentation required for end-market access.
- Adhesives:Hot-melt grades require specialized hydrogenation equipment that elevates capital intensity versus conventional chlorinated resins. Amorphous polyolefin technology from specialized producers commands premium positioning in automotive bonding stacks where cycle time compression justifies higher input costs.
- Coatings:Thin-film deposition processes for consumer goods contact applications face emerging ECHA scrutiny on residual catalyst traces, requiring analytical method investments that smaller formulators struggle to absorb.
- Sealants:Construction-grade specifications prioritize cost efficiency over certification depth, opening specification windows for non-validated resin sources.
- Films:Multilayer coextrusion protocols in packaging applications demand precise rheology matching that limits qualified supplier pools.
Adhesives command the largest revenue pool, with coatings gaining share fastest on regulatory displacement of chlorinated alternatives.
End User:
Customer-type segmentation reveals divergent procurement power, with consolidated automotive OEMs extracting supply chain documentation that fragmented consumer goods buyers rarely demand.
- Aerospace:FAA-compliant flame resistance specifications limit nonchlorinated polyolefin penetration due to glass transition temperature ceilings near -20°C that underperform in high-heat zones.
- Automotive Suppliers:Tier-1 laminators in Germany's manufacturing corridor face margin compression unless they qualify for preferred supplier status under consolidated resin specifications.
- Consumer Goods:EU Green Deal product passport requirements are favoring materials with verifiable halogen-free content, pulling formulation demand toward certified hydrogenated grades.
- Medical Devices:USP Class VI certification requirements for injection-molded components lock procurement into validated resin sources ahead of formal restriction timelines.
Automotive suppliers anchor the volume base, with medical devices expanding most quickly on compliance-driven specification lock-in.
Technology:
Processing technology segmentation tracks the installed equipment base and the reconfiguration costs adhesive laminators face when substituting hydrogenated resins for chlorinated incumbents with different rheology profiles.
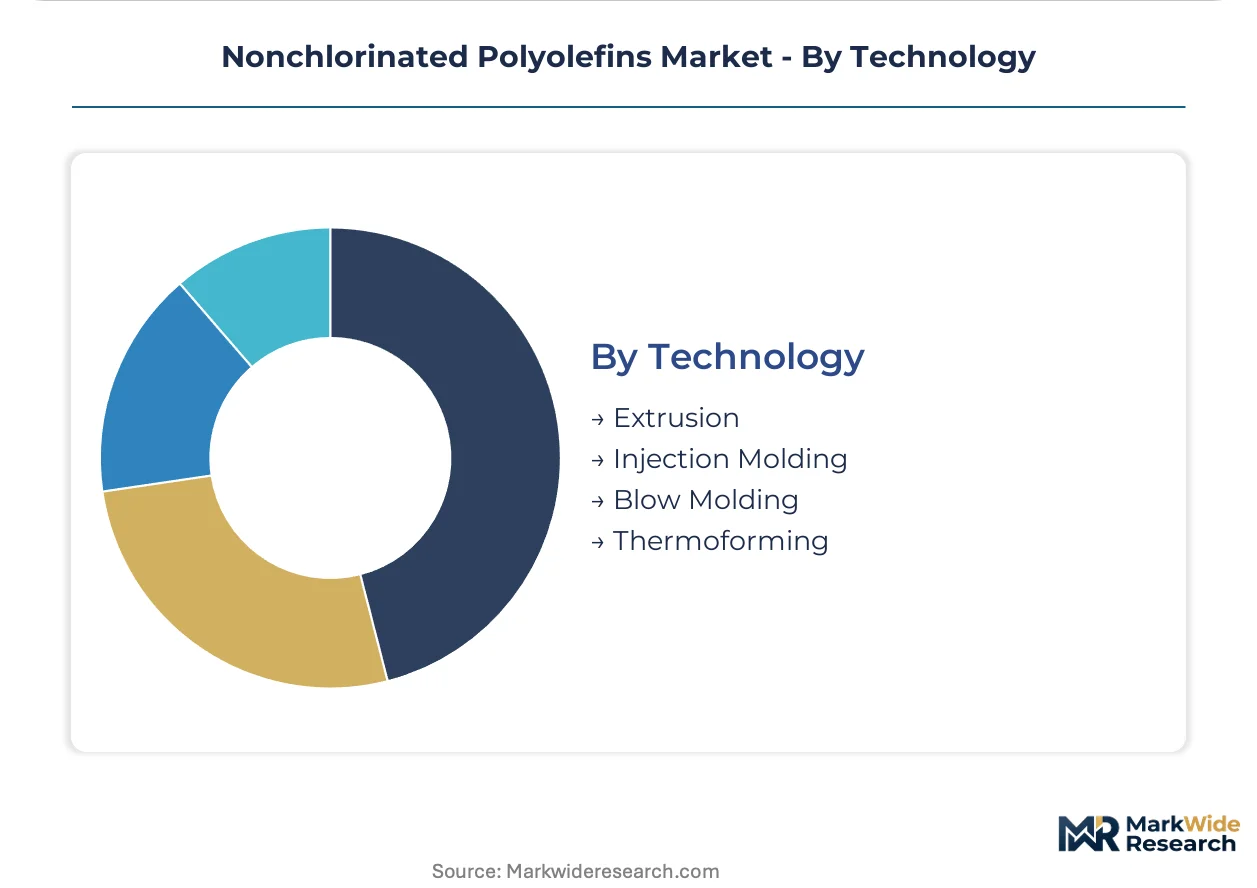
- Extrusion:The largest installed base for nonchlorinated polyolefin processing serves multilayer film and sheet applications where die design retooling represents significant switching costs.
- Injection Molding:Medical device component fabrication requires validated biocompatibility profiles that restrict qualified resin sources and concentrate procurement among documented suppliers.
- Blow Molding:Hollow-part production for packaging applications favors lower-viscosity polyethylene grades with established process windows.
- Thermoforming:Thin-gauge sheet applications in consumer goods contact face emerging catalyst residue scrutiny under ECHA evaluation protocols.
Extrusion holds the dominant installed position, with injection molding ascending fastest on medical device compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor anchors nonchlorinated polyolefin consumption as tier-1 suppliers rebuild resin baskets around hydrogenated feedstocks. REACH Annex XVII enforcement across Stuttgart and Wolfsburg is compressing procurement timelines for validated grades. The regulatory divergence between European ECHA protocols and American EPA oversight is fragmenting formulation standards.
Germany
Dashboard and door panel lamination protocols in Stuttgart and Wolfsburg consume elastomeric polypropylene copolymers as OEMs consolidate approved vendor lists. REACH Annex XVII restrictions on chlorinated substance content force adhesive formulators to source metallocene-catalyzed alternatives with documented residue controls. Bavaria's chemical processing clusters host compounders investing in analytical certification infrastructure.
United States
Medical device injection molders specify USP Class VI certified hydrogenated resins for biocompatible components. EPA oversight under TSCA Section 5 governs new chemical introductions of modified polyolefin architectures. Minnesota's medical technology corridor concentrates procurement among documented suppliers ahead of formal restriction timelines.
China
Automotive interior suppliers in the Yangtze River Delta adopt nonchlorinated tie-layer resins for lightweight bonding stacks. MIIT industrial standards for vehicle emission reductions align material specifications with EU fleet targets. Shanghai's chemical parks host formulators qualifying hydrogenated grades for export-oriented production.
Japan
Metallocene catalyst production concentrates among integrated petrochemical complexes serving Asian adhesive markets. METI guidelines on sustainable manufacturing favor halogen-free content in consumer goods contact applications. Osaka's polymer research institutes collaborate with automotive OEMs on single-resin bonding architectures.
India
Domestic automotive expansion under PLI scheme incentives creates specification windows for imported tie-layer resins. BIS standards for vehicle component safety are converging with REACH-compliant documentation requirements. Tamil Nadu's manufacturing belt attracts compounders establishing localized hydrogenated resin distribution.
Nonchlorinated Polyolefins Market Competitive Environment
Global majors compete with regional champions across catalyst technology and certification depth. The vendor base separates into integrated petrochemical groups with captive metallocene production and specialized compounders focused on validated medical-grade portfolios. Three archetypes dominate: hydrogenation technology specialists, polymer blend innovators, and automotive specification validators. Competitive moves concentrate on backward integration into catalyst supply and geographic licensing partnerships for regional formulation rights.
Within the integrated technology tier, Mitsui Chemicals and Eastman Chemical Company exemplify divergent positioning strategies. Mitsui anchors Asian supply through Japanese-based petrochemical infrastructure. Eastman occupies a position among amorphous polyolefin specialists serving adhesive grade differentiation. BASF SE represents European polymer blend expertise aligned with automotive tier-1 documentation requirements.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Toyobo Co., Ltd. |
| Eastman Chemical Company |
| BASF SE |
| Advanced Polymer, Inc. |
| Nippon Paper Industries Co., Ltd. |
| ExxonMobil |
| Dow Chemical Company |
| LyondellBasell Industries |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive laminators in Germany's Stuttgart-Wolfsburg corridor concentrate procurement volumes, forcing contract-based long-term offtake structures with metallocene-catalyzed resin suppliers. REACH Annex XVII enforcement compresses supplier qualification timelines, embedding certification premiums into negotiated price bands.
Pricing Analysis
Metallocene catalyst cost pass-through dominates hydrogenated polyolefin pricing, with Asian producers controlling captive supply and extracting margin premiums from European compounders. Three-tier pricing structure across USP Class VI certified, REACH-compliant industrial, and non-validated construction grades reflects documentation burden differentials. Pricing pressure stems from automotive OEM vendor-list consolidation squeezing tier-1 laminator margins. Construction-grade buyers exhibit highest price sensitivity, while medical device molders accept premium positioning for validated biocompatibility profiles.
Supply Chain Analysis
Metallocene catalyst supply rests on Japanese and South Korean integrated petrochemical complexes, creating input dependency for European and North American compounders. Hydrogenated hydrocarbon feedstocks and specialized hydrogenation equipment anchor raw material requirements. Single-source vulnerability concentrates in catalyst technology licensing. Distribution runs through regional compounding hubs serving qualified automotive and medical-grade formulation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Annex XVII chlorinated substance restrictions are compressing formulation timelines and consolidating procurement around validated hydrogenated alternatives.
For Market Incumbents: To counter margin compression from automotive OEM vendor-list consolidation, secure backward integration into metallocene catalyst supply through Asian licensing partnerships. Invest in analytical certification infrastructure ahead of ECHA residual trace evaluation protocols tightening. For New Entrants and Emerging Players: Capture specification windows in India's PLI-scheme automotive expansion by establishing localized distribution partnerships for REACH-compliant tie-layer resins. Target medical device injection molding segments where USP Class VI certification creates procurement lock-in and limits qualified supplier pools. For Investors and Strategic Acquirers: Specialty chemical groups with automotive specification expertise are the most active acquirer in this space, seeking polymer blend innovators with validated European tier-1 relationships. Long-term viability hinges on regulatory divergence management capabilities across ECHA and EPA jurisdictions. Watch ECHA substance evaluation protocol expansion timelines as inflection triggers for certification investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive metallocene catalyst production insulates margin pools from Asian supply concentration. |
| Certification Investment | USP Class VI and REACH Annex XVII documentation opens specification-locked automotive and medical segments. |
| Polymer Blend Innovation | Single-resin architectures for mixed-polarity substrates capture procurement consolidation trends. |
| Geographic Licensing Partnership | Regional formulation rights in India and Southeast Asia access PLI-scheme automotive expansion. |
| Analytical Method Development | Residual catalyst trace validation meets ECHA evaluation protocol scrutiny for food-contact applications. |
Study Parameters
Bottom-up automotive and medical device end-use modeling reconciled against top-down metallocene catalyst production tracking forms the analytical core. Primary interviews with tier-1 adhesive laminator procurement directors, compounder technical R&D leads, and medical device molding operations managers combined with secondary validation from ECHA substance evaluation databases, REACH Annex XVII restriction timelines, and customs trade flow records. Triangulation across supply-side capacity announcements and demand-side specification requirements validates volume estimates.
Historical trendline analysis of hydrogenated polyolefin adoption rates across German automotive interior applications established baseline penetration curves. The analytical framework segments by product grade tier, end-use vertical, certification requirement level, and regional production hub across the projection horizon. CAGRs derive from regression analysis of substitution rates for chlorinated alternatives, calibrated against automotive lightweighting mandate compliance deadlines and medical device biocompatification validation cycles.
REACH restriction timeline acceleration, metallocene catalyst supply disruption, and ECHA residual trace protocol expansion are the dominant revision risks. Forecasts embed assumptions on regulatory enforcement consistency and specification consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Thermoplastic Starch (TPS) Market