
 Military Aviation Repair Solutions Market | 2026-2036
Military Aviation Repair Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aviation Repair Solutions Market Insights
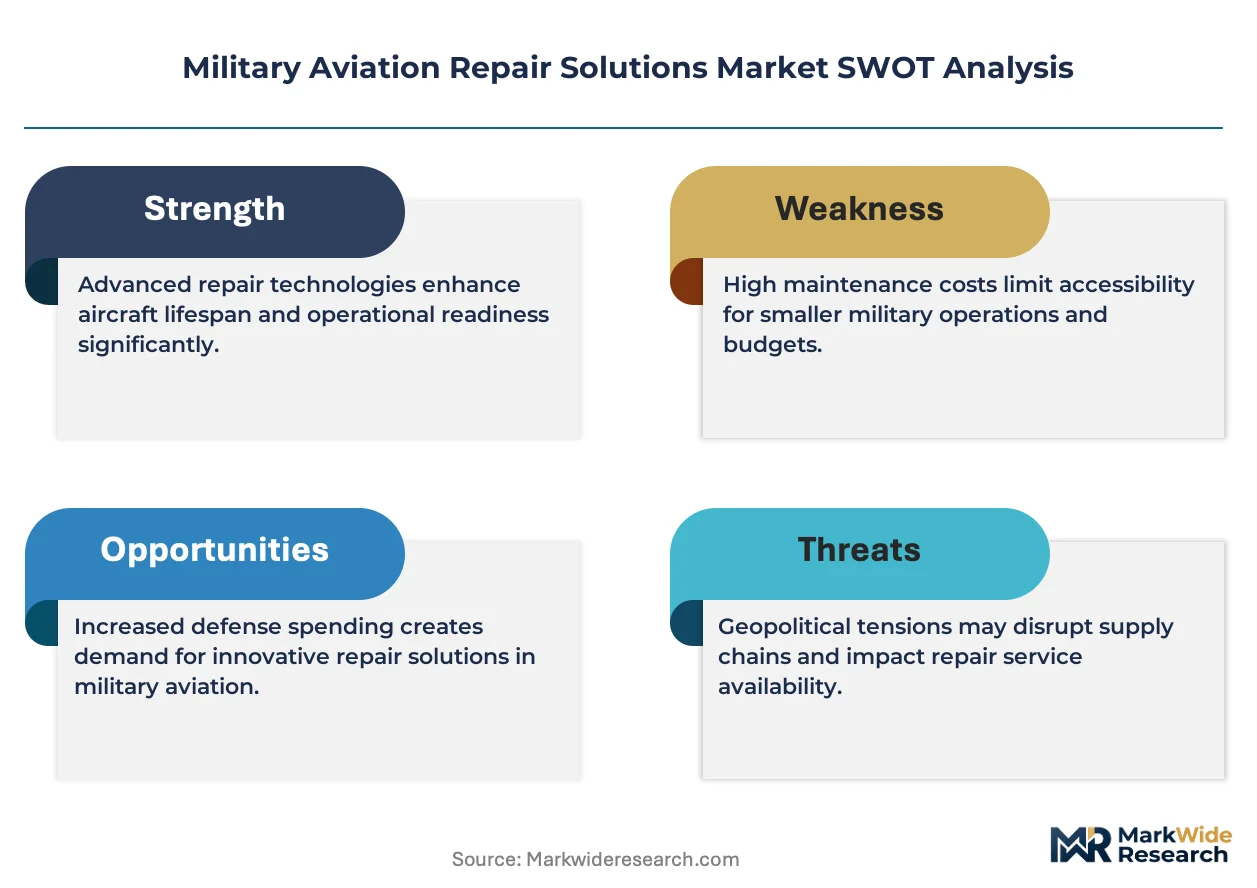
Defense contractors are gaining procurement share as air force units is reorganizing maintenance budgets toward performance-based logistics contracts. Boeing sustains depot-level repair capacity across multiple domestic military installations. AAR Corp dominates component testing and airframe refurbishment for rotary-wing platforms. ST Engineering positions its Singapore and US facilities to capture contracted support work for regional allied militaries.
Military aviation repair solutions encompass the technical restoration, overhaul, and certification of airframes, propulsion systems, avionics suites, and mission-critical software to original equipment manufacturer specifications and military airworthiness standards. These services restore flight-ready status to platforms operating beyond their original design service life, ensuring mission availability rates meet operational command requirements. Engine overhaul and structural repair command the largest revenue pools given the capital intensity of turbine disassembly and airframe fatigue remediation. Depot repair services are expanding fastest as armed forces outsource fixed-base maintenance to reduce in-house infrastructure costs. Avionics refurbishment concentrates margin where software update cycles for mission computers and electronic warfare suites outpace hardware replacement intervals.
The FAA issues airworthiness directives governing civil-military dual-use components, while the Department of Defense mandates contractor logistics support performance metrics through its acquisition regulations. The EPA oversees hazardous material handling in coating removal and surface treatment processes at military overhaul facilities. Stakeholders must monitor how the Pentagon recalibrates sustainment funding between organic depot capacity and contractor-operated facilities as fleet modernization priorities shift.
Market Dynamics
Performance-based logistics contracts are consolidating sustainment spending around contractor-operated depot facilities, compressing organic military maintenance capacity as defense agencies prioritize flight-hour availability over asset ownership.
Growth Catalysts
- Airworthiness Directive Intensification:The FAA and Department of Defense are tightening component traceability mandates for refurbished parts, forcing upgrade investments that expand certified repair vendor pools.
- Fourth-Generation Fleet Extension:Air forces are deferring fighter replacement programs, directing sustainment budgets toward structural life-extension programs for aging tactical aircraft platforms.
- Rotary-Wing Utilization Surge:Military helicopter flight hours in counter-insurgency and maritime patrol roles are accelerating component wear rates, driving demand for dynamic component overhaul services.
Market Restraints
- Specialized Alloy Supply Concentration:Nickel-based superalloys for turbine blade restoration concentrate among a limited supplier base, exposing repair facilities to input cost volatility and delivery uncertainty.
- Depot Infrastructure Lock-In:Military customers face high switching costs when migrating from organic maintenance facilities to contractor logistics support, slowing contract reallocation.
- Technical Data Rights Friction:Original equipment manufacturers restrict access to proprietary repair manuals and software diagnostics, limiting third-party depot capabilities for avionics refurbishment.
Strategic Opportunities
- Unmanned Aerial Vehicle Sustainment:Military drone fleets lack established depot repair infrastructure, creating white space for contractors to develop predictive maintenance protocols for unmanned platforms.
- Allied Military Contracting:NATO member states and Pacific allies are outsourcing fighter and transport aircraft overhaul to US-based facilities, expanding addressable contract volume beyond domestic Pentagon spending.
- Additive Manufacturing Qualification:The FAA is developing airworthiness certification pathways for 3D-printed replacement components, enabling localized production of obsolete structural parts without original tooling.
Industry Challenges
- Certified Workforce Scarcity:Airframe and powerplant mechanics with military security clearances and turbine-specific expertise are in short supply, constraining depot throughput expansion.
- Legacy System Integration Complexity:Digital mission computer upgrades must interface with analog wiring harnesses and mechanical flight control systems, extending software validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aviation Repair Solutions Market |
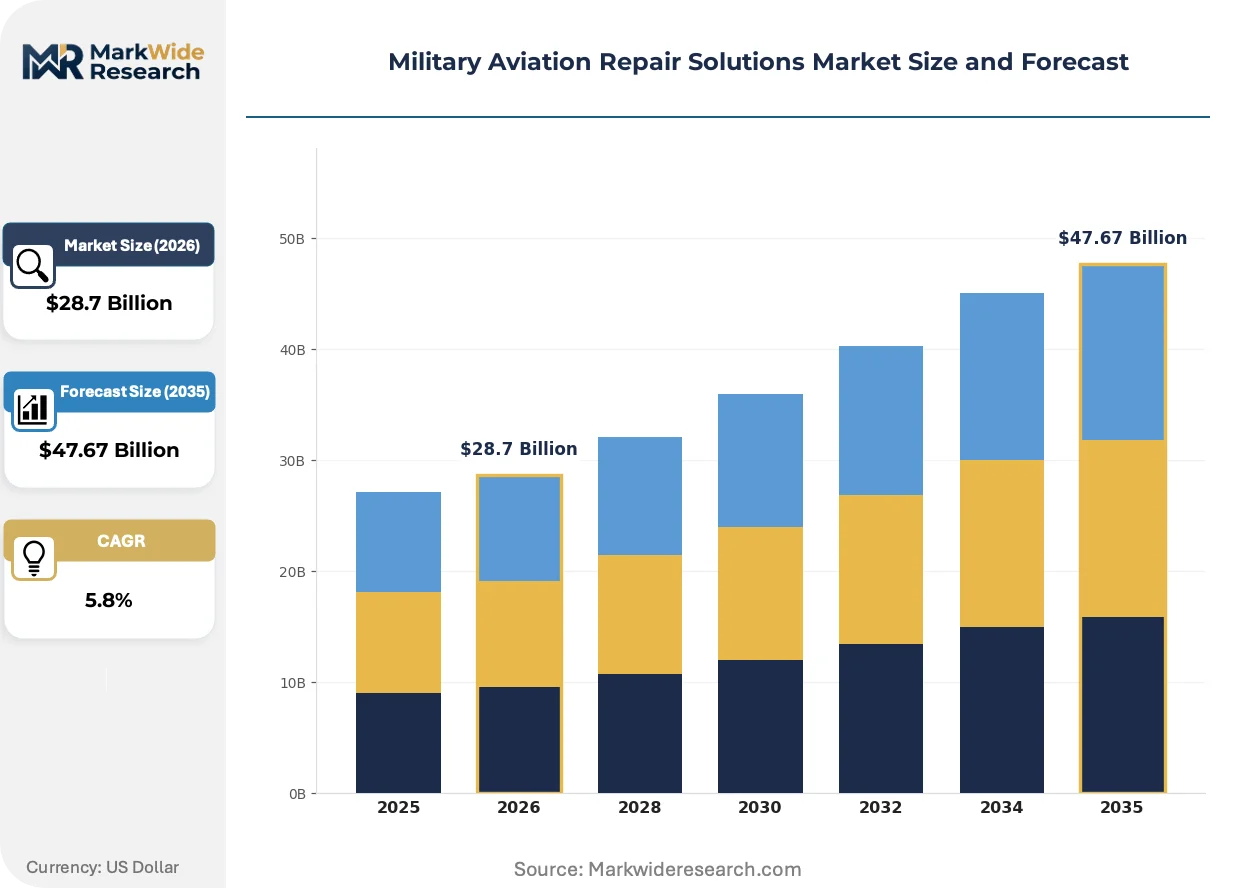
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Engine Overhaul, Avionics Refurbishment, Structural Repair, Component Testing, Software Update Service Delivery Model: On-site Maintenance, Depot Repair, Mobile Repair Teams, Contracted Support Aircraft Category: Fixed-Wing Fighters, Rotary-Wing Helicopters, Unmanned Aerial Vehicles, Strategic Bombers End User: Air Force Units, Naval Aviation Wings, Defense Contractors, Training Academies |
| Companies Covered | Lockheed Martin Corporation, Boeing, BAE Systems, Raytheon Technologies, Northrop Grumman Corporation, AAR Corp, ST Engineering, Lufthansa Technik, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aviation Repair Solutions Market Trends and Innovations
Digital thread technologies are penetrating military aviation sustainment, creating continuous data flows between flight operations, predictive analytics platforms, and depot scheduling systems that compress maintenance turnaround intervals.
Digital twin modeling is decomposing traditional scheduled overhaul intervals by enabling real-time structural health monitoring of airframe fatigue, flight-line sensor networks feed stress accumulation data to depot planners, and this capability is compressing unnecessary component replacements while concentrating repair capacity on actual wear patterns.
The Department of Defense is mandating contractor logistics support performance metrics through acquisition regulation updates, binding payment structures to aircraft availability rates rather than labor hours consumed, and fixed-wing transport operators are restructuring contract terms fastest to align fiscal outflows with operational output.
Defense procurement offices are unbundling hardware refresh cycles from software sustainment, separating avionics suite upgrade contracts from airframe depot visits, and United States-based tactical aircraft units are piloting this disaggregation to accelerate electronic warfare capability insertion without grounding platforms for full structural overhaul.
Military Aviation Repair Solutions Market Segmentation
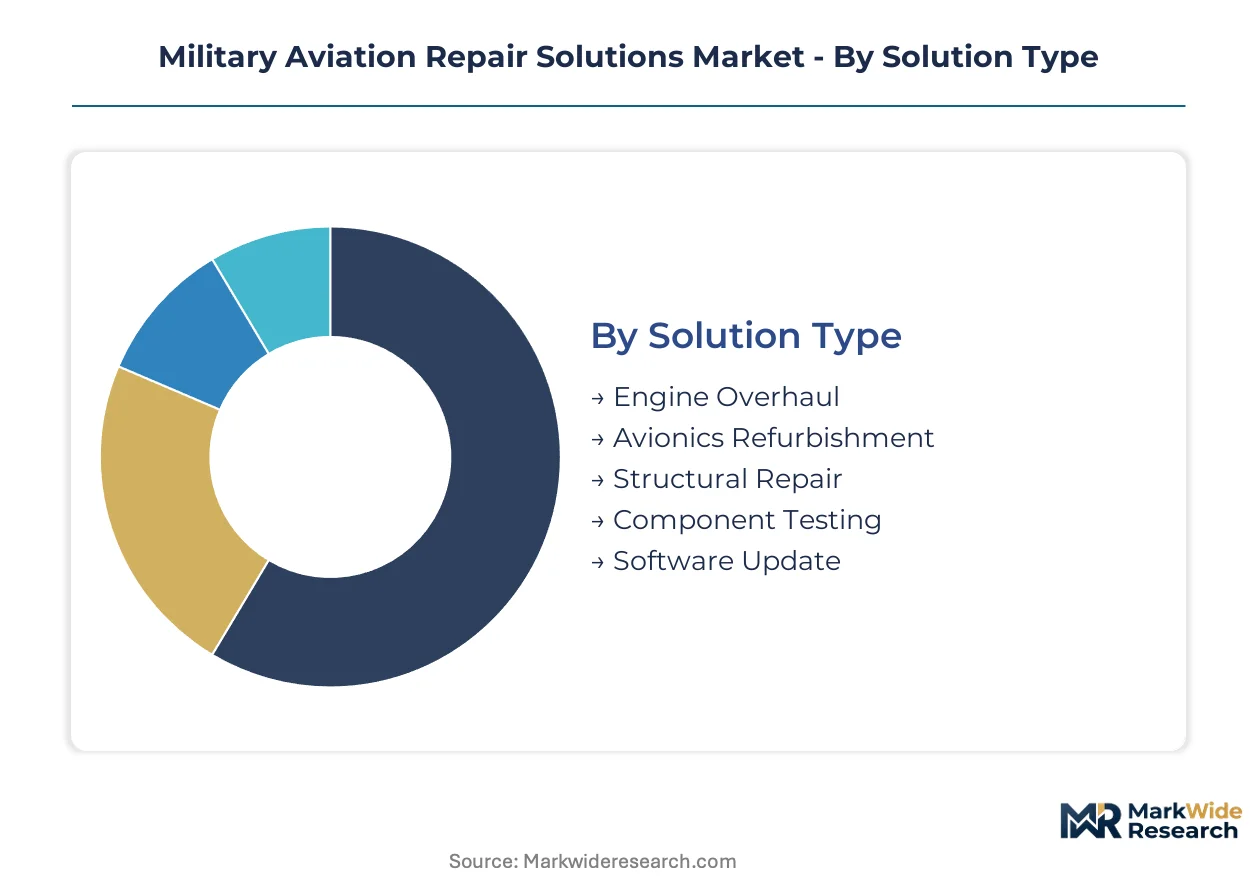
Military aviation repair solutions fragment across technical disciplines, service modalities, platform types, and customer organizations. Understanding these segment boundaries clarifies where capital intensity concentrates, where outsourcing pressure builds fastest, and which capability gaps create procurement friction.
Solution Type:
Engine overhaul and structural repair face the strongest substitution pressure from additive manufacturing and modular component replacement, while avionics refurbishment resists substitution due to proprietary software lock-in.
- Engine Overhaul:Turbine disassembly, hot-section inspection, and blade reconditioning using nickel-based superalloys demand specialized vacuum furnaces and coordinate measuring machines. The United States Air Force concentrates demand through performance-based logistics contracts at Tinker Air Force Base and private depots, constrained by certified mechanic shortages and alloy supply volatility.
- Avionics Refurbishment:Mission computer upgrades, electronic warfare suite modernization, and software patch validation for analog-digital hybrid architectures. Naval aviation wings in the United States drive concentrated procurement, facing extended validation timelines from legacy system integration complexity.
- Structural Repair:Fatigue crack remediation, corrosion treatment, and airframe life-extension through bonded composite patches and metallic reinforcement.
- Component Testing:Non-destructive inspection, functional validation, and airworthiness certification of refurbished hydraulic, pneumatic, and electrical subsystems.
- Software Update:Flight control law modifications, navigation database refreshes, and cybersecurity patch implementation for mission-critical avionics.
Engine overhaul anchors the volume base while avionics refurbishment gains share at the steepest rate.
Service Delivery Model:
Cost tier stratification separates capital-intensive depot infrastructure from variable-cost mobile and on-site alternatives, with contracted support capturing margin through availability guarantees.
- Depot Repair:Fixed-base facilities with specialized tooling for deep structural and propulsion work, governed by FAA airworthiness directives and DoD acquisition regulations. Concentrated in the United States at military installations and contractor-operated sites, facing infrastructure lock-in that slows contract migration.
- Contracted Support:Long-term performance-based agreements binding payment to flight-hour availability rather than labor inputs. Defense contractors in the United States dominate this segment, with payment structures restructuring fastest around fixed-wing transport operators.
- On-site Maintenance:Flight-line servicing, pre-flight inspections, and minor component replacement at operational bases.
- Mobile Repair Teams:Deployable technical units providing intermediate-level maintenance in expeditionary or austere environments.
Depot repair commands the capital base while contracted support climbs the fastest as procurement shifts toward operational output metrics.
Aircraft Category:
Platform maturity curves determine repair intensity, with aging fourth-generation fighters requiring life-extension interventions and unmanned systems lacking established sustainment infrastructure.
- Fixed-Wing Fighters:Tactical aircraft including F-15, F-16, and F/A-18 variants undergoing structural life-extension programs and avionics modernization. United States Air Force units concentrate demand, with sustainment budgets expanding as replacement programs defer.
- Rotary-Wing Helicopters:Military helicopters in counter-insurgency and maritime patrol roles accumulating accelerated component wear. United States Army and Navy aviation wings drive overhaul demand for dynamic components and airframes.
- Unmanned Aerial Vehicles:Military drone fleets requiring predictive maintenance protocol development and rapid turnaround for high-utilization platforms.
- Strategic Bombers:Long-range strike aircraft with extended service lives demanding specialized depot capacity for large airframe structures.
Fixed-wing fighters anchor the volume base while unmanned aerial vehicles expand most quickly from minimal installed infrastructure.
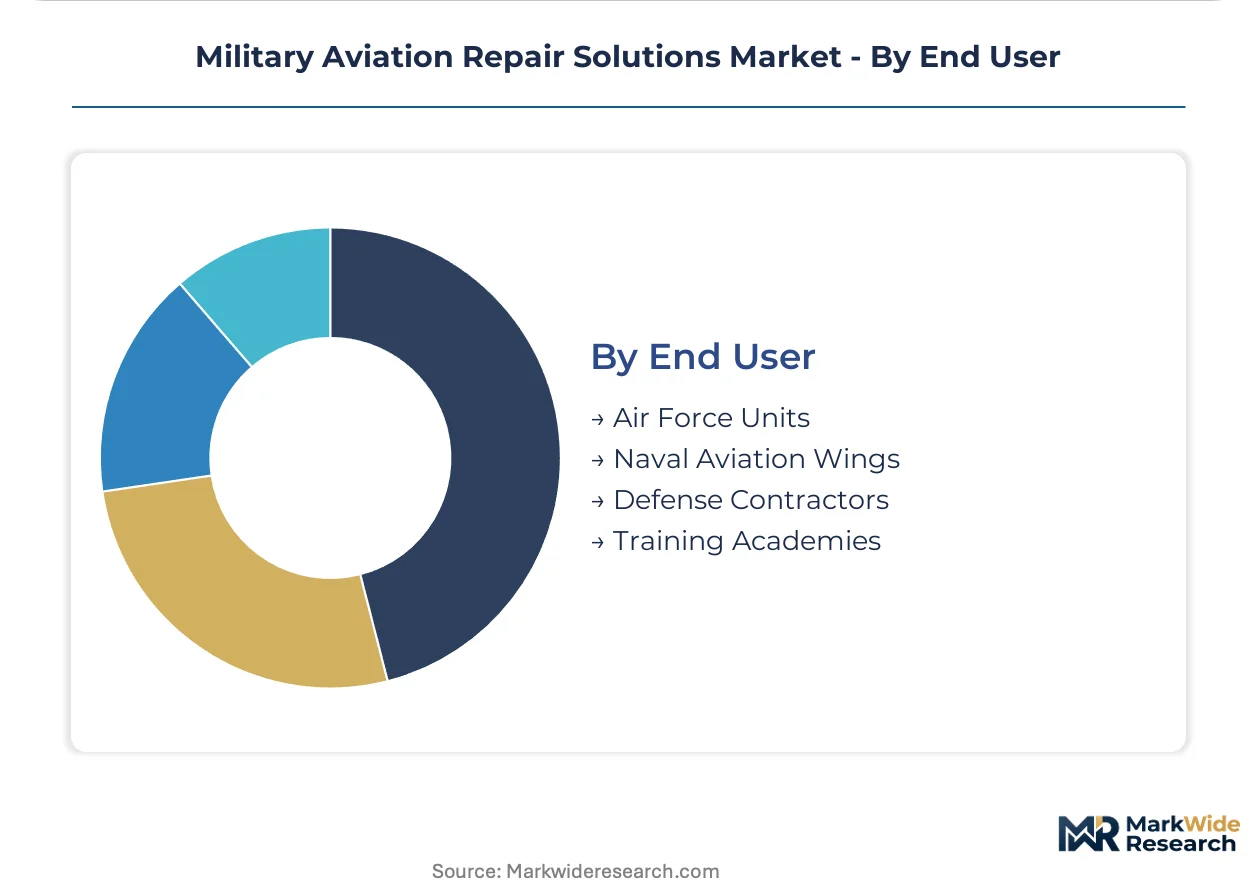
End User:
Customer type determines procurement authority, with defense contractors gaining share as military units reorganize maintenance budgets toward outsourced logistics.
- Air Force Units:Organic and contracted sustainment for fighter, bomber, and mobility aircraft fleets, with the United States Air Force representing the largest single customer.
- Naval Aviation Wings:Carrier-based and maritime patrol aircraft maintenance, concentrated in United States Navy and Marine Corps operations.
- Defense Contractors:Prime and subcontractors assuming depot operations through performance-based logistics contracts, with Boeing and AAR Corp capturing significant United States-based volume.
- Training Academies:Flight school aircraft maintenance for pilot training platforms with high utilization rates and accelerated wear cycles.
Air Force units anchor the volume base while defense contractors gain share at the steepest rate through contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based depots export contracted overhaul services to NATO allies and Pacific partners, with Singapore and Germany emerging as secondary technical centers for regional military aviation sustainment.
United States
The Pentagon operates the world's largest military aircraft inventory, driving depot-level demand at Tinker Air Force Base and contractor-operated facilities. The FAA and Department of Defense enforce tightening component traceability mandates through airworthiness directives. Oklahoma and Georgia host concentrated structural repair capacity for aging fighter fleets.
Germany
The Luftwaffe maintains fourth-generation Tornado and Eurofighter fleets requiring life-extension programs and avionics modernization. EASA and national military aviation authorities coordinate certification standards for dual-use components. Bavaria and Lower Saxony cluster specialized turbine overhaul facilities serving domestic and allied European air forces.
United Kingdom
Royal Air Force units outsource increasing sustainment volumes to contractor logistics support agreements for Typhoon and F-35 platforms. The UK Military Aviation Authority publishes airworthiness regulations governing refurbished component certification. Wiltshire and Lancashire house deep maintenance infrastructure for strategic bomber and transport fleets.
Singapore
The Republic of Singapore Air Force leverages regional MRO hub status to capture contracted support work from ASEAN militaries and Pacific allies. The Civil Aviation Authority of Singapore aligns military airworthiness standards with international certification protocols. Changi and Seletar aerospace parks concentrate rotary-wing and fixed-wing depot capacity for regional export.
Israel
Israeli Air Force technical units develop indigenous depot capabilities for F-15 and F-16 structural life-extension programs alongside unmanned aerial vehicle sustainment. The Israeli Ministry of Defense mandates performance-based logistics metrics for contractor maintenance agreements. Central district facilities near Tel Aviv specialize in avionics refurbishment and mission computer upgrades for domestic and export customers.
Military Aviation Repair Solutions Market Competitive Landscape
Player mix skews toward defense primes with captive depot infrastructure, creating a tiered structure where full-service integrators command performance-based logistics contracts and specialized component shops capture niche testing and refurbishment work. Strategic archetypes include platform-agnostic sustainment integrators, OEM-affiliated depot operators, and independent component specialists. Consolidation through vertical capability acquisition and geographic expansion into allied military markets represent dominant competitive vectors.
Among US-based defense contractors, Boeing, Lockheed Martin Corporation, and Northrop Grumman Corporation exemplify the integrated prime archetype, occupying positions that bind airframe manufacturing heritage with depot-level repair authority. These entities sit within the top tier of performance-based logistics contracting, representing the consolidation pattern where manufacturing-origin firms capture sustainment spend through bundled procurement vehicles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Boeing |
| BAE Systems |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| AAR Corp |
| ST Engineering |
| Lufthansa Technik |
| Airbus SE |
| Others |
Pricing and Supply Chain Analysis
180-day nickel-based superalloy lead times from specialty foundries in the United States and Germany compress pricing power for turbine blade reconditioning services while amplifying cost pass-through negotiations between depot operators and defense procurement offices. This inventory pressure concentrates margin control among suppliers with vacuum furnace capacity and FAA-certified welding protocols.
Pricing Analysis
Fourth-generation fighter sustainment commands a 15-25% premium over rotary-wing depot work due to structural fatigue complexity and airworthiness directive compliance burdens, while unmanned aerial vehicle repair services trade at standard-tier rates reflecting nascent certification pathways. Pricing stratifies across OEM-authorized depots, independent certified facilities, and expeditionary mobile teams based on technical data rights access and security clearance tiers. Cost compression in structural repair is intensifying as additive manufacturing qualifications expand qualified vendor pools for obsolete component fabrication. Air Force units exhibit highest price sensitivity for routine engine overhauls, whereas naval aviation wings prioritize availability guarantees over unit cost minimization for carrier-based platforms.
Supply Chain Analysis
Straits of Malacca transit risk for specialty alloy shipments from Japanese and South Korean mills exposes United States depot operators to quarterly input volatility for turbine blade restoration. The military aviation repair supply chain draws from concentrated nickel superalloy production in the United States, Germany, and Japan, with cobalt-chromium coatings sourcing from Canadian and Australian refiners. Single-source vulnerability concentrates in vacuum heat treatment services for hot-section components, where only three domestic facilities maintain DoD security clearances. Distribution runs through prime contractor logistics networks rather than open market procurement, with Boeing and Lockheed Martin captive supply chains dominating alloy inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military aviation repair solutions sit in early-cycle expansion as unmanned platform sustainment infrastructure remains largely unbuilt and allied outsourcing contracts accelerate. Performance-based logistics penetration in NATO allied fleets provides the adoption tailwind justifying capacity positioning ahead of demand crystallization.
For Market Incumbents: Compound depot-level advantage by acquiring FAA-certified additive manufacturing specialists before 3D-printed component pathways mature, and deepen backward integration into nickel superalloy recycling to offset raw material volatility from limited supplier bases. Threat substitution from predictive maintenance algorithms reducing unscheduled depot visits demands software capability investment alongside hardware refurbishment expertise.
For New Entrants and Emerging Players: Military airworthiness certification fast-tracks through partnership with established primes offer the most penetrable entry vector for unmanned aerial vehicle predictive maintenance protocols, where no incumbent possesses entrenched infrastructure. White space concentrates in ASEAN military contracting through Singapore-based facilities, and in software-defined avionics refresh cycles that separate from airframe depot visits. Go-to-market positioning should emphasize flight-hour availability guarantees rather than labor-rate competitiveness.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because performance-based logistics contracts concentrate spending around integrated primes with security clearance infrastructure and technical data rights. Acquisition targets should display dual-use civil-military certification breadth and captive alloy supply relationships. The signal to watch is Pentagon budget reallocation between organic depot capacity and contractor logistics support as fleet modernization priorities shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contract Expansion | Aligns fiscal outflows with operational output metrics for United States Air Force fighter wings. |
| Additive Manufacturing Qualification Investment | Captures FAA certification pathways for 3D-printed structural components without original tooling. |
| Allied Military Facility Geographic Expansion | Positions Singapore and Germany depots to capture NATO and ASEAN outsourcing volumes. |
| Technical Data Rights Acquisition | Unblocks proprietary repair manual access for avionics refurbishment capability expansion. |
| Certified Workforce Pipeline Development | Addresses airframe and powerplant mechanic scarcity constraining depot throughput expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, incorporating depot operations directors at Tinker Air Force Base and contractor-operated facilities, procurement officers from naval aviation wings, turbine overhaul engineers with FAA certification credentials, and defense acquisition specialists managing performance-based logistics contracts. Secondary validation drew from Department of Defense acquisition regulations, FAA airworthiness directive filings, EPA hazardous material handling compliance records, and SEC 10-K disclosures from prime defense contractors. Bottom-up segment sizing triangulated against top-down Pentagon sustainment budget allocations.
Across the projection horizon, the analytical framework modeled engine overhaul, avionics refurbishment, structural repair, and software update segments against service delivery modalities including depot repair, contracted support, and mobile repair teams. Platform-level granularity captured fixed-wing fighter, rotary-wing helicopter, unmanned aerial vehicle, and strategic bomber categories. CAGRs were derived from flight-hour accumulation projections, fleet age distributions, and outsourcing penetration curves. Industry-specific forecast inputs included nickel superalloy price indices and certified mechanic graduation rates from military technical training pipelines.
Underlying assumptions cover sustained fourth-generation fleet extension decisions, allied outsourcing appetite, and additive manufacturing regulatory acceptance timelines, with deviation risk concentrated in Pentagon budget reallocation between organic and contractor depot capacity. Practitioners should keep alternative scenarios live as unmanned platform sustainment infrastructure buildout and technical data rights litigation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market