
 North America Aerospace Maintenance Chemical Market | 2026-2036
North America Aerospace Maintenance Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aerospace Maintenance Chemical Market Analytics
MIL-PRF-680 specification-grade solvent demand is collapsing toward lower-VOC alternatives as environmental compliance tightens across North American aviation. Eastman Chemical Company leverages its specialty fluid portfolio to capture reformulation contracts from legacy solvent users. The Dow Chemical Company anchors regional supply through its integrated hydrocarbon processing network. Henkel AG & Co. KGaA differentiates via surface-treatment chemistries certified to Boeing and Airbus material specifications.
North America aerospace maintenance chemicals encompass formulated products used to clean, protect, lubricate, and seal aircraft surfaces, engines, and interiors, typically meeting flash-point thresholds above 140°F and compatibility requirements with aluminum, titanium, and composite substrates. Their primary purpose is to restore airworthiness, prevent corrosion-induced fatigue, and extend component life between overhaul cycles. Cleaning agents lead product-type revenue as operators face shorter turnaround windows between flights, while corrosion inhibitors represent the fastest-growing category driven by salt-laden coastal operating environments. Among end users, maintenance providers command the largest volume share due to outsourced MRO growth, though airlines are building captive chemical management programs to reduce per-flight-hour costs.
The EPA regulates solvent emissions under NESHAP standards, while the FAA mandates material flammability and airframe compatibility through its Parts 25 and 43 certification pathways. Health Canada and PMRA impose parallel restrictions on biocide-containing formulations used in aircraft potable water systems, creating a dual-compliance burden for cross-border suppliers. Stakeholders must monitor pending EPA rulemakings on perchloroethylene and trichloroethylene phase-downs, as these solvents remain embedded in legacy depainting and degreasing protocols at military and commercial depots.
Market Dynamics
The EPA's NESHAP solvent emission standards are forcing reformulation across every major product category, collapsing demand for legacy chlorinated degreasers while creating immediate procurement pressure for compliant alternatives in military and commercial depots alike.
Growth Catalysts
- FAA Part 25 certification pathways:Updated material flammability testing protocols expand approved chemical lists, enabling broader substitution of restricted solvents in interior maintenance applications.
- Salt-laden coastal operating environments:Aircraft based near the Gulf of Mexico and Atlantic seaboard drive accelerated corrosion inhibitor consumption as operators shorten protective treatment intervals.
- Texas and Arizona MRO clusters:Concentrated heavy maintenance capacity in these southwestern states generates localized chemical demand spikes tied to aging fleet refurbishment cycles.
Market Restraints
- Specialty additive cost volatility:Fluoropolymer and rare earth corrosion inhibitor feedstocks face price instability from concentrated upstream supply.
- Dual-jurisdiction compliance burden:Cross-border suppliers serving US and Canadian operators must satisfy parallel EPA and Health Canada/PMRA biocide registration requirements.
- Aqueous system performance gaps:Water-based cleaners struggle to match solvent-based products on drying speed and residue-free performance for precision avionics cleaning.
Strategic Opportunities
- Canadian defense fleet modernization:Royal Canadian Air Force procurement of used Australian F-18s and new fighter acquisitions expand northern MRO chemical demand.
- EPA perchloroethylene phase-down:Pending rulemakings create regulatory tailwind for suppliers offering qualified drop-in replacements in depainting operations.
- Biobased surfactant convergence:Integration of agricultural-derived cleaning agents with existing aerospace certification infrastructure opens formulation differentiation paths.
Industry Challenges
- Qualified chemist scarcity:Formulation specialists capable of navigating MIL-PRF-680 specification transitions command premium compensation, constraining R&D bandwidth at mid-tier suppliers.
- Legacy system integration friction:New low-VOC chemistries require recalibration of automated spray systems and waste handling infrastructure at established military depots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aerospace Maintenance Chemical Market |
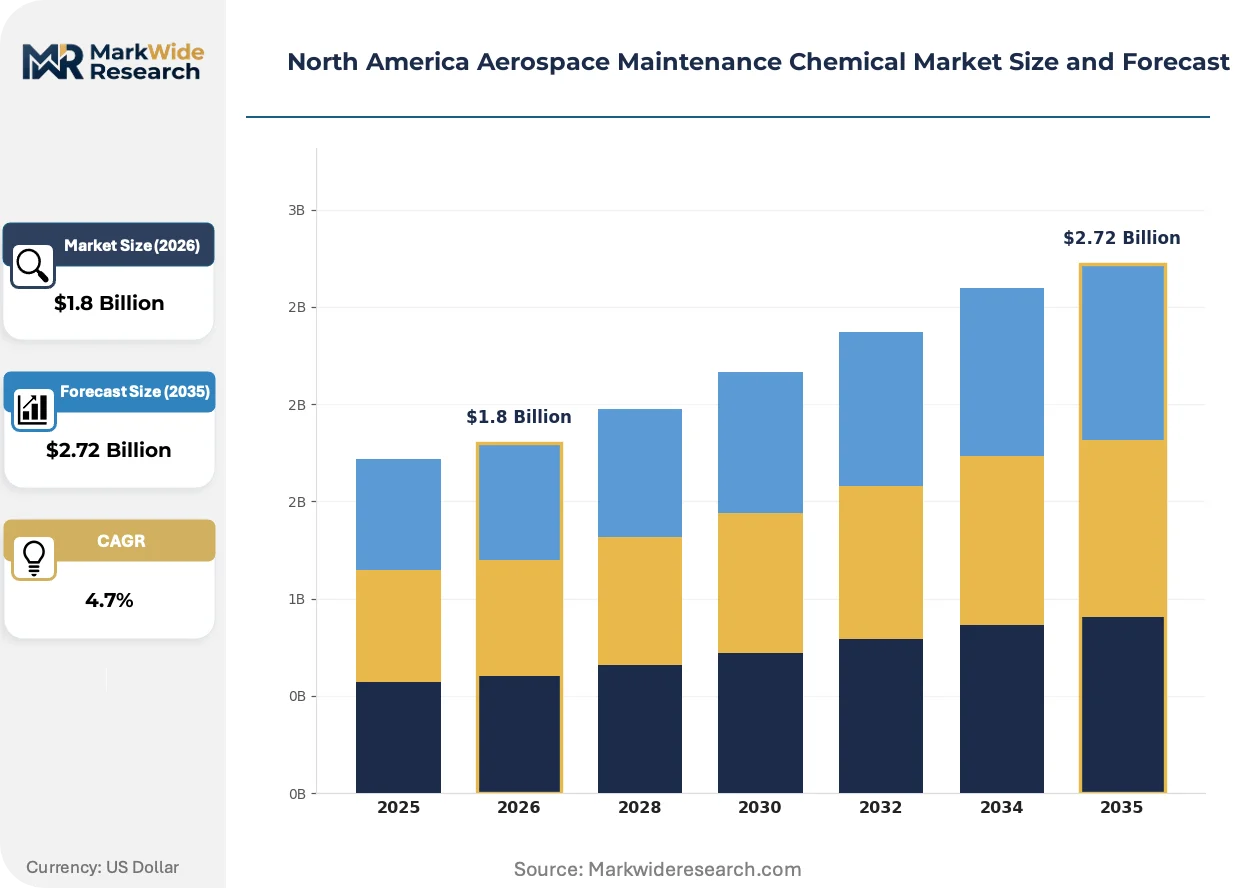
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Agents, Corrosion Inhibitors, Sealants, Lubricants End User: Aerospace Manufacturers, Maintenance Providers, Repair Stations, Airlines Application: Interior Cleaning, Exterior Cleaning, Engine Maintenance, Surface Protection Packaging Type: Bulk Containers, Spray Bottles, Pouches, Cans |
| Companies Covered | Eastman Chemical Company, Arrow Solutions, The Dow Chemical Company, Nexeo Solutions, Aircraft Spruce and Specialty Co., Exxon Mobil Corporation, 3M Company, Aviation Chemical Solutions, Inc., Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aerospace Maintenance Chemical Market Evolving Landscape
Reformulation imperatives are compressing product development cycles while opening technical pathways previously blocked by incumbent solvent economics. Three interconnected developments define the current innovation landscape.
Microemulsion cleaning systems are miniaturizing surfactant structures to penetrate tight-tolerance engine components without residue buildup. Airlines with narrow turnaround windows adopt these formulations fastest, particularly at hub operations where gate-time constraints are tightest. The technology is miniaturizing droplet size distributions, enabling water-based products to match solvent penetration in previously inaccessible geometries.
EPA pending rulemakings on perchloroethylene and trichloroethylene phase-downs are accelerating qualification programs for replacement chemistries. Military depots with embedded legacy depainting infrastructure face the steepest compliance cliffs. Southwestern US maintenance clusters are responding first, driven by state-level air quality management district pressure叠加 federal timelines.
Airlines are consolidating chemical procurement under centralized technical management functions, displacing decentralized site-level purchasing. Maintenance providers face margin compression as airline captive programs capture volume leverage. This concentration is most visible among US legacy carriers building dedicated aerospace chemicals teams to manage specification compliance directly.
North America Aerospace Maintenance Chemical Market Segmentation
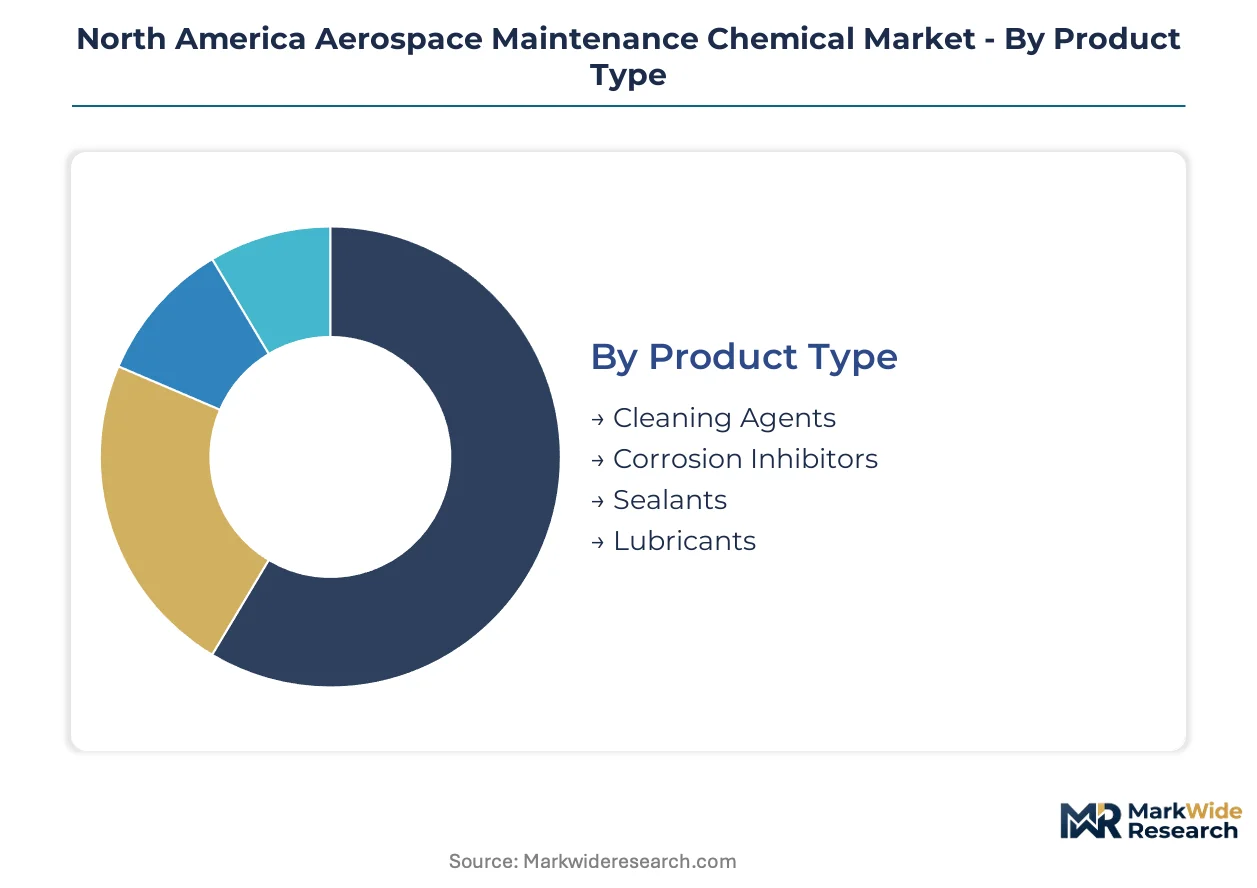
Aerospace maintenance chemicals serve distinct operational requirements across aircraft systems, with formulation specifications varying sharply between commercial airlines and military depots. Segmentation reveals how EPA compliance timelines and MRO consolidation reshape procurement patterns across product categories.
Product Type:
Domestic military depots and southwestern US MRO clusters drive concentrated demand for specification-grade formulations, while Canadian operators import specialized corrosion inhibitors under Health Canada PMRA registration pathways.
- Cleaning Agents:Formulated surfactant blends meeting MIL-PRF-680 Type II specifications dominate procurement volumes. Southwestern US maintenance clusters in Texas and Arizona absorb the heaviest throughput as aging commercial fleets require intensive degreasing between overhaul cycles, though EPA NESHAP solvent emission standards force rapid reformulation toward microemulsion alternatives.
- Corrosion Inhibitors:Fluoropolymer and rare earth additive packages protect aluminum and titanium substrates in salt-laden coastal operating environments. Gulf of Mexico and Atlantic seaboard bases drive the steepest consumption acceleration as operators shorten protective treatment intervals to combat accelerated pitting fatigue.
- Sealants:Polysulfide and silicone formulations certified to Boeing and Airbus material specifications serve fuel tank and pressurized cabin applications.
- Lubricants:Synthetic ester and polyalphaolefin base stocks meeting AS5780 specifications reduce friction in high-temperature engine zones.
Cleaning agents command the established base. The steepest expansion runs through corrosion inhibitors.
End User:
Cost tier stratification separates captive airline programs from outsourced maintenance providers, with volume leverage determining specification influence over formulation standards.
- Maintenance Providers:Third-party MRO facilities in Arizona and Texas handle heavy maintenance for multiple carrier fleets, generating aggregated chemical demand that justifies dedicated storage infrastructure. These operators face margin compression as airline captive programs consolidate procurement leverage.
- Airlines:US legacy carriers building dedicated aerospace chemicals teams capture direct specification compliance management. Centralized technical functions displace decentralized site-level purchasing, with narrow turnaround windows at hub operations demanding rapid-drying cleaning formulations.
- Aerospace Manufacturers:Original equipment producers consume surface-treatment chemistries during production-line assembly and delivery preparation.
- Repair Stations:FAA Part 145-certified facilities perform specialized component overhaul with niche formulation requirements.
Maintenance providers absorb the highest volume throughput. Airlines are gaining share fastest through captive program expansion.
Application:
Volume concentration aligns with fleet age profiles, with older aircraft requiring more intensive intervention across multiple application zones.
- Engine Maintenance:High-temperature degreasing and compressor blade cleaning demand solvent formulations with flash points above 140°F and compatibility with Inconel and titanium alloys. Southwestern US MRO clusters process the densest engine overhaul activity as regional carriers extend aging powerplant life cycles.
- Surface Protection:Exterior coating preservation and substrate sealing combat ultraviolet degradation and chemical attack. Salt-exposed coastal bases drive specification tightening for extended-interval protection products.
- Interior Cleaning:FAA Part 25 flammability testing protocols govern cabin surface treatments, with updated approved chemical lists enabling broader solvent substitution.
- Exterior Cleaning:Fuselage and flight surface washing requires runoff-compliant formulations meeting municipal wastewater discharge standards.
Engine maintenance anchors procurement volume. Surface protection is climbing the fastest as coastal operating intensity increases.
Packaging Type:
Supply chain configuration favors bulk delivery to concentrated MRO clusters, with unit packaging serving dispersed line maintenance operations.
- Bulk Containers:55-gallon drums and tote systems feed automated spray systems at military depots and major commercial MRO facilities. Southwestern US maintenance clusters with embedded waste handling infrastructure prefer bulk delivery to minimize packaging waste disposal costs under state-level air quality management district pressure.
- Spray Bottles:Trigger-actuated dispensers serve gate-side line maintenance crews requiring portable application for spot cleaning and corrosion touch-up.
- Pouches:Single-use sachets reduce cross-contamination risk in precision avionics cleaning applications.
- Cans:Aerosol and pump-dispense metal containers support remote field maintenance with limited storage infrastructure.
Bulk containers dominate value throughput. Spray bottles are expanding most quickly as line maintenance outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American aerospace maintenance chemical trade flows reflect concentrated domestic production capacity alongside specialized import requirements for Canadian operators. Cross-border supply chains handle specification-grade formulations under dual EPA and Health Canada compliance frameworks.
United States
Southwestern MRO clusters in Texas and Arizona absorb the heaviest chemical throughput as aging commercial fleets require intensive degreasing between overhaul cycles. EPA NESHAP solvent emission standards force rapid reformulation toward microemulsion alternatives at military depots nationwide. The Gulf Coast corridor generates accelerated corrosion inhibitor consumption as salt-laden coastal bases shorten protective treatment intervals.
Canada
Royal Canadian Air Force procurement of used Australian F-18s and new fighter acquisitions expand northern MRO chemical demand. Health Canada and PMRA impose parallel restrictions on biocide-containing formulations used in aircraft potable water systems, creating compliance burden for cross-border suppliers. Ontario and Quebec maintenance facilities import specialized corrosion inhibitors under PMRA registration pathways.
Mexico
Northern border states host emerging MRO capacity serving US carrier outsourcing requirements with growing chemical procurement volumes. Mexican aviation regulators align material flammability protocols with FAA Part 25 standards, easing specification-grade product entry. Querétaro and Baja California maintenance clusters process narrow-body overhaul work with concentrated cleaning agent demand.
North America Aerospace Maintenance Chemical Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialty fluid formulators serving specification-driven procurement. The vendor base stratifies across three tiers: multinational diversified suppliers with hydrocarbon processing networks, mid-scale aerospace-certified specialists, and regional distributors handling import logistics. Strategic moves center on reformulation partnerships with military depots and captive supply agreements with consolidating airline technical management functions.
Within the integrated chemical tier, Eastman Chemical Company and The Dow Chemical Company exemplify archetypes with specialty fluid portfolios and hydrocarbon processing infrastructure respectively. Henkel AG & Co. KGaA occupies a position among surface-treatment specialists certified to Boeing and Airbus material specifications. These three anchors represent distinct competitive vectors: reformulation capability, supply security, and OEM specification access.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Arrow Solutions |
| The Dow Chemical Company |
| Nexeo Solutions |
| Aircraft Spruce and Specialty Co. |
| Exxon Mobil Corporation |
| 3M Company |
| Aviation Chemical Solutions, Inc. |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Microemulsion solvent substitution simultaneously redraws procurement geography across southwestern US MRO clusters and compresses pricing premiums historically attached to MIL-PRF-680 Type II formulations. EPA NESHAP compliance timelines concentrate buyer leverage among military depots and airline technical management functions with volume consolidation power.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tier discounts separating specification-grade certified formulations from generic maintenance chemicals. Price differentiation rests on MIL-PRF-680 certification tier and after-sales technical support bundling. Cost compression in mid-tier water-based cleaners intensifies because aqueous systems struggle to match solvent drying speeds for avionics applications. Regional MRO providers exhibit highest price sensitivity due to margin compression from airline captive programs, while military depots with embedded infrastructure show lowest sensitivity.
Supply Chain Analysis
Strategic stockpile preferences dominate military depot procurement with 55-gallon drum forward positioning, while commercial airlines shift toward just-in-time microemulsion delivery to minimize hazardous waste handling costs. Geographic supply concentration centers on US Gulf Coast petrochemical infrastructure, Canadian specialty additive imports under Health Canada PMRA pathways, and Mexican northern border state blending capacity. Raw material dependencies feed from fluoropolymer corrosion inhibitor packages, rare earth feedstocks, and agricultural-derived biobased surfactants. Single-source vulnerability concentrates in qualified chemist formulation expertise for MIL-PRF-680 specification transitions. Distribution runs through integrated chemical conglomerates direct to major MRO clusters, with regional distributors serving dispersed line maintenance operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern aerospace maintenance chemical procurement as airline technical management functions consolidate specification compliance under centralized interoperability frameworks. This ecosystem shift rewards suppliers embedding reformulation services within long-term chemical management contracts.
For Market Incumbents: Consolidate backward integration into rare earth corrosion inhibitor feedstocks to secure supply against concentrated upstream sourcing. Acquire mid-tier aerospace-certified specialists with captive MIL-PRF-680 reformulation expertise to defend against airline captive program margin compression. Lock long-term offtake agreements with southwestern US MRO clusters before EPA perchloroethylene phase-down rulemakings accelerate.
For New Entrants and Emerging Players: Canadian defense fleet modernization under-serve creates immediate white-space for PMRA-registered corrosion inhibitor suppliers. Target Royal Canadian Air Force F-18 refurbishment depots with cross-border logistics capabilities and dual EPA-Health Canada compliance documentation. Penetrate through biobased surfactant formulations converging with existing aerospace certification infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale aerospace-certified specialists carrying MIL-PRF-680 reformulation capabilities and established military depot relationships. Long-term viability frames around regulatory compliance service embedding rather than commodity chemical throughput. Watch EPA perchloroethylene phase-down final rule publication as inflection signal for replacement chemistry qualification program acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Feedstocks | Secures corrosion inhibitor supply chain against concentrated Chinese and Australian upstream sourcing. |
| MIL-PRF-680 Reformulation Partnership | Captures military depot switching demand ahead of EPA NESHAP compliance cliffs. |
| Biobased Surfactant Certification Program | Opens agricultural-derived cleaning agent pathways through Boeing and Airbus material specification channels. |
| Canadian PMRA Registration Buildout | Enables Royal Canadian Air Force procurement access under parallel Health Canada biocide restrictions. |
| Airline Chemical Management Contract | Consolidates decentralized site-level purchasing under centralized technical management functions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with military depot procurement officers, airline technical management directors, MRO facility managers, and specialty chemical formulation chemists; and secondary validation against FAA Parts 25 and 43 certification databases, EPA NESHAP rulemaking dockets, SEC 10-K filings from integrated chemical conglomerates, and Health Canada PMRA registration records. Bottom-up triangulation cross-checked regional MRO cluster chemical throughput estimates against top-down market sizing from hydrocarbon processing network capacity disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type reformulation tiers, end-user consolidation archetypes, application zone intensity profiles, and packaging format logistics configurations. CAGRs derived from regression analysis of fleet age demographics, refurbishment cycle frequency, and regulatory compliance cost pass-through elasticity. Industry-specific forecast inputs incorporated EPA pending rulemaking timelines and Royal Canadian Air Force procurement schedules.
Underlying assumptions cover stable EPA NESHAP enforcement trajectories and continued airline outsourcing-to-captive program conversion, with deviation risk concentrated in accelerated perchloroethylene phase-down schedules or Canadian defense procurement delays. Revision becomes warranted when EPA final rule publication crosses threshold acceleration timelines or Health Canada PMRA registration backlogs exceed eighteen months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market