
 Cabin Reconfiguration and Retrofit MRO Services Market | 2026-2036
Cabin Reconfiguration and Retrofit MRO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cabin Reconfiguration and Retrofit MRO Services Market Insights
Modular seat-and-galley bundling is restructuring buyer procurement patterns across airline retrofit programs. Lufthansa Technik leverages its Hamburg and Malta facilities to dominate wide-body VIP reconfiguration workflows. ST Engineering anchors Asia-Pacific demand through Singapore-based MRO hangars serving narrow-body operators. HAECO Group extends its Hong Kong and Xiamen footprint to capture mainland Chinese airline retrofit volumes.
Cabin reconfiguration and retrofit MRO services encompass the structural modification, systems integration, and aesthetic refurbishment of existing aircraft interiors to extend operational life or upgrade passenger experience, typically involving fire-blocking materials meeting 16 CFR Part 25.853 flammability standards and seat-track load testing to 16g crashworthiness criteria. Interior refurbishment and seat modification command the largest share of current revenue as airlines prioritize densification over premium cabin expansion. Narrow-body jets represent the fastest-growing aircraft type segment as carriers maximize per-aircraft yield through slimline seating and space-flex lavatory installations.
FAA airworthiness directives and EASA CS-25 certification requirements govern structural modification approvals, while REACH compliance constrains material selection for European-registered fleet retrofits. Airlines must monitor evolving EPA volatile organic compound limits on interior coatings and adhesives, which are tightening finish-shop operational parameters. Stakeholders should track regulatory divergence between FAA and EASA on lithium battery installations for in-flight entertainment retrofits, as certification pathway choices will shape supplier qualification timelines and program costs.
Market Dynamics
Composite panel innovations are compressing aircraft downtime windows from weeks to days, forcing MRO providers to restructure hangar scheduling and labor deployment around rapid-cure adhesive systems and modular interior architectures.
Growth Catalysts
- Narrow-body densification mandates:Low-cost carriers across Indonesia, Vietnam, and the Philippines are retrofitting aging A320 and 737 fleets with slimline seating configurations to match competitor yield metrics.
- FAA 16g crashworthiness compliance:Updated seat-track load testing requirements are triggering mandatory cabin overhauls for US-registered aircraft approaching structural recertification deadlines.
- Composite bonding automation:Robotic application of fire-blocking materials meeting 16 CFR Part 25.853 standards is reducing manual labor hours and rework rates in finish-shop operations.
Market Restraints
- Specialized technician scarcity:Certified airframe mechanics with composite repair qualifications command wage premiums exceeding 40% above standard MRO rates in Singapore and Hong Kong labor markets.
- REACH material substitution costs:European-registered fleets face restricted adhesive and coating chemistries, forcing dual inventory systems and extended supplier qualification timelines.
- Hangar slot congestion:Asia-Pacific MRO capacity concentrates in Singapore, Xiamen, and Hong Kong, creating 90-day booking backlogs during peak fleet renewal cycles.
Strategic Opportunities
- Vietnam domestic route expansion:VietJet and Bamboo Airways are accelerating narrow-body acquisition schedules, creating captive retrofit demand for cabin standardization across mixed lessor fleets.
- Lithium battery IFE retrofits:Regulatory divergence between FAA and EASA certification pathways creates first-mover advantage for suppliers securing dual-approval technical standard orders.
- Space-flex lavatory integration:Airbus and Boeing OEM-approved galley reconfiguration packages enable aft-cabin seat count increases of 6-8 positions per narrow-body installation.
Industry Challenges
- EASA-FAA certification pathway fragmentation:Divergent technical interpretation of structural modification approvals forces duplicate documentation and extended validation timelines for cross-registered fleets.
- Legacy aircraft documentation gaps:Pre-digital era Boeing 737 Classics and early A320 family airframes lack complete as-built interior drawings, requiring laser scanning and reverse engineering before modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabin Reconfiguration and Retrofit MRO Services Market |
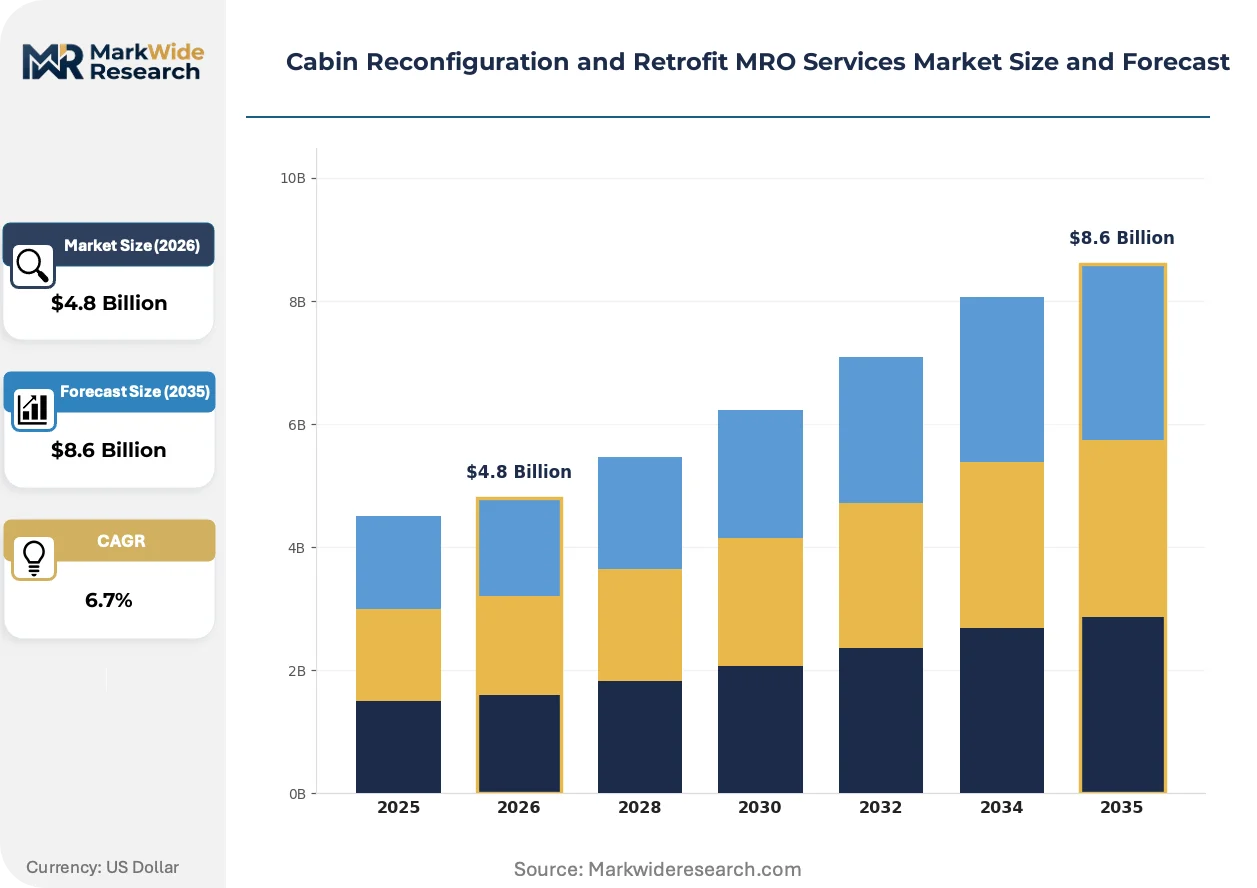
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Interior Refurbishment, Seat Modification, Galley Upgrades, Lavatory Retrofits, In-flight Entertainment Installation, Lighting Enhancement Aircraft Type: Wide-body Jets, Narrow-body Jets, Regional Aircraft, Business Jets, Turboprops, Commuter Planes Client Type: Airlines, Charter Operators, Leasing Companies, Corporate Operators, Government Fleets, Cargo Operators Aircraft Age Group: Less than 5 Years, 5 to 10 Years, 10 to 20 Years, Over 20 Years |
| Companies Covered | Lufthansa Technik, Collins Aerospace, Safran, ST Engineering, Diehl Aviation, Panasonic Avionics, Thales, HAECO Group, JAMCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabin Reconfiguration and Retrofit MRO Services Market Trends and Innovations
Digital thread technologies are collapsing the handoff friction between design engineering and shop floor execution, enabling real-time adjustment of retrofit specifications without program delay.
Prefabricated cabin modules incorporating integrated power, data, and HVAC distribution are rewriting installation sequencing for narrow-body programs. LCC procurement teams in Southeast Asia are specifying these units for 72-hour turnarounds on leased aircraft returns. The compression of dwell time is shifting contract structures toward fixed-price outcomes rather than time-and-material billing.
EPA volatile organic compound limits on interior coatings and adhesives are tightening finish-shop operational parameters in US-based MRO facilities. Compliance investments in enclosed spray booths and thermal oxidizer systems are raising facility capital thresholds. Smaller independent shops in Florida and Arizona are consolidating or exiting the market rather than absorbing remediation costs.
Airline technical procurement departments are unbundling seat modification from full cabin reconfiguration contracts, creating direct relationships with seat OEMs and fragmenting traditional MRO scope. This disintermediation is most pronounced among Indonesian carriers managing mixed lessor portfolios with varying return conditions. The shift pressures incumbent MRO providers to defend position through exclusive airframe access agreements rather than bundled service offerings.
Cabin Reconfiguration and Retrofit MRO Services Market Segmentation
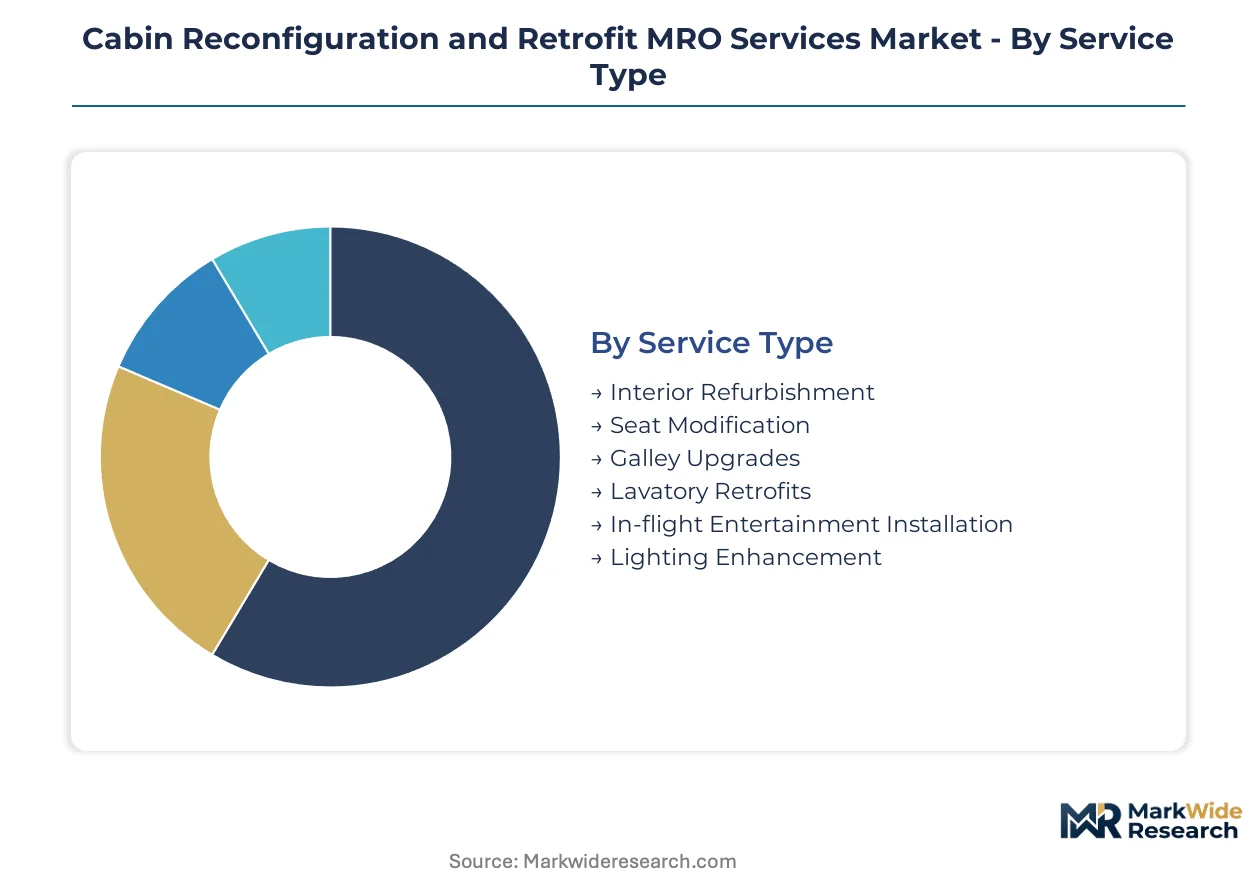
Cabin reconfiguration and retrofit MRO services fragment across four structural dimensions that determine procurement patterns, technical complexity, and margin profiles. Each segmentation axis reveals distinct competitive dynamics between volume-driven standardization and premium customization workflows.
Service Type:
Volume concentrates in high-frequency, quick-turnaround offerings, while premium tiers attach to integrated cabin transformation programs requiring extended airframe downtime.
- Interior Refurbishment:Encompasses sidewall panel replacement, carpet renewal, and overhead bin modifications using fire-blocking materials meeting 16 CFR Part 25.853 standards. Demand clusters among Southeast Asian LCCs modernizing aging A320 and 737 interiors to match competitor yield configurations, with composite panel innovations compressing downtime from weeks to days.
- Seat Modification:Involves track replacement, 16g crashworthiness load testing, and slimline seating densification packages. Indonesian and Vietnamese carriers drive procurement as they retrofit mixed lessor fleets with standardized seat counts to simplify return conditions and maximize per-aircraft revenue.
- Galley Upgrades:OEM-approved reconfiguration packages enabling aft-cabin optimization.
- Lavatory Retrofits:Space-flex installations adding 6-8 seat positions per narrow-body.
- In-flight Entertainment Installation:Lithium battery retrofits navigating FAA-EASA regulatory divergence.
- Lighting Enhancement:LED cabin mood systems replacing legacy fluorescent architectures.
Today's leader: Interior Refurbishment. Tomorrow's challenger: Seat Modification.
Aircraft Type:
Application splits between long-haul premium reconfiguration and short-haul densification economics, with fleet age and utilization patterns dictating retrofit investment thresholds.
- Narrow-body Jets:A320 and 737 family airframes dominate retrofit volumes across Indonesia, Vietnam, and the Philippines, where LCCs pursue rapid turnaround programs. Composite bonding automation and prefabricated cabin modules enable 72-hour lease return completions, restructuring contract structures toward fixed-price outcomes.
- Wide-body Jets:VIP and premium cabin transformations command extended dwell times at specialized facilities. Hamburg and Malta serve as primary hubs for first-class and business suite reconfigurations, with regulatory complexity around EASA CS-25 structural approvals filtering provider eligibility.
- Regional Aircraft:Limited retrofit activity concentrated in fleet standardization programs.
- Business Jets:Custom VIP interiors with bespoke material specifications and extended completion timelines.
- Turboprops:Essential service refurbishments for remote connectivity operators.
- Commuter Planes:Minimal reconfiguration demand given short operational lifecycles.
Narrow-body Jets capture current volume leadership. Wide-body Jets present the steepest expansion trajectory as premium cabin competition intensifies on long-haul routes.
Client Type:
Procurement authority fragments between asset owners seeking residual value protection and operators optimizing passenger experience within lease constraints.
- Airlines:Direct technical procurement departments unbundling seat modification from full cabin reconfiguration contracts, creating direct OEM relationships and fragmenting traditional MRO scope. Indonesian carriers managing mixed lessor portfolios exhibit the most pronounced disintermediation behavior.
- Leasing Companies:Mandate standardized return conditions across heterogeneous fleets, driving captive retrofit demand for cabin configuration normalization.
- Charter Operators:Seasonal refurbishment cycles aligned with aircraft redeployment schedules.
- Corporate Operators:Bespoke VIP completions with personalized specification requirements.
- Government Fleets:Security-cleared modification protocols with restricted facility access.
- Cargo Operators:Limited passenger-to-freighter conversion adjacent services.
Airlines dominate current procurement volume. Leasing Companies are gaining procurement influence as lessor fleet concentration increases across Southeast Asia.
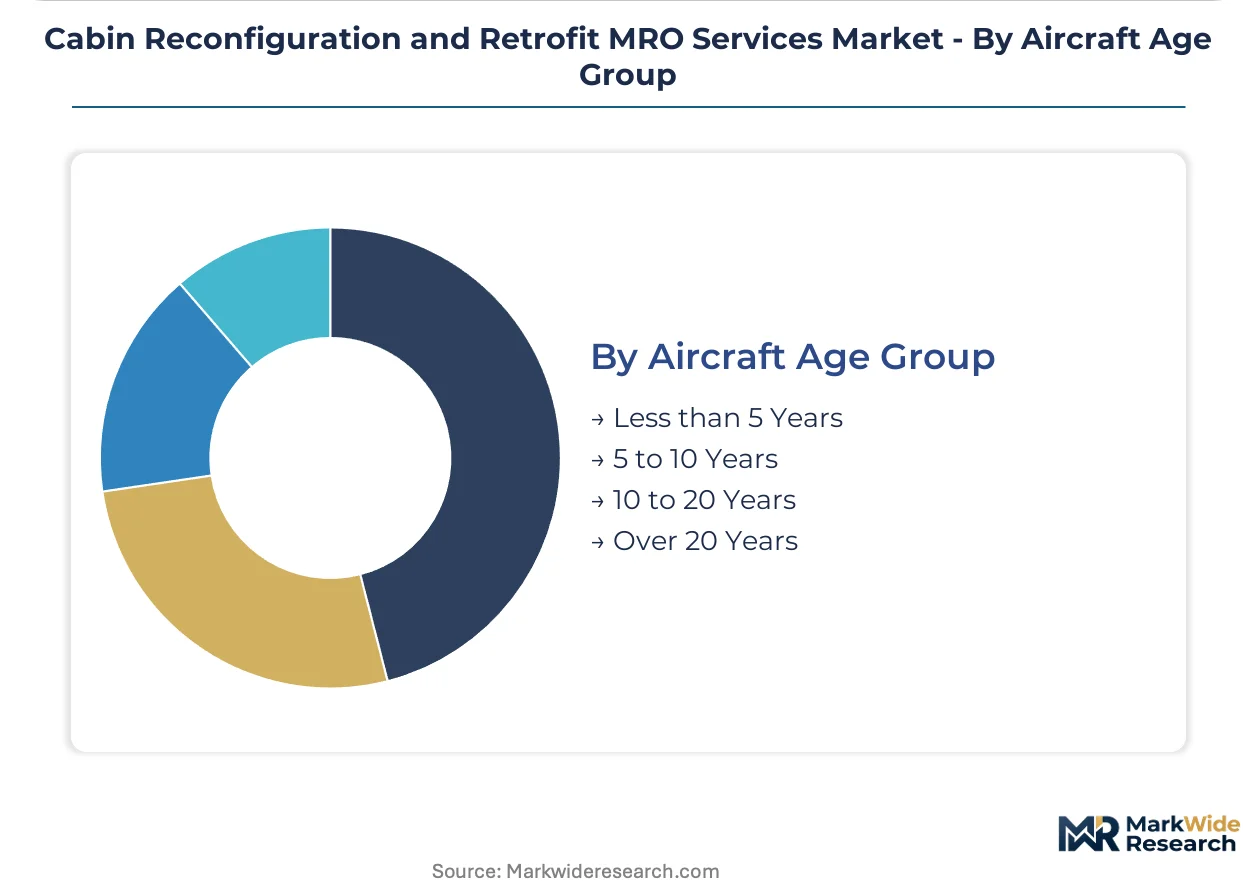
Aircraft Age Group:
Investment timing correlates with structural recertification milestones and competitive positioning windows, with mid-life airframes presenting optimal retrofit economics.
- 10 to 20 Years:Peak retrofit activity as A320ceo and 737NG family airframes approach mid-life cabin modernization cycles. FAA 16g crashworthiness compliance deadlines and competitor yield matching drive mandatory overhaul programs across US-registered and Southeast Asian fleets.
- 5 to 10 Years:Early cosmetic refresh and IFE upgrade programs preserving residual values.
- Less than 5 Years:Minimal reconfiguration beyond warranty corrections and minor specification adjustments.
- Over 20 Years:Documentation gaps in pre-digital era Boeing 737 Classics and early A320 family airframes require laser scanning and reverse engineering, extending program timelines and filtering viable project scope.
10 to 20 Years commands current retrofit intensity. 5 to 10 Years represents the emerging growth segment as airlines front-load modernization to extend competitive relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cabin reconfiguration and retrofit MRO services industry traces its modern scale to post-war European airframe engineering centers, where Lufthansa Technik's Hamburg facility pioneered integrated VIP transformation workflows that established the technical and regulatory templates now deployed worldwide.
Germany
Wide-body VIP reconfigurations concentrate at Hamburg facilities serving first-class and business suite transformations. EASA CS-25 structural modification approvals filter provider eligibility, creating certification moats around established technical centers. The Hamburg-Munich corridor anchors premium cabin engineering talent pools.
United States
FAA 16g crashworthiness compliance deadlines trigger mandatory cabin overhauls for aging US-registered fleets approaching structural recertification milestones. EPA volatile organic compound limits on interior coatings tighten finish-shop operational parameters across Florida and Arizona MRO clusters. Smaller independent shops consolidate rather than absorb remediation capital thresholds.
Singapore
ST Engineering anchors Asia-Pacific narrow-body demand through Singapore-based MRO hangars serving LCC fleet renewal programs. Certified airframe mechanics with composite repair qualifications command wage premiums exceeding 40% above standard MRO rates. The Changi aerospace cluster experiences 90-day booking backlogs during peak fleet renewal cycles.
Indonesia
Lion Air and Garuda Indonesia drive narrow-body densification mandates across aging A320 and 737 fleets to match competitor yield metrics. Airline technical procurement departments unbundle seat modification from full cabin reconfiguration contracts, fragmenting traditional MRO scope. Jakarta-Surabaya routes concentrate retrofit demand for cabin standardization across mixed lessor portfolios.
China
HAECO Group extends its Hong Kong and Xiamen footprint to capture mainland Chinese airline retrofit volumes. REACH material substitution costs force dual inventory systems for European-registered fleet retrofits handled through Chinese facilities. The Pearl River Delta aerospace corridor develops composite bonding automation capabilities for fire-blocking material applications.
Cabin Reconfiguration and Retrofit MRO Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and aircraft type specialization. The market structures around three tiers: integrated airframe OEM affiliates controlling wide-body VIP workflows, independent MRO networks capturing narrow-body volume through geographic density, and specialist seat-and-galley OEMs disintermediating traditional service bundling. Consolidation accelerates through exclusive airframe access agreements and prefabricated module partnerships that compress turnaround commitments.
Within the integrated airframe service tier, Lufthansa Technik and ST Engineering exemplify geographic anchoring strategies—Hamburg and Singapore facilities respectively—while HAECO Group represents the Greater China corridor specialization. Collins Aerospace and Safran occupy positions spanning avionics-to-interior system integration. These five entities illustrate how certification depth, hangar slot control, and regional fleet access determine competitive position without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Lufthansa Technik |
| Collins Aerospace |
| Safran |
| ST Engineering |
| Diehl Aviation |
| Panasonic Avionics |
| Thales |
| HAECO Group |
| JAMCO Corporation |
| Others |
Pricing and Supply Chain Analysis
Indonesian carrier unbundling of seat modification from full cabin reconfiguration contracts is fragmenting traditional MRO scope and forcing suppliers to absorb margin compression through fixed-price outcomes rather than time-and-material billing. This procurement shift concentrates pricing power with airlines managing mixed lessor portfolios while MRO providers compete for exclusive airframe access agreements.
Pricing Analysis
Three-tier pricing structure across premium VIP, standard narrow-body, and economy quick-turnaround levels governs contract structures in this market. Price differentiation hinges on EASA CS-25 certification depth and hangar slot scarcity at Singapore and Hamburg facilities. Cost compression in economy quick-turnaround tiers is intensifying because prefabricated cabin modules enable 72-hour lease return completions. Charter operators exhibit highest price sensitivity due to seasonal cash flow cycles, while government fleets accept premium pricing for security-cleared modification protocols.
Supply Chain Analysis
Certified airframe mechanics with composite repair qualifications command wage premiums exceeding 40% above standard MRO rates in Singapore and Hong Kong labor markets, constraining capacity expansion at established facilities. Supply concentrates in Germany, Singapore, and China, with fire-blocking materials and rapid-cure adhesive systems drawing from specialized chemical suppliers. Single-source vulnerability around REACH-compliant coating chemistries forces dual inventory systems for European-registered fleet retrofits. Distribution runs through OEM-approved reconfiguration packages and direct airline technical procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where MRO providers capture margin by locating finish-shop operations in jurisdictions with relaxed EPA volatile organic compound limits while serving FAA-registered fleets.
For Market Incumbents: Anchor competitive position through exclusive airframe access agreements with Indonesian and Vietnamese carriers managing mixed lessor portfolios. Invest in composite bonding automation capabilities at Singapore and Xiamen facilities to offset wage premiums for certified technicians. Defend against seat OEM disintermediation by integrating prefabricated cabin module partnerships that compress turnaround commitments. For New Entrants and Emerging Players: Launch via direct relationships with VietJet and Bamboo Airways as these carriers accelerate narrow-body acquisition schedules and require cabin standardization across mixed fleets. Target Vietnam domestic route expansion as the most penetrable geography given captive retrofit demand and limited incumbent MRO density. Penetrate through space-flex lavatory integration expertise as Airbus and Boeing OEM-approved packages enable aft-cabin seat count increases. For Investors and Strategic Acquirers: Asymmetric upside sits with independent MRO networks capturing narrow-body volume through geographic density rather than integrated airframe OEM affiliates controlling wide-body VIP workflows. Long-term viability favors providers with dual FAA-EASA certification pathways as regulatory divergence on lithium battery installations for in-flight entertainment retrofits creates first-mover advantage. Watch for consolidation signals through prefabricated module partnerships as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Bonding Automation Investment | Robotic fire-blocking material application reduces manual labor hours at Singapore facilities. |
| Prefabricated Cabin Module Partnership | Integrated power and HVAC distribution enables 72-hour narrow-body lease return completions. |
| Dual Certification Pathway Development | Simultaneous FAA and EASA approval for lithium battery IFE retrofits accelerates supplier qualification. |
| Exclusive Airframe Access Agreement | Direct relationships with Indonesian carriers defend against seat OEM disintermediation. |
| Geographic Facility Expansion | Xiamen and Hong Kong footprint extension captures mainland Chinese airline retrofit volumes. |
Research Methodology
Direct dialogue with MRO operations directors, airline technical procurement managers, leasing company asset managers, and composite materials suppliers grounded the qualitative foundation of this analysis. Secondary validation drew from FAA airworthiness directives, EASA CS-25 certification databases, EPA volatile organic compound regulatory filings, and customs trade data on fire-blocking material imports. Bottom-up project pipeline enumeration and top-down fleet age demographic analysis were triangulated to establish market sizing.
Segmented outputs across service type, aircraft type, client type, and aircraft age group were generated through the projection horizon. CAGRs were derived from fitted growth curves calibrated to narrow-body densification mandates and wide-body VIP reconfiguration cycles. Key forecast inputs included A320 and 737 family retirement timelines, REACH material substitution cost trajectories, and hangar slot availability at Singapore and Hamburg facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FAA 16g crashworthiness compliance deadlines or prolonged EASA-FAA certification pathway fragmentation. Forecasts reflect documented assumptions on fleet renewal program pacing and composite panel innovation adoption curves. Material deviation in Indonesian carrier procurement unbundling velocity or REACH regulatory enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market