
 UK Military Aviation Market | 2026-2036
UK Military Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
UK Military Aviation Market Analytics
Modular mission-system architectures is shifting procurement patterns across UK defense aviation, enabling incremental capability upgrades without full platform replacement. BAE Systems anchors the national Combat Air Strategy through its Tempest program leadership and deep integration with RAF operational requirements. Rolls-Royce Holdings sustains propulsion technology sovereignty via specialized military turbine development at its Bristol and Derby facilities. Leonardo competes in rotary-wing segments, leveraging its Yeovil manufacturing base for Wildcat and Merlin helicopter deliveries to British armed forces.
UK military aviation encompasses manned and uncrewed aerospace platforms, propulsion systems, avionics suites, and mission-critical subsystems designed for defense operations at altitudes from surface level to stratospheric regimes, typically incorporating radar-absorbent materials and hardened electronic architectures against electromagnetic threats. Fighter aircraft and UAV segments attract disproportionate R&D allocation as the RAF pursues sixth-generation capability and autonomous collaborative platforms under Future Combat Air System roadmaps. Avionics and sensor technology categories concentrate value capture, with electro-optical targeting systems and active electronically scanned arrays representing high-margin procurement priorities within Ministry of Defence equipment plans.
The UK Ministry of Defence shapes market access through Defence and Security Industrial Strategy requirements mandating domestic content thresholds and sovereign capability preservation in combat air and submarine-launched systems. Military Aviation Authority certification standards, aligned with NATO STANAG frameworks, dictate airworthiness protocols for platforms entering RAF service. The Civil Aviation Authority maintains overlapping jurisdiction for dual-use airspace integration, particularly affecting UAV operations in controlled corridors. Stakeholders must monitor how Integrated Review refresh commitments to Indo-Pacific tilt redirect platform prioritization and basing infrastructure away from legacy European theater assumptions.
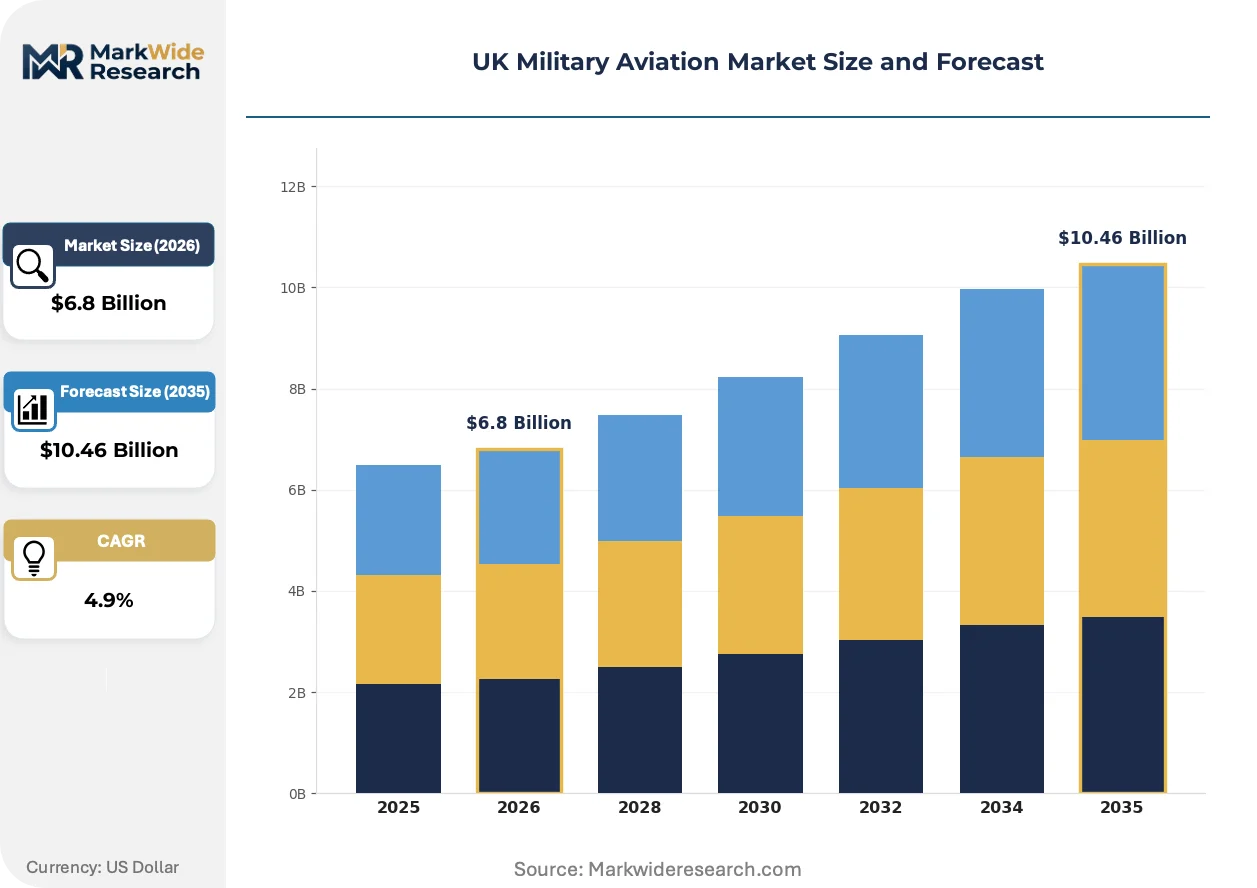
Market Dynamics
The UK Ministry of Defence's Integrated Review refresh is compressing platform replacement cycles while accelerating uncrewed systems integration into RAF operational doctrine. This structural pivot toward autonomous collaborative platforms is reallocating industrial capacity away from legacy manned aircraft sustainment.
Growth Catalysts
- Future Combat Air System roadmaps:The RAF's sixth-generation fighter requirements under Combat Air Strategy frameworks are pulling investment toward advanced propulsion and sensor architectures.
- Scottish aerospace cluster concentration:Specialized manufacturing capabilities around Glasgow and Prestwick for military turbine components create domestic supply security advantages.
- Defence and Security Industrial Strategy mandates:Domestic content thresholds for combat air systems are locking in BAE Systems and Rolls-Royce as anchor suppliers for sovereign capability preservation.
Market Restraints
- Titanium and nickel superalloy input volatility:Military-grade metallurgical supply chains face price pressure from aerospace demand competition and energy-intensive processing constraints.
- Single-source propulsion dependency:Rolls-Royce's effective monopoly on UK military turbine production concentrates technical risk and limits supplier negotiation leverage for the Ministry of Defence.
- Military Aviation Authority certification timelines:Airworthiness protocols aligned with NATO STANAG frameworks impose multi-year validation periods that compress operational availability windows for new platforms.
Strategic Opportunities
- Indo-Pacific basing infrastructure pivot:The Integrated Review's geographic reorientation toward Oman and Singapore creates demand signals for long-range strike and maritime patrol platform variants.
- Dual-use UAV corridor integration:Civil Aviation Authority controlled airspace frameworks for uncrewed systems are opening military-autonomous technology transfer pathways.
- Electro-optical targeting convergence:Sensor fusion between synthetic aperture radar and infrared search-and-track systems is creating upgrade markets for existing Typhoon and Wildcat fleets.
Industry Challenges
- Systems engineering talent scarcity:The contraction of UK aerospace apprenticeship pipelines since 2010 is constraining platform integration capacity for Tempest program timelines.
- Legacy platform interoperability:RAF demands for uncrewed-manned teaming require software-defined radio architectures that must bridge 1980s-era Link 16 protocols with modern waveform standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Military Aviation Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fighter Aircraft, Transport Aircraft, Helicopters, UAVs Technology: Avionics, Propulsion Systems, Sensors, Communication Systems End User: Royal Air Force, Ministry of Defence, Private Contractors, Defense Agencies Application: Combat Operations, Surveillance, Reconnaissance, Training |
| Companies Covered | BAE Systems, Airbus, Leonardo, Lockheed Martin Corporation, The Boeing Company, Rolls-Royce Holdings, Thales Group, MBDA, QinetiQ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Military Aviation Market Evolving Landscape
Digital engineering methodologies are compressing design-validation cycles across UK defense aviation, displacing physical prototyping with model-based systems engineering. This shift is restructuring supplier relationships around simulation capability rather than manufacturing scale.
Artificial intelligence-enabled mission planning is converging with autonomous swarming algorithms to reshape RAF operational concepts. The Rapid Capabilities Office is field-testing these architectures through Project Mosquito and related uncrewed wingman programs. This convergence is forcing traditional prime contractors to acquire software competency while opening entry points for non-traditional defense suppliers.
The UK Ministry of Defence's Net Zero Carbon emissions mandate for defense estates is tightening fuel efficiency specifications for next-generation platforms. This regulatory pressure is redirecting Rolls-Royce research spending toward hybrid-electric propulsion demonstrators and sustainable aviation fuel compatibility testing. Rotary-wing segments face the most acute compliance pressure given Merlin and Wildcat fleet operational intensity.
Consolidated through-life support contracts are displacing transactional spares purchasing across RAF platform categories. The Typhoon Total Availability Enterprise model is extending to Tempest development, locking suppliers into performance-based availability guarantees. This pattern is most advanced in fast-jet segments where operational readiness metrics now dominate procurement evaluation criteria.
UK Military Aviation Market Segmentation
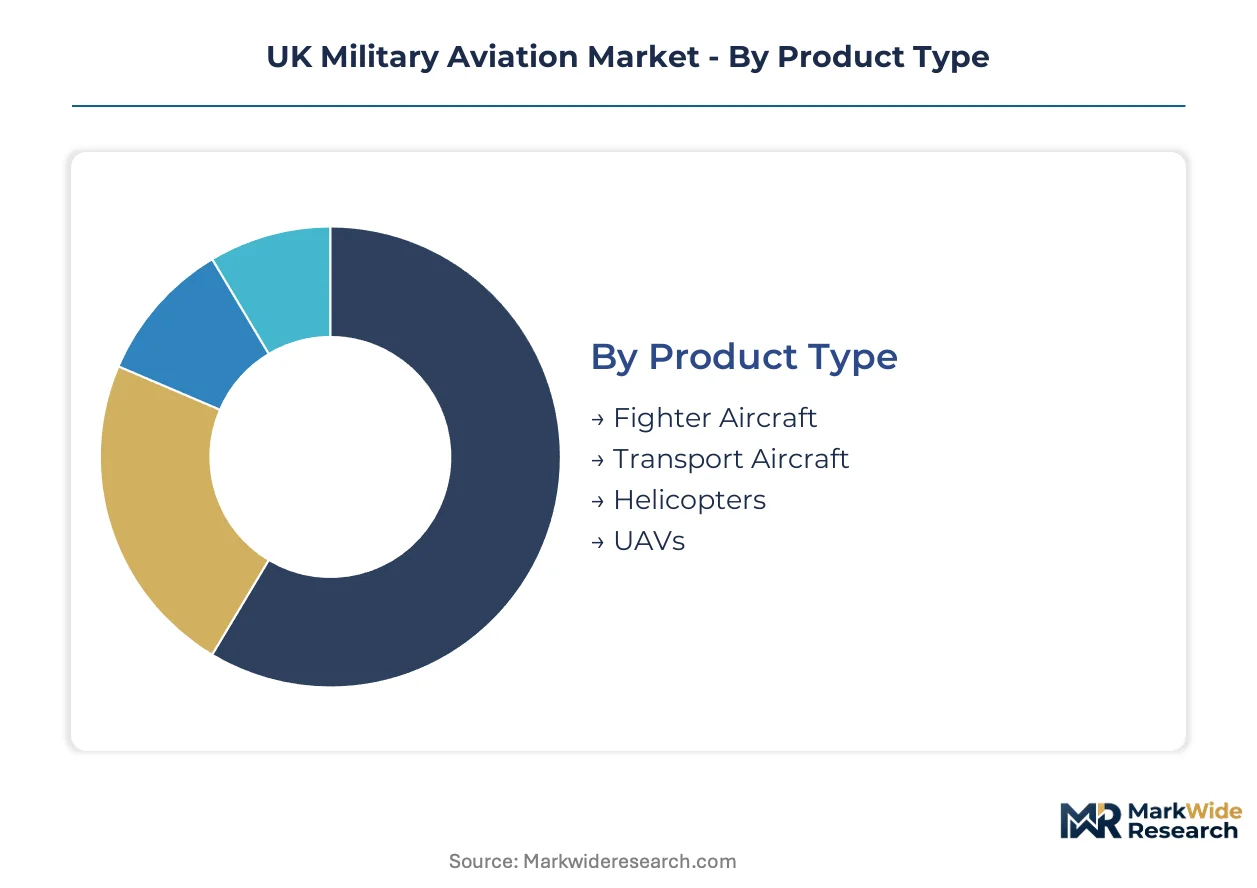
Segmentation of the UK Military Aviation Market reveals how procurement concentration and capability requirements reshape supplier relationships across platform categories. Understanding these divisions clarifies where Defence and Security Industrial Strategy mandates lock in domestic content versus where import substitution remains viable.
Product Type:
Supply concentration clusters around platforms requiring sovereign manufacturing capability under Ministry of Defence procurement frameworks, with Scottish and South West England aerospace hubs anchoring production for militarily sensitive categories.
- Fighter Aircraft:Manned combat air platforms incorporate radar-absorbent materials and hardened electronic architectures against electromagnetic threats. The Tempest program at BAE Systems' Warton facility concentrates sixth-generation development investment, pulling Scottish aerospace cluster capacity toward advanced propulsion integration.
- Helicopters:Rotary-wing systems span utility, anti-submarine, and battlefield support roles with specialized maritime variants. Leonardo's Yeovil manufacturing base sustains Wildcat and Merlin deliveries to British armed forces, concentrating Yeovil-Somerset supply chain employment under through-life support contracts.
- Transport Aircraft:Strategic and tactical airlift platforms enable force projection and logistics sustainment across dispersed basing infrastructure.
- UAVs:Uncrewed platforms span tactical reconnaissance through autonomous collaborative wingman concepts under RAF operational doctrine.
Fighter Aircraft absorbs the bulk of installed capacity; UAVs are expanding most quickly.
Technology:
Cost tier differentiation separates sovereign-controlled subsystems from import-dependent components, with avionics and propulsion commanding premium procurement evaluation given certification complexity.
- Avionics:Mission-critical electronic suites encompass flight control, navigation, and combat management systems. Electro-optical targeting systems and active electronically scanned arrays represent high-margin procurement priorities within Ministry of Defence equipment plans, concentrating value capture in South East England sensor development clusters.
- Propulsion Systems:Military turbine engines demand nickel superalloy precision manufacturing and specialized thermal barrier coatings. Rolls-Royce's Bristol and Derby facilities sustain effective monopoly on UK military turbine production, concentrating technical risk for Ministry of Defence supplier negotiation.
- Sensors:Detection and targeting subsystems span radar, infrared, and electronic warfare architectures for threat identification.
- Communication Systems:Secure data links and software-defined radio platforms enable uncrewed-manned teaming protocols.
Avionics absorbs the bulk of installed capacity; Communication Systems are climbing the fastest.
End User:
Volume concentration follows Integrated Review refresh commitments, with operational readiness metrics now dominating procurement evaluation across fast-jet and rotary-wing segments.
- Royal Air Force:The primary operational consumer executes fleet modernization under Combat Air Strategy frameworks. RAF demands for uncrewed-manned teaming redirect platform prioritization toward autonomous collaborative architectures, compressing legacy manned aircraft sustainment cycles.
- Ministry of Defence:The central procurement authority mandates domestic content thresholds and sovereign capability preservation. Defence and Security Industrial Strategy requirements lock in BAE Systems and Rolls-Royce as anchor suppliers for combat air and submarine-launched systems.
- Private Contractors:Outsourced through-life support providers deliver availability guarantees under performance-based contracts.
- Defense Agencies:Research and development bodies including the Rapid Capabilities Office field-test autonomous architectures.
The Royal Air Force absorbs the bulk of installed capacity; Private Contractors are gaining share fastest.
Application:
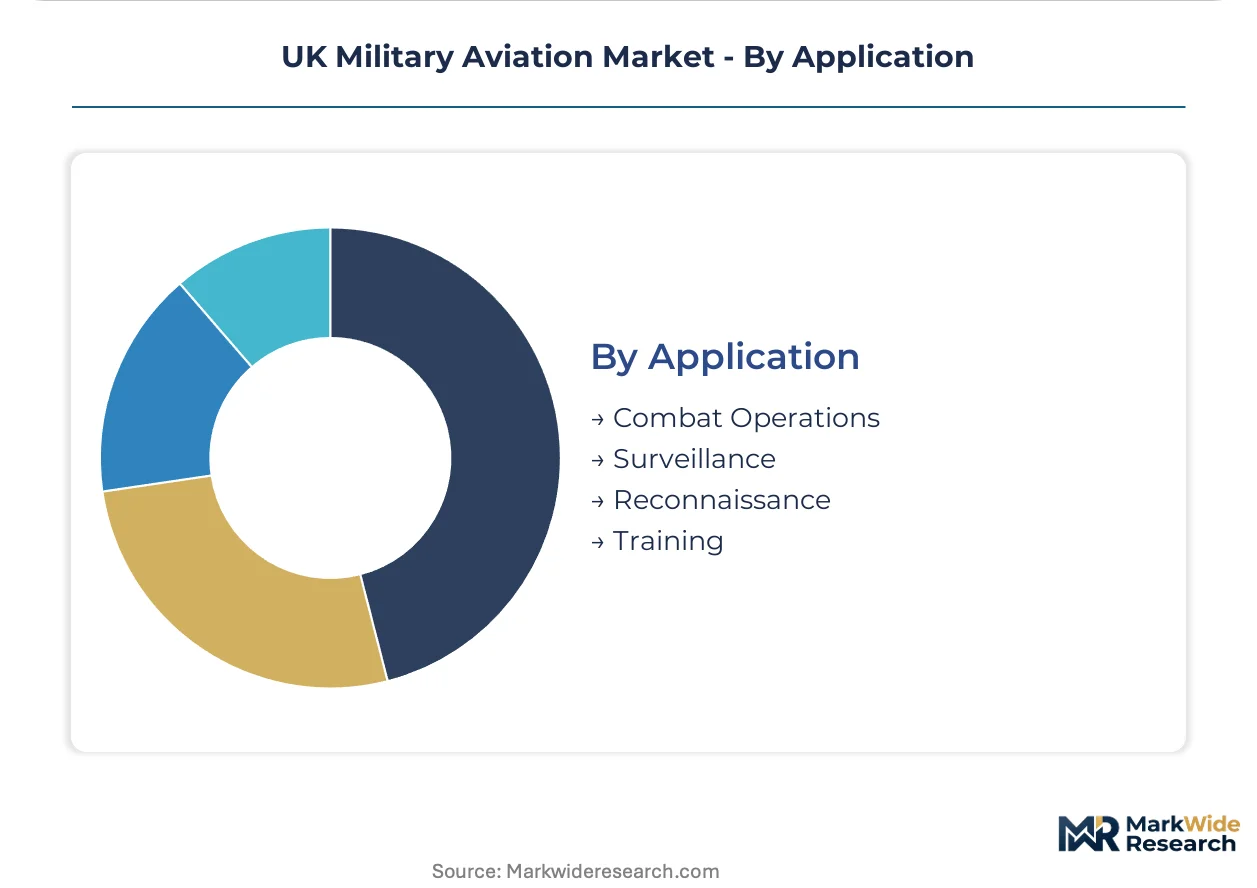
Margin concentration favors multi-mission platforms capable of spanning operational categories, with sensor fusion investments enabling upgrade markets for existing Typhoon and Wildcat fleets.
- Combat Operations:Kinetic strike and air superiority missions drive sixth-generation fighter requirements. Future Combat Air System roadmaps pull investment toward advanced propulsion and sensor architectures, with Indo-Pacific basing infrastructure pivot creating demand signals for long-range strike variants.
- Surveillance:Persistent intelligence collection platforms span manned maritime patrol through uncrewed persistent stare capabilities. Synthetic aperture radar and infrared search-and-track convergence creates upgrade markets for existing fleets, concentrating sensor development in specialized South East England clusters.
- Reconnaissance:Tactical and strategic information gathering supports targeting and battle damage assessment.
- Training:Pilot and crew qualification systems maintain operational currency across platform categories.
Combat Operations absorbs the bulk of installed capacity; Surveillance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK Military Aviation Market concentrates production capacity in Scottish and South West England aerospace clusters while operational consumption centers on RAF basing infrastructure across eastern England. Domestic manufacturing dominance contrasts with selective technology import dependencies for specialized subsystems.
Scotland
Glasgow and Prestwick aerospace corridors anchor military turbine component manufacturing for Rolls-Royce propulsion systems. Scottish Enterprise innovation funding supports advanced materials research for thermal barrier coatings under UK sovereign capability mandates. The Prestwick cluster concentrates precision forging capacity for nickel superalloy engine parts serving Tempest program timelines.
South West England
Bristol and Yeovil manufacturing bases sustain Leonardo helicopter deliveries and Rolls-Royce military engine assembly. The region's aerospace apprenticeship pipelines feed specialized technician demand for Wildcat and Merlin through-life support contracts. Yeovil-Somerset supply chain employment concentrates under Ministry of Defence performance-based availability agreements.
North West England
BAE Systems' Warton facility drives sixth-generation fighter development under Combat Air Strategy frameworks. Lancashire's engineering heritage supports systems integration capacity for autonomous collaborative platform architectures. The Warton cluster pulls Scottish propulsion expertise toward advanced combat air demonstrator programs.
South East England
Sensor development clusters around electro-optical targeting and active electronically scanned array technologies concentrate procurement value capture. The region's electronics manufacturing base supplies avionics subsystems for Typhoon fleet upgrades. Farnborough-area defense research facilities field-test uncrewed-manned teaming protocols under Rapid Capabilities Office direction.
East Anglia
RAF Marham and surrounding bases host operational fast-jet squadrons driving fleet modernization demand. The region's basing infrastructure supports Indo-Pacific tilt commitments through long-range strike platform staging. East Anglian airfields increasingly integrate civil-military UAV corridor testing under Civil Aviation Authority frameworks.
UK Military Aviation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across UK military aviation supply tiers. Market structure tilts toward consolidation in combat air and propulsion segments where Defence and Security Industrial Strategy mandates lock in anchor suppliers. Three archetypes dominate: sovereign capability primes, technology subsystem specialists, and through-life support integrators. Competitive moves concentrate on strategic partnerships for autonomous systems development and portfolio diversification toward dual-use UAV technologies.
Among UK-headquartered primes, BAE Systems and Rolls-Royce Holdings occupy anchor positions under sovereign capability preservation frameworks. Leonardo represents European specialist competition in rotary-wing segments. These three exemplify how domestic content thresholds structure competitive access to Ministry of Defence procurement channels.
| Leading Market Players |
|---|
| BAE Systems |
| Airbus |
| Leonardo |
| Lockheed Martin Corporation |
| The Boeing Company |
| Rolls-Royce Holdings |
| Thales Group |
| MBDA |
| QinetiQ |
| Others |
Value Network & Pricing Analysis
Nickel superalloy spot indices cascading through Rolls-Royce turbine component supply chains stratify UK military aviation procurement across sovereign-manufactured premium tiers and import-dependent standard tiers. Ministry of Defence through-life support contracts compress transactional spares margins while locking anchor suppliers into performance-based availability guarantees.
Pricing Analysis
Margin tightening in propulsion subsystems reflects Rolls-Royce's effective monopoly on UK military turbine production and the energy-intensive processing constraints of nickel superalloy thermal barrier coatings. Three-tier pricing structure across sovereign-manufactured premium, dual-source standard, and import-dependent economy levels segments buyer access by certification tier and domestic content threshold. Cost-down pressure on rotary-wing avionics accelerates as Leonardo's Yeovil facility consolidates Wildcat and Merlin through-life support under consolidated availability contracts. Private contractors demonstrate highest price sensitivity due to performance-based penalty clauses, while Ministry of Defence central procurement exhibits lowest sensitivity given sovereign capability preservation mandates.
Supply Chain Analysis
Refurbishment flows for Typhoon and Tornado engine cores cycle through Rolls-Royce Bristol facilities before re-entering RAF operational squadrons, creating captive reverse logistics capacity unavailable to competing suppliers. Geographic supply concentration clusters in the United Kingdom for combat air final assembly, Italy for Leonardo rotary-wing subsystems, and the United States for F-35 Lightning II component sourcing. Raw material dependencies span titanium sponge from Kazakhstan and Japan, nickel superalloy precision forgings from Scottish Prestwick clusters, and specialized thermal barrier coating precursors from German chemical suppliers. Single-source vulnerability concentrates in Rolls-Royce military turbine production, where no qualified alternative exists for Tempest program propulsion requirements. Distribution runs through Ministry of Defence Defence Equipment and Support procurement channels with long-term framework agreements displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Military Aviation Market operates as a cost-of-compliance story where Military Aviation Authority certification standards aligned with NATO STANAG frameworks erect decade-long validation barriers that protect incumbent primes from agile challengers.
For Market Incumbents: Extend sovereign capability moats by deepening in-house production of nickel superalloy precision forgings at Scottish Prestwick facilities to offset titanium input volatility. Anchor supplier status under Defence and Security Industrial Strategy mandates should be leveraged to secure multi-decade through-life support contracts before Rapid Capabilities Office autonomous programs open entry points for software-native competitors.
For New Entrants and Emerging Players: Begin with electro-optical targeting subsystem development for Typhoon fleet upgrades, where South East England sensor clusters demonstrate penetrable white space absent BAE Systems or Rolls-Royce lock-in. Dual-use UAV corridor integration under Civil Aviation Authority frameworks offers the most accessible go-to-market angle, transferring commercial autonomous technology into military-autonomous architectures through controlled airspace pilot programs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap avionics specialists with Military Aviation Authority certification history in South East England electronics corridors. Long-term viability hinges on positioning within Tempest program supply tiers before sixth-generation platform investment peaks. Monitor Rapid Capabilities Office field-testing announcements for Project Mosquito and related uncrewed wingman programs as inflection indicators for autonomous collaborative platform budget allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Capability Preservation | Defence and Security Industrial Strategy domestic content thresholds lock BAE Systems and Rolls-Royce into anchor supplier positions for combat air systems. |
| Autonomous Systems Integration | Rapid Capabilities Office field-testing of Project Mosquito architectures redirects RAF operational doctrine toward uncrewed-manned teaming protocols. |
| Scottish Cluster Expansion | Prestwick precision forging capacity expansion secures nickel superalloy supply security for Tempest program propulsion timelines. |
| Through-Life Support Consolidation | Typhoon Total Availability Enterprise model extension to Tempest development locks suppliers into performance-based readiness guarantees. |
| Dual-Use UAV Corridor Development | Civil Aviation Authority controlled airspace frameworks open military-autonomous technology transfer pathways for non-traditional defense entrants. |
Research Methodology
Document review covered Ministry of Defence equipment plans, Military Aviation Authority certification protocols, and NATO STANAG framework documentation, complemented by interviews with RAF programme directors, BAE Systems platform engineers, Rolls-Royce propulsion specialists, and Leonardo supply chain managers. Secondary validation drew from UK Defence and Security Industrial Strategy publications, Scottish Enterprise aerospace innovation reports, and Civil Aviation Authority UAV corridor regulations. Bottom-up platform-level demand modeling triangulated against top-down Ministry of Defence budget allocation analysis.
Historical procurement patterns cross-referenced against expert panel input on Tempest program timelines and Integrated Review refresh commitments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass platform type, technology tier, end-user procurement channel, and application mission profile. CAGRs were derived from weighted scenario analysis incorporating sovereign capability preservation mandates and autonomous systems adoption curves. Industry-specific forecast inputs included RAF fleet modernization schedules and Scottish aerospace cluster capacity utilization rates.
Underlying measurement precision varies by segment; fighter aircraft and propulsion systems carry tighter precision given concentrated supplier visibility than UAV and communication systems categories where Rapid Capabilities Office program confidentiality constrains data availability. Forecasts reflect documented assumptions on Ministry of Defence budget continuity and NATO alliance commitment durability. Practitioners should monitor Integrated Review refresh implementation, titanium and nickel superalloy commodity price movements, and Military Aviation Authority certification timeline extensions for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aviation Crew Management System Market
Aircraft
Aerospace Winglet System Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Turboprop Aircraft Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Europe Aviation Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Air Starter Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Evtol Aircraft Market