
 Frame Alignment Systems Market | 2026-2036
Frame Alignment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Frame Alignment Systems Market Analysis
Market Context with Strategic Players
Fleet services is recalibrating procurement priorities toward faster throughput alignment systems. Chief Automotive Technologies leverages its technology leadership in computerized measuring to anchor North American workshop demand. Josam Products dominates European fleet installation contracts through manufacturing scale. Celette specializes in premium fixture systems for luxury vehicle repair networks.
Technical Definition and Structural Segments
Frame alignment systems are precision mechanical and electromechanical devices that restore vehicle chassis geometry to manufacturer specifications using calibrated reference points, hydraulic force application, and laser or optical measurement feedback. These systems correct structural deformation from collisions, wear, or manufacturing defects to ensure safe vehicle handling, tire longevity, and regulatory compliance. Digital aligners command the widest margin pools as workshops trade up from manual equipment, while laser-based technology leads growth due to faster cycle times and reduced technician training burdens. The service type segment shows calibration and maintenance outpacing installation revenue as installed bases mature across automotive workshops.
Regulatory Frame and Forward Outlook
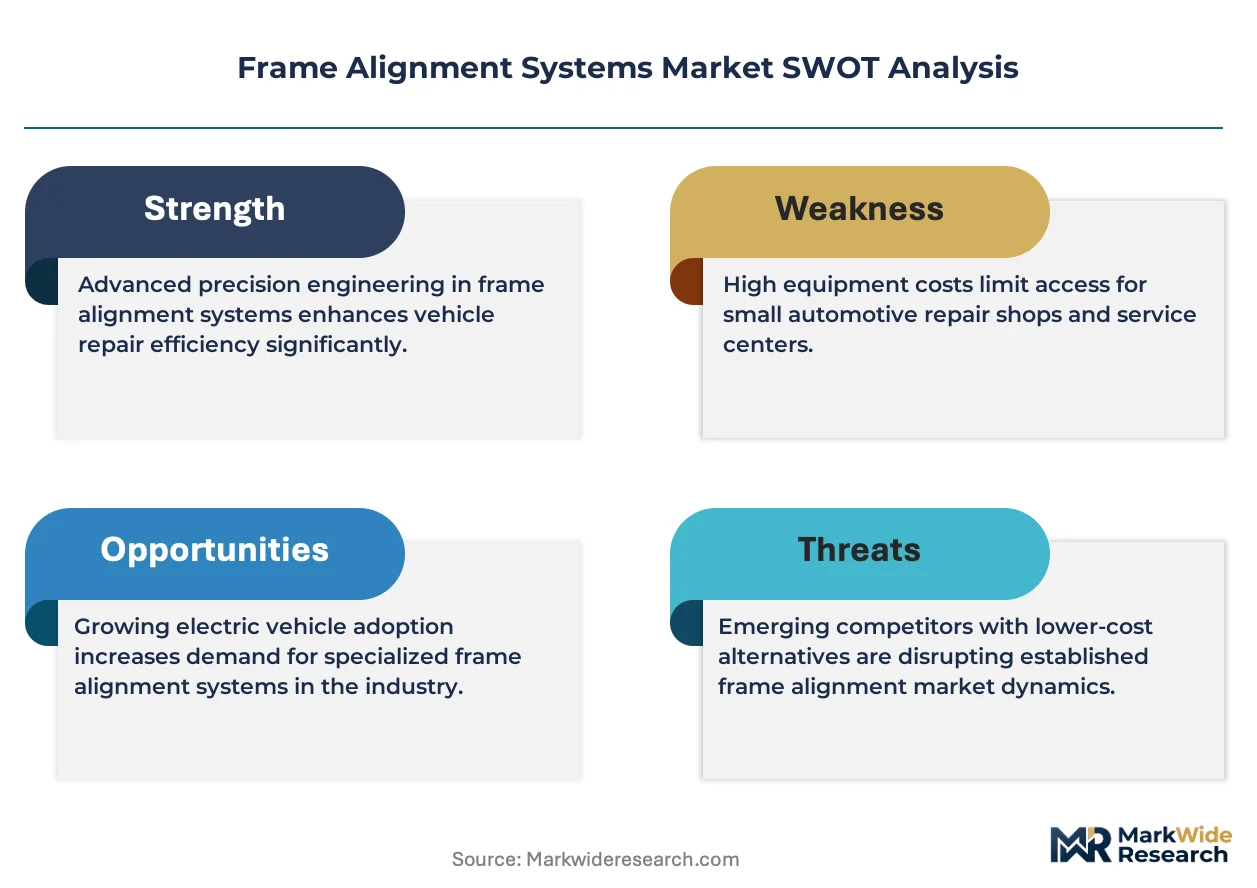
NHTSA crashworthiness standards and EPA emissions compliance requirements in the United States mandate precise structural repair documentation, while EU Green Deal circular-economy directives in Europe push extend-vehicle-life repair protocols over replacement. Germany's KBA enforces rigorous post-collision inspection protocols that directly specify alignment verification. Stakeholders must monitor how software-defined vehicle architectures alter chassis measurement reference databases and technician certification requirements.
Market Dynamics
Fleet operators are consolidating procurement around throughput-optimized computerized platforms, while collision repair networks face margin compression from EPA emissions documentation requirements and NHTSA structural repair traceability mandates. This dual pressure is compressing equipment replacement cycles and elevating calibration accuracy to a competitive differentiator.
Growth Catalysts
- EPA Vehicle Emissions Enforcement:United States repair documentation requirements mandate precise structural restoration verification, driving workshop investment in measurement-capable alignment systems.
- Software-Defined Vehicles:Chassis geometry reference databases now update over-the-air, requiring alignment platforms with live data connectivity to maintain measurement accuracy.
- Germany's Stuttgart-Munich Aftermarket Cluster:Dense concentration of premium vehicle service centers generates concentrated demand for high-precision fixture systems.
Market Restraints
- Hydraulic Component Supply Concentration:Precision actuator manufacturing concentrates among German and Japanese suppliers, exposing lead time volatility.
- Technician Certification Bottlenecks:OEM-specific training programs create regional service coverage gaps where certified operators are scarce.
- Mobile Alignment Substitutes:Portable laser systems encroach on fixed-platform revenue in light-duty fleet segments.
Strategic Opportunities
- EU Green Deal Circular-Economy Directives:Extend-vehicle-life repair protocols elevate structural restoration over component replacement in collision workflows.
- Subscription-Based Calibration Services:Recurring revenue models for software updates and measurement verification are penetrating independent workshop networks.
- AI-Enhanced Diagnostic Convergence:Machine vision integration with alignment platforms compresses technician decision time and reduces rework rates.
Industry Challenges
- Legacy Platform Integration Complexity:Older hydraulic systems lack data interfaces required by modern insurance documentation portals.
- Measurement Technician Skill Scarcity:Optical system operation and chassis geometry interpretation require specialized training pipelines that outpace workforce development.
Report Scope
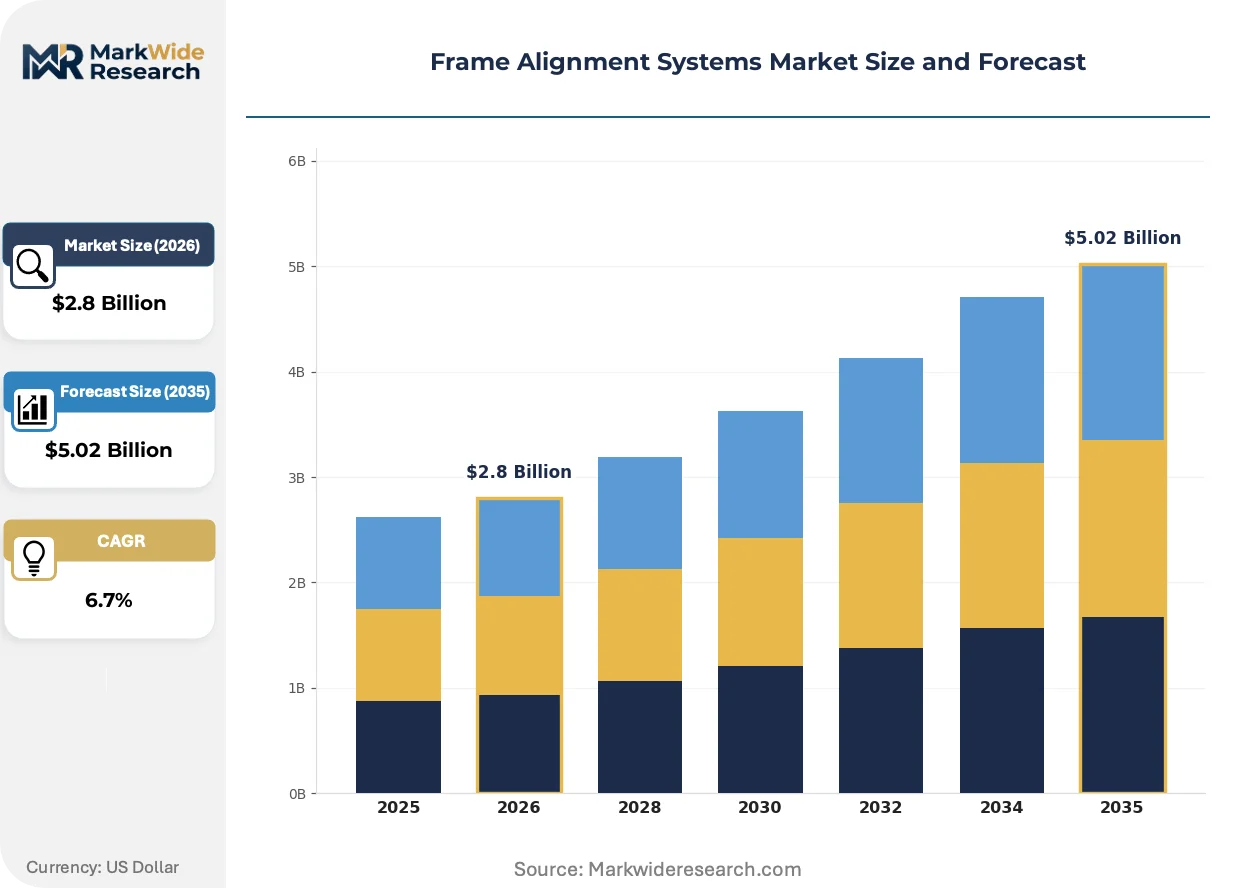
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frame Alignment Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Aligners, Digital Aligners, Hydraulic Aligners, Pneumatic Aligners End User: Automotive Workshops, Fleet Services, Body Shops, DIY Enthusiasts Technology: Laser-Based, Electromechanical, Optical, Computerized Service Type: Installation, Maintenance, Training, Calibration |
| Companies Covered | Josam Products, Bee Line, Chief Automotive Technologies, Car-O-Liner, Celette, Blackhawk, Pro Line Systems International, Booth Concepts, Chassis Alignment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frame Alignment Systems Market Emerging Trajectories
Measurement technology is fragmenting across multiple sensing modalities while regulatory documentation requirements harden data architecture standards. These forces are elevating software and connectivity to parity with mechanical precision in purchasing decisions.
Cloud-connected alignment platforms are decentralizing diagnostic authority from centralized OEM servers to workshop-level systems. Independent collision centers in the United States are adopting these systems fastest, compressing the historical advantage of dealer-affiliated repair networks in structural certification workflows.
REACH substance restrictions and RoHS compliance deadlines in Europe are forcing material substitutions in hydraulic fluids and electronic housings. Manufacturers serving the German market are reformulating component specifications ahead of enforcement windows, with premium fixture suppliers absorbing certification costs to maintain KBA approval status.
Buyer consolidation among national fleet management companies is compressing vendor negotiation cycles and unbundling after-sales service from equipment purchase. Large United States rental and logistics operators now procure alignment capacity through centralized maintenance contracts, displacing decentralized workshop purchasing authority.
Frame Alignment Systems Market Segmentation
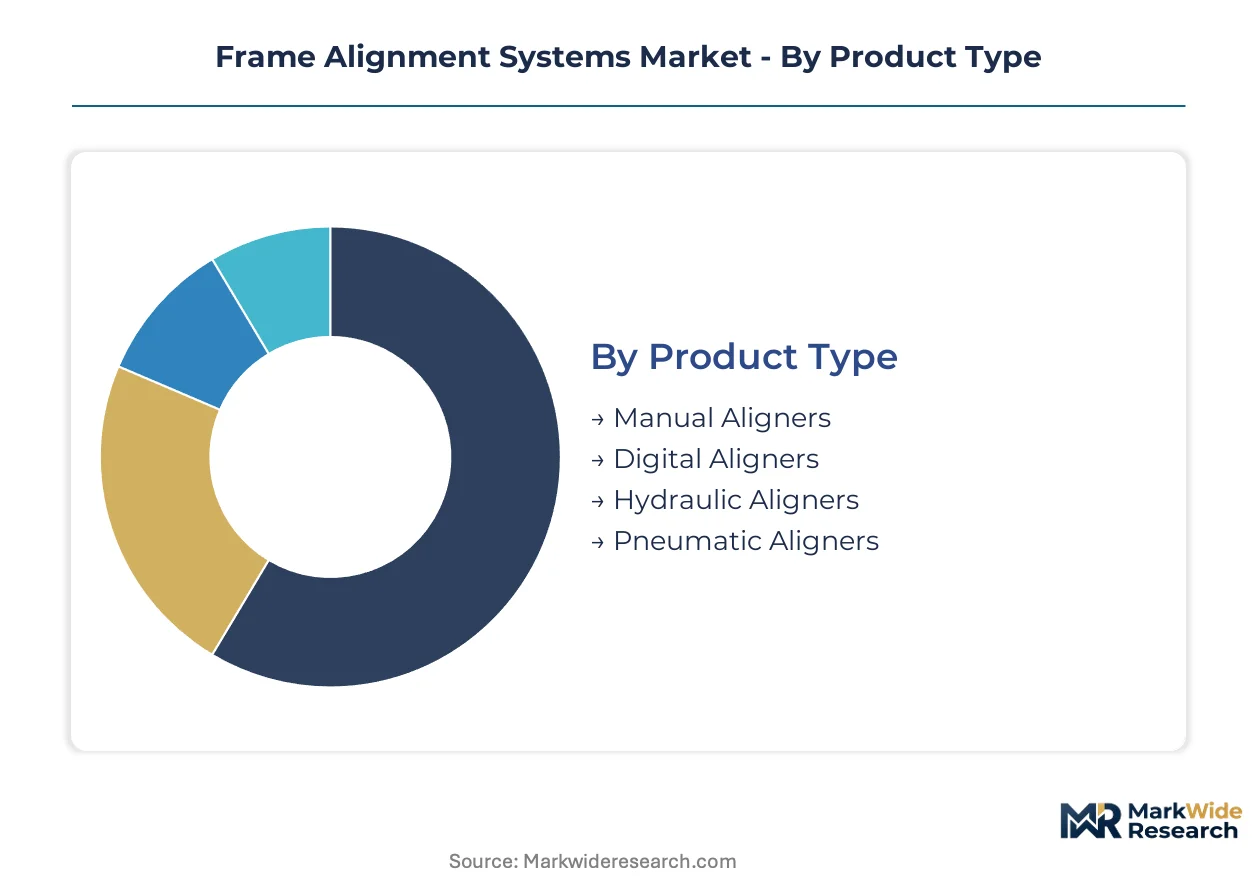
Workshop procurement patterns diverge sharply across product tiers and service models. Fleet operators prioritize throughput metrics while independent body shops balance capital constraints against regulatory documentation requirements.
Product Type:
Cost tier separates workshop buyers more than any other variable, with capital availability dictating precision levels and connectivity features.
- Digital Aligners:Computerized measurement platforms integrate laser sensors with cloud-based reference databases for real-time specification updates. United States collision repair networks facing NHTSA structural repair traceability mandates are consolidating procurement around these systems to automate documentation workflows.
- Hydraulic Aligners:Force application systems using precision actuators deliver the torque ranges required for heavy-duty commercial vehicle chassis restoration. German KBA post-collision inspection protocols specify alignment verification capabilities that hydraulic platforms with integrated measurement modules satisfy.
- Manual Aligners:Mechanical reference systems without electronic feedback serve cost-constrained independent workshops in mature aftermarket clusters.
- Pneumatic Aligners:Compressed-air force systems occupy a narrow niche for light-duty applications where shop air infrastructure already exists.
Digital aligners lead volumes today; hydraulic aligners are gaining share fastest in commercial fleet segments.
End User:
Volume scale and procurement centralization create distinct customer archetypes with incompatible service expectations.
- Fleet Services:National rental and logistics operators procure alignment capacity through centralized maintenance contracts, displacing decentralized workshop purchasing authority. These buyers demand throughput-optimized platforms with minimal technician training burdens to accommodate high staff turnover.
- Automotive Workshops:Independent service centers balance equipment versatility against bay utilization metrics. Germany's Stuttgart-Munich aftermarket cluster generates concentrated demand for high-precision fixture systems serving premium vehicle repair networks.
- Body Shops:Collision repair specialists face margin compression from EPA emissions documentation requirements and insurance documentation portal integration mandates.
- DIY Enthusiasts:Consumer-grade portable systems serve a limited aftermarket for personal vehicle maintenance.
Fleet services command the largest transaction sizes; automotive workshops represent the broadest installed base.
Technology:
Measurement modality selection now hinges on software connectivity and data architecture compliance rather than mechanical precision alone.
- Laser-Based:Optical triangulation systems deliver sub-millimeter accuracy with cycle times compressed below traditional methods. Cloud-connected platforms are decentralizing diagnostic authority from centralized OEM servers to workshop-level systems in United States independent collision centers.
- Computerized:Integrated sensor arrays with live data connectivity maintain measurement accuracy as software-defined vehicle architectures update chassis geometry reference databases over-the-air.
- Electromechanical:Hybrid force-and-measurement systems serve mid-tier workshops transitioning from manual methods.
- Optical:Camera-based systems without laser emitters occupy cost-sensitive market tiers.
Laser-based systems lead replacement demand; computerized platforms are expanding most quickly in dealer-affiliated networks.
Service Type:
Maturity of installed bases is shifting revenue mix from equipment sales toward recurring service relationships.
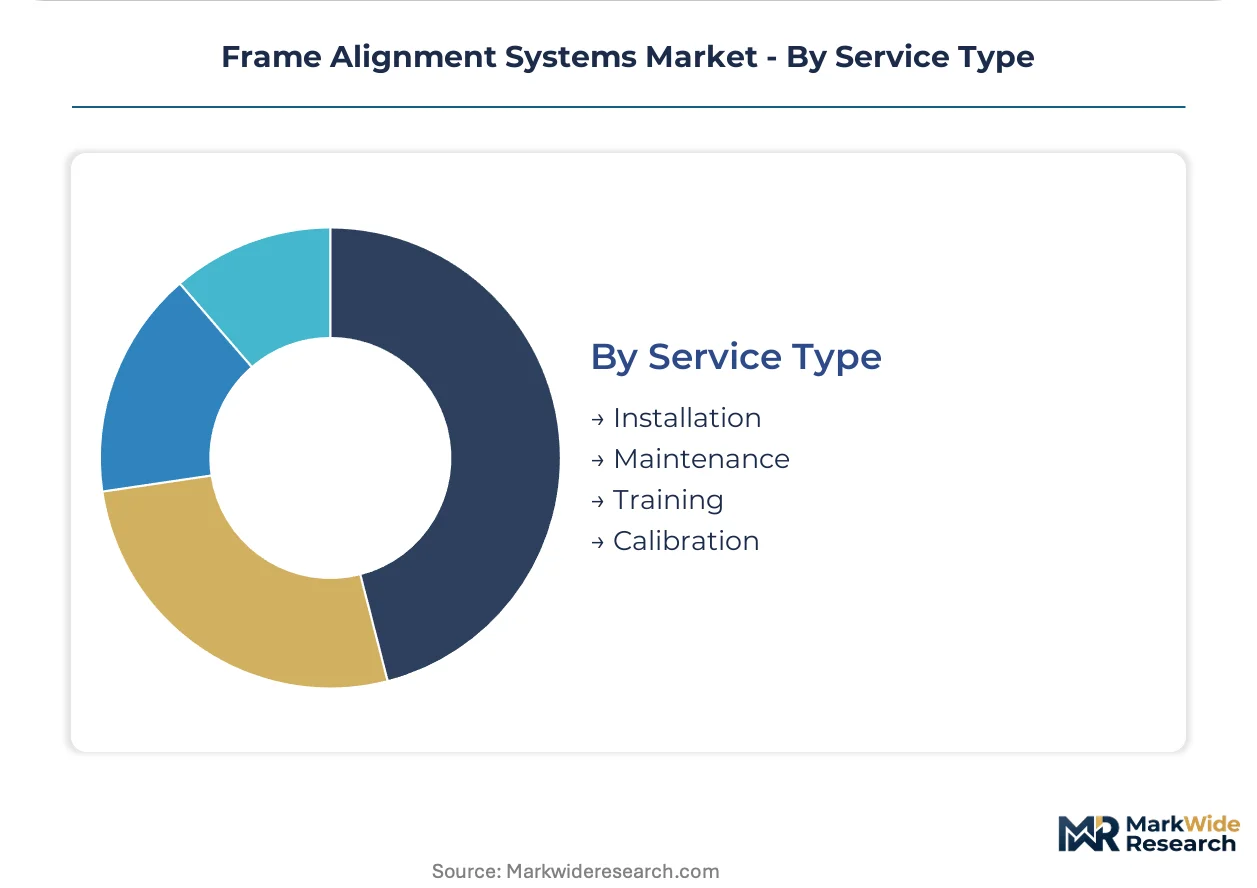
- Calibration:Measurement accuracy verification and reference standard updates now outpace installation revenue as digital aligner populations mature. Subscription-based models for software updates and measurement verification are penetrating independent workshop networks.
- Maintenance:Preventive service contracts for hydraulic actuator systems and sensor arrays generate recurring revenue streams.
- Installation:New equipment deployment concentrates in fleet consolidation events and workshop network expansions.
- Training:OEM-specific certification programs address technician skill scarcity in optical system operation and chassis geometry interpretation.
Calibration leads service revenue today; subscription-based maintenance contracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly capacity toward jurisdictions with streamlined vehicle equipment certification regimes and lower compliance documentation burdens.
United States
Fleet consolidation among national rental operators and logistics companies drives centralized procurement of throughput-optimized alignment platforms. NHTSA crashworthiness standards mandate structural repair traceability documentation that accelerates workshop investment in measurement-capable systems. The collision repair corridor spanning Texas, California, and the industrial Midwest concentrates independent body shop demand for cloud-connected diagnostic platforms.
Germany
Premium vehicle service networks around Stuttgart and Munich generate concentrated demand for high-precision fixture systems serving luxury marque repair workflows. KBA post-collision inspection protocols specify rigorous alignment verification requirements that elevate equipment certification standards. The Baden-Württemberg automotive aftermarket cluster anchors European procurement for computerized measuring platforms with integrated force application modules.
China
Domestic commercial vehicle fleet expansion and ride-hailing platform maintenance networks create scale demand for hydraulic alignment systems. MIIT vehicle safety inspection regulations tighten structural repair documentation requirements for commercial operators. The Yangtze River Delta manufacturing belt concentrates precision actuator component production, exposing supply chain lead time volatility to downstream system assemblers.
Japan
Precision manufacturing heritage sustains domestic demand for laser-based measurement systems with sub-millimeter accuracy specifications. METI industrial equipment efficiency standards incentivize platform upgrades that reduce technician cycle times and energy consumption. The Aichi Prefecture automotive supplier ecosystem anchors regional distribution networks serving Southeast Asian export markets.
India
Commercial vehicle fleet modernization and organized multi-brand service networks expand addressable market for mid-tier electromechanical alignment systems. BIS automotive equipment safety standards create compliance thresholds that filter sub-scale domestic manufacturers. The Maharashtra-Gujarat industrial corridor concentrates aftermarket distribution infrastructure serving northern and western logistics corridors.
Frame Alignment Systems Market Vendor Landscape
Technology licensing dominates the current landscape as established manufacturers partner with sensor and software providers to accelerate digital platform development. The vendor base organizes around three tiers: integrated multinational equipment suppliers with captive distribution networks, regional specialists serving fleet installation contracts, and component-focused fabricators supplying precision actuators and measurement modules. Two strategic archetypes define competitive positioning: throughput-optimized platform builders targeting fleet consolidation procurement, and precision-fixture specialists serving premium vehicle repair networks. Geographic expansion through distributor partnerships and vertical integration into sensor calibration services represent the dominant competitive moves.
Among North American equipment builders, Chief Automotive Technologies and Bee Line occupy positions within the fleet-focused tier, with the former exemplifying technology leadership in computerized measuring and the latter representing scale-driven penetration of rental and logistics operator maintenance contracts. European fixture specialists include Celette, a French-based manufacturer exemplifying premium-tier positioning for luxury vehicle repair networks, and Josam Products, a Swedish entity anchoring the regional fleet installation segment through manufacturing scale advantages. Blackhawk and Car-O-Liner represent diversified equipment portfolios spanning hydraulic force application and digital measurement integration.
| Leading Market Players |
|---|
| Josam Products |
| Bee Line |
| Chief Automotive Technologies |
| Car-O-Liner |
| Celette |
| Blackhawk |
| Pro Line Systems International |
| Booth Concepts |
| Chassis Alignment |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up collision equipment specialists anchor supply discipline through centralized procurement mandates, compressing distributor margins while elevating pricing power for measurement-integrated platforms serving United States fleet operators facing NHTSA documentation requirements.
Pricing Analysis
Distributor margin compression dominates channel economics as national fleet management companies consolidate procurement through direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels separates laser-based computerized systems from hydraulic force-application platforms and manual reference equipment. Pricing pressure stems from mobile laser alignment substitutes encroaching on light-duty fleet segments. Independent automotive workshops exhibit highest price sensitivity, while premium vehicle repair networks serving Germany's Stuttgart-Munich cluster absorb certification premiums for KBA-compliant fixture systems.
Supply Chain Analysis
Single-source vulnerability sits with precision hydraulic actuator manufacturing concentrated in Germany and Japan, exposing assemblers to lead time volatility. Downstream system production draws from Taiwanese sensor module suppliers, Chinese steel fabrication capacity, and Italian electronic control unit specialists. Raw material dependencies include high-grade alloy steel for fixture frames, precision-machined hydraulic components, and laser diode arrays. Tariff exposure on electromechanical subassemblies threatens margin stability for North American equipment builders. Distribution runs through captive OEM service networks and independent aftermarket distributors serving collision repair corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-enabled calibration services and premium-tier fixture systems, justified by fleet procurement consolidation that rewards throughput-optimized platforms with recurring revenue attachment.
For Market Incumbents: Lock in fleet installation contracts through subscription-based calibration service bundling, offsetting mobile laser substitution threats in light-duty segments. Deepen backward integration into sensor calibration capabilities to capture documentation workflow value from EPA emissions enforcement and NHTSA structural repair traceability mandates. Prioritize cloud-connectivity R&D to maintain measurement accuracy as software-defined vehicle architectures update chassis geometry reference databases over-the-air. For New Entrants and Emerging Players: The price-point gap between premium laser-based systems and economy manual aligners creates entry space for mid-tier electromechanical platforms with modular upgrade paths. Target India's organized multi-brand service networks expanding across the Maharashtra-Gujarat industrial corridor, where BIS compliance thresholds filter sub-scale domestic competition. Deploy technician certification partnerships as the primary go-to-market angle, addressing skill scarcity in optical system operation and chassis geometry interpretation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hydraulic component fabricators lacking digital measurement integration, presenting consolidation targets for platform builders seeking captive supply of precision actuators. Long-term viability frames around software-defined vehicle penetration rates and collision repair network consolidation trajectories. Monitor Germany's KBA enforcement intensity as the signal indicating premium-tier equipment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Platform Development | Enables real-time chassis geometry database updates for software-defined vehicles. |
| Subscription Calibration Services | Captures recurring revenue from mature digital aligner installed bases. |
| Backward Integration into Sensors | Secures measurement module supply against Taiwanese supplier concentration. |
| Technician Certification Partnerships | Addresses optical system skill gaps compressing workshop productivity. |
| EU Green Deal Compliance Positioning | Aligns extend-vehicle-life repair protocols with circular-economy directives. |
Methodological Framework
Multiple input streams — structured interviews with collision repair network operators, fleet maintenance procurement directors, and aftermarket equipment distributors; trade data from customs records and automotive supplier filings; and technical documentation from NHTSA and Germany's KBA — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged equipment manufacturer product managers, hydraulic component engineers, and insurance documentation portal developers. Secondary validation drew from EPA enforcement guidance, EU Green Deal implementation texts, and vehicle production databases.
Historical alignment equipment shipment patterns were cross-referenced against panel input from procurement executives at national rental operators and logistics companies. The analytical framework modeled volume and value across product type, technology modality, end-user archetype, and service revenue mix throughout the forecast period. CAGRs were derived from equipment replacement cycle compression rates and software-enabled service attachment trajectories. Industry-specific inputs included software-defined vehicle penetration assumptions and collision repair network consolidation timelines.
Caveats apply where NHTSA enforcement intensity shifts, EU circular-economy directive implementation accelerates, or hydraulic component supply disruptions from German and Japanese suppliers could materially shift the outlook. Forecasts reflect documented assumptions about fleet procurement centralization and technician certification pipeline development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Narrowbody Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Aircraft Exterior Strip and Repaint Services Market