
 Middle-East and Africa Military Aviation Market | 2026-2036
Middle-East and Africa Military Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Military Aviation Market Foresight
The gap between fifth-generation fighter platforms and legacy rotorcraft fleets is shifting procurement priorities across Middle-East and Africa defense establishments. Lockheed Martin Corporation leverages its F-35 program footprint to sustain long-term engagement with Gulf air forces seeking interoperable NATO-standard assets. Boeing anchors regional helicopter modernization through Apache and Chinook sustainment contracts. Turkish Aerospace Industries competes aggressively in African markets with cost-effective unmanned aerial systems and light attack aircraft.
Military aviation encompasses fixed-wing, rotary-wing, and unmanned aerial platforms engineered for defense missions, typically operating at Mach 0.8 to Mach 2.5 speeds with service ceilings exceeding 50,000 feet and incorporating radar-absorbent materials or electronic countermeasure suites. Avionics and combat systems segments command disproportionate margin pools as software-defined architectures replace analog legacy systems. Military fixed-wing aircraft retain volume leadership in contract value, though drones represent the fastest-expanding category as asymmetric warfare doctrines proliferate across Sahel and Horn of Africa theaters. Propulsion systems specialization determines supplier stickiness given engine certification cycles spanning decades.
Saudi Arabia's General Authority for Military Industries and South Africa's Armaments Corporation impose local content thresholds that reshape vendor selection criteria and offset obligations. Israel's Ministry of Defense and the UAE's Tawazun Council coordinate technology transfer requirements that condition market access on joint production commitments. Stakeholders must monitor how evolving offset frameworks and indigenous capability targets redistribute contract flows between established OEMs and emerging regional champions.
Market Dynamics
Indigenous manufacturing mandates across Gulf Cooperation Council states are restructuring vendor selection criteria, forcing original equipment manufacturers to surrender intellectual property and establish joint production facilities as a condition of contract award.
Growth Catalysts
- Offset Frameworks:Saudi Arabia's General Authority for Military Industries imposes local content thresholds that redirect contract flows toward joint ventures with domestic partners.
- Asymmetric Warfare Doctrines:Sahel and Horn of Africa theaters prioritize unmanned aerial systems for intelligence, surveillance, and reconnaissance missions without pilot risk exposure.
- Rotary-Wing Modernization:Aging helicopter fleets across the United Arab Emirates and Qatar drive sustainment contracts and platform replacement programs.
Market Restraints
- Engine Certification Cycles:Propulsion systems specialization creates supplier stickiness spanning decades, limiting vendor switching for air forces seeking platform upgrades.
- Technology Transfer Friction:Israel's Ministry of Defense restricts export of sensitive avionics and radar-absorbent materials, constraining regional interoperability.
- Skilled Workforce Scarcity:Maintenance, repair, and overhaul capabilities concentrate in South Africa and Turkey, creating geographic bottlenecks for distributed fleet support.
Strategic Opportunities
- East African Air Defense Gaps:Kenya and Ethiopia seek cost-effective light attack aircraft and unmanned platforms to secure porous borders and counter insurgent mobility.
- Software-Defined Architectures:Analog legacy avionics replacement opens margin pools for systems integrators capable of retrofitting fourth-generation fighters with open mission systems.
- Tawazun Council Coordination:The UAE's technology transfer requirements create pathways for foreign OEMs to establish permanent engineering centers in Abu Dhabi and Dubai.
Industry Challenges
- Interoperability Certification:NATO-standard asset integration with legacy Soviet-era platforms requires custom middleware development and extended flight testing protocols.
- Supply Chain Reconfiguration:Western component embargoes force rapid qualification of alternative avionics suppliers, compressing qualification timelines without compromising airworthiness standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Military Aviation Market |
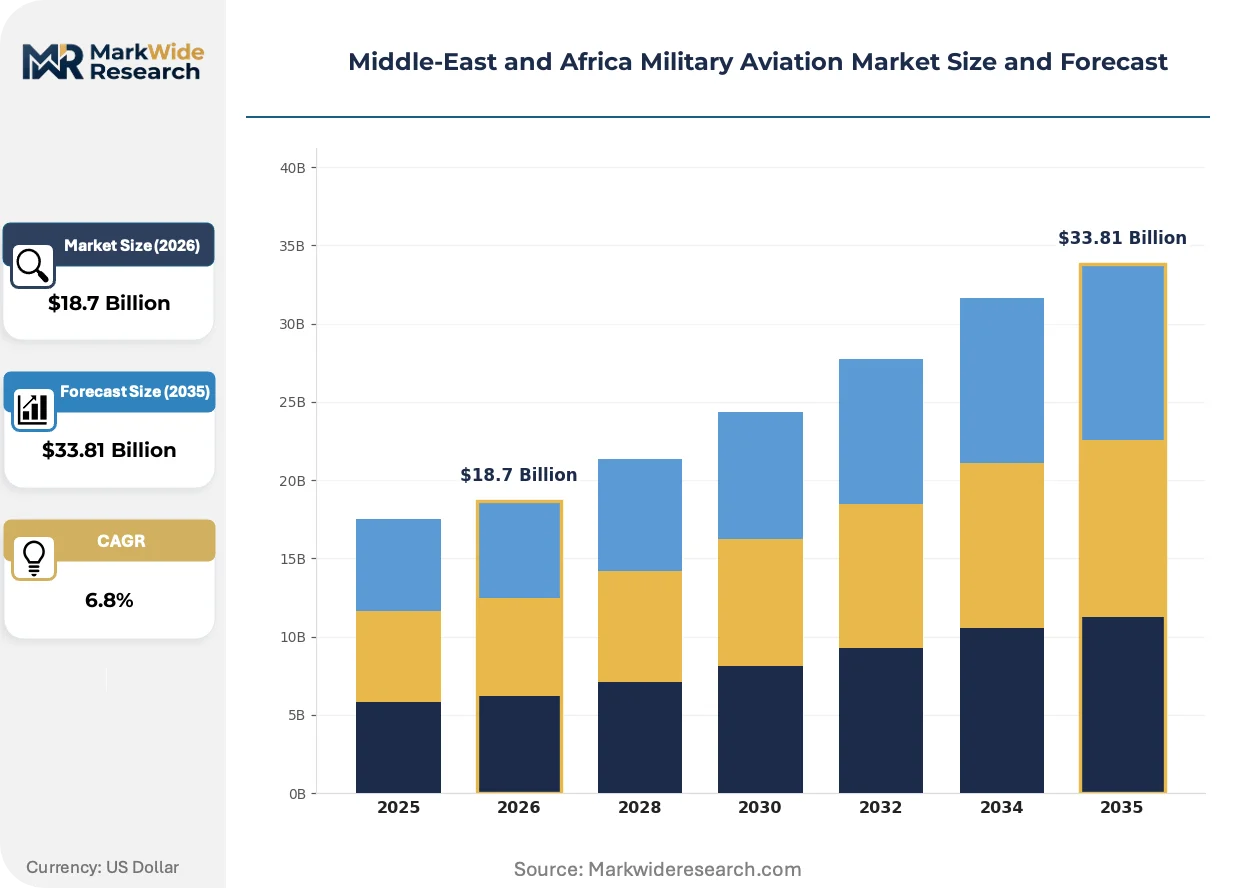
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Fixed-Wing Aircraft, Military Helicopters, Drones, Support Equipment End User: Air Forces, Defense Ministries, Private Contractors, Security Agencies Technology: Avionics, Propulsion Systems, Navigation Systems, Combat Systems Service Type: Maintenance, Training, Logistics, Research & Development |
| Companies Covered | Airbus SE, Lockheed Martin Corporation, The Boeing Company, Dassault Aviation, Turkish Aerospace Industries, Israel Aerospace Industries Ltd, BAE Systems PLC, Northrop Grumman Corporation, RTX Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Military Aviation Market Shifts & Advancements
Software-defined mission systems are displacing hardware-locked avionics across fixed-wing and rotary platforms, enabling rapid capability insertion through firmware updates rather than physical retrofit cycles.
Open systems architecture is modularizing radar and electronic warfare suites, permitting Gulf air forces to mix subsystems from competing suppliers without platform lock-in. Royal Saudi Air Force F-15 modernization programs adopt modular mission computers to accelerate threat library updates. This architecture compresses upgrade cycles from years to months and fragments supplier power away from vertically integrated primes.
The UAE's Tawazun Council mandates joint production commitments as a condition of market access, conditioning contract awards on technology transfer depth rather than unit pricing alone. Defense primes must embed engineering talent in-country and surrender source code for mission-critical subsystems. Rotary-wing and unmanned categories face the most stringent localization thresholds, reshaping offset negotiation leverage.
Air forces across the region unbundle after-sales service from initial platform procurement, separating maintenance contracts from acquisition awards to introduce competitive pressure on sustainment pricing. The South African Air Force and Egyptian Air Force now tender logistics support independently of airframe purchase agreements. This pattern concentrates in markets with mature maintenance infrastructure and experienced technical labor pools.
Middle-East and Africa Military Aviation Market Segmentation
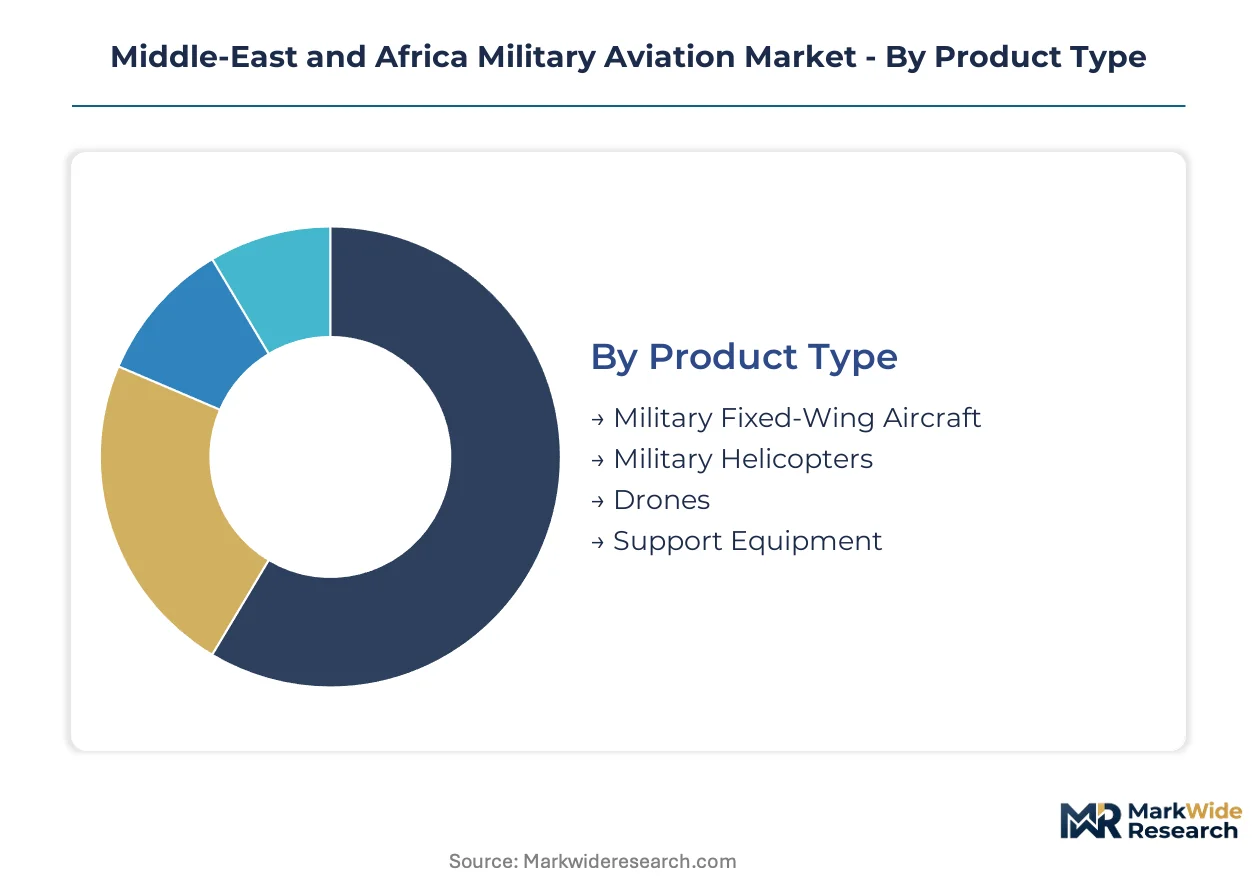
Segmentation in Middle-East and Africa military aviation reveals how procurement budgets fragment across platform categories and service requirements. Capital allocation patterns differ sharply between Gulf states prioritizing fleet modernization and African defense establishments seeking cost-effective sustainment solutions.
Product Type:
Fixed-wing platforms demand the heaviest upfront capital commitment, with fifth-generation fighter programs consuming multi-billion dollar outlays over decade-long procurement cycles.
- Military Fixed-Wing Aircraft:Multirole fighters and transport aircraft engineered for Mach 0.8 to Mach 2.5 speeds with service ceilings exceeding 50,000 feet. Saudi Arabia and the United Arab Emirates concentrate demand through F-15 and F-35 acquisition programs driven by interoperability requirements with NATO allies.
- Drones:Unmanned aerial systems spanning tactical ISR platforms to armed combat variants with satellite communication relay capabilities. Sahel and Horn of Africa theaters prioritize these assets for asymmetric warfare missions where pilot risk exposure is unacceptable.
- Military Helicopters:Rotary-wing platforms including attack, utility, and heavy-lift configurations. Aging fleets across Qatar and Kuwait drive Apache and Chinook modernization contracts.
- Support Equipment:Ground-based systems encompassing flight simulators, refueling apparatus, and mobile maintenance units. South Africa's Armaments Corporation sources these through local content mandates.
Military fixed-wing aircraft absorb the bulk of installed capacity; drones are expanding most quickly across theaters with limited pilot availability.
End User:
Customer type determines procurement authority and budget scale, with institutional buyers exercising distinct technical specifications and offset negotiation leverage.
- Air Forces:Operational commands controlling fleet deployment and mission readiness. Royal Saudi Air Force and Israeli Air Force dominate regional procurement volume through sovereign defense appropriations.
- Defense Ministries:Centralized procurement authorities setting capability targets and vendor qualification standards. These entities impose technology transfer requirements that reshape contract structures.
- Private Contractors:Commercial entities providing outsourced flight training, logistics support, and platform leasing. Their presence concentrates in markets with limited indigenous maintenance infrastructure.
- Security Agencies:Paramilitary organizations operating surveillance and border patrol missions. Kenyan and Ethiopian agencies drive demand for light attack aircraft and tactical unmanned systems.
Air Forces command the dominant share of platform acquisition budgets; private contractors are gaining share fastest where maintenance capacity bottlenecks persist.
Technology:
Technology segmentation tracks how value migrates from hardware to software-defined architectures across mission-critical subsystems.
- Avionics:Cockpit instrumentation, flight management computers, and sensor fusion architectures. Royal Saudi Air Force F-15 modernization programs adopt modular mission computers to compress upgrade cycles.
- Combat Systems:Radar, electronic warfare suites, and weapons integration interfaces. These subsystems command disproportionate margin pools as open architecture standards fragment supplier power.
- Propulsion Systems:Turbofan and turboshaft engines with certification cycles spanning decades. Supplier stickiness limits vendor switching for air forces seeking platform upgrades.
- Navigation Systems:GPS-denied positioning, inertial reference units, and terrain-following radar. Israeli Ministry of Defense restrictions on sensitive technology constrain regional availability.
Avionics captures the largest development expenditure; combat systems are climbing the fastest as threat library updates accelerate.
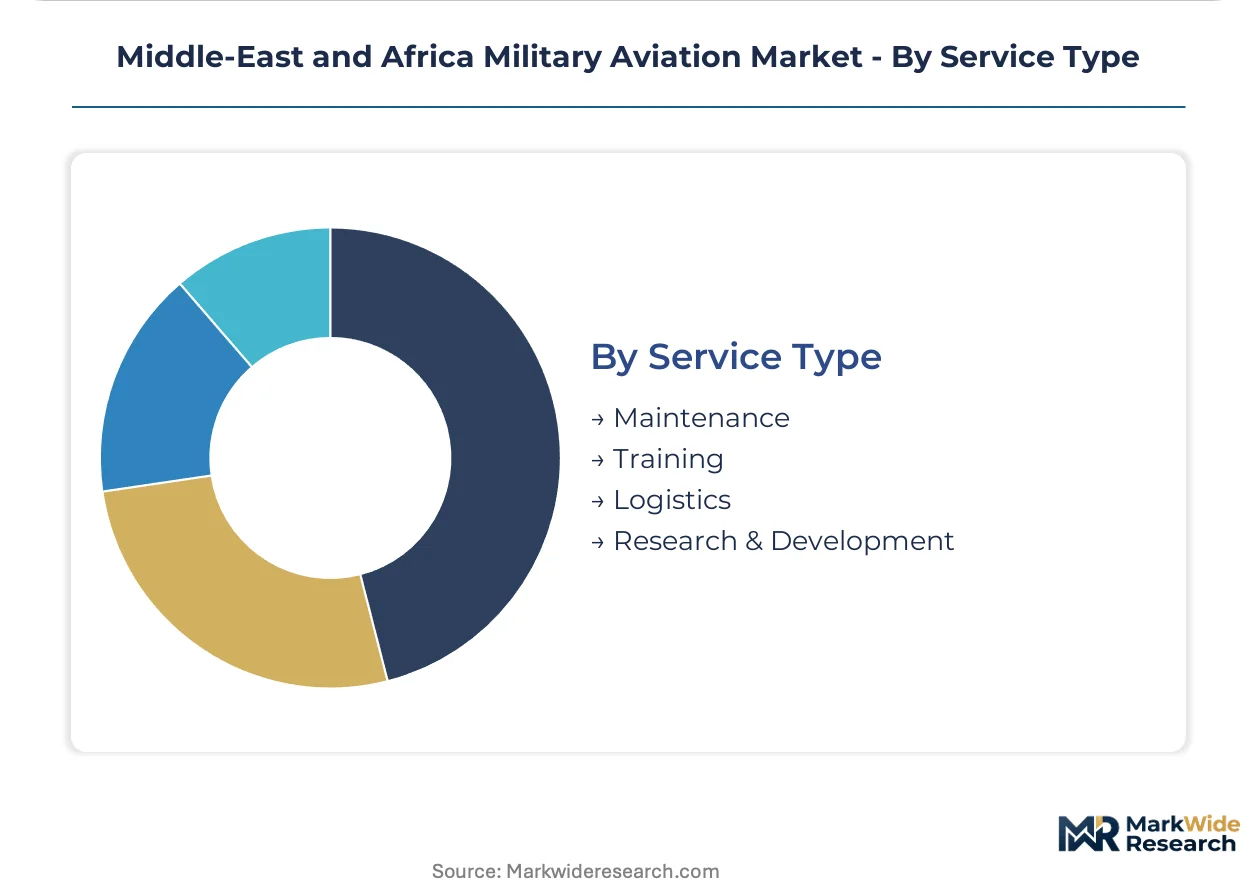
Service Type:
Service segmentation reflects the unbundling of after-sales support from initial platform procurement across mature defense markets.
- Maintenance:Scheduled overhaul, component repair, and airworthiness certification services. South African Air Force and Egyptian Air Force now tender logistics support independently of airframe purchases.
- Training:Pilot instruction, simulator-based mission rehearsal, and technical certification programs. These services concentrate where skilled workforce scarcity limits indigenous capability.
- Logistics:Spare parts distribution, supply chain management, and deployed field support. Geographic bottlenecks emerge as maintenance capabilities concentrate in Turkey and South Africa.
- Research & Development:Joint technology programs, prototype integration, and indigenous platform development. UAE's Tawazun Council mandates these commitments as conditions of market access.
Maintenance represents the largest ongoing expenditure category; research and development is gaining share fastest under localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi's Tawazun Council headquarters anchors the region's most aggressive technology transfer regime, conditioning multi-billion dollar contract awards on joint production commitments and permanent engineering center establishment.
Saudi Arabia
The General Authority for Military Industries mandates local content thresholds that redirect fighter procurement toward joint ventures with domestic partners. SAMI Aerospace coordinates offset negotiations for F-15 modernization and drone manufacturing programs. Riyadh's King Salman Industrial City hosts emerging assembly facilities where foreign OEMs embed technical personnel under sovereign control.
United Arab Emirates
Al Tariq bin Fahd Al Mansouri oversees the Tawazun Council's coordination of technology transfer requirements that condition F-35 access on source code surrender for mission-critical subsystems. Dubai's Mohammed bin Rashid Aerospace Hub concentrates engineering talent pools for unmanned platform development. Abu Dhabi's defense procurement authority now unbundles maintenance contracts from initial platform awards.
Israel
The Ministry of Defense restricts export of sensitive avionics and radar-absorbent materials, constraining regional interoperability for Gulf air forces seeking NATO-standard integration. Israel Aerospace Industries develops indigenous unmanned platforms that illustrate domestic manufacturing capabilities. Tel Aviv's defense technology corridor hosts classified R&D facilities for electronic warfare suite miniaturization.
South Africa
The Armaments Corporation imposes local content mandates that reshape vendor selection criteria for support equipment and rotary-wing sustainment. Skilled workforce scarcity elsewhere in the region concentrates maintenance, repair, and overhaul capabilities in Pretoria's industrial belt. Cape Town's technical training institutes supply certified aviation mechanics to distributed African fleet operators.
Turkey
Turkish Aerospace Industries competes aggressively in African markets with cost-effective unmanned aerial systems and light attack aircraft priced below Western alternatives. Ankara's defense procurement authority leverages NATO membership for subsystem interoperability certification. Istanbul's aviation cluster houses propulsion systems specialists whose certification cycles span decades and create supplier stickiness.
Middle-East and Africa Military Aviation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology transfer depth and sovereign offset compliance. The vendor base fragments between vertically integrated primes controlling propulsion certification and modular systems integrators exploiting open architecture standards. Three archetypes dominate: defense conglomerates with decades-long engine supply relationships, state-affiliated champions leveraging domestic procurement preference, and specialist unmanned platform developers capturing asymmetric warfare budgets. Competitive moves concentrate on joint venture formation for local production rights and firmware-based capability insertion to compress upgrade cycles.
Among American defense conglomerates, Lockheed Martin Corporation and The Boeing Company occupy positions reflecting divergent platform strategies—fixed-wing stealth integration versus rotary-wing fleet sustainment. Airbus SE represents the European tier competing on NATO interoperability and civil-military dual-use manufacturing scale. Within the state-affiliated champion archetype, Turkish Aerospace Industries and Israel Aerospace Industries Ltd exemplify how domestic manufacturing mandates redistribute contract flows toward regional engineering centers.
| Leading Market Players |
|---|
| Airbus SE |
| Lockheed Martin Corporation |
| The Boeing Company |
| Dassault Aviation |
| Turkish Aerospace Industries |
| Israel Aerospace Industries Ltd |
| BAE Systems PLC |
| Northrop Grumman Corporation |
| RTX Corporation |
| Others |
Supply & Pricing Matrix
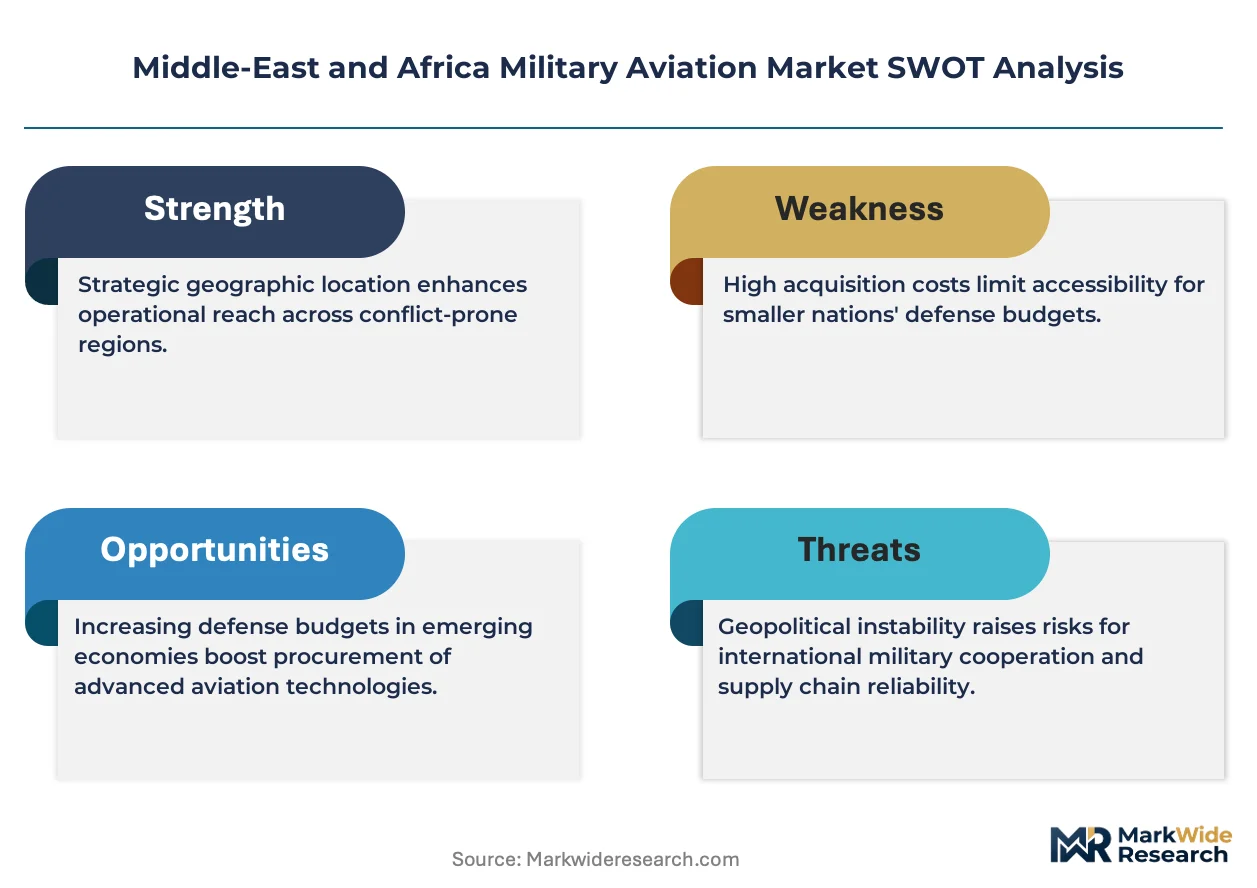
Software-defined mission systems are displacing hardware-locked avionics across fixed-wing and rotary platforms, compressing upgrade cycles from years to months while fragmenting supplier power away from vertically integrated primes. This shift simultaneously reduces physical retrofit costs and redistributes margin pools toward firmware developers, altering how Gulf air forces negotiate platform sustainment contracts and joint production commitments.
Pricing Analysis
Value-based pricing anchored to mission readiness uptime dominates fighter and helicopter sustainment contracts, with Royal Saudi Air Force and UAE procurement authorities unbundling after-sales service from initial platform awards to introduce competitive pressure. Price differentiation hinges on technology transfer depth and local content thresholds imposed by the General Authority for Military Industries and Tawazun Council, with joint ventures commanding premiums over direct foreign sales. Cost compression in rotary-wing modernization runs through South African and Turkish maintenance hubs where skilled labor scarcity concentrates bargaining power. Air forces with mature infrastructure exhibit lowest price sensitivity; paramilitary security agencies in East Africa face acute budget constraints and prioritize unit economics over capability depth.
Supply Chain Analysis
Freight costs for oversized airframe components and precision avionics modules concentrate supply planning around Turkey, South Africa, and the UAE's Mohammed bin Rashid Aerospace Hub, where multimodal logistics infrastructure supports just-in-time delivery to dispersed fleet operators. Propulsion systems specialization draws from US and UK engine certification cycles spanning decades, creating supplier stickiness that limits vendor switching for platform upgrades. Single-source vulnerability pervades radar-absorbent materials and sensitive electronic warfare subsystems where Israel's Ministry of Defense restricts export. Distribution runs through sovereign offset frameworks that mandate in-country assembly and embedded engineering personnel, transforming traditional OEM-customer relationships into permanent joint venture structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engine certification cycles spanning decades constrain propulsion systems supply, propping pricing power for incumbent turbine manufacturers and forcing air forces into long-term sole-source dependencies that resist competitive tendering.
For Market Incumbents: Acquire software-defined architecture capabilities and modular mission computer specialists to defend against open-systems integrators fragmenting avionics margins. Lockheed Martin Corporation and The Boeing Company must embed engineering talent in Saudi Arabia's King Salman Industrial City and Abu Dhabi's defense procurement authority to satisfy Tawazun Council localization mandates before Turkish Aerospace Industries captures rotary-wing sustainment contracts through cost-effective unmanned platforms. For New Entrants and Emerging Players: Digital-channel routes through government-to-government offset negotiation platforms offer entry pathways into East African air defense gaps where Kenya and Ethiopia seek cost-effective light attack aircraft. Target security agency procurement in the Sahel and Horn of Africa theaters, where asymmetric warfare doctrines prioritize tactical unmanned systems and pilot risk avoidance over NATO-standard interoperability. Partner with South Africa's Armaments Corporation to leverage Pretoria's concentrated maintenance, repair, and overhaul capabilities as a regional service hub. For Investors and Strategic Acquirers: Exit pathways concentrate in defense conglomerates with decades-long engine supply relationships and state-affiliated champions capturing domestic procurement preference through sovereign manufacturing mandates. Long-term viability favors vertically integrated primes controlling propulsion certification or modular systems integrators exploiting open architecture standards. Watch for Tawazun Council and General Authority for Military Industries escalation of source code surrender requirements as the inflection signal reshaping contract negotiation leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Production Facility Establishment | Tawazun Council mandates condition F-35 access on permanent engineering center embedding in Abu Dhabi. |
| Software-Defined Avionics Migration | Royal Saudi Air Force F-15 modernization adopts modular mission computers to compress threat library update cycles. |
| Rotary-Wing Sustainment Unbundling | South African Air Force and Egyptian Air Force now tender logistics support independently of airframe purchases. |
| Unmanned Platform Localization | Israel Aerospace Industries' indigenous development illustrates how domestic mandates reshape procurement patterns. |
| Propulsion Systems Certification Investment | Turkish Aerospace Industries leverages Ankara's NATO membership for subsystem interoperability certification spanning decades. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with air force procurement officers, defense ministry capability planners, offset negotiation specialists, and maintenance directorate leads. Secondary sources encompassed SAMI Aerospace program disclosures, Tawazun Council technology transfer guidelines, Israel Ministry of Defense export restriction notices, and South African Armaments Corporation local content mandates. Bottom-up platform delivery tracking and top-down defense budget appropriation analysis were triangulated to reconcile contract value estimates.
Data-stream reconciliation across fixed-wing, rotary-wing, unmanned, and support equipment categories informed analytical framework construction across the projection horizon. Segmentation dimensions encompassed platform type, end-user authority, technology subsystem, and service requirement, with particular weighting to avionics and combat systems margin migration. CAGRs were derived from sovereign defense appropriation trajectories and documented procurement pipeline values, incorporating propulsion systems certification timelines and software-defined upgrade cycle compression as industry-specific forecast inputs.
The model holds under sustained localization mandate enforcement and stable NATO-Gulf interoperability requirements; deviation in offset framework relaxation or Western component embargo escalation would shift contract flow distributions. Forecasts reflect documented procurement authority commitments and technology transfer negotiation positions. Stakeholders should weight assumptions against their own operating context and sovereign partnership structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Global Flying Cars Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Flying Taxi Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Airborne Pods Market