
 Aircraft Tire Balancer Market | 2026-2036
Aircraft Tire Balancer Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Tire Balancer Market Insights
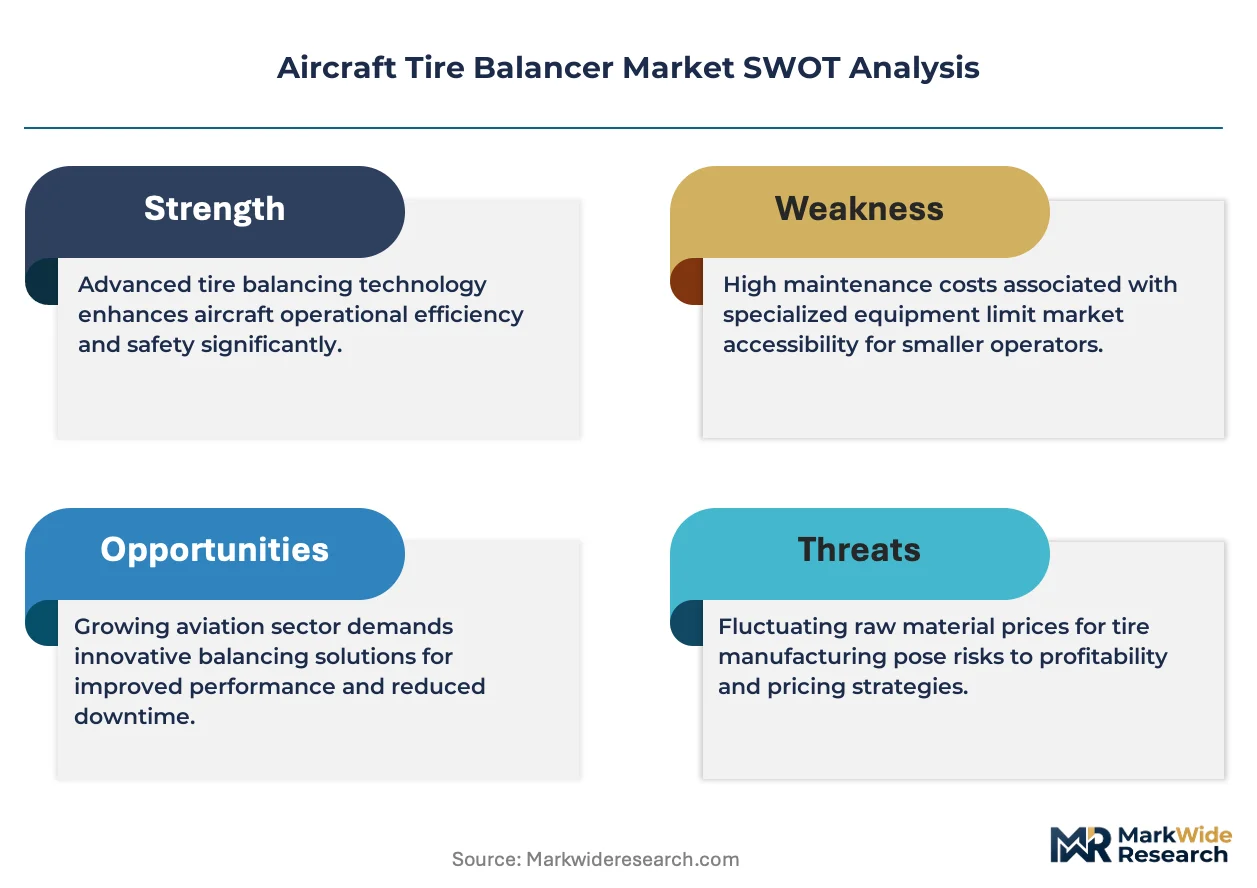
Buyer concentration among aircraft maintenance centers is expanding as regional airlines consolidate servicing contracts with large multi-facility operators. McFarlane leverages its parts distribution network to supply balancer consumables across North American general aviation channels. Tronair anchors ground support equipment portfolios with portable balancing systems for remote airfield operations. Goodyear competes through tire-and-balancer bundling programs at commercial airline maintenance hubs.
An aircraft tire balancer is a precision instrument that detects and corrects mass asymmetry in aviation tires and wheel assemblies, typically achieving balance tolerances within 0.05 ounce-inches to prevent airframe vibration and landing gear fatigue. The device serves the essential commercial purpose of ensuring FAA and EASA compliance while extending tire service life and reducing brake system wear. Dynamic balancers command the premium product tier due to electromechanical sensor complexity and higher throughput at commercial maintenance centers. Digital technology adoption is accelerating fastest among defense contractors seeking automated data logging for military airworthiness documentation. Portable balancers occupy a specialized niche serving regional aircraft repair stations with limited hangar infrastructure.
FAA airworthiness directives mandate periodic tire balance verification under 14 CFR Part 43 maintenance standards, while EASA implements comparable requirements through Part-145 approved organization frameworks. The EPA regulates solvent-based cleaning compounds used in balancer maintenance cycles, pushing manufacturers toward aqueous cleaning system integration. ISO 9001 and AS9100 quality certifications function as de facto market access requirements for balancer suppliers serving tier-one airlines and defense procurement channels. Stakeholders must monitor evolving MRO consolidation patterns and electromechanical technology substitution timelines to calibrate portfolio positioning.
Market Dynamics
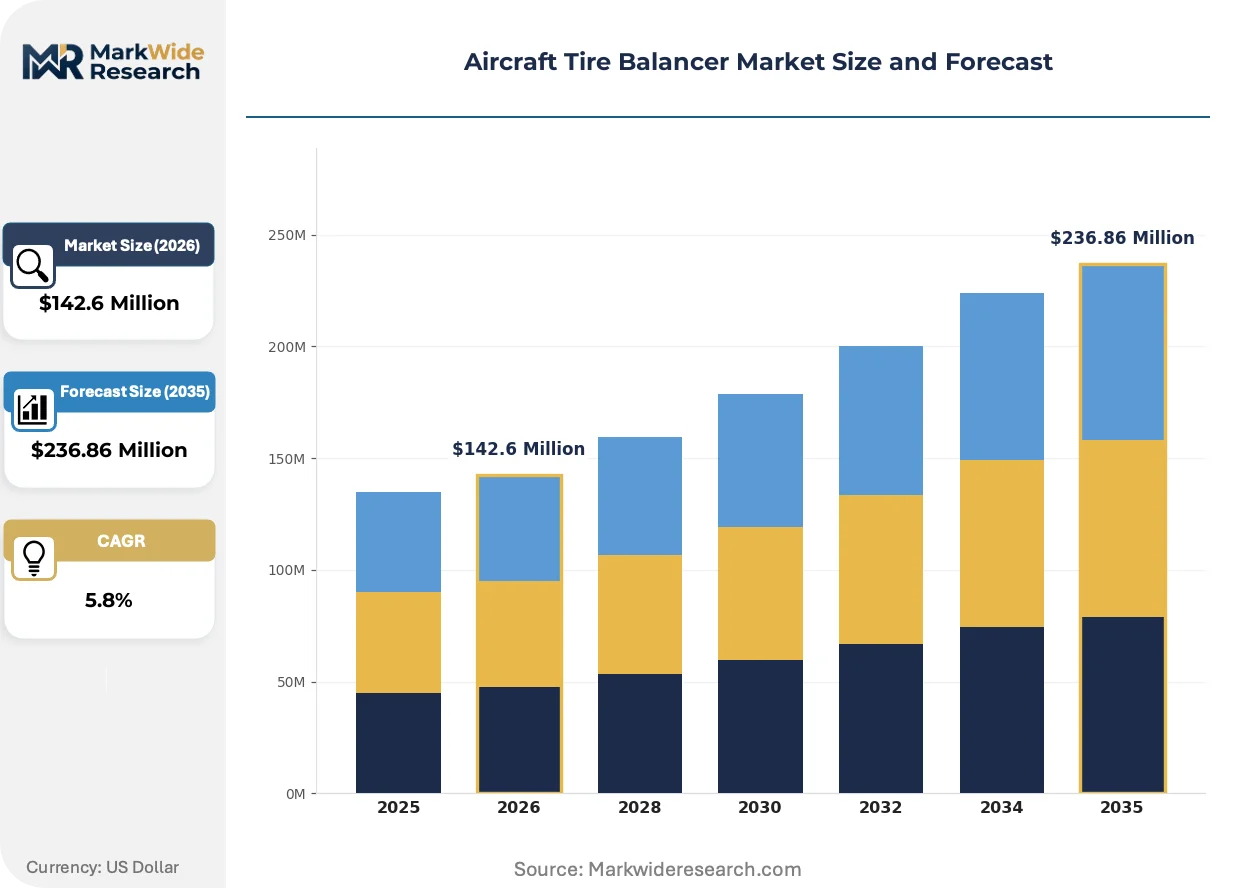
Fleet renewal cycles and regulatory tightening on tire vibration limits are compressing maintenance intervals and forcing precision balancing equipment upgrades at commercial and defense facilities.
Growth Catalysts
- 14 CFR Part 43 Standards:FAA maintenance rules mandate periodic tire balance verification, creating recurring demand for certified balancing systems at Part 145 repair stations.
- Electromechanical Sensor Arrays:Dynamic balancer architectures now integrate multi-axis load cells and piezoelectric transducers, enabling real-time imbalance detection during high-speed wheel rotation.
- Defense Contractor Adoption:Military airworthiness documentation requirements are accelerating automated data logging capabilities for audit trail compliance in rotorcraft and fixed-wing tire maintenance.
Market Restraints
- Specialized Alloy Input Costs:Precision spindle assemblies and vibration-isolation bases rely on aerospace-grade aluminum and tungsten alloys subject to commodity price volatility.
- Calibration Equipment Concentration:Primary suppliers of NIST-traceable calibration masses and certification services cluster in Germany and the United States, creating geographic supply risk.
- Technical Throughput Limitations:Static balancer designs face displacement pressure from dynamic systems capable of simultaneous dual-plane correction, constraining static product lifecycle extension.
Strategic Opportunities
- Regional Airfield Infrastructure Gaps:Portable balancer penetration remains underdeveloped across secondary airfields in Brazil and Southeast Asia, where hangar space constraints favor mobile equipment.
- Aqueous Cleaning System Convergence:EPA solvent regulations are driving integration between balancer maintenance cycles and closed-loop aqueous cleaning technologies, creating bundled equipment sales potential.
- AS9100 Certification Pathways:Quality certification gaps among smaller maintenance providers create advisory service revenue streams for tier-one balancer manufacturers seeking channel expansion.
Industry Challenges
- Metrology Technician Scarcity:Precision balancing equipment operation requires specialized training in vibration analysis and rotational dynamics, with qualified personnel concentrated at major maintenance hubs.
- Dual Certification Timelines:Simultaneous FAA and EASA field approval processes for new balancer installations extend deployment cycles by six to twelve months at multinational airline operators.
- Legacy System Integration Friction:Digital balancer data outputs must interface with existing maintenance information systems, requiring custom middleware development at facilities running 1990s-era software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Tire Balancer Market |
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $236.86 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Balancer, Dynamic Balancer, Portable Balancer, Computerized Balancer, Manual Balancer Technology: Mechanical, Hydraulic, Pneumatic, Electromechanical, Digital Application: Commercial Aircraft Maintenance, Cargo Aircraft Servicing, Military Aircraft Overhaul, Business Jets Tires, Regional Aircraft Repair End User: Aircraft Maintenance Centers, Airlines, Defense Contractors, General Aviation Operators, Lease Companies |
| Companies Covered | McFarlane, Tronair, Goodyear, Michelin, Dunlop, Cessna Aircraft, Piper Aircraft, Cleveland, Aero-Classics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Tire Balancer Market Trends and Innovations
Sensor miniaturization and cloud-connected diagnostics are redistributing balancing capabilities from centralized maintenance hangars toward distributed operational environments.
Wireless vibration telemetry is decentralizing condition monitoring across commercial fleets. Piezoelectric accelerometers now transmit imbalance signatures via low-power wide-area networks, enabling tire health tracking without physical balancer docking. Regional carriers with dispersed route structures are piloting this architecture to reduce AOG incidents at outstations lacking full maintenance infrastructure.
EASA Part-145 framework revisions are tightening documentation granularity for tire maintenance events. Approved organizations must now retain digital imbalance readings with timestamps and technician identifiers for audit retrieval. German and French maintenance hubs are retrofitting existing balancers with data logging modules to preempt compliance gaps during surveillance audits.
Maintenance contract unbundling is fragmenting balancer procurement authority. Airlines increasingly separate tire service agreements from airframe maintenance, pushing balancing equipment decisions toward specialized wheel and brake shops. This pattern concentrates visible in the United States, where independent MRO providers now specify balancer configurations previously dictated by carrier engineering departments.
Aircraft Tire Balancer Market Segmentation
Precision balancing equipment segments diverge sharply by technical capability and regulatory compliance burden. Fleet operators select balancer architectures based on throughput requirements, hangar infrastructure, and airworthiness documentation obligations.
Product Type:
Electromechanical sophistication and correction precision define the product hierarchy across maintenance environments.
- Static Balancer:Single-plane correction devices measure imbalance at rest using gravity-based pendulum systems. Demand concentrates among general aviation operators in the United States where Part 43 compliance for light aircraft permits simpler verification protocols. Budget constraints and limited wheel assembly complexity favor these systems at rural repair stations.
- Dynamic Balancer:High-speed rotation platforms with multi-axis load cells detect dual-plane imbalance during simulated operational conditions. Commercial aircraft maintenance centers in Germany specify these systems to meet EASA Part-145 vibration documentation requirements for narrow-body and wide-body fleets. Real-time correction algorithms reduce tire mounting cycles by 40% versus static alternatives.
- Portable Balancer:Battery-powered units with wireless sensor arrays enable field balancing at remote airfields lacking fixed infrastructure. Southeast Asian regional carriers deploy these for AOG response at secondary airports.
- Computerized Balancer:Integrated software platforms automate imbalance calculation, correction weight placement, and digital record retention. Defense contractors in the United States prioritize these for military airworthiness audit trails.
- Manual Balancer:Technician-operated mechanical fixtures with graduated bubble indicators serve legacy aircraft populations. Limited procurement persists at heritage aviation museums and vintage aircraft restoration facilities.
Dynamic Balancer leads on scale; Portable Balancer leads on momentum.
Technology:
Actuation mechanisms determine accuracy thresholds, maintenance intervals, and capital recovery timelines.
- Electromechanical:Servo-driven spindle assemblies with piezoelectric transducers deliver 0.05 ounce-inch precision for commercial airline hubs. United States-based Part 145 stations favor these for high-volume tire rotation programs. Sensor drift requires annual NIST-traceable recalibration.
- Digital:FPGA-based signal processing architectures with cloud-connected diagnostics enable predictive maintenance alerts. Chinese MRO facilities adopt these fastest to satisfy CAAC documentation digitization mandates.
- Mechanical:Spring and fulcrum assemblies without electronic components persist at budget-constrained general aviation operators. Calibration dependency on physical wear makes these unsuitable for precision commercial applications.
- Hydraulic:Fluid-pressure actuation systems provide vibration isolation for oversized cargo aircraft wheel assemblies. Specialized deployment at heavy-lift freighter maintenance bases.
- Pneumatic:Compressed-air spindle drives suit explosive-atmosphere environments where electrical spark risk is prohibited. Limited niche at military ammunition handling facilities.
Electromechanical dominates installed base; Digital climbs the fastest.
Application:
Operational tempo and regulatory scrutiny intensity shape equipment specification across aviation sectors.
- Commercial Aircraft Maintenance:High-cycle narrow-body and wide-body tire servicing at hub airports drives demand for automated dynamic systems. United States legacy carriers specify integrated balancer-wheel wash stations to compress turnaround times.
- Military Aircraft Overhaul:Rotorcraft and tactical fixed-wing programs require tamper-evident digital logging for airworthiness release. Defense contractors in Germany integrate balancers with maintenance information systems for Bundeswehr compliance.
- Cargo Aircraft Servicing:Heavy-lift freighter operations with oversized tires demand reinforced spindle capacity and extended bed configurations. DHL and FedEx hubs in the United States operate dedicated cargo balancer lines.
- Regional Aircraft Repair:Turboprop and regional jet operators with dispersed fleets favor portable or semi-portable systems. Brazilian regional airlines expand mobile balancing capabilities to Amazon basin outstations.
- Business Jets Tires:Low-volume, high-precision requirements at fixed-base operators favor computerized systems with rapid changeover between aircraft types. Teterboro and Van Nuys facilities lead North American deployment.
Commercial Aircraft Maintenance anchors volume; Military Aircraft Overhaul shows steepest expansion trajectory.
End User:
Procurement authority and technical staffing depth determine equipment sophistication and service contract structures.
- Aircraft Maintenance Centers:Independent MRO providers with multi-airline contracts consolidate balancer investments across bay configurations. Lufthansa Technik and ST Engineering facilities specify enterprise-grade dynamic platforms.
- Defense Contractors:Military-specified equipment with cybersecurity-hardened data architectures. Lockheed Martin and Airbus Defence integrate balancers within classified maintenance networks.
- Airlines:In-house engineering departments at large carriers retain direct procurement authority for hub balancer fleets. Delta TechOps and Lufthansa Cargo operate captive balancing operations.
- General Aviation Operators:Owner-operators and flight schools with limited maintenance infrastructure select manual or basic static systems. United States Part 91 operations dominate this segment.
- Lease Companies:Asset managers specifying return-condition tire balance verification for off-lease aircraft. AerCap and GECAS require documented imbalance readings in redelivery protocols.
Aircraft Maintenance Centers command installed base; Defense Contractors drive specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing base commands higher balancer specification intensity than China's rapid fleet expansion programs, while the United States anchors commercial aviation maintenance volume.
United States
Legacy carrier fleet renewal and independent MRO consolidation drive dynamic balancer procurement at Delta TechOps and United TechOps facilities. FAA Part 145 repair stations enforce 14 CFR Part 43 tire balance verification mandates. Dallas-Fort Worth and Atlanta maintenance hubs concentrate electromechanical system deployments for narrow-body high-cycle operations.
Germany
Lufthansa Technik and ST Engineering facilities specify premium dynamic platforms for EASA Part-145 compliance. The country's national aviation regulator enforces stringent vibration documentation granularity for audit trail retention. Hamburg and Frankfurt maintenance clusters retrofit data logging modules to preempt surveillance audit gaps.
China
CAAC fleet expansion and MRO infrastructure buildout accelerate digital balancer adoption for documentation digitization mandates. The Civil Aviation Administration of China mandates enhanced maintenance record retention protocols. Shanghai and Beijing maintenance hubs integrate cloud-connected diagnostic architectures for predictive maintenance alerts.
Brazil
Regional carrier consolidation and Amazon basin route dispersion favor portable balancer penetration at secondary airfields. ANAC, the national civil aviation agency, aligns with international airworthiness standards for tire maintenance verification. São Paulo and Brasília repair stations expand mobile balancing capabilities for turboprop AOG response.
United Arab Emirates
Emirates and Etihad hub operations drive demand for high-throughput dynamic systems at Dubai and Abu Dhabi facilities. The General Civil Aviation Authority enforces maintenance standards harmonized with EASA frameworks. Dubai South and Al Ain maintenance zones concentrate computerized balancer installations for wide-body fleet servicing.
Aircraft Tire Balancer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base clusters around three strategic archetypes: tire manufacturers extending into balancing equipment, ground support equipment specialists, and dedicated precision instrument fabricators. Portfolio bundling and geographic channel expansion constitute the dominant competitive moves, with M&A activity concentrated in North American and European maintenance equipment portfolios.
Within the tire manufacturer tier, Goodyear and Michelin occupy positions exemplifying integrated tire-and-balancer bundling strategies at commercial airline hubs. Tronair anchors the ground support equipment archetype with portable system specialization. McFarlane represents the parts distribution channel archetype, leveraging established aviation supply networks for balancer consumable penetration across general aviation segments.
| Leading Market Players |
|---|
| McFarlane |
| Tronair |
| Goodyear |
| Michelin |
| Dunlop |
| Cessna Aircraft |
| Piper Aircraft |
| Cleveland |
| Aero-Classics |
| Others |
Pricing and Supply Chain Analysis
Electromechanical sensor miniaturization and FPGA-based signal processing migration simultaneously compress per-unit production costs and concentrate component sourcing among specialized semiconductor foundries in Germany and the United States. This technological shift redistributes margin capture from mechanical fabricators toward chip-integrated system suppliers while amplifying pricing leverage for NIST-traceable calibration service providers.
Pricing Analysis
Capacity additions in China's MRO infrastructure are reshaping price floors for digital balancer architectures while electromechanical systems retain premium positioning at EASA-regulated European hubs. Three-tier pricing structure across electromechanical premium, digital mid-market, and static economy levels segments buyer tiers by certification burden and throughput requirements. Cost compression in portable balancer categories is intensifying because battery and wireless module commoditization erodes hardware differentiation. General aviation operators in the United States exhibit highest price sensitivity due to Part 43 compliance flexibility, whereas defense contractors accept substantial premiums for AS9100-certified systems with tamper-evident audit trails.
Supply Chain Analysis
Precision spindle assemblies and vibration-isolation bases rest on aerospace-grade aluminum and tungsten alloy supply from Germany, the United States, and Japan. Piezoelectric transducers, FPGA processors, and NIST-traceable calibration masses constitute critical component dependencies. Single-source vulnerability concentrates in German and United States-based metrology certification services, creating geographic chokepoints for field recalibration compliance. Distribution runs through tier-one aviation parts distributors to Part 145 repair stations, with direct OEM relationships dominating defense contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft tire balancer margins are expanding through sensor-to-software value migration, where digital tier suppliers capture recurring diagnostic revenue streams unavailable to mechanical-only competitors.
For Market Incumbents: Cement aftermarket service lock-in by embedding predictive maintenance algorithms that require proprietary calibration protocols, blocking independent MRO providers from bypassing authorized service networks. Deepen backward integration into piezoelectric transducer supply through exclusive foundry partnerships in Germany, insulating against semiconductor allocation volatility that threatens dynamic balancer production schedules. For New Entrants and Emerging Players: Capture underserved portable balancer demand across Brazil's Amazon basin airfields and Southeast Asian secondary airports where hangar infrastructure constraints favor mobile equipment deployment. Target aqueous cleaning system bundling opportunities created by EPA solvent regulations, offering integrated balancer-maintenance station packages to regional repair stations seeking compliance simplification. For Investors and Strategic Acquirers: Valuations sit cheapest among manual and static balancer specialists serving general aviation segments, as digital tier multiples reflect software-recurring revenue premiums already. Long-term viability favors electromechanical-digital hybrid platforms capable of serving both commercial airline high-throughput requirements and defense contractor audit documentation mandates. Watch EASA Part-145 framework revision implementation timelines as the inflection signal for data logging module retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Supply | Secures piezoelectric component allocation from German foundries against semiconductor cycle volatility. |
| Aqueous Cleaning System Bundling | Captures EPA compliance-driven retrofit demand at United States Part 145 repair stations. |
| Cloud-Connected Diagnostic Platform Launch | Enables predictive maintenance revenue streams for Chinese MRO facilities under CAAC digitization mandates. |
| AS9100 Certification Pathway Investment | Unlocks defense contractor procurement channels requiring cybersecurity-hardened audit architectures. |
| Portable Balancer Geographic Expansion | Penetrates Brazil's regional carrier consolidation and Amazon basin route dispersion patterns. |
Research Methodology
Bottom-up MRO facility modeling reconciled against top-down balancer shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at Part 145 repair stations, procurement leads at airline engineering departments, defense contractor quality assurance managers, and aftermarket service heads at ground support equipment distributors combined with secondary validation from FAA airworthiness directive filings, EASA Part-145 organization registers, customs trade data for precision instrument imports, and SEC filings from diversified aviation equipment suppliers. This triangulation approach ensures demand-side installation data aligns with supply-side production volumes.
Input-output matrices map balancer procurement by product type, technology tier, application sector, and end-user category across the projection horizon. Segmentation dimensions modeled include electromechanical versus digital versus mechanical technology architectures, static versus dynamic versus portable product configurations, and commercial maintenance versus military overhaul versus general aviation application contexts. CAGRs derive from fitted growth curves applied to base-year installed base estimates, with fleet renewal cycle timing and regulatory compliance deadline clustering serving as aviation-specific demand drivers.
Regulatory implementation delays, alloy commodity price spikes, and metrology technician labor scarcity are the dominant revision risks to forecast assumptions. Forecasts reflect documented assumptions about EASA framework revision adherence timelines and CAAC digitization mandate enforcement intensity. A small set of named triggers—Part-145 audit granularity changes, EPA solvent ban expansion scope, and defense procurement cybersecurity specification updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market