
 Military Aircraft Maintenance, Repair and Overhaul Market | 2026-2036
Military Aircraft Maintenance, Repair and Overhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Maintenance, Repair and Overhaul Market Insights
FAA repair station certification reciprocity with EASA is decoupling small MRO providers from legacy airworthiness frameworks, raising compliance costs for independent shops while favoring primes with transatlantic regulatory depth. Lockheed Martin Corporation leverages its vertically integrated sustainment architecture across F-35 global fleets. Boeing dominates heavy airframe overhaul through organic depot partnerships with US Air Force Material Command. ST Engineering Aerospace anchors rotary-wing MRO capacity across Southeast Asian military operators with specialized helicopter blade repair capabilities.
Military aircraft maintenance, repair and overhaul encompasses the technical preservation, defect rectification, and life-extension of tactical and strategic air platforms through scheduled inspections, component replacement, and structural fatigue remediation, typically governed by Technical Order intervals and Mean Time Between Failure metrics. Engine Overhaul captures the largest value pool given turbine hot-section replacement cycles and performance restoration demands for turbofan powerplants. Unmanned Aerial Vehicles represent the fastest-expanding application segment as attrition-tolerant drone fleets require modular, rapid-turnaround repair protocols distinct from manned-aircraft depot schedules. Third-Party Outsourcing is gaining share among budget-constrained air forces seeking to preserve uniformed technical manpower for operational missions rather than base-level maintenance.
US Air Force Instruction 21-101 governs on-base maintenance workflows, while EASA Part 145 military exemptions shape European sovereign fleet sustainment standards, and Australia's Defence Aviation Safety Regulation mandates independent military airworthiness oversight distinct from civil frameworks. These regulatory architectures determine which providers qualify for depot-level contracts and what technical data rights must transfer with platform sales. Stakeholders must monitor how classified sustainment data restrictions affect cross-border MRO subcontracting as allied nations deepen interoperability commitments.
Market Dynamics
Condition-Based Maintenance Plus mandates from the US Department of Defense are compressing inspection cycles across fourth- and fifth-generation fighter platforms, forcing depot infrastructure to retool for sensor-driven predictive workflows rather than calendar-based overhauls.
Growth Catalysts
- CBM+ Policy Mandate:The US Department of Defense's Condition-Based Maintenance Plus directive requires sensor integration across tactical airframes, creating standardized demand for predictive analytics infrastructure and automated diagnostic tooling.
- UAV Fleet Proliferation:Attrition-tolerant unmanned aerial vehicle fleets require modular, rapid-turnaround repair protocols that bypass traditional heavy depot schedules, opening dedicated MRO capacity for high-velocity drone sustainment.
- Hot-Section Replacement Cycles:Turbofan powerplant performance restoration demands drive recurring engine overhaul revenue, with turbine blade and combustor replacement intervals generating predictable depot-level workload.
Market Restraints
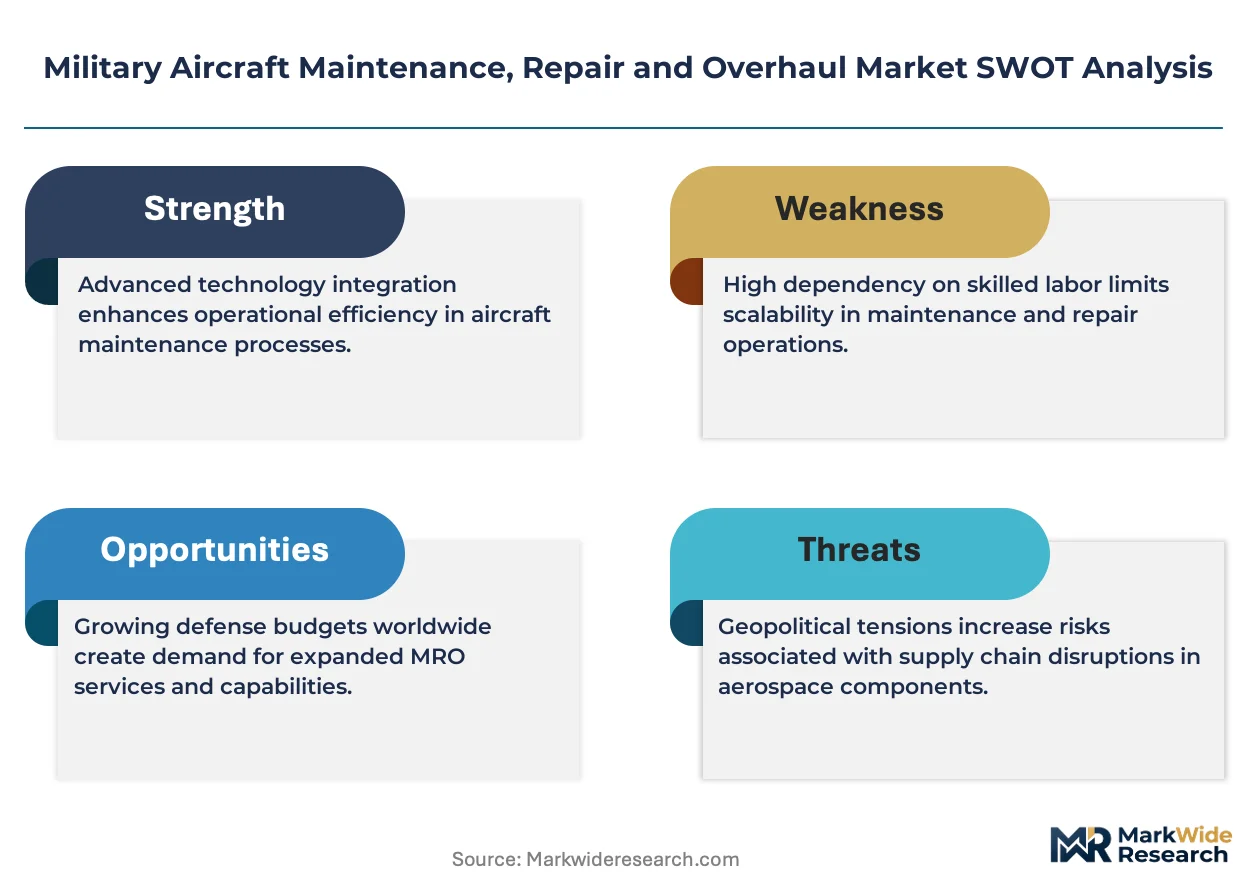
- Technical Data Rights Restrictions:Classified sustainment documentation limitations prevent cross-border subcontracting for allied nations, fragmenting MRO capacity along national security boundaries and duplicating fixed costs.
- Specialized Labor Scarcity:Airframe and powerplant certificated mechanics with security clearances concentrate at US Air Force Material Command depots, constraining surge capacity during contingency operations.
- Titanium and Superalloy Input Volatility:Turbine disk and structural component fabrication depends on nickel-based superalloy and titanium sponge supply chains vulnerable to export control disruptions and primary metal price swings.
Strategic Opportunities
- Southeast Asian Rotary-Wing Expansion:Military helicopter operators in Thailand, Indonesia, and Vietnam lack indigenous blade repair capabilities, creating demand for specialized composite rotorcraft MRO facilities with regional hub positioning.
- Digital Twin Convergence:Integration of physics-based degradation modeling with live sensor streams enables pre-positioned component staging and condition-based inventory, compressing turnaround times for critical subsystems.
- Third-Party Outsourcing Tailwinds:Budget-constrained NATO air forces are preserving uniformed technical manpower for operational missions, transferring base-level maintenance to civilian contractors under long-term availability contracts.
Industry Challenges
- Security-Cleared Workforce Pipeline:Depot-level facilities require mechanics with active clearance credentials, and the multi-year investigation timeline creates hiring friction that outpaces attrition from aging technical workforces.
- Legacy Platform Data Fragmentation:Cold War-era aircraft lack digital technical order systems and integrated health monitoring, forcing manual inspection protocols that resist automation and extend turnaround durations.
- EASA-US FAA Certification Reciprocity Gaps:Divergent military airworthiness exemptions between European and American frameworks force dual compliance investments for transatlantic MRO providers serving allied fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Maintenance, Repair and Overhaul Market |
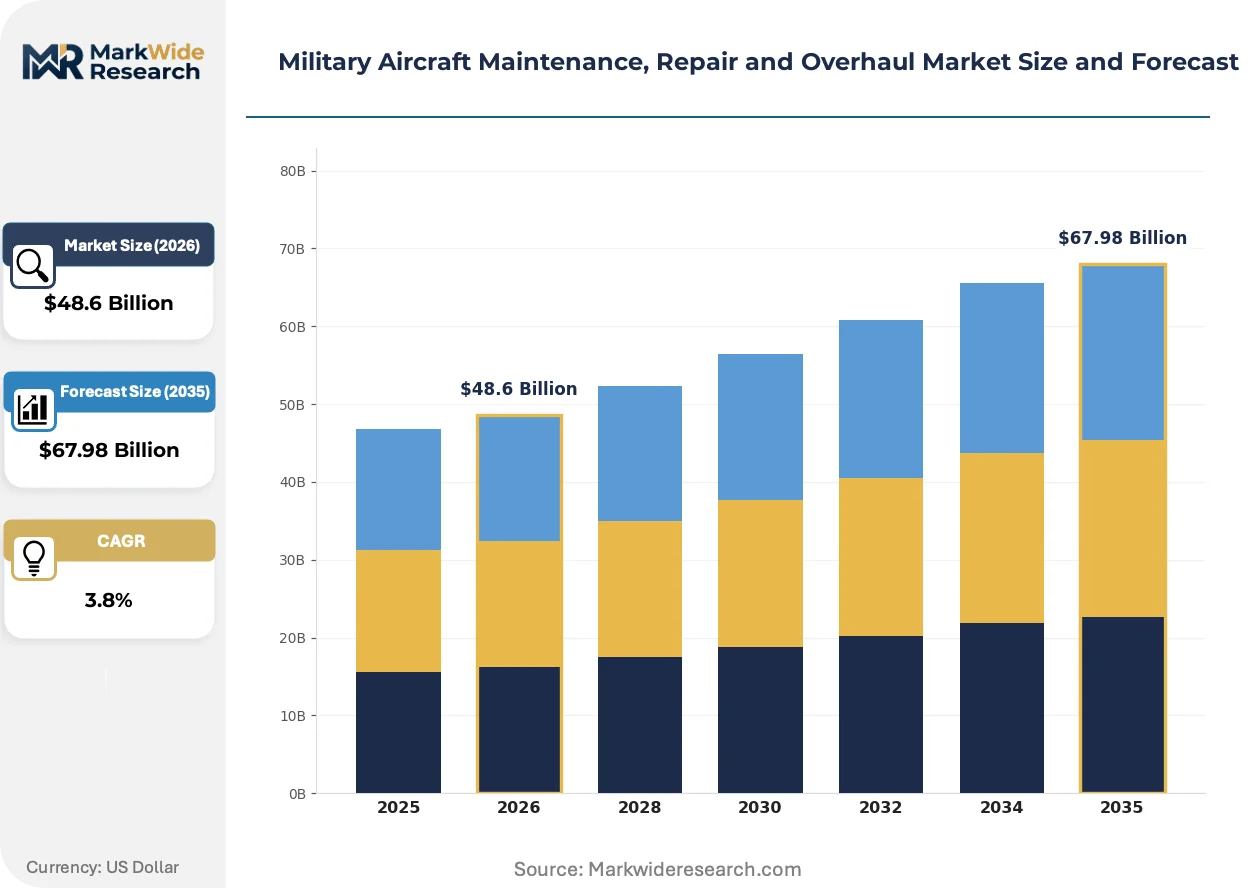
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $67.98 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engine Overhaul, Avionics Repair, Structural Maintenance, Component Refurbishment, Systems Integration Application: Fixed-Wing Fighters, Rotary-Wing Helicopters, Unmanned Aerial Vehicles, Transport Aircraft, Surveillance Planes End User: Air Force Squadrons, Naval Aviation Units, Defense Contractors, Government Repair Facilities, Private MRO Providers Deployment Model: On-Base Maintenance, Field-Level Repair, Depot-Level Overhaul, Mobile Repair Teams, Third-Party Outsourcing |
| Companies Covered | BAE Systems plc, Airbus SE, Lockheed Martin Corporation, AAR Corp, ST Engineering Aerospace, RTX Corporation, The Boeing Company, General Atomics, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Maintenance, Repair and Overhaul Market Trends and Innovations
Sensor integration and physics-based modeling are converging to displace scheduled maintenance intervals with condition-driven workflows, compressing aircraft availability cycles while redistributing technical labor from inspection to predictive intervention.
Digital twin architectures for turbine engine modules are absorbing real-time vibration, temperature, and oil debris data streams to forecast component degradation before threshold failures occur. US Air Force Material Command depots at Tinker and Warner Robins are deploying these systems across F-35 and C-17 powerplant fleets, collapsing unscheduled removal rates and enabling pre-positioned spare positioning that cuts mean-time-to-repair by eliminating diagnostic delays.
EASA Part 145 military exemptions are tightening documentation requirements for sovereign fleet sustainment across European Union member states, forcing independent MRO providers to upgrade quality management systems or exit defense subcontracting. The regulation is compressing vendor pools for national air forces in Germany, France, and Italy, concentrating depot-level contracts with primes possessing transatlantic regulatory depth and certified technical data repositories.
Availability-based contracting is displacing transactional labor-hour agreements for fighter and transport fleet sustainment, transferring operational risk from uniformed services to contractor balance sheets. Royal Air Force and Royal Australian Air Force procurement offices are leading this transition, with payment tied to aircraft-ready rates rather than discrete maintenance events, forcing MRO providers to invest in predictive tooling and integrated supply chains to manage cost volatility.
Military Aircraft Maintenance, Repair and Overhaul Market Segmentation
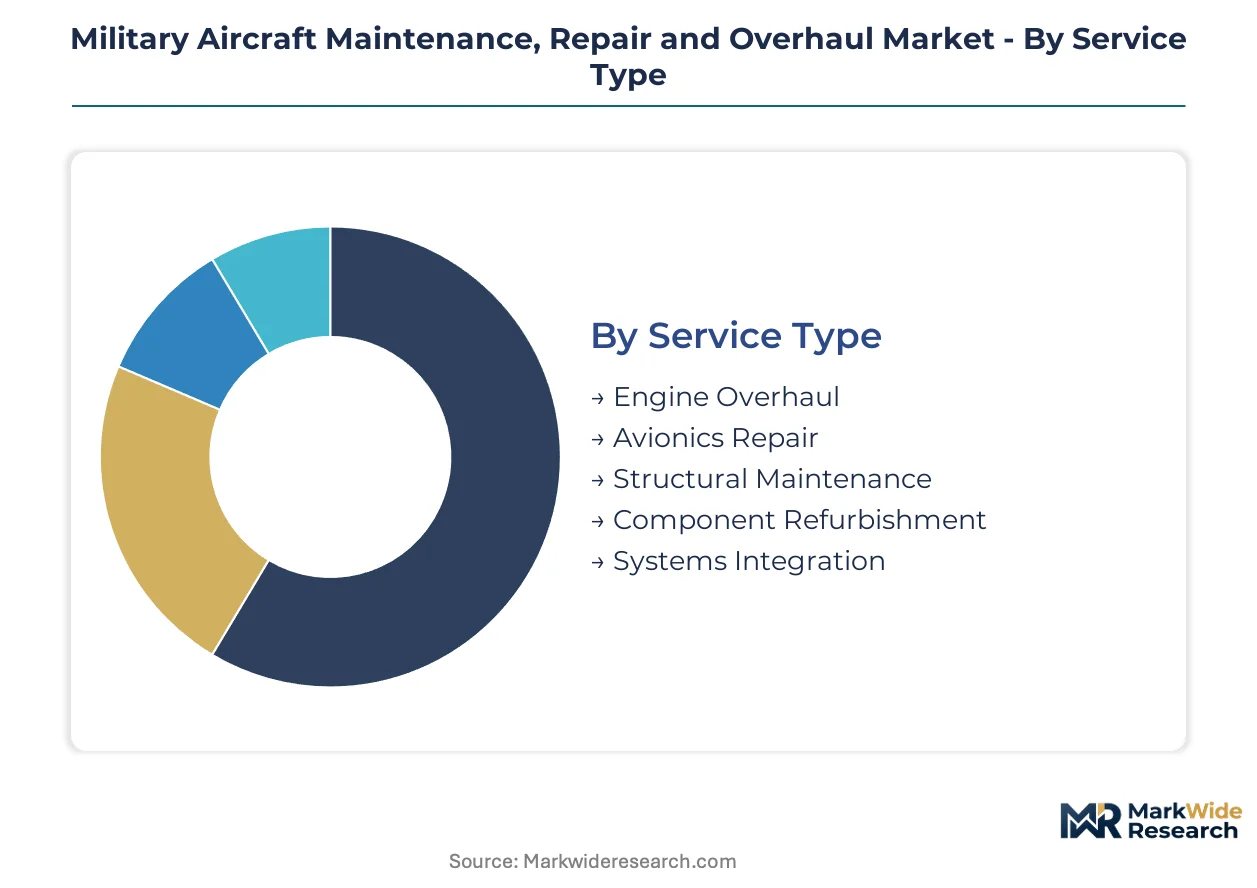
Military MRO segmentation reflects divergent technical workflows across airframe types, service depths, and custody arrangements. Each axis governs distinct certification requirements, labor skill profiles, and capital intensity thresholds that shape provider economics and competitive positioning.
Service Type:
Technical specification intensity determines margin structure and facility certification tiers across maintenance disciplines.
- Engine Overhaul:Turbofan hot-section restoration involves turbine blade replacement, combustor refurbishment, and performance testing to original equipment specifications. Demand concentrates at US Air Force Material Command depots and Lockheed Martin captive facilities, driven by recurring powerplant life-limiting component cycles and F-35 fleet expansion.
- Avionics Repair:Mission system restoration encompasses radar, electronic warfare, and communications module diagnostics and firmware reconfiguration. Royal Air Force and Royal Australian Air Force procurement offices are shifting toward availability-based contracts for these systems, transferring operational risk from uniformed services to contractor balance sheets.
- Structural Maintenance:Fatigue remediation and corrosion control for airframe primary structures.
- Component Refurbishment:Landing gear, actuators, and auxiliary power unit restoration to serviceable condition.
- Systems Integration:Software-defined mission system upgrades and interoperability modifications.
Engine Overhaul leads on scale; Avionics Repair leads on momentum.
Application:
Platform mission profiles dictate maintenance interval density and depot infrastructure requirements.
- Fixed-Wing Fighters:Fourth- and fifth-generation tactical aircraft require structural fatigue monitoring and stealth coating restoration. US Department of Defense Condition-Based Maintenance Plus mandates are compressing inspection cycles across these platforms, forcing depot retooling for sensor-driven predictive workflows.
- Unmanned Aerial Vehicles:Attrition-tolerant drone fleets demand modular, rapid-turnaround repair protocols that bypass traditional heavy depot schedules. Southeast Asian operators are establishing dedicated MRO capacity for high-velocity drone sustainment as surveillance and strike missions expand.
- Rotary-Wing Helicopters:Dynamic component replacement and rotor track-and-balance services.
- Transport Aircraft:High-cycle airframe and cargo system maintenance for strategic lift platforms.
- Surveillance Planes:Specialized sensor integration and mission system calibration for intelligence platforms.
Fixed-Wing Fighters dominate revenue concentration; Unmanned Aerial Vehicles exhibit the steepest expansion trajectory.
End User:
Custody arrangements determine technical data access rights and security clearance requirements for maintenance personnel.
- Air Force Squadrons:Organic base-level maintenance performed by uniformed technicians under Technical Order protocols. These units are preserving technical manpower for operational missions, transferring base-level workload to civilian contractors under long-term availability contracts.
- Defense Contractors:Lockheed Martin and Boeing sustainment divisions performing depot-level overhaul with proprietary technical data rights. EASA Part 145 military exemptions are tightening documentation requirements, compressing vendor pools and concentrating contracts with primes possessing transatlantic regulatory depth.
- Naval Aviation Units:Carrier-based aircraft maintenance with corrosion-intensive maritime environment protocols.
- Government Repair Facilities:Warner Robins and Tinker Air Force Base depots handling heavy maintenance for strategic fleets.
- Private MRO Providers:Independent shops facing rising compliance costs from FAA-EASA certification reciprocity gaps.
Defense Contractors command the largest contract values; Private MRO Providers face the most severe qualification barriers.
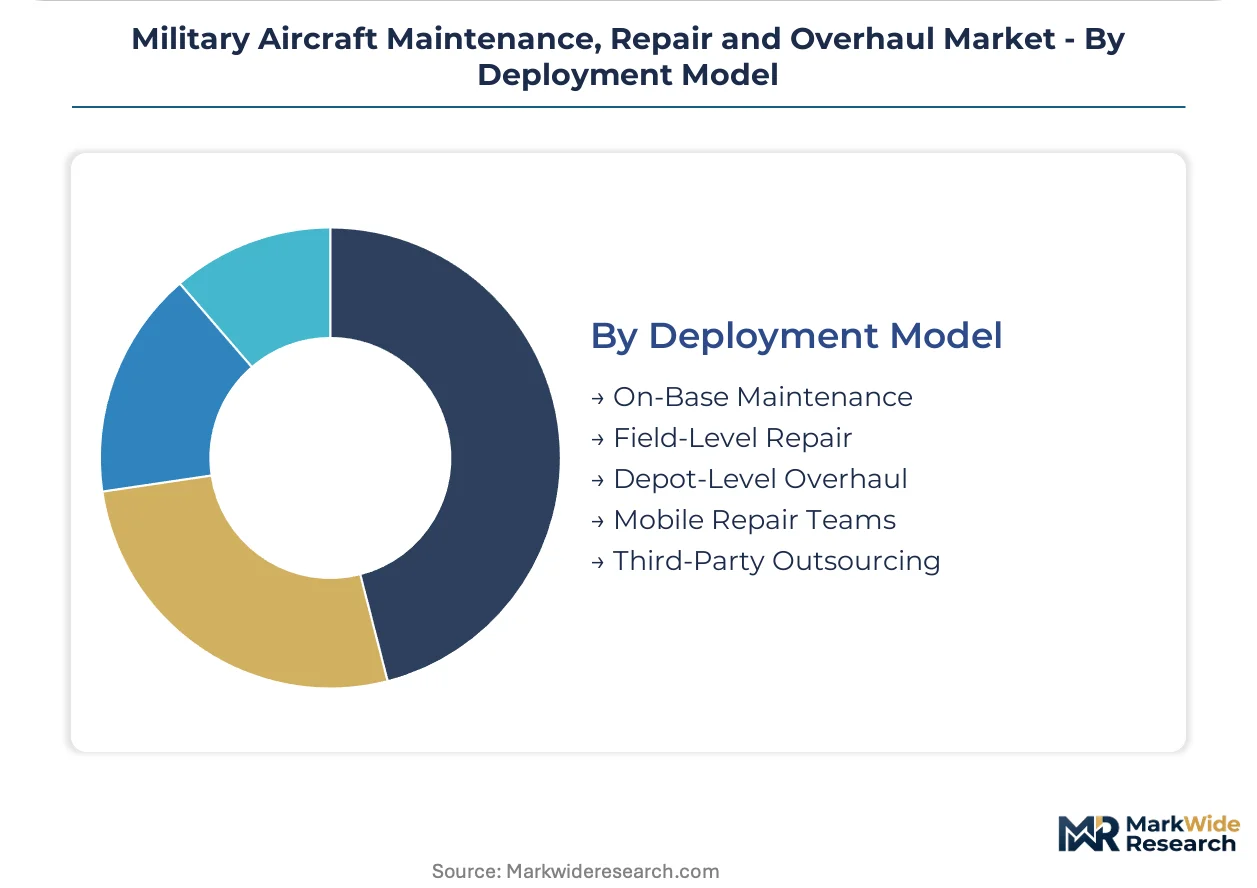
Deployment Model:
Facility mobility and custody location shape capital deployment and inventory positioning strategies.
- Depot-Level Overhaul:Heavy structural and powerplant restoration requiring specialized jigs, test cells, and bonded storage. Digital twin architectures for turbine engine modules are absorbing real-time data streams at Tinker and Warner Robins, collapsing unscheduled removal rates through pre-positioned spare positioning.
- Third-Party Outsourcing:Long-term availability contracts transferring operational risk to civilian balance sheets. Budget-constrained NATO air forces are accelerating this shift to preserve uniformed technical manpower for operational missions rather than base-level maintenance.
- On-Base Maintenance:Squadron-level servicing and flight line turnaround operations.
- Field-Level Repair:Contingency forward deployment maintenance with limited tooling.
- Mobile Repair Teams:Rapid response units for aircraft recovery and battle damage repair.
Depot-Level Overhaul absorbs the majority of capital investment; Third-Party Outsourcing is gaining share fastest among procurement reform initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified airframe mechanics with active security clearances concentrate disproportionately at US Air Force Material Command depots, creating regional talent asymmetries that shape where heavy overhaul capacity can expand.
United States
F-35 and C-17 fleet sustainment drives depot-level workload concentration at Warner Robins Air Logistics Complex in Georgia and Tinker Air Force Base in Oklahoma. US Department of Defense Condition-Based Maintenance Plus mandates accelerate sensor integration across tactical platforms, retooling infrastructure for predictive rather than calendar-based workflows. Tinker Air Force Base deploys digital twin architectures for turbine engine modules, collapsing unscheduled removal rates through real-time data absorption.
United Kingdom
Royal Air Force availability-based contracting shifts operational risk from uniformed services to contractor balance sheets, restructuring procurement toward aircraft-ready rate payments. Military airworthiness standards diverge from civil frameworks under sovereign oversight protocols, complicating transatlantic subcontracting arrangements. RAF procurement offices in High Wycombe and Bristol anchor this transition toward long-term sustainment partnerships.
Germany
EASA Part 145 military exemptions tighten documentation requirements for sovereign fleet sustainment, compressing vendor pools for national air force contracts. Luftwaffe base-level maintenance preservation priorities accelerate third-party outsourcing to civilian contractors. Industrial concentration clusters around Munich and Hamburg, where primes maintain certified technical data repositories for transatlantic regulatory compliance.
Australia
Defence Aviation Safety Regulation mandates independent military airworthiness oversight distinct from civil frameworks, creating specialized compliance requirements for domestic MRO providers. Royal Australian Air Force availability-based contracting mirrors UK procurement reform, transferring operational risk to contractor balance sheets. RAAF facilities at Amberley and Williamstown anchor regional heavy maintenance capacity for F/A-18 and F-35 fleets.
Singapore
ST Engineering Aerospace anchors rotary-wing MRO capacity across Southeast Asian military operators with specialized helicopter blade repair capabilities. Regional hub positioning captures demand from Thailand, Indonesia, and Vietnam operators lacking indigenous composite rotorcraft maintenance infrastructure. Seletar Aerospace Park concentrates specialized tooling and cleared technical personnel for regional defense subcontracting.
Military Aircraft Maintenance, Repair and Overhaul Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers, creating a bifurcated structure where scale-driven primes capture depot-level overhaul contracts while regional specialists dominate niche component disciplines. Market concentration favors entities with transatlantic regulatory depth and proprietary technical data rights. Three archetypes predominate: vertically integrated defense primes with captive sustainment divisions, government-owned depot facilities with uniformed-civilian hybrid workforces, and independent MRO providers facing rising compliance barriers. Competitive dynamics center on strategic partnerships for sensor integration and geographic expansion into under-served rotary-wing markets.
Among defense prime contractors, Lockheed Martin Corporation, The Boeing Company, and BAE Systems plc exemplify distinct strategic positioning within the sustainment ecosystem. Lockheed Martin occupies a position centered on vertically integrated F-35 global fleet architecture. The Boeing Company anchors heavy airframe overhaul capacity through organic depot partnerships. BAE Systems plc represents European-based regulatory depth for EASA-compliant sovereign fleet contracts.
| Leading Market Players |
|---|
| BAE Systems plc |
| Airbus SE |
| Lockheed Martin Corporation |
| AAR Corp |
| ST Engineering Aerospace |
| RTX Corporation |
| The Boeing Company |
| General Atomics |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
Security-cleared airframe mechanics concentrated at US Air Force Material Command depots in Georgia and Oklahoma create labor-cost asymmetries that widen pricing spreads between prime contractor depot services and independent MRO shops. These clearance-holding technical workforces command premium compensation that feeds into tiered service rate structures across the military aviation sustainment ecosystem.
Pricing Analysis
Bundled availability-based contracts are displacing unbundled labor-hour transactional agreements across NATO air forces, with Royal Air Force and Royal Australian Air Force procurement offices leading the shift toward aircraft-ready rate payments. Price differentiation hinges on security clearance depth and proprietary technical data access rights, with cleared personnel services commanding substantial premiums over uncertified alternatives. Pricing pressure stems from budget-constrained allied nations seeking to transfer operational risk to contractor balance sheets. National air forces with organic depot capacity exhibit lowest price sensitivity, while smaller Southeast Asian operators demonstrate highest sensitivity to per-flight-hour sustainment costs.
Supply Chain Analysis
Freight costs for turbine disk and hot-section component shipments from specialized US and European foundries to depot facilities at Tinker and Warner Robins compress margins on urgent engine overhaul orders. Supply concentration centers on nickel-based superalloy production in the United States, United Kingdom, and Germany, with titanium sponge processing anchored in US and Japanese facilities. Raw material dependencies include cobalt-chromium alloys, ceramic thermal barrier coatings, and precision-forged turbine blades. Single-source vulnerability for classified-grade superalloy specifications poses structural risk. Distribution runs through defense prime captive networks and government-owned depot storage systems with bonded security protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance platform deployment that collapses unscheduled removal rates and shifts revenue toward higher-margin sensor analytics services.
For Market Incumbents: Cement depot-level positioning through exclusive technical data rights negotiations with F-35 program offices, while accelerating sensor integration investments to capture Condition-Based Maintenance Plus mandate flows. Threat of emerging drone-focused MRO specialists with modular rapid-turnaround protocols demands defensive capability building in unmanned aerial vehicle sustainment. Vertical integration into nickel-based superalloy sourcing hedges against titanium and superalloy input volatility. For New Entrants and Emerging Players: EASA Part 145 military exemptions in Germany and France open a window for specialized helicopter blade repair facilities serving Southeast Asian operators lacking indigenous composite rotorcraft capabilities. White-space targets include Thailand, Indonesia, and Vietnam military helicopter fleets and attrition-tolerant drone rapid-turnaround protocols. Go-to-market through regional hub partnerships with ST Engineering Aerospace at Seletar Aerospace Park offers lowest barrier to cleared technical personnel access. For Investors and Strategic Acquirers: Defense prime sustainment divisions are the most active acquirer in this space, seeking predictive analytics and digital twin capabilities to bolster availability-based contract performance. Long-term viability favors providers with transatlantic regulatory depth and proprietary technical data repositories. Acquisition target archetype: regional rotary-wing specialists with EASA-certified composite repair capabilities. Signal to watch: Royal Air Force and Royal Australian Air Force procurement office contract award velocity for long-term availability partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Tinker Air Force Base absorbs real-time engine data to collapse unscheduled removal rates. |
| EASA Certification Investment | Luftwaffe vendor pool compression forces quality management system upgrades for defense subcontracting access. |
| Southeast Asian Hub Establishment | Seletar Aerospace Park positioning captures Thai, Indonesian, and Vietnamese helicopter blade repair demand. |
| Availability-Based Contract Transition | RAF procurement shifts operational risk to contractor balance sheets through aircraft-ready rate structures. |
| Security-Cleared Workforce Pipeline | Warner Robins and Tinker facilities require multi-year investigation timelines that outpace technical workforce attrition. |
Research Methodology
Coverage spans the United States, United Kingdom, Germany, Australia, and Singapore, with primary inputs from each market cluster through structured interviews with depot operations directors, defense procurement officers, airworthiness regulation specialists, and prime contractor sustainment executives. Secondary validation draws from US Air Force Instruction 21-101 documentation, EASA Part 145 military exemption filings, Australia's Defence Aviation Safety Regulation guidance, and Department of Defense Condition-Based Maintenance Plus policy directives. Bottom-up fleet sustainment demand modeling triangulates against top-down defense budget allocation analysis.
Rate-of-change decomposition separates fleet age profile effects from policy mandate acceleration and platform mix shifts across the projection horizon. Segmentation dimensions include service type, application platform category, end-user custody arrangement, and deployment model mobility tier. CAGRs derive from fitted trend analysis of historical contract award values and projected fleet expansion schedules. Industry-specific forecast inputs incorporate F-35 fleet delivery timelines and UAV attrition replacement rates.
Revisions become necessary when classified sustainment data restrictions tighten cross-border subcontracting protocols, superalloy supply chains face export control disruptions, or allied nations accelerate third-party outsourcing beyond modeled penetration rates. Forecasts reflect documented assumptions about security clearance processing timelines and technical data rights transfer negotiations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market