
 Europe Aircraft Engine MRO Market | 2026-2036
Europe Aircraft Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Engine MRO Market Foresight
EU Green Deal compliance is shifting the cost-of-entry calculus for independent MRO shops across Europe. Lufthansa Technik leverages its Hamburg headquarters to sustain integrated engine-to-wing service bundles. Rolls-Royce anchors Derby as a global center for widebody engine overhauls. MTU Aero Engines competes through specialized high-pressure turbine module repairs at its Munich facility.
Europe Aircraft Engine MRO encompasses the technical servicing, restoration, and life-extension of aviation propulsion systems, including hot-section component refurbishment, borescope inspection protocols, and thrust-specific performance restoration to airworthiness standards. The primary purpose is to return engines to certified operational parameters while managing total cost of ownership for fleet operators. Turbofan overhaul generates the dominant revenue pool given narrowbody fleet density across European low-cost carriers, while predictive maintenance technology represents the fastest-expanding segment as airlines deploy real-time engine health monitoring to reduce unscheduled shop visits. Additive manufacturing for turbine blade repair is emerging as a margin concentration point for specialized providers.
EASA mandates, REACH chemical handling protocols, and the EU F-Gas Regulation collectively shape material sourcing, test cell emissions, and refrigerant use in European MRO facilities. The EU AI Act introduces forthcoming compliance layers for automated inspection algorithms deployed in digital engine monitoring systems. Stakeholders must weigh capital allocation between legacy turbofan overhaul capacity and predictive maintenance platform development as fleet renewal timelines accelerate.
Market Dynamics
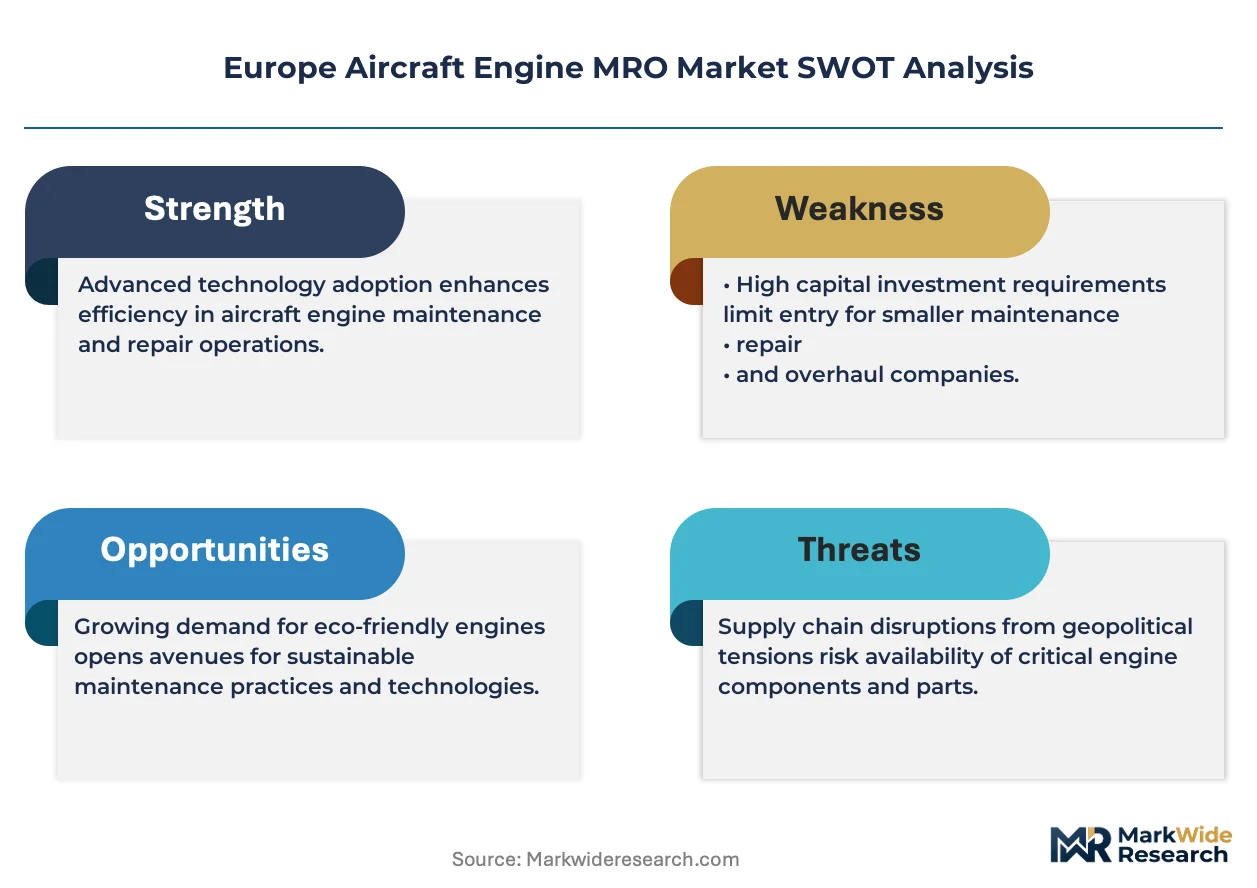
EASA's tightening emissions certification standards are forcing MRO providers to rebuild test cell infrastructure around cleaner combustion protocols, compressing margins for independent shops while advantaging integrated operators with captive capital.
Growth Catalysts
- EU Green Deal compliance mandates:The EU F-Gas Regulation and REACH chemical handling protocols are accelerating facility upgrades that extend engine service life through cleaner refurbishment processes.
- Predictive maintenance platforms:Real-time engine health monitoring is electrifying fleet management economics by reducing unscheduled shop visits and optimizing overhaul timing for narrowbody operators.
- Eastern European low-cost carrier expansion:Ryanair, Wizz Air, and their competitors are extending engine overhaul contracts to manage aging Airbus A320 and Boeing 737 fleets.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloy sourcing for turbine blade refurbishment remains concentrated among a handful of European and North American metallurgical suppliers.
- Test cell capex intensity:EASA-compliant emissions-capable test infrastructure requires eight-figure capital commitments that independent MRO shops struggle to finance.
- Additive manufacturing qualification timelines:Powder bed fusion repair processes for high-pressure turbine components face extended airworthiness certification cycles under current regulatory frameworks.
Strategic Opportunities
- Poland and Romania MRO capacity gaps:These Eastern European markets lack indigenous widebody engine overhaul capability, creating white space for module repair specialists.
- EU AI Act automated inspection pathways:The forthcoming regulatory framework for algorithmic borescope analysis creates first-mover advantages for digital-native MRO platforms.
- Convergence of additive manufacturing and robotics:Automated directed energy deposition for blade tip restoration is compressing turnaround times for hot-section repairs.
Industry Challenges
- Certified non-destructive testing technician scarcity:EASA Part-66 licensed inspectors with eddy current and ultrasonic expertise command premium wages that strain shop economics.
- Legacy engine-to-digital platform integration:CFM56 and V2500 powerplants lack native sensor architectures, forcing retrofit complexity for predictive maintenance deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Engine MRO Market |
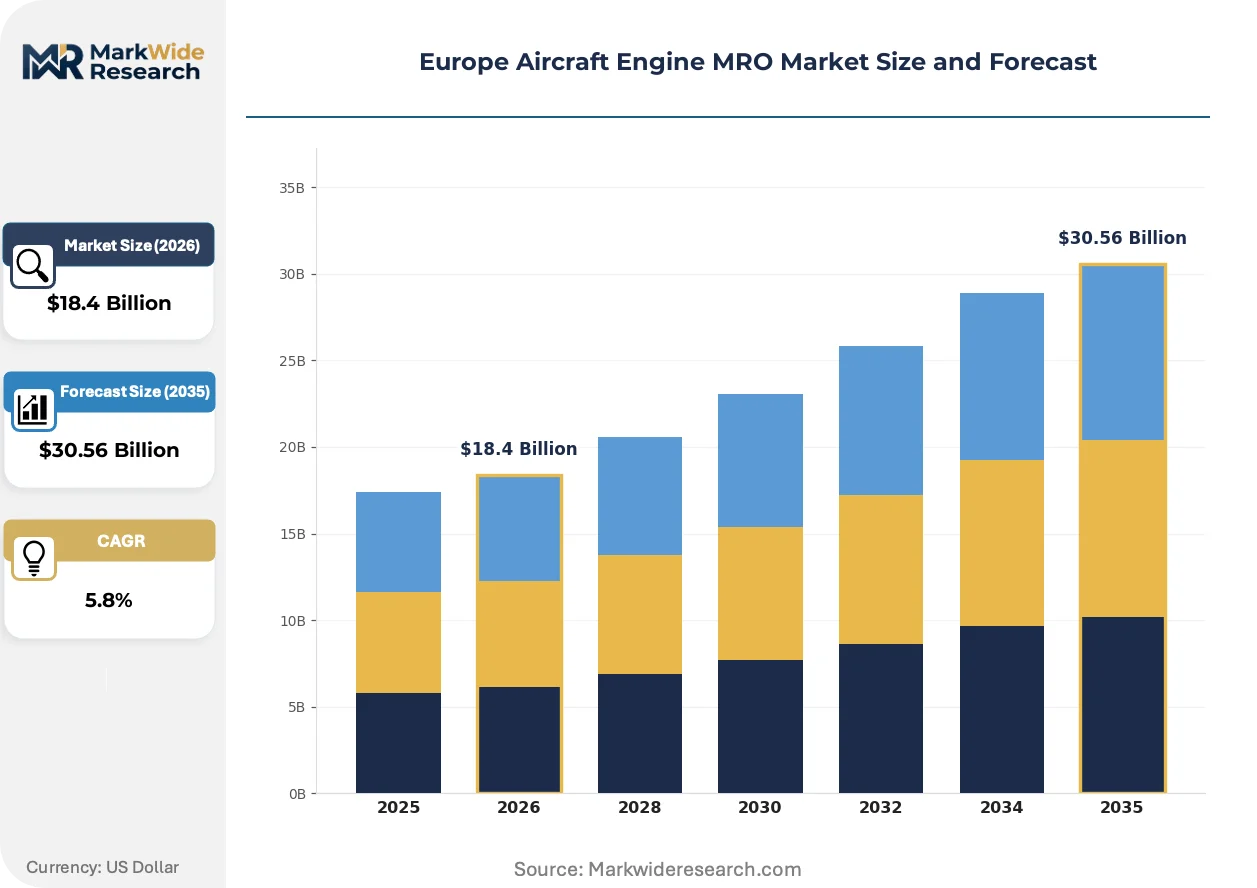
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Inspection Engine Type: Turbojet, Turbofan, Turboprop, Piston End User: Commercial Airlines, Cargo Operators, Military Operators, Private Aviation Technology: Digital Inspection, Engine Monitoring, Predictive Maintenance, Additive Manufacturing |
| Companies Covered | Lufthansa Technik, Rolls-Royce, Safran Aircraft Engines, MTU Aero Engines, Air France Industries KLM Engineering & Maintenance, GE Aerospace, Pratt & Whitney, SR Technics Switzerland, Airbus SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Engine MRO Market Shifts & Advancements
Digital thread technologies are rewiring how engine life-cycle data flows from wing to shop floor, compressing diagnostic cycles and enabling condition-based overhaul triggers rather than hour-based intervals.
Additive manufacturing for turbine blade repair is electrifying margin structures in specialized MRO niches. Directed energy deposition and cold spray metallization enable restoration of airfoil geometries previously requiring full replacement. Lufthansa Technik and MTU Aero Engines are scaling these capabilities at their Hamburg and Munich facilities respectively. The technology is compressing material costs and turnaround times for high-pressure compressor and turbine module overhauls.
REACH chemical handling protocols and the EU F-Gas Regulation are restructuring solvent-based cleaning and refrigerant use across European MRO facilities. EASA's alignment with these frameworks is forcing investment in aqueous cleaning systems and closed-loop refrigerant recovery. German and French overhaul centers face the steepest compliance curves given their legacy infrastructure density.
Power-by-the-hour contracting is displacing traditional time-and-material overhaul arrangements among European low-cost carriers. Airlines now bundle engine availability risk with MRO providers, transferring operational volatility in exchange for predictable unit economics. This shift concentrates most visibly at Ryanair's Dublin and Budapest operational bases where fleet scale enables such risk-transfer negotiations.
Europe Aircraft Engine MRO Market Segmentation
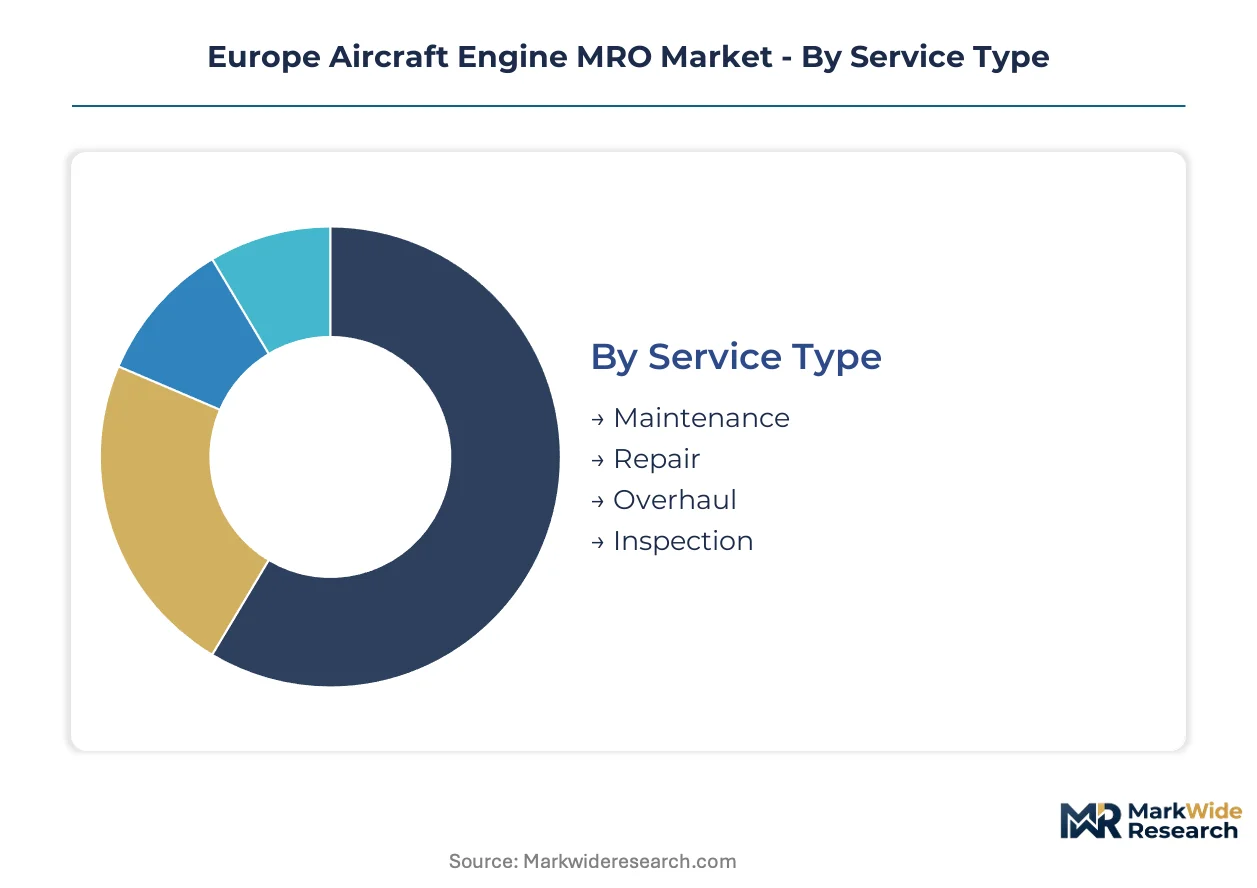
Engine MRO segmentation reveals how service intensity, propulsion architecture, and operator economics fragment procurement patterns across Europe. Each dimension exposes distinct margin structures and regulatory exposure that shape provider specialization strategies.
Service Type:
Customization intensity spans from standardized line maintenance to bespoke module rebuilds, with cost predictability inversely correlated with technical complexity.
- Maintenance:Routine servicing preserves airworthiness between scheduled shop visits through oil system checks, filter replacement, and minor component adjustments. European low-cost carriers concentrate demand in Germany and the UK as they maximize aircraft utilization rates.
- Overhaul:Comprehensive disassembly, inspection, and restoration of core modules including high-pressure compressors and turbines to manufacturer specifications. Lufthansa Technik and MTU Aero Engines anchor this segment in Hamburg and Munich, capturing widebody engine contracts from network carriers.
- Repair:Corrective interventions address specific component failures or damage events without full module replacement.
- Inspection:Borescope and non-destructive testing protocols verify internal component condition against EASA Part-145 airworthiness standards.
Most installed capacity flows through Overhaul. Expansion is steepest in Inspection as digital borescope automation reduces technician labor intensity.
Engine Type:
Volume concentration versus margin concentration splits sharply across thrust classes and thermal management architectures.
- Turbofan:High-bypass propulsion systems dominate European narrowbody and widebody fleets, generating the largest revenue pool through recurring shop visits. Eastern European low-cost carriers at Ryanair and Wizz Air bases drive demand concentration for CFM56 and V2500 overhauls.
- Turbojet:Lower-bypass military and business jet applications require specialized hot-section expertise with limited provider competition.
- Turboprop:Regional aircraft and cargo feeders sustain steady demand for gearbox and propeller control unit servicing.
- Piston:General aviation powerplants follow distinct Part-M light maintenance protocols with minimal module complexity.
Revenue gravity centers on Turbofan given fleet density. Turboprop is climbing the fastest as ATR freighter conversions expand across Central European cargo networks.
End User:
Contract structure and risk allocation diverge between price-sensitive volume operators and mission-critical defense procurement.
- Commercial Airlines:Scheduled passenger carriers negotiate power-by-the-hour agreements that transfer availability risk to MRO providers. German and French flag carriers anchor demand for integrated engine-to-wing service bundles at Lufthansa Technik facilities.
- Cargo Operators:Express and general freight carriers prioritize turnaround speed over unit cost given night-hub operational constraints.
- Military Operators:National air forces require security-cleared facilities and sovereign capability preservation with limited commercial crossover.
- Private Aviation:Business jet and helicopter owners favor time-and-material billing with premium scheduling flexibility.
Contract value concentrates in Commercial Airlines. Cargo Operators are gaining share fastest as e-commerce fulfillment networks expand dedicated freighter fleets.
Technology:
Capital intensity and qualification timelines separate mature process technologies from emerging digital and additive platforms.
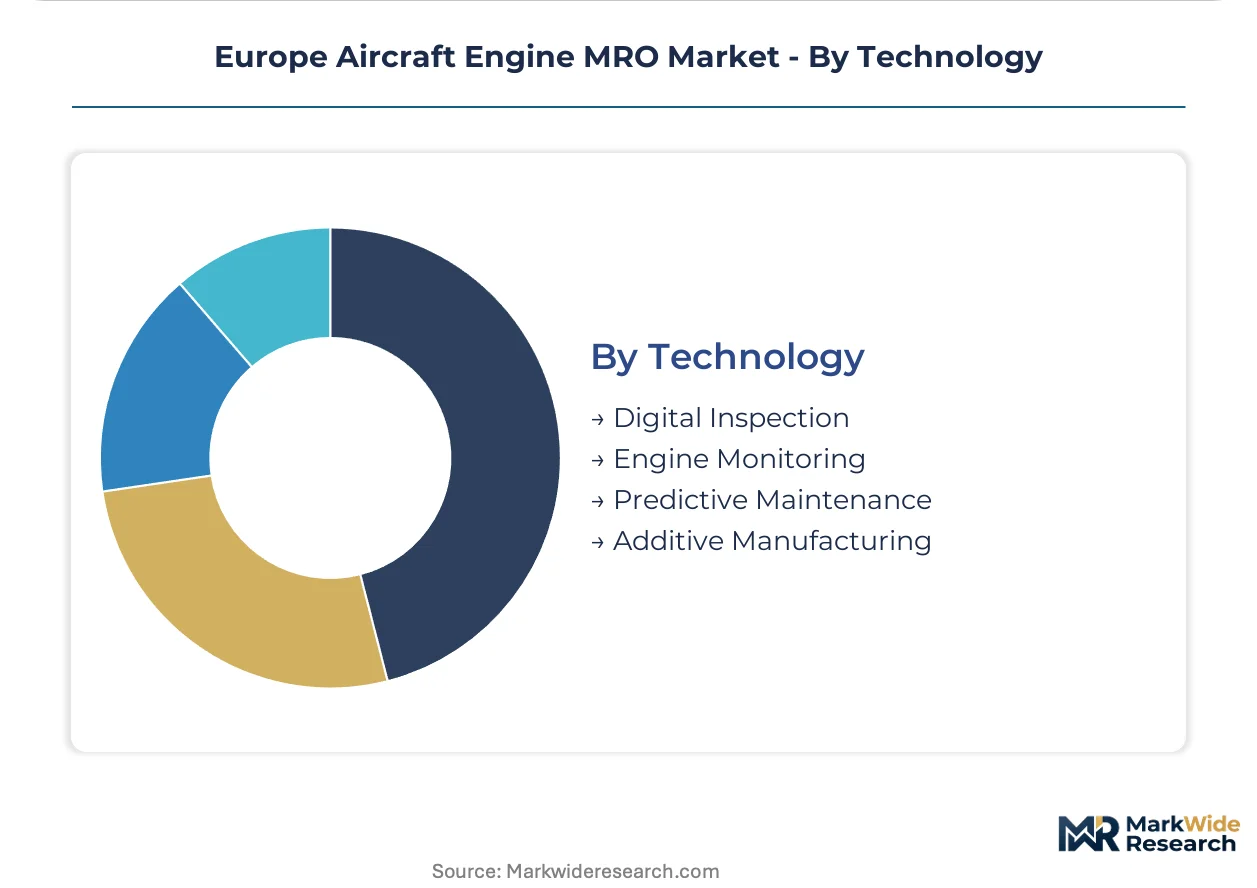
- Predictive Maintenance:Real-time engine health monitoring via airborne sensor telemetry reduces unscheduled shop visits and optimizes overhaul timing. Ryanair's operational scale at Dublin and Budapest enables full platform deployment across its aging narrowbody fleet.
- Additive Manufacturing:Directed energy deposition and cold spray metallization restore turbine blade geometries previously requiring full replacement. MTU Aero Engines scales these capabilities at Munich for high-pressure compressor module repairs.
- Digital Inspection:Automated borescope image analysis accelerates fault detection with reduced Part-66 licensed technician dependency.
- Engine Monitoring:Flight data acquisition and ground-based trend analysis support condition-based maintenance triggers.
Platform investment concentrates in Predictive Maintenance. Additive Manufacturing shows the steepest capability expansion trajectory as EASA qualification pathways mature for powder bed fusion repairs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aircraft engine overhaul operations trace their European lineage to post-war industrial reconstruction in Germany and the UK, where state-backed aviation programs established the technical foundations for modern MRO infrastructure. These historical centers remain the continent's dominant overhaul hubs today.
Germany
Lufthansa Technik and MTU Aero Engines anchor the continent's largest engine overhaul capacity, serving narrowbody and widebody fleets across European network carriers. EASA Part-145 certification requirements and REACH chemical handling protocols govern facility operations in Hamburg and Munich. The Hamburg cluster sustains integrated engine-to-wing service bundles, while Munich specializes in high-pressure turbine module repairs through additive manufacturing scale-up.
United Kingdom
Rolls-Royce's Derby facility commands widebody engine overhaul volume for Trent powerplants deployed across British Airways and international flag carriers. The UK CAA maintains alignment with EASA emissions certification standards while preserving sovereign regulatory autonomy. Derby's industrial concentration reflects decades of state-supported aerospace manufacturing that transitioned into commercial MRO dominance.
France
Air France Industries KLM Engineering & Maintenance consolidates overhaul demand from the Air France-KLM group at Paris-Charles de Gaulle and Amsterdam Schiphol maintenance bases. ANSM oversight of workplace chemical exposure complements EU F-Gas Regulation compliance for test cell refrigerant management. The Paris basin cluster leverages proximity to Airbus final assembly lines for integrated supply chain coordination.
Poland
Eastern European low-cost carrier expansion at Warsaw Chopin and Kraków-Balice airports drives CFM56 and V2500 shop visit demand from Ryanair and Wizz Air bases. Polish aviation authorities implement EASA regulatory frameworks with localized Part-66 licensing requirements for non-destructive testing technicians. The Warsaw-Mazovia region lacks indigenous widebody engine capability, creating white space for module repair specialists.
Switzerland
SR Technics Switzerland maintains Zurich-based overhaul capacity serving business aviation and regional carrier segments with specialized hot-section expertise. Swissmedic-aligned occupational safety standards and cantonal environmental permits shape facility investment decisions. The Zurich industrial corridor concentrates precision machining capabilities for turbine blade refurbishment serving adjacent German and French markets.
Europe Aircraft Engine MRO Market Competitive Landscape
The competitive structure tilts toward integrated full-service providers with captive airline relationships and proprietary technology access. Tiered specialization separates global OEM-affiliated operations from independent module repair shops and niche component specialists. Two dominant archetypes prevail: vertically integrated airline MRO divisions with guaranteed feedstock, and technology-licensed independents competing on turnaround speed. Competitive moves concentrate on test cell capacity expansion and predictive maintenance platform partnerships.
Within the integrated full-service tier, Lufthansa Technik and Rolls-Royce exemplify divergent scale advantages. Lufthansa Technik occupies a position as the Hamburg-based airline-captive operator with diversified engine type coverage. Rolls-Royce represents the OEM-anchored archetype with proprietary access to Trent powerplant intellectual property. MTU Aero Engines sits within the technology-specialist segment, leveraging Munich-based capabilities in high-pressure compressor module repairs.
| Leading Market Players |
|---|
| Lufthansa Technik |
| Rolls-Royce |
| Safran Aircraft Engines |
| MTU Aero Engines |
| Air France Industries KLM Engineering & Maintenance |
| GE Aerospace |
| Pratt & Whitney |
| SR Technics Switzerland |
| Airbus SE |
| Others |
Supply & Pricing Matrix
European low-cost carrier fleet managers concentrate procurement leverage through power-by-the-hour contracts that transfer availability risk to MRO providers in exchange for predictable unit economics. This buyer concentration anchors pricing models around performance guarantees rather than transactional shop-visit rates, compressing margins for independent operators while advantaging integrated providers with captive overhaul capacity.
Pricing Analysis
Power-by-the-hour contracting dominates European engine MRO procurement, with pricing stratifying across premium, standard, and economy tiers based on EASA Part-145 certification scope and turnaround time guarantees. Price differentiation rests on test cell infrastructure tier and additive manufacturing capability for hot-section repairs. Cost compression in the independent shop segment is intensifying because EASA emissions-compliant test cell capex requirements favor integrated operators. Low-cost carriers exhibit highest price sensitivity through volume-aggregated negotiations, while business aviation operators accept premium scheduling flexibility.
Supply Chain Analysis
Dual-sourcing mandates from EASA and REACH compliance officers require European MRO facilities to qualify multiple superalloy suppliers for turbine blade refurbishment. Geographic supply concentration centers on Germany, the United Kingdom, and France for precision-machined compressor components and specialized coating chemistries. Raw material dependencies include nickel-based superalloys, ceramic thermal barrier coatings, and high-purity refrigerants for test cell operations. Single-source vulnerability persists in powder bed fusion feedstock for additive manufacturing repairs. Distribution runs through OEM-authorized service networks and independent Part-145 certified shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's aircraft engine MRO sector offers margin expansion through predictive maintenance platform deployment and additive manufacturing scale-up that reduces material costs for hot-section repairs. Premium-tier shifts toward integrated engine-to-wing service bundles reward providers with test cell infrastructure and digital health monitoring capabilities.
For Market Incumbents: Acquire automated borescope inspection capabilities and EASA-qualified additive manufacturing cells to defend against digital-native entrants and independent module specialists. Lufthansa Technik and MTU Aero Engines should deepen backward integration into powder bed fusion feedstock production to secure supply continuity. Certification investment in EU AI Act-compliant automated inspection algorithms represents critical defensive positioning. For New Entrants and Emerging Players: Launch via specialized high-pressure turbine module repair services targeting Poland and Romania, where widebody engine capability gaps persist among Eastern European low-cost carrier bases. White-space concentration sits in directed energy deposition blade restoration for aging CFM56 and V2500 fleets. Go-to-market traction flows through power-by-the-hour risk-sharing partnerships with Ryanair and Wizz Air operational hubs. For Investors and Strategic Acquirers: OEM-affiliated MRO divisions are the most active acquirer in this space, seeking technology-licensed independents with qualified additive manufacturing pathways. Long-term viability favors providers with predictive maintenance platform integration and EASA emissions-compliant test infrastructure. Acquisition target archetypes include specialized hot-section repair shops with Part-66 licensed technician benches. The signal to watch is EASA qualification timeline acceleration for powder bed fusion repairs as regulatory frameworks mature.| Strategic Initiative | Industry Significance |
|---|---|
| Test Cell Emissions Compliance Upgrade | EASA-aligned infrastructure investment secures overhaul certification for Trent and GEnx powerplants. |
| Predictive Maintenance Platform Deployment | Real-time engine health monitoring reduces unscheduled shop visits for Ryanair's narrowbody fleet. |
| Additive Manufacturing Scale-Up | Directed energy deposition capabilities at MTU Munich compress turnaround times for compressor modules. |
| Eastern European Capacity Expansion | Poland and Romania module repair facilities capture white-space from Warsaw and Kraków low-cost bases. |
| EU AI Act Inspection Algorithm Qualification | Automated borescope analysis certification creates first-mover advantage for digital-native MRO platforms. |
Research Methodology
Bottom-up commercial airline fleet modeling reconciled against top-down MRO capacity tracking forms the analytical core of this study. Primary interviews with EASA Part-145 facility directors, airline fleet managers, and additive manufacturing qualification engineers combined with secondary validation from EASA regulatory filings, REACH compliance databases, and EU F-Gas Regulation implementation reports. Trade data from German and UK customs authorities, alongside Lufthansa Technik and Rolls-Royce annual disclosures, anchored supply-side triangulation.
Input-output matrices map engine shop visit frequency against fleet age profiles and power-by-the-hour contract penetration across the projection horizon. Segmentation dimensions include service type, engine architecture, end-user category, and technology adoption tier. CAGRs derive from regression analysis of historical overhaul volume against fleet expansion patterns and regulatory compliance cost trajectories. Forecast inputs incorporate EASA emissions certification timeline assumptions and predictive maintenance platform deployment curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or supply disruption in nickel-based superalloy feedstock. Deviation in EASA additive manufacturing qualification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market