
 US Aviation MRO Software Market | 2026-2036
US Aviation MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Aviation MRO Software Market Insights
FAA Airworthiness Directive digitization is shifting maintenance record-keeping from paper-based logs to integrated software platforms. Oracle Corporation leverages cloud infrastructure to anchor enterprise-scale deployments across major carrier fleets. GE Aviation specializes in predictive maintenance modules that tie directly into engine sensor telemetry. Boeing competes through vertical integration, embedding MRO software into its broader digital aviation ecosystem.
US Aviation MRO Software encompasses digital platforms that manage aircraft maintenance workflows, parts inventory, regulatory compliance documentation, and technician scheduling through centralized databases with real-time synchronization across hangar and flight operations. These systems integrate with ARINC 633 and SPEC 2000 data standards to ensure interoperability between airlines, OEMs, and third-party repair stations. Cloud-based deployment models represent the fastest-expanding segment as carriers retire legacy on-premises servers to reduce capital intensity and enable remote access for distributed maintenance teams. Predictive maintenance solutions command premium positioning within the solution stack, drawing disproportionate R&D investment from vendors seeking differentiation through AI-driven failure forecasting.
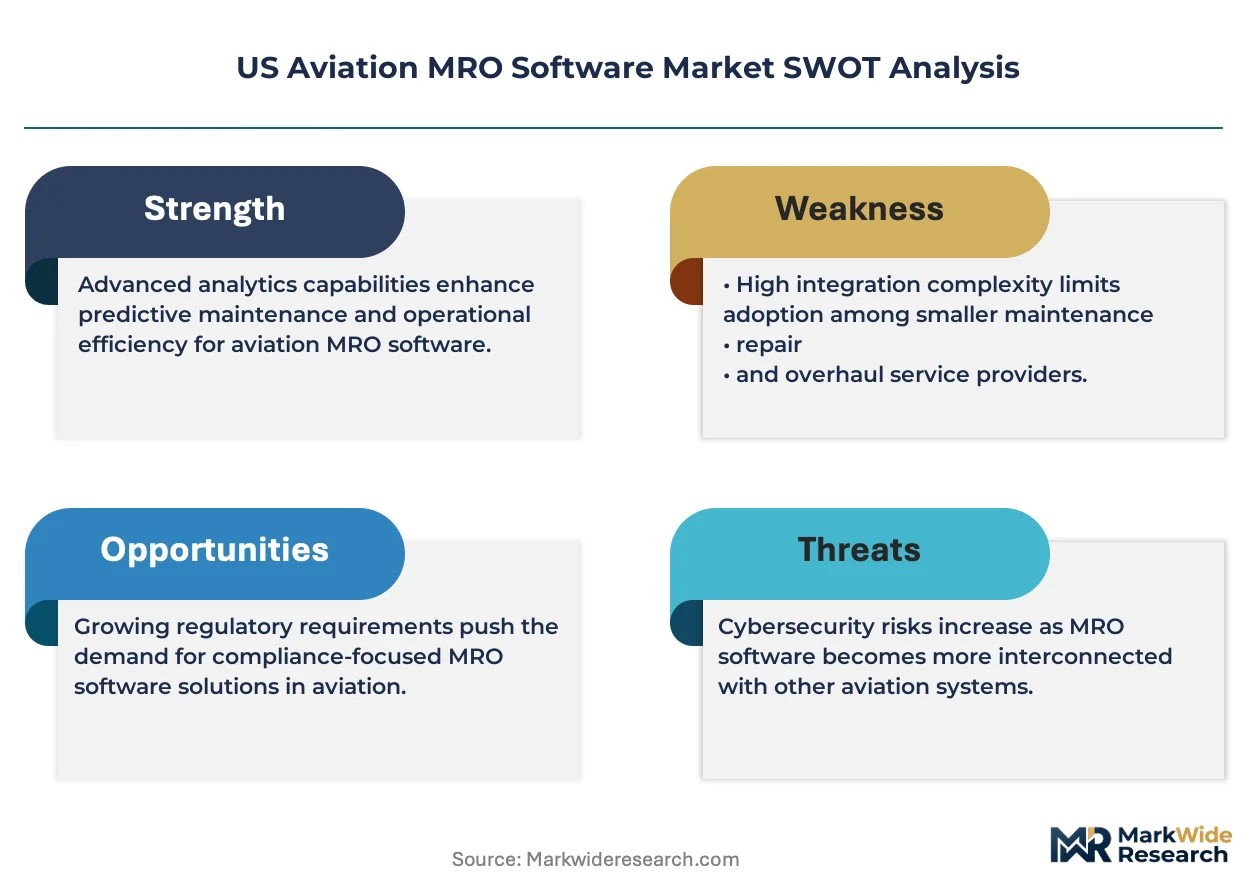
FAA mandates, NHTSA safety reporting protocols, and OSHA hangar workplace standards collectively shape software functionality requirements, forcing vendors to build audit trails, electronic signature capture, and hazard documentation modules into core platforms. The Department of Transportation's ongoing push for predictive safety analytics will tighten compliance automation expectations. Stakeholders must weigh the trade-off between proprietary system depth and open-architecture interoperability as fleet data becomes a contested strategic asset.
Market Dynamics
FAA Airworthiness Directive digitization mandates are forcing carriers to abandon paper maintenance logs, compressing procurement cycles for compliance-automation platforms and concentrating vendor selection authority among fleet technical directors.
Growth Catalysts
- ARINC 633 standardization:Airlines are mandating SPEC 2000 data interoperability to streamline parts traceability across third-party repair stations and OEM networks.
- Predictive maintenance modules:Engine sensor telemetry integration is pulling carriers toward AI-driven failure forecasting to minimize AOG incidents.
- Southwestern MRO hub concentration:Heavy maintenance demand clusters around Dallas-Fort Worth and Phoenix repair corridors, anchoring regional software procurement.
Market Restraints
- Legacy system integration costs:Carriers face prohibitive capex to bridge 1990s-era on-premises maintenance databases with cloud-native platforms.
- Cybersecurity compliance burden:FAA cybersecurity directives for aircraft systems are extending audit requirements to MRO software vendors, lengthening sales cycles.
- Technician workforce scarcity:A&P mechanic shortages in the Southwestern United States are constraining implementation velocity for workflow-automation tools.
Strategic Opportunities
- Mobile-first technician interfaces:AR-enabled troubleshooting modules are opening white space in line maintenance operations at Southwestern hub airports.
- OSHA hangar safety digitization:Automated hazard documentation workflows are creating cross-sell potential into workplace compliance software.
- Parts inventory optimization:Blockchain-anchored provenance tracking is converging with existing MRO platforms to reduce counterfeit component risk.
Industry Challenges
- Multi-fleet data harmonization:Carriers operating mixed Boeing-Airbus fleets struggle to normalize maintenance histories across incompatible OEM data formats.
- Electronic signature authentication:FAA Part 43 compliance requires cryptographic audit trails that many legacy technician workflows cannot support without overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aviation MRO Software Market |
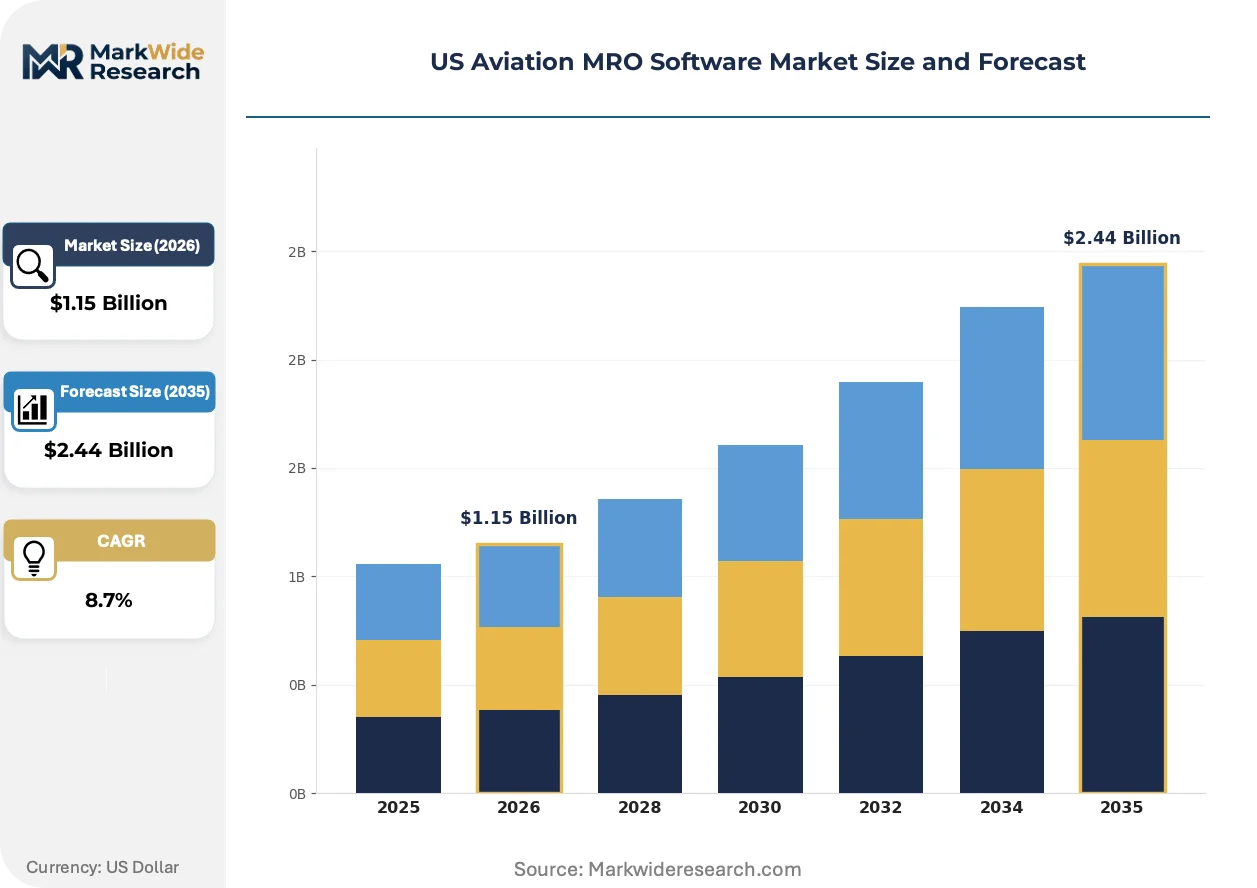
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maintenance Management, Inventory Control, Compliance Monitoring, Scheduling Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Commercial Airlines, Military Aviation, General Aviation, MRO Providers Solution: Work Order Management, Predictive Maintenance, Performance Analytics, Flight Operations |
| Companies Covered | Oracle Corporation, IBM Corporation, The Boeing Company, GE Aviation, SAP SE, CAMP Systems International Inc., Jet Support Services Inc., ATP Inc., Honeywell Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aviation MRO Software Market Trends and Innovations
Cloud infrastructure is displacing on-premises server architectures as the dominant deployment model, compressing capital requirements while enabling distributed maintenance team access. Three forces are reshaping competitive positioning.
Digital twin technology is converging with physical asset monitoring to create persistent virtual replicas of airframe and engine health. Southwestern MRO providers are piloting these systems for heavy check planning. This convergence is compressing maintenance interval forecasting from statistical estimates to physics-based simulations.
OSHA's evolving hangar workplace standards are mandating real-time exposure monitoring for hazardous materials. Software vendors are embedding chemical inventory tracking and ventilation alerts into core platforms. Line maintenance stations in high-temperature Southwestern climates face the steepest compliance adaptation curves.
Buyer consolidation among ultra-low-cost carriers is shifting procurement toward centralized fleet management platforms. Regional operators are abandoning point solutions for integrated suites. Texas and Arizona-based MRO specialists report elongated sales cycles but larger contract values.
US Aviation MRO Software Market Segmentation
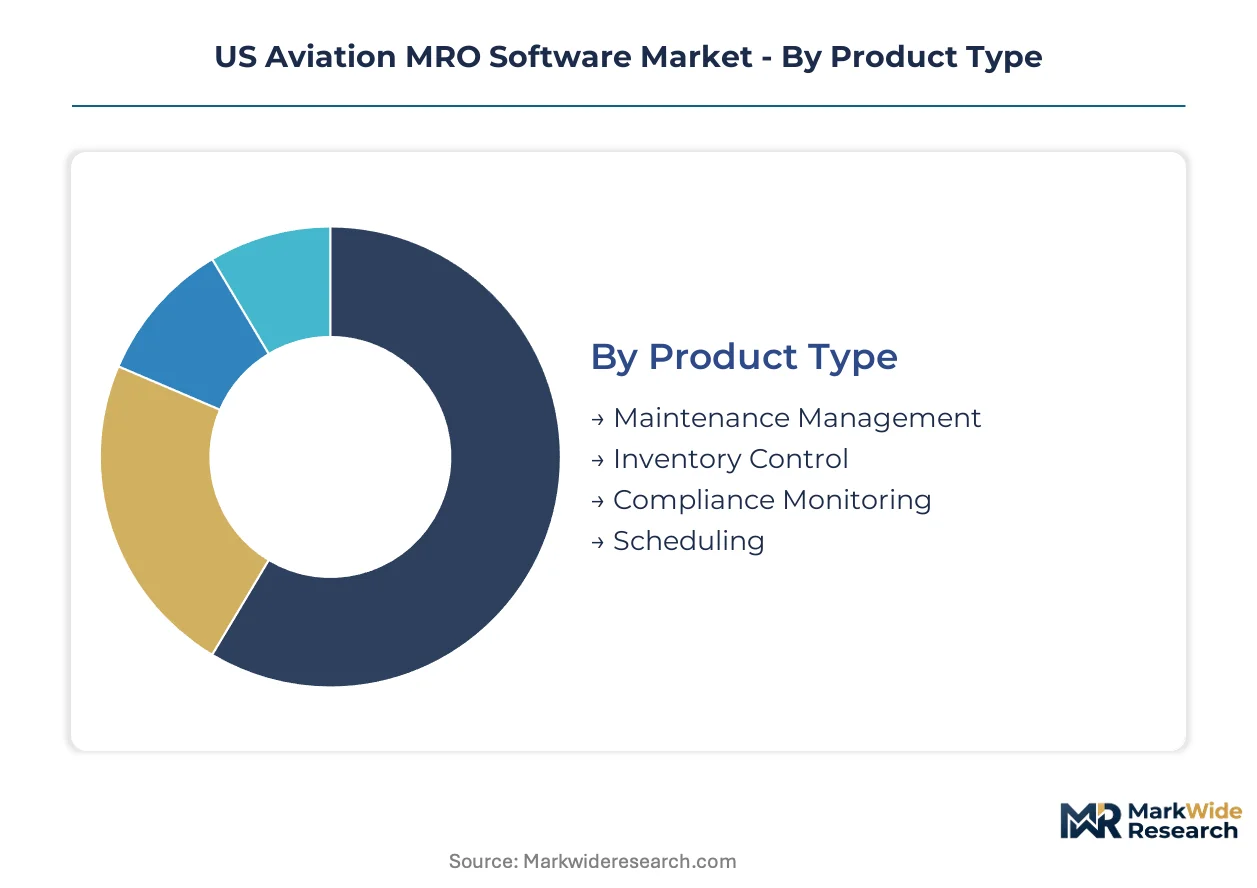
US Aviation MRO Software procurement patterns diverge sharply across fleet scale and regulatory exposure. Carrier technical directors weight solution selection against FAA audit readiness and mixed-fleet data harmonization requirements.
Product Type:
Volume concentrates in compliance-automation platforms driven by FAA Airworthiness Directive digitization mandates. Premium positioning commands predictive modules with AI-driven failure forecasting.
- Maintenance Management:Core platforms orchestrate work order routing, technician dispatch, and hangar resource allocation through centralized dashboards. Demand clusters among Southwestern MRO providers in Dallas-Fort Worth and Phoenix corridors where heavy check volume drives workflow complexity.
- Inventory Control:Systems tracking parts traceability, rotable management, and supplier integration anchor procurement for carriers operating mixed Boeing-Airbus fleets. SPEC 2000 data standardization is pulling investment toward modules with ARINC 633 interoperability.
- Compliance Monitoring:Automated audit trail generation and electronic signature capture address FAA Part 43 documentation requirements.
- Scheduling:Crew and maintenance window coordination tools optimize AOG recovery timelines.
Mature deployment sits with Maintenance Management. Newer deployment is concentrated in Compliance Monitoring.
Deployment Model:
Cost tier separation runs between capital-intensive on-premises infrastructure and operational-expense cloud models. Procurement authority increasingly rests with CIOs seeking to retire legacy server footprints.
- Cloud-Based:Remote-access architectures enable distributed maintenance team coordination without hangar-proximity server requirements. Southwestern hub operators with multiple line stations across Texas and Arizona terrain favor this model for field technician mobility.
- SaaS:Subscription licensing with embedded regulatory updates reduces compliance tracking burden for ultra-low-cost carriers with limited IT staff. Buyer consolidation among regional operators is expanding contract values for integrated suites.
- On-Premises:Air-gapped installations persist among military aviation operators with cybersecurity classification requirements.
- Hybrid:Split architectures maintain sensitive maintenance records locally while pushing analytics workloads to cloud infrastructure.
Established carriers anchor On-Premises retention. Cloud-Based solutions are climbing the fastest among commercial fleet operators.
End User:
Customer type segmentation reflects divergent regulatory exposure and procurement centralization. Military operators face distinct cybersecurity protocols while commercial carriers prioritize fleet-wide standardization.
- Commercial Airlines:Fleet technical directors mandate enterprise-scale platforms with predictive maintenance modules tied to engine sensor telemetry. Digital twin adoption for heavy check planning is expanding contract scope among network carriers.
- MRO Providers:Third-party repair stations in Southwestern maintenance corridors require multi-tenant architectures serving multiple airline clients with segregated data environments. OSHA hangar safety digitization is creating cross-sell demand for workplace compliance modules.
- Military Aviation:Defense operators prioritize air-gapped deployment with cryptographic audit trails exceeding FAA commercial requirements.
- General Aviation:Fractional ownership fleets and business jet operators favor lightweight SaaS configurations with mobile-first technician interfaces.
Procurement maturity rests with Commercial Airlines. Implementation velocity is expanding most quickly among MRO Providers.
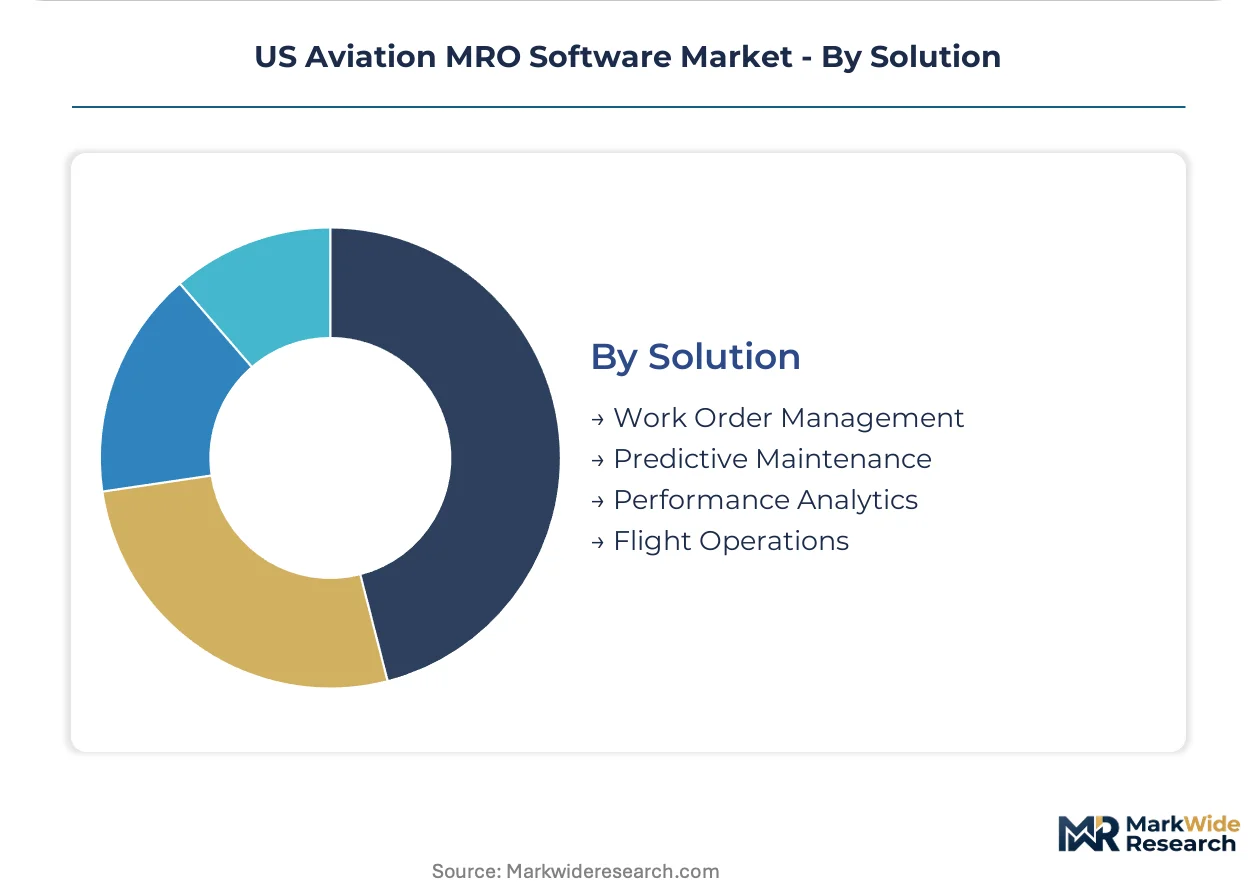
Solution:
Application depth separates operational workflow tools from strategic analytics layers. Margin concentration follows predictive capabilities with direct AOG avoidance value.
- Predictive Maintenance:AI models processing engine sensor telemetry and flight data recorder outputs forecast component degradation before failure triggers operational disruption. Southwestern operators with high-temperature climate exposure prioritize thermal stress prediction for line maintenance.
- Work Order Management:Digital task card distribution and electronic sign-off capture streamline technician execution while building FAA-compliant audit trails. A&P mechanic scarcity in Southwestern labor markets is accelerating automation investment.
- Performance Analytics:Fleet reliability dashboards aggregate maintenance history across mixed OEM data formats for normalized benchmarking.
- Flight Operations:Integration with crew scheduling and dispatch systems closes the loop between maintenance status and flight release authority.
Deep integration characterizes Work Order Management. Predictive Maintenance is gaining share fastest as carriers retire statistical interval planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone incentives in Texas and Arizona concentrate heavy maintenance capacity, anchoring regional software procurement clusters. FAA Airworthiness Directive digitization mandates synchronize compliance automation demand across Southwestern repair corridors. State-level workforce development programs in aviation mechanics shape implementation velocity for workflow platforms.
Texas
Dallas-Fort Worth International Airport anchors the nation's densest third-party MRO corridor, driving enterprise-scale platform procurement. Texas Workforce Commission aviation mechanic apprenticeships address A&P technician scarcity constraining automation rollout. Foreign Trade Zone 168 at Alliance Airport concentrates heavy check volume for narrowbody fleets.
Arizona
Phoenix Sky Harbor and Tucson International host expanding line maintenance stations requiring mobile-first technician interfaces. Arizona Commerce Authority aerospace tax credits attract MRO providers seeking lower operational costs than California. Mesa-Gateway Airport corridor pilots digital twin technology for thermal stress prediction in desert climate operations.
California
Los Angeles International and San Francisco International sustain legacy carrier fleet management platform upgrades despite higher labor costs. California Air Resources Board emissions monitoring extends to hangar operations, embedding environmental compliance modules in MRO software. San Diego's military aviation cluster maintains air-gapped cybersecurity requirements distinct from commercial deployments.
Florida
Miami International and Orlando International support Latin American carrier MRO demand, requiring multi-tenant architectures with segregated data environments. Florida Department of Transportation aviation grants fund workforce training programs easing technician onboarding for automated systems. Tampa-St. Petersburg corridor specializes in cargo fleet maintenance driving inventory control module investment.
Illinois
Chicago O'Hare International anchors Midwest network carrier technical operations, concentrating procurement authority for integrated fleet management suites. Illinois Department of Commerce aerospace incentives target MRO software R&D facilities. Rockford International cargo expansion drives parts traceability system demand for integrated carrier-MRO workflows.
US Aviation MRO Software Market Competitive Landscape
US-based technology conglomerates anchor one tier; European enterprise software specialists hold procurement relationships with network carriers seeking regulatory compliance depth. Market structure concentrates among five to seven vendors with cloud infrastructure scale, while mid-tier specialists fragment across narrow maintenance workflow niches. Two archetypes dominate: full-stack platform providers integrating predictive analytics, and point-solution vendors capturing technician mobility segments. Competitive moves center on cloud migration partnerships and predictive module acquisitions.
Among US-based platform providers, Oracle Corporation and GE Aviation exemplify contrasting strategic positions. Oracle Corporation anchors enterprise-scale deployments through cloud infrastructure breadth. GE Aviation occupies a predictive maintenance specialization tied to engine telemetry integration. IBM Corporation represents the hybrid archetype bridging legacy system integration with AI-driven analytics layers.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| The Boeing Company |
| GE Aviation |
| SAP SE |
| CAMP Systems International Inc. |
| Jet Support Services Inc. |
| ATP Inc. |
| Honeywell Aerospace |
| Others |
Pricing and Supply Chain Analysis
A&P mechanic scarcity across Texas and Arizona maintenance corridors widens labor-cost differentials between premium predictive platforms and baseline compliance modules, compressing margins for vendors unable to automate technician workflows.
Pricing Analysis
Short lead-time premiums for FAA Part 43 compliance automation compress procurement cycles among carriers facing audit deadlines. Three-tier pricing structure across enterprise, mid-market, and entry-level SaaS tiers separates Oracle-scale cloud deployments from point-solution vendors. Price differentiation centers on AI-driven failure forecasting capabilities and ARINC 633 interoperability depth. Cost compression in the entry tier is intensifying because ultra-low-cost carriers consolidate procurement around integrated suites.
Supply Chain Analysis
Domestic-content mandates under FAA cybersecurity directives for aircraft systems are reshaping vendor sourcing toward US-based cloud infrastructure providers. Software development concentrates in California, Texas, and Washington state engineering clusters. Platform architecture draws from hyperscaler compute resources, proprietary AI model training pipelines, and SPEC 2000 data standard libraries. Single-source vulnerability sits with concentrated hyperscaler reliance for enterprise-scale deployments. Distribution runs through direct enterprise sales teams and aviation-specific systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack platform providers as FAA cybersecurity compliance burdens force point-solution vendors toward acquisition or exit.
For Market Incumbents: Lock in fleet technical director relationships through predictive maintenance module bundling with core compliance platforms. Deepen backward integration into engine sensor telemetry data streams to defend against GE Aviation's OEM-anchored positioning. Prioritize cloud migration partnerships with Southwestern MRO providers in Dallas-Fort Worth and Phoenix corridors where heavy check volume anchors multi-year contracts. For New Entrants and Emerging Players: Direct-to-technician mobile interfaces offer the most penetrable white space, targeting line maintenance stations at Arizona hub airports where A&P mechanic scarcity constrains incumbent rollout velocity. Focus AR-enabled troubleshooting modules on thermal stress prediction for desert climate operations. Pursue OEM-agnostic positioning to exploit multi-fleet data harmonization pain points among mixed Boeing-Airbus operators. For Investors and Strategic Acquirers: Re-rating potential sits with predictive maintenance specialists given FAA's push toward automated safety analytics and carrier urgency to minimize AOG incidents. Target vendors with proven AI model accuracy in component degradation forecasting and established ARINC 633 interoperability. Watch for inflection when Department of Transportation predictive safety analytics mandates tighten compliance automation expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Module Acquisition | Engine sensor telemetry integration anchors premium positioning against AOG cost avoidance. |
| Cloud Infrastructure Partnership | Hyperscaler alliances compress capital requirements for distributed maintenance team access. |
| AR-Enabled Technician Interface Launch | Mobile-first troubleshooting captures line maintenance white space at Southwestern hubs. |
| OSHA Safety Digitization Cross-Sell | Automated hazard documentation extends platform scope into workplace compliance software. |
| Blockchain Provenance Integration | Parts traceability modules reduce counterfeit component risk for inventory control buyers. |
Research Methodology
Independent corroboration across fleet technical directors, MRO operations managers, and aviation software procurement officers underwrites the qualitative findings. Primary fieldwork encompassed structured interviews with airline IT executives, third-party repair station controllers, and FAA compliance auditors alongside validation calls with systems integrators serving Southwestern maintenance corridors. Secondary sources included FAA Airworthiness Directive filings, Department of Transportation safety analytics disclosures, SEC 10-K software segment reports, and OSHA hangar workplace standard updates. Bottom-up vendor revenue estimates and top-down carrier IT spend allocations were cross-referenced for triangulation.
Historical reference periods anchored the projection framework to pre-pandemic fleet utilization baselines and post-recovery digital transformation cycles across the analysis window. Segmentation dimensions encompassed deployment model, fleet scale tier, regulatory exposure intensity, and mixed-fleet data complexity. CAGRs were derived from regression analysis against aircraft fleet growth, MRO labor cost inflation, and compliance automation penetration curves. Forecast inputs weighted FAA mandate implementation timelines and cloud infrastructure adoption velocity among regional operators.
The model holds under steady FAA regulatory enforcement and continued hyperscaler cloud expansion; deviation in cybersecurity directive stringency or A&P mechanic training program funding would shift implementation timelines. Forecasts reflect documented assumptions about carrier consolidation patterns and OEM data format standardization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Global Degaussing System Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market