
 Military Antenna Market | 2026-2036
Military Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Military Antenna Market Intelligence
The emphasis on electronic warfare capabilities over traditional communication applications is rebalancing procurement priorities for military antennas. This shift favors suppliers with integrated systems expertise. L3Harris Technologies, Inc. leverages its strong position in tactical communications and electronic systems. BAE Systems specializes in advanced aperture technologies and signal processing for surveillance and threat detection platforms. General Dynamics Corporation sustains its market presence through extensive platform integration contracts across land and naval systems.
A military antenna is an apparatus designed to transmit and receive electromagnetic waves for defense applications, engineered for durability and performance in harsh environments. These devices must operate across specific frequency bands, from HF to Ka-band, with high gain and low sidelobe characteristics. Within technology segments, active antenna systems incorporating software-defined radios are gaining share over passive systems. Phased array antennas represent a premium product type, essential for advanced surveillance and electronic warfare applications, commanding higher margins than simpler dipole or blade antennas.
Product development adheres to stringent military standards such as MIL-STD-810 for environmental engineering and MIL-STD-461 for electromagnetic interference. In Europe, compliance with CE marking directives is necessary for dual-use components, while NATO Standardization Agreements (STANAGs) ensure interoperability. Vendors must navigate these complex requirements to secure contracts with military forces. The primary strategic decision for manufacturers involves balancing investment in next-generation phased array technologies against the volume market for conventional antenna types.
Market Dynamics
The central tension in the military antenna market is the strategic resource allocation between developing high-margin, complex active phased array systems for electronic warfare and servicing the high-volume, lower-margin demand for conventional communication antennas for platform-wide modernization.
Growth Catalysts
- Software-Defined Radios (SDRs):The integration of SDRs drives demand for agile antennas that can support dynamic frequency hopping and cognitive radio functions, enhancing communications resilience and electronic support measures.
- NATO Modernization Mandates:Interoperability requirements under NATO Standardization Agreements (STANAGs) compel member nations, such as Poland and the Baltic states, to upgrade legacy communication systems, creating a consistent replacement cycle for compliant antennas.
- Unmanned Systems Proliferation:The expanding operational use of unmanned aerial vehicles (UAVs) and unmanned ground vehicles (UGVs) requires compact, lightweight, and high-gain antennas for reliable command, control, and sensor data links.
Market Restraints
- Gallium Nitride (GaN) Supply Constraints:High-performance active antennas rely on GaN semiconductors, whose concentrated supply chain is subject to geopolitical risk and price volatility, limiting mass production and increasing lead times.
- Stringent Export Controls:Defense trade regulations, including the US International Traffic in Arms Regulations (ITAR), impose significant administrative burdens and limit the addressable market, lengthening sales cycles for advanced systems.
- Spectrum Congestion:The increasingly crowded electromagnetic spectrum in operational theaters creates severe interference challenges, requiring complex and costly filtering solutions that can compromise antenna size, weight, and power (SWaP) budgets.
Strategic Opportunities
- Indo-Pacific Naval Expansion:Rising defense investment in Japan, Australia, and South Korea for maritime surveillance and air defense platforms creates significant opportunities for suppliers of advanced naval radar and satellite communication antennas.
- Militarized LEO Communications:The build-out of Low Earth Orbit (LEO) satellite constellations for resilient military communications opens a new market for advanced ground station and platform-integrated antennas capable of tracking multiple fast-moving satellites.
- Metamaterial-Based Apertures:Development of electronically steerable antennas using engineered metamaterials offers a path to radical SWaP-C reduction compared to traditional phased arrays, enabling integration on smaller platforms.
Industry Challenges
- RF Engineering Talent Scarcity:A persistent shortage of radio frequency engineers with expertise in digital beamforming and monolithic microwave integrated circuit (MMIC) design hampers product development and innovation across the industry.
- Legacy Platform Integration:Integrating modern, digitally-controlled antennas with older, analog-based vehicle and ship electronics presents significant software and hardware interface challenges, often requiring costly, custom engineering efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Antenna Market |
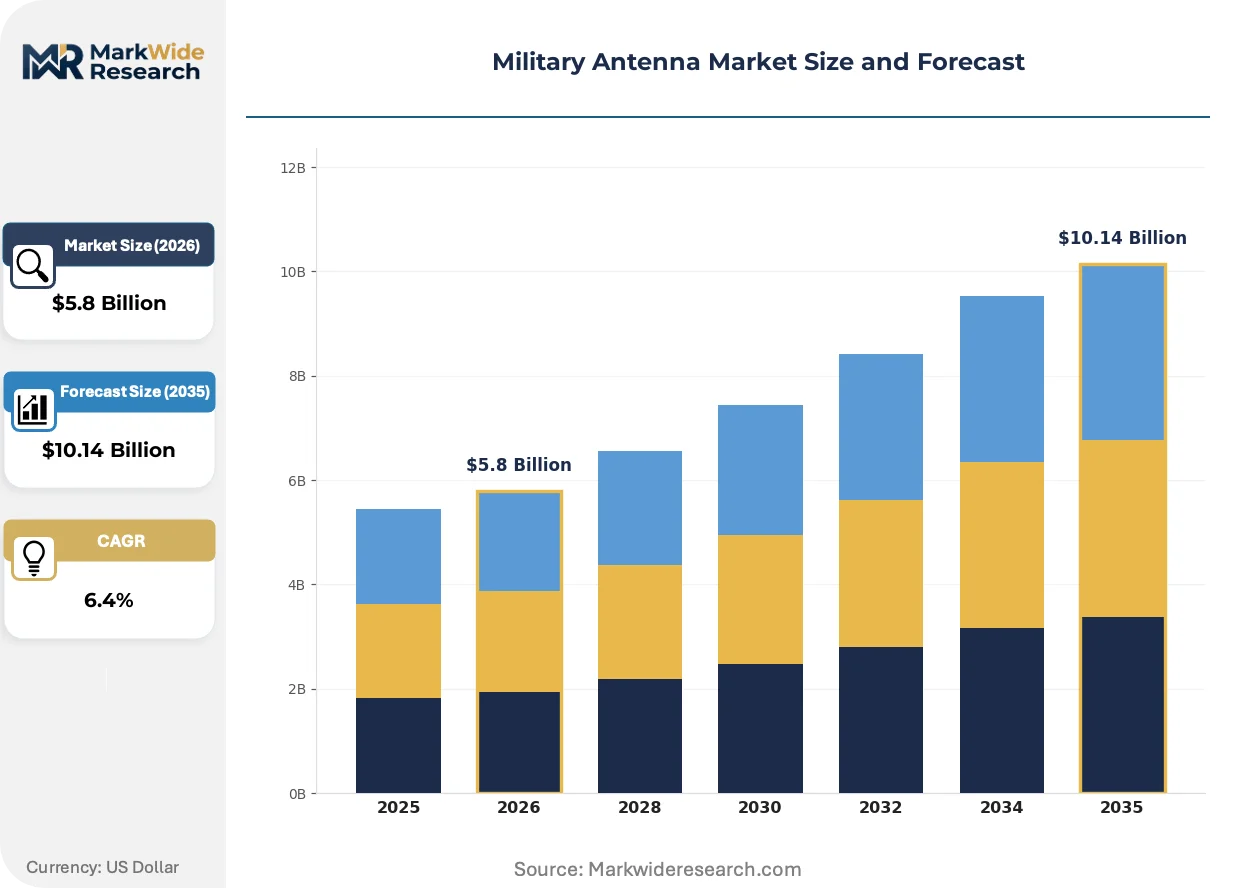
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Antennas, Dipole Antennas, Phased Array Antennas, Log-Periodic Antennas Technology: Active Antenna Systems, Passive Antenna Systems, Software-Defined Radios, Integrated Antenna Systems Application: Communication, Surveillance, Navigation, Electronic Warfare End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions |
| Companies Covered | Thales, General Dynamics Corporation, L3Harris Technologies, Inc., Lockheed Martin Corporation, Rohde & Schwarz, RTX, Honeywell International Inc., Viasat, Inc., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Antenna Market Strategic Shifts & Innovations
The convergence of advanced digital processing directly at the aperture is creating intelligent antennas that can sense, adapt, and respond to the electromagnetic environment in real time. This moves the antenna's role beyond a simple transducer to a core component of the electronic warfare and signals intelligence sensor web.
Active Electronically Scanned Arrays (AESA) use thousands of software-controlled transmit/receive modules to steer radar and communication beams without physical movement. Air forces and navies are rapidly adopting AESA technology for next-generation fighter jets, surface combatants, and surveillance aircraft. This technology is electrifying battlefield awareness by enabling simultaneous multi-function operations like tracking, jamming, and data linking from a single aperture.
European Union spectrum harmonization policies, driven by frameworks like Permanent Structured Cooperation (PESCO), promote the development of interoperable communication systems. This regulatory push incentivizes the creation of multi-band antennas that can operate seamlessly across different national forces' equipment. The trend most affects suppliers targeting pan-European defense programs, who must now engineer for broader compatibility beyond specific national or NATO standards.
A clear shift is occurring from procuring individual antenna components to acquiring integrated radio frequency (RF) front-end subsystems. This model challenges standalone antenna specialists, favoring vertically integrated suppliers that can deliver a pre-validated module including the antenna, amplifiers, and filters. This demand-side change is most prominent in the United States for airborne pod and radar modernization programs where optimizing size, weight, and power is a primary design driver.
Military Antenna Market Segmentation
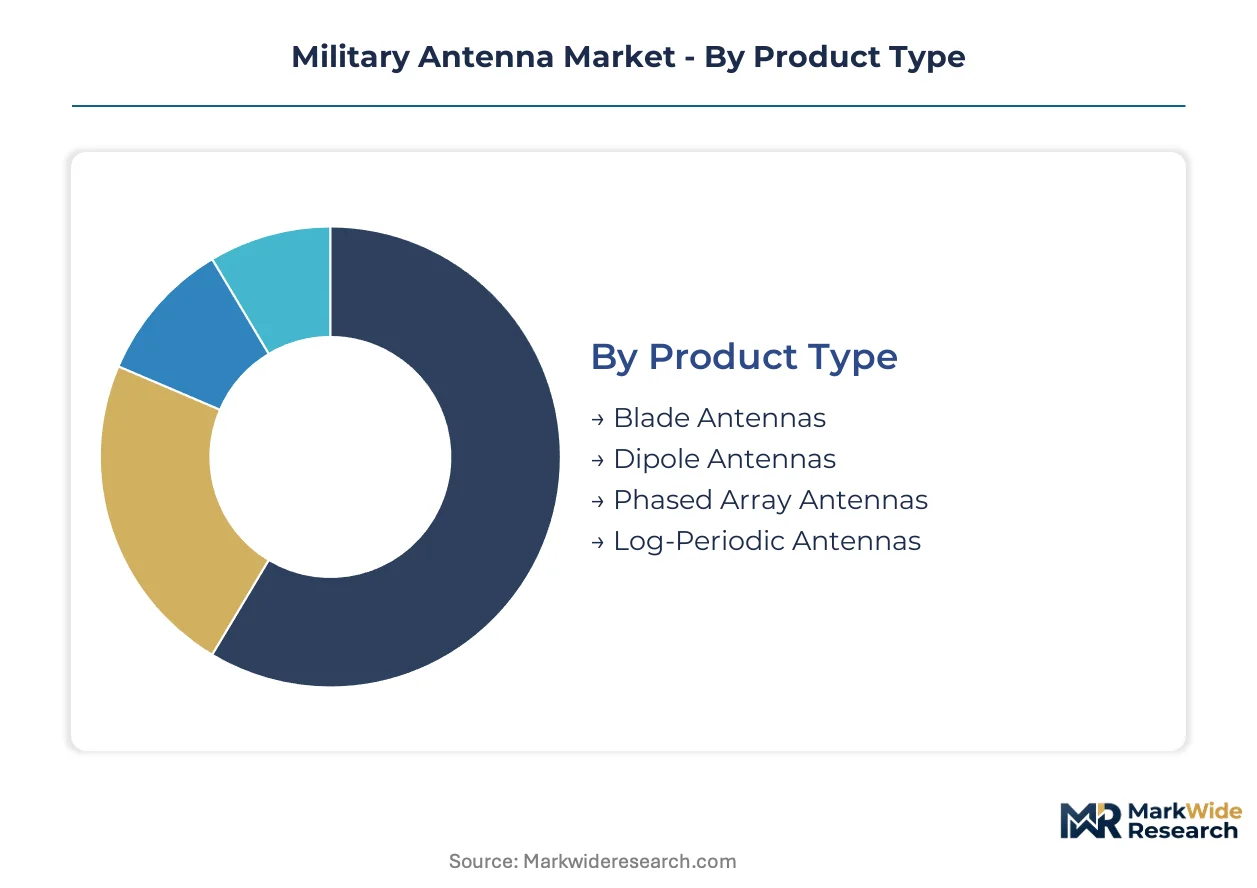
Understanding the segmentation of the military antenna market is crucial for identifying areas of concentrated demand and emerging technological shifts. This detailed breakdown highlights how modernization programs and evolving threat landscapes influence procurement decisions across various product types, technologies, applications, and end-users within the defense sector.
Product Type:
The upgrade cycle for military platforms directly influences antenna product type demand, emphasizing both advanced capabilities and reliable legacy replacements.
- Phased Array Antennas:These advanced systems electronically steer beams without physical movement, essential for multi-function radar, electronic warfare, and advanced surveillance platforms. Demand is concentrating in next-generation fighter jets and naval combatants in the United States and Japan, driven by the need for simultaneous tracking and jamming capabilities.
- Blade Antennas:Designed for aerodynamic efficiency and ruggedness, blade antennas are commonly used for VHF/UHF communication and navigation across a wide range of aircraft. Their demand remains consistently high for platform-wide modernization and replacement cycles in European NATO member states, supporting interoperable communication systems.
- Dipole Antennas:Simple and robust, dipole antennas serve as fundamental components for various radio communication systems across ground and naval platforms.
- Log-Periodic Antennas:These broadband antennas offer stable performance across wide frequency ranges, making them suitable for electronic intelligence and countermeasure applications.
Blade Antennas sits at the top of the volume ranking, with Phased Array Antennas climbing the fastest.
Technology:
Technological maturity and integration complexity define distinct market segments for military antenna systems, influencing development priorities and adoption rates.
- Active Antenna Systems:These systems integrate transmit/receive modules directly with the antenna elements, enabling digital beamforming and enhanced signal processing at the aperture. The United States and Australia are investing heavily in these systems for advanced radar and electronic warfare applications, seeking superior performance and reduced size, weight, and power.
- Software-Defined Radios:SDRs allow for dynamic reconfiguration of communication waveforms and frequency bands through software, requiring agile antennas that can support cognitive radio functions. Poland and the Baltic states are driving demand for SDR-compatible antennas to meet NATO interoperability standards and enhance communications resilience.
- Passive Antenna Systems:Traditional antennas that rely on external transceivers for signal processing, offering cost-effectiveness for standard communication and navigation tasks.
- Integrated Antenna Systems:Solutions combining multiple antenna functions into a single physical unit, optimizing space and reducing installation complexity on diverse military platforms.
Active Antenna Systems lead in technological innovation, while Software-Defined Radios demonstrate significant market penetration.
Application:
Defense strategic priorities directly shape the demand across various military antenna applications, reflecting the evolving nature of modern warfare.
- Electronic Warfare:Antennas for electronic warfare (EW) are designed for jamming, deception, and signal intelligence, requiring high gain, wide bandwidth, and low sidelobe performance. Demand from the United States and Japan is particularly strong for these applications, driven by the need to counter advanced threats in contested electromagnetic environments.
- Communication:These antennas facilitate secure and reliable voice and data links for tactical, strategic, and satellite communications across all military domains. NATO modernization mandates are a key driver for communication antenna upgrades, ensuring interoperability among member nations.
- Surveillance:Antennas for surveillance systems support radar, SIGINT, and ELINT platforms, providing critical battlefield awareness and threat detection capabilities.
- Navigation:Essential for GPS, inertial navigation, and other positioning systems, navigation antennas ensure precise location and guidance for military assets.
Electronic Warfare applications command the highest margin, with Communication applications representing consistent demand.
End User:
Procurement patterns and specific operational requirements differentiate demand across military antenna end-user segments, reflecting distinct acquisition processes.
- Military Forces:Direct end-users who procure antennas for integration into their operational platforms, including air, land, and naval systems. Defense spending increases in countries like Japan and Australia directly translate into procurement for their armed forces, particularly for naval and air defense platforms.
- Defense Contractors:Companies that design, develop, and integrate complex defense systems, acting as prime contractors for large-scale military programs. L3Harris Technologies and BAE Systems exemplify contractors driving demand for advanced antenna solutions as part of larger system packages for global defense clients.
- Government Agencies:Non-military government entities involved in defense-related research, intelligence, or border security, requiring specialized antenna systems.
- Research Institutions:Organizations focused on developing next-generation antenna technologies and prototypes for future military applications, often funded by defense grants.
Military Forces represent the largest purchasing segment, while Defense Contractors are critical for system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense technology hubs across the globe drive significant demand for military antennas, reflecting ongoing modernization programs and evolving threat landscapes. These regional dynamics are shaped by national defense budgets, strategic alliances, and the imperative for advanced electronic warfare capabilities. The market sees concentrated procurement activity in key industrialized nations.
United States
The United States leads in military antenna procurement, driven by substantial defense spending on next-generation fighter jets and naval combatants. US International Traffic in Arms Regulations (ITAR) impose stringent export controls on advanced systems, influencing domestic production. California's aerospace and defense corridor drives innovation in advanced radar and electronic warfare systems.
Japan
Japan's defense investment, particularly for maritime surveillance and air defense platforms, fuels demand for sophisticated military antennas. The Ministry of Economy, Trade and Industry (METI) oversees defense technology development and industrial policy. Tokyo's defense industry firms focus on advanced naval radar and satellite communication antennas for regional security.
Poland
Poland's commitment to NATO modernization mandates compels significant upgrades to its communication systems, creating consistent demand for compliant antennas. Compliance with NATO Standardization Agreements (STANAGs) ensures interoperability among allied forces. Warsaw's defense sector integrates new communication systems for land forces modernization programs.
Australia
Australia is investing heavily in advanced naval radar and air defense platforms, increasing demand for high-performance military antennas. The nation's defense procurement frameworks prioritize local industrial capability and technological self-reliance. Adelaide's shipbuilding industry drives demand for advanced naval radar and satellite communication antennas.
Military Antenna Market Key Industry Players
Strategic partnerships and portfolio diversification dominate the current landscape, as companies seek to offer integrated solutions rather than standalone components. The market structure is tiered, with large defense prime contractors operating alongside specialized antenna manufacturers. Key competitive moves include vertical integration into critical component supply chains and technology licensing to expand market reach.
Within the vertically integrated defense prime archetype, L3Harris Technologies, Inc. leverages its strong position in tactical communications and electronic systems. BAE Systems exemplifies a specialist in advanced aperture technologies and signal processing for surveillance platforms. General Dynamics Corporation occupies a position through extensive platform integration contracts across land and naval systems, anchoring a significant portion of market activity.
| Leading Market Players |
|---|
| Thales |
| General Dynamics Corporation |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| Rohde & Schwarz |
| RTX |
| Honeywell International Inc. |
| Viasat, Inc. |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
NATO modernization mandates compel nations to upgrade legacy communication systems, requiring suppliers to meet stringent interoperability standards, which affects pricing due to compliance costs and specialized component needs.
Pricing Analysis
Rising input costs, particularly for Gallium Nitride (GaN) semiconductors, exert upward pressure on pricing for active antenna systems. The dominant pricing model for advanced systems is project-based, while conventional antennas often use per-unit transactional pricing. Price differentiation stems from customization level for phased arrays and volume scale for blade antennas. Cost compression in conventional antennas is intensifying due to high-volume demand from European NATO member states. Military Forces are less price-sensitive for advanced electronic warfare systems, while Defense Contractors are more sensitive for high-volume, lower-margin communication components.
Supply Chain Analysis
Reverse logistics for military antennas primarily involves specialized repair and refurbishment programs due to the high value and long service life of these assets. The supply chain for advanced military antennas concentrates in the United States, Japan, and parts of Europe, particularly for specialized components. Production relies heavily on critical raw materials such as GaN semiconductors, specialized RF integrated circuits, and high-grade composites. Geopolitical risk for GaN supply represents a significant structural risk for active antenna manufacturers. Distribution typically occurs through direct sales channels to military forces and defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military antenna market is a late-cycle quality story as defense spending shifts towards advanced electronic warfare capabilities. This demand-shift favors premium, high-performance phased array antennas over conventional types.
For Market Incumbents:Anticipate sustained demand for integrated RF front-end subsystems, driven by airborne pod and radar modernization programs. Invest in next-generation GaN-based active antenna systems to counter emerging threats and maintain technological leadership. Deepen backward integration for critical components like monolithic microwave integrated circuits (MMICs) to mitigate supply chain risks. Focus on MIL-STD-810 and MIL-STD-461 compliance as a barrier to entry against less specialized competitors.
For New Entrants and Emerging Players:Capture opportunities in the unmanned systems segment by developing compact, lightweight, metamaterial-based apertures. Target the NATO modernization mandates in Poland and the Baltic states with SDR-compatible multi-band antenna solutions. Leverage agility in RF engineering talent to offer custom integration services for legacy platform upgrades. Focus on niche applications requiring advanced signal processing capabilities for electronic support measures.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized technology providers offering advanced phased array and metamaterial antenna solutions. The long-term viability extends over a decade, driven by continuous defense modernization cycles and geopolitical tensions. Acquisition targets should be agile firms with strong intellectual property in digital beamforming or advanced material science. Monitor defense budget allocations in the Indo-Pacific region and LEO satellite communication contracts for inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in GaN MMIC R&D | Secures critical component supply and enhances active antenna performance for electronic warfare systems. |
| Develop Metamaterial Antennas | Enables radical size, weight, and power-cost reduction for integration on smaller unmanned platforms. |
| Expand SDR-Compatible Portfolio | Addresses interoperability requirements and dynamic frequency agility for European defense modernization programs. |
| Strengthen Platform Integration Expertise | Ensures seamless deployment of advanced antenna systems across complex land and naval combat platforms. |
| Pursue NATO STANAG Certification | Unlocks consistent replacement cycles and market access within the European defense sector for communication antennas. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, analysis of defense procurement data, and secondary validation from technical publications — were reconciled to build a robust market perspective. This involved engaging RF engineers, defense procurement officers, prime contractor project managers, and defense policy analysts. Secondary data sources included MIL-STD documents, NATO STANAGs, national defense budget reports, and company annual filings, enabling both bottom-up and top-down triangulation.
Historical market data was cross-referenced against expert panel input to establish a comprehensive forecast framework over the projection horizon. The analysis modeled segmentation dimensions including product type, technology, application, end-user, and regional defense spending. Compound annual growth rates were derived from a model incorporating demand-side drivers and supply-side constraints. Key forecast inputs included defense modernization program timelines and electronic warfare system upgrade cycles.
Geopolitical shifts, technological breakthroughs in materials science, and defense budget reallocations are the dominant revision risks for market forecasts. These forecasts reflect current assumptions regarding procurement priorities and supply chain stability. Practitioners should monitor advanced materials R&D and major defense program announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Global Military Communications Market