
 Tactical Inertial Systems Market | 2026-2036
Tactical Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Inertial Systems Market Analytics
Defense procurement agencies is bifurcating demand between legacy platform upgrades and next-generation unmanned system programs. Honeywell International Inc. leverages its captive MEMS fabrication capacity to dominate tactical-grade accelerometer supply. Safran Group anchors European demand through ring laser gyroscope specialization for land and naval platforms. Kearfott Corporation competes in the combined systems segment with vertically integrated inertial measurement unit production.
Tactical inertial systems comprise self-contained navigation instruments that measure linear acceleration and rotational rate to compute position, velocity, and attitude without external references, typically achieving bias stability below one degree per hour and operating across temperature ranges from minus 40 to plus 71 degrees Celsius for military qualification. These systems serve as primary navigation backbones when GPS signals are jammed or unavailable in electronic warfare environments. Fiber optic gyroscopes command the highest precision tier in guidance systems for long-range munitions, while MEMS-based micro inertial navigation penetrates swarming robotics and disposable platforms where unit cost constraints dominate. GPS-aided technology represents the fastest-expanding configuration as militaries demand seamless degradation from satellite-dependent to purely inertial modes.
US DoD PNT resilience mandates and NATO STANAG certification requirements shape product roadmaps, forcing vendors to demonstrate anti-spoofing and anti-jamming performance in live trials. The EU AI Act and emerging European Defence Fund procurement rules add compliance layers for cross-border platform integration. Stakeholders must monitor how export control recalibrations under ITAR reform discussions reshape supplier eligibility for allied nation programs.
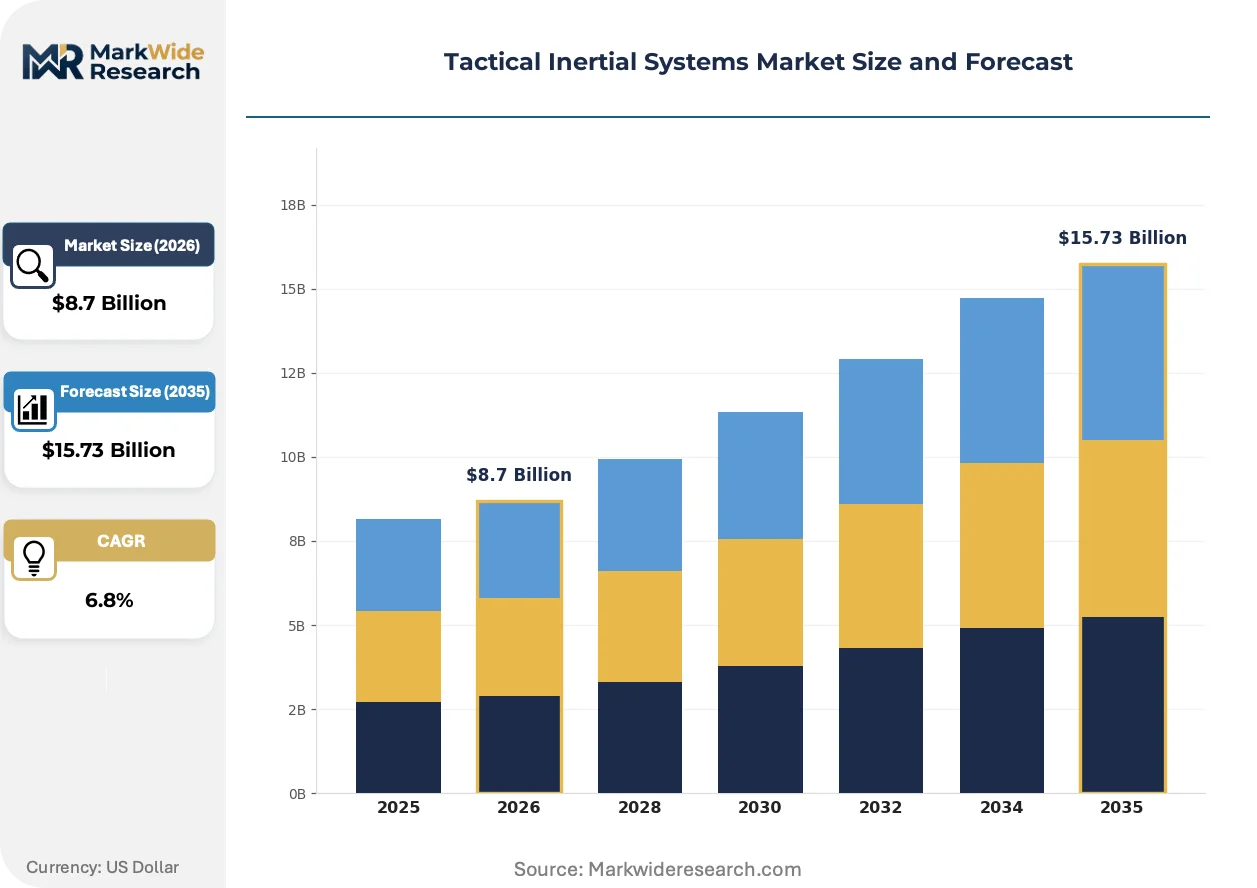
Market Dynamics
Defense procurement agencies across NATO member states are bifurcating demand between legacy platform upgrades and next-generation unmanned system programs, forcing suppliers to maintain dual production lines for ring laser gyroscopes and MEMS-based alternatives simultaneously.
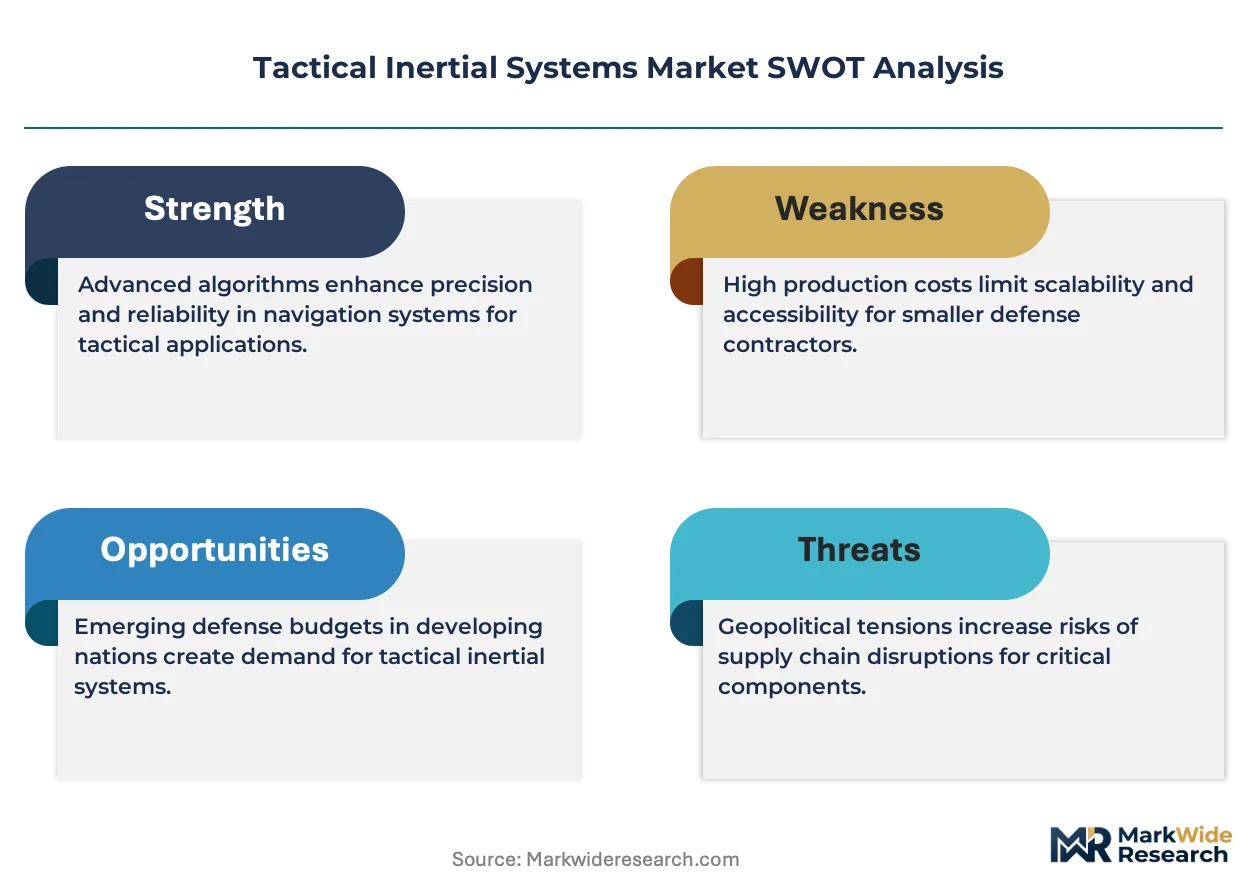
Growth Catalysts
- US DoD PNT Resilience Mandates:The Department of Defense's position-navigation-timing resilience requirements in contested environments are accelerating technology refresh cycles for GPS-denied navigation suites.
- Swarming Robotics Deployment:Military demand for disposable micro inertial navigation units in unmanned aerial vehicle swarms is expanding addressable unit volumes beyond traditional precision-guided munitions.
- NATO STANAG Certification:Standardization requirements for cross-border platform integration are creating pull-through demand for certified inertial measurement units across allied defense procurement programs.
Market Restraints
- ITAR Export Control Friction:US International Traffic in Arms Regulations reform discussions are recalibrating supplier eligibility for allied nation programs, creating uncertainty in cross-border technology transfer.
- High-Purity Fiber Optic Coil Supply Concentration:Specialty fiber production for precision gyroscopes concentrates among limited qualified suppliers, exposing downstream integrators to input bottlenecks.
- Temperature Hardening Cost Structure:Military qualification requirements spanning minus 40 to plus 71 degrees Celsius impose thermal cycling validation costs that exclude commercial-grade MEMS competitors from tactical-tier procurement.
Strategic Opportunities
- EU AI Act Compliance Layer:Emerging European Defence Fund procurement rules incorporating algorithmic transparency requirements create first-mover advantage for vendors with pre-certified autonomous navigation software stacks.
- GPS-Aided Inertial Convergence:Seamless degradation technology from satellite-dependent to purely inertial modes represents the fastest-expanding configuration as militaries demand jam-resistant navigation backbones.
- Arizona Defense Corridor Cluster:Concentrated testing infrastructure and prime contractor proximity in the southwestern United States offers co-location efficiencies for qualification-intensive product development cycles.
Industry Challenges
- Anti-Spoofing Live Trial Certification:Demonstrating anti-jamming performance in contested electronic warfare environments requires access to restricted military test ranges, creating queue bottlenecks for vendor validation schedules.
- Legacy Platform Integration Complexity:Backward compatibility requirements for 1980s-era ring laser gyroscope form factors constrain mechanical packaging innovation for next-generation solid-state replacements.
- Specialized Inertial Engineer Scarcity:Deep expertise in bias stability characterization below one degree per hour resides within a narrow demographic of defense-industry veterans approaching retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Inertial Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro Inertial Navigation, Fiber Optic Gyroscopes, Accelerometers, Combined Systems Technology: MEMS, Ring Laser Gyroscopes, GPS-Aided, Tactical Grade End User: Defense, Aerospace, Marine, Robotics Application: Guidance Systems, Navigation, Stabilization, Motion Control |
| Companies Covered | Honeywell International Inc., Thales Group, Analog Devices Inc., Kearfott Corporation, Rockwell Collins Inc., Northrop Grumman Corporation, Collins Aerospace, KVH Industries Inc., Safran Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Inertial Systems Market Evolving Landscape
Active development programs are compressing the traditional trade-off between tactical-grade precision and unit cost, enabling new deployment concepts previously excluded by economic constraints on disposable platforms.
MEMS-based micro inertial navigation is decomposing the historical monopoly of fiber optic gyroscopes in swarming robotics applications. Defense laboratories in the United States and United Kingdom are qualifying silicon accelerometer arrays for disposable unmanned aerial platforms. This cost collapse is decomposing the traditional volume ceiling that restricted tactical inertial systems to reusable assets.
EU AI Act algorithmic transparency requirements are mandating explainable navigation decision pathways for autonomous platforms operating in European airspace and territorial waters. Vendors must now document inertial fusion logic for certification authorities. Land and naval platform programs in France, Germany, and Italy face the steepest compliance ramps as national procurement offices integrate these rules into tender specifications.
Defense agencies are unbundling sensor hardware from navigation software in acquisition contracts, enabling mixed-vendor architectures. Prime contractors now source inertial measurement units from specialized suppliers while retaining proprietary Kalman filter integration. This pattern is most visible in US Army Futures Command next-generation combat vehicle programs, where modular open systems approaches permit rapid technology insertion without platform redesign.
Tactical Inertial Systems Market Segmentation
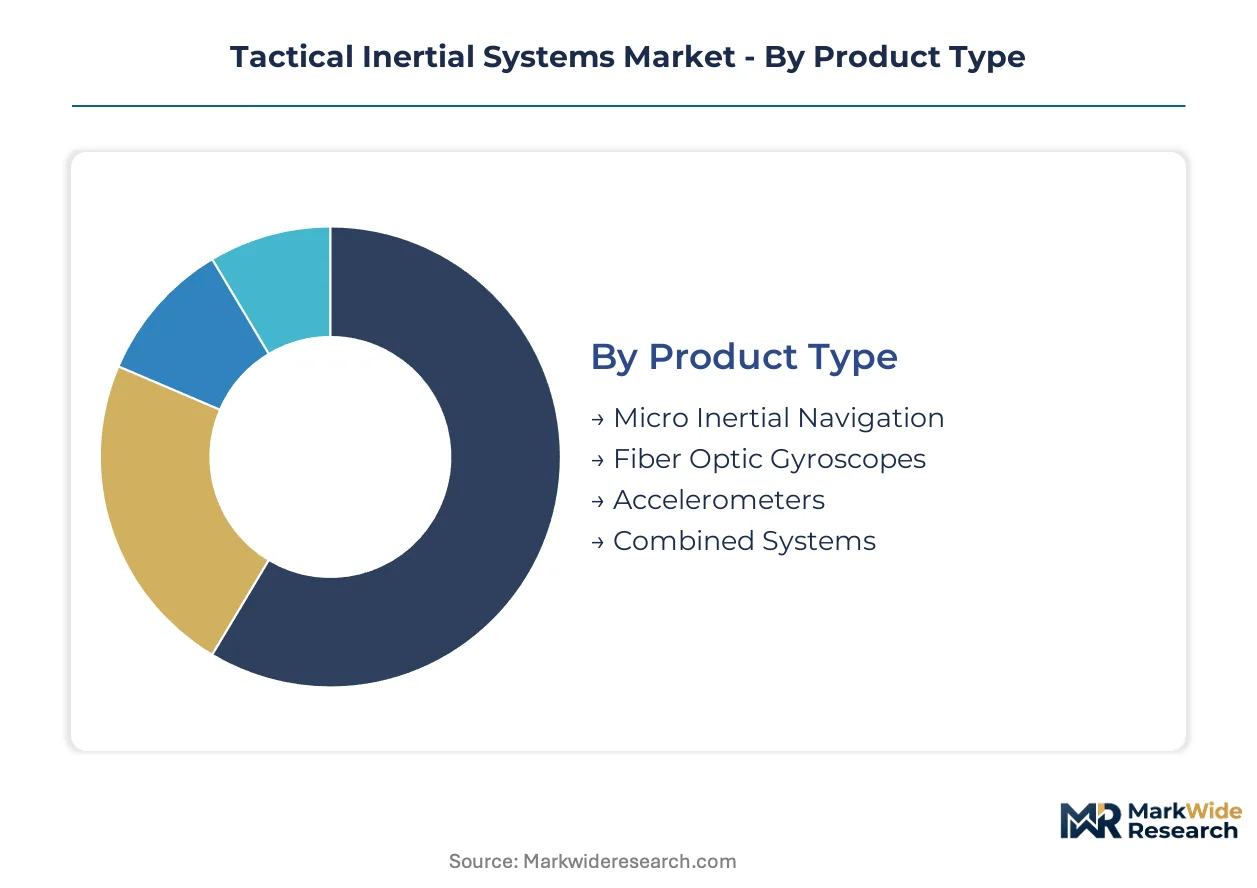
Tactical inertial systems fragment across four intersecting dimensions that determine procurement pathways and supplier positioning. Product type and technology choices lock in performance tiers, while end-user and application splits dictate certification requirements and contract structures.
Product Type:
Domestic US defense procurement dominates fiber optic gyroscope and combined systems demand, while export markets in NATO Europe and Asia-Pacific pull MEMS-based alternatives for cost-constrained platforms.
- Fiber Optic Gyroscopes:Precision rotation sensors using light interference in coiled fiber achieve bias stability below 0.01 degrees per hour. US Army long-range precision fires programs and Navy submarine navigation suites anchor demand, with ITAR restrictions limiting foreign sales to approved allied nations.
- Combined Systems:Integrated inertial measurement units fuse gyroscopes, accelerometers, and processing electronics in single enclosures. Land vehicle programs in Germany and France favor these for rapid platform integration, though thermal cycling validation across minus 40 to plus 71 degrees Celsius extends qualification timelines.
- Micro Inertial Navigation:Compact MEMS-based units for disposable swarming platforms.
- Accelerometers:Linear motion sensors deployed across all platform categories.
Fiber optic gyroscopes hold the largest share; momentum sits with combined systems as NATO standardization drives integrated procurement.
Technology:
Cost tiers separate military-qualified solutions from commercial derivatives, with GPS-aided configurations commanding premium pricing for contested-environment resilience.
- GPS-Aided:Hybrid architectures blending satellite signals with inertial dead reckoning enable seamless degradation when jamming occurs. US DoD PNT resilience mandates accelerate adoption across Army Futures Command programs, with anti-spoofing algorithms now mandatory for new procurements.
- MEMS:Silicon micromachined sensors exploit semiconductor economies of scale. Swarming robotics programs in the United Kingdom and Australia consume volumes previously impossible at tactical-grade precision, though temperature hardening excludes consumer-grade suppliers.
- Ring Laser Gyroscopes:Helium-neon gas laser systems remain entrenched in strategic platforms.
- Tactical Grade:Certification tier denoting bias stability below one degree per hour.
GPS-aided technology holds the largest share; MEMS is climbing the fastest as unit cost thresholds collapse for disposable applications.
End User:
Customer type determines contract duration and technology refresh cadence, with defense agencies driving specifications that cascade into adjacent sectors.
- Defense:National military procurement accounts for platform-integrated navigation suites requiring STANAG certification. US Department of Defense, UK Ministry of Defence, and French Direction Générale de l'Armement dominate volume, with multi-year frameworks locking in supplier relationships.
- Robotics:Autonomous system developers demand miniaturized units for unmanned platforms. US Army Rapid Capabilities and Critical Technologies Office programs and British Army Robotic Platoon Vehicle trials expand addressable volumes beyond traditional manned systems.
- Aerospace:Manned aircraft and missile applications requiring flight-qualified hardware.
- Marine:Naval surface and subsurface platforms with extended mission endurance requirements.
Defense holds the largest share; robotics is gaining share fastest as swarming concepts mature from demonstration to deployment.
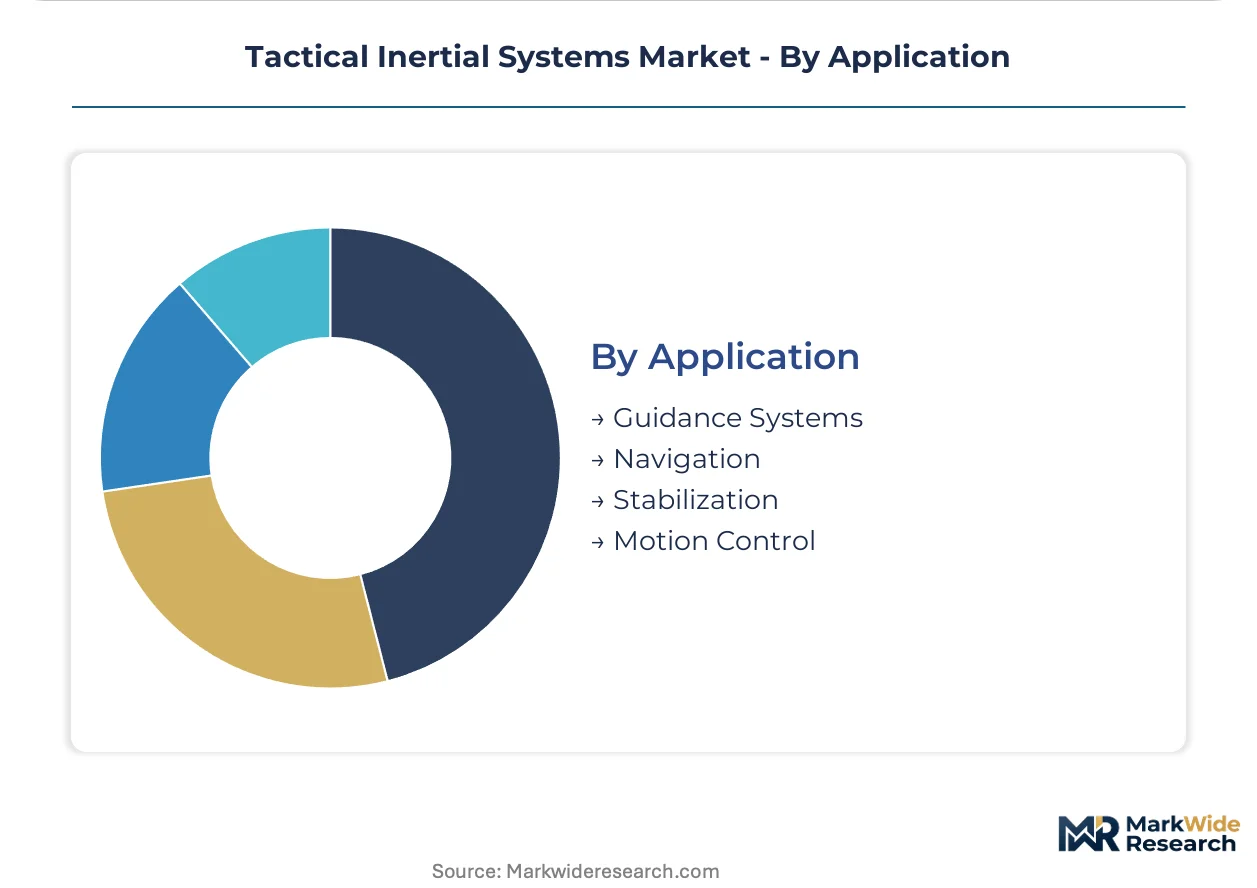
Application:
Functional use case dictates performance specifications and environmental qualification, with guidance systems imposing the most stringent accuracy demands.
- Guidance Systems:Terminal navigation for precision munitions demands drift rates below 0.1 nautical miles per hour. US Navy Conventional Prompt Strike and Army Long-Range Hypersonic Weapon programs concentrate development resources, with live-fire trials at restricted test ranges creating validation bottlenecks.
- Navigation:Continuous position fixing for platform orientation. Submarine inertial navigation suites in France and the United Kingdom require submerged endurance without external fixes, sustaining demand for highest-precision ring laser and fiber optic configurations.
- Stabilization:Platform attitude control for sensor and weapon pointing.
- Motion Control:Closed-loop feedback for autonomous vehicle maneuvering.
Navigation holds the largest share; guidance systems show the steepest expansion trajectory as hypersonic and long-range precision fires programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense contractors export GPS-denied navigation suites to NATO allied procurement programs across Europe and the Asia-Pacific, establishing transatlantic and transpacific supply corridors for tactical-grade inertial systems.
United States
Arizona and Massachusetts defense corridors concentrate prime contractor engineering and testing infrastructure. US DoD PNT resilience mandates accelerate technology refresh cycles for contested-environment navigation. Honeywell International Inc. leverages captive MEMS fabrication capacity in these corridors to supply tactical-grade accelerometers for Army Futures Command programs.
United Kingdom
British Army Robotic Platoon Vehicle trials and Royal Navy submarine navigation suites drive demand for combined inertial measurement units. Ministry of Defence procurement frameworks align with NATO STANAG certification requirements for cross-border platform integration. Defense laboratories in England qualify silicon accelerometer arrays for disposable unmanned aerial platforms.
France
Direction Générale de l'Armement land and naval programs anchor European demand for ring laser gyroscope specialization. EU AI Act algorithmic transparency requirements mandate explainable navigation decision pathways for autonomous platforms. Safran Group maintains vertically integrated production for French and export programs.
Germany
Bundeswehr next-generation combat vehicle programs favor modular open systems approaches for rapid technology insertion. Federal Office of Bundeswehr Equipment mandates thermal cycling validation across military temperature ranges for platform-integrated navigation. Land vehicle programs in Bavaria and Baden-Württemberg drive combined systems procurement for rapid integration timelines.
Australia
Australian Defence Force swarming robotics programs consume MEMS-based micro inertial navigation volumes for cost-constrained disposable platforms. Defence Strategic Review priorities emphasize position-navigation-timing resilience in Indo-Pacific contested environments. Research partnerships between Canberra defense laboratories and US contractors accelerate qualification of silicon micromachined sensors for regional unmanned systems.
Tactical Inertial Systems Market Competitive Landscape
Listed leaders compete with private specialists across defense procurement channels, creating a tiered structure where scale advantages in MEMS fabrication coexist with precision-focused niche positions in fiber optic and ring laser technologies. The vendor base separates into three strategic archetypes: diversified aerospace conglomerates with captive inertial component production, specialized navigation houses with vertically integrated measurement unit assembly, and MEMS-focused suppliers exploiting semiconductor economies of scale. Competitive moves concentrate on strategic partnerships for restricted military test range access and backward integration into specialty fiber coil supply.
Among diversified aerospace conglomerates, Honeywell International Inc. and Northrop Grumman Corporation exemplify scale-driven positions spanning multiple precision tiers. Safran Group anchors European demand through specialized gyroscope production for land and naval platforms. Kearfott Corporation occupies a position within the combined systems segment, representing vertically integrated inertial measurement unit specialists serving prime contractor integration programs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Analog Devices Inc. |
| Kearfott Corporation |
| Rockwell Collins Inc. |
| Northrop Grumman Corporation |
| Collins Aerospace |
| KVH Industries Inc. |
| Safran Group |
| Others |
Value Network & Pricing Analysis
Multi-year framework agreements with take-or-pay clauses lock in supply access for high-purity fiber optic coils while freezing unit pricing visibility for prime contractors across US DoD and NATO procurement channels. Defense agencies in the United States, France, and Germany structure these contracts to bypass spot-market volatility for ring laser gyroscope and MEMS accelerometer inputs.
Pricing Analysis
The technology-generation pricing gap separates current-gen GPS-aided inertial systems from prior-gen standalone configurations and emerging MEMS-based alternatives. Project-based contracting dominates, with price differentiation driven by ITAR certification tier and thermal cycling validation depth. Cost compression in MEMS tiers is intensifying because semiconductor fabrication economies of scale are displacing traditional precision gyroscope cost structures. Swarming robotics programs exhibit highest price sensitivity; submarine navigation suites show least.
Supply Chain Analysis
Specialty fiber coil production concentrates among qualified suppliers in the United States, Japan, and Germany, creating a chokepoint that constrains fiber optic gyroscope output expansion. The supply chain draws from helium-neon gas laser components, silicon wafer substrates, and precision optical assemblies. Single-source vulnerability in ITAR-controlled component categories exposes downstream integrators to export control recalibration risk. Distribution runs through prime contractor integration facilities in Arizona and Massachusetts defense corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through ITAR certification and NATO STANAG compliance creates near-impassable barriers for unqualified suppliers.
For Market Incumbents: Shield proprietary MEMS fabrication capacity through capacity reservation agreements with Arizona-based testing infrastructure. Deepen backward integration into specialty fiber coil supply to offset single-source vulnerability. Lock in long-term framework agreements with Army Futures Command before export control reform discussions conclude. For New Entrants and Emerging Players: NATO STANAG certification fast-tracks offer the most penetrable entry path for European defense procurement participation. Target Australian Defence Force swarming robotics programs where cost-constrained disposable platforms prioritize unit economics over legacy precision. Pursue research partnerships with Canberra defense laboratories as a go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated inertial measurement unit specialists with captive gyroscope production and established prime contractor relationships. Long-term viability hinges on positioning for GPS-denied navigation refresh cycles across the next decade. Watch for ITAR reform finalization as the inflection signal for cross-border supplier eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Fiber Supply | Captive coil production insulates Honeywell and Safran from input bottlenecks in high-purity fiber. |
| NATO STANAG Certification Investment | Pre-certified navigation stacks accelerate French Direction Générale de l'Armement tender participation. |
| MEMS Fabrication Scale-Up | Semiconductor economies of scale enable Kearfott to serve UK swarming robotics volume demands. |
| GPS-Aided Technology Convergence | Seamless degradation architectures align with US DoD PNT resilience mandates for contested environments. |
| Arizona Defense Corridor Co-Location | Proximity to Army Yuma Proving Ground compresses thermal cycling validation timelines for new entrants. |
Research Methodology
Operator-level perspectives from defense procurement officers, inertial systems engineering leads, prime contractor integration specialists, and military test range administrators anchored the qualitative base for this study. Primary interview insights combined with secondary validation from US DoD budget justification documents, NATO STANAG certification registries, EU Defence Fund tender databases, and SEC filings from listed aerospace conglomerates. Bottom-up unit demand estimates and top-down defense budget allocation analysis triangulated market sizing across segments.
Sensitivity analysis tested forecast robustness against ITAR reform scenarios, MEMS cost curve acceleration assumptions, and NATO standardization timeline variations across the projection horizon. Segmentation modeling incorporated product type, technology configuration, end-user category, and application function dimensions. CAGRs derived from defense budget trajectory analysis, platform retirement-replacement cycles, and unmanned systems deployment curves. Industry-specific inputs included PNT resilience mandate implementation schedules and thermal cycling qualification queue depths at restricted test ranges.
Underlying assumptions cover sustained defense budget prioritization for GPS-denied navigation, with deviation risk concentrated in export control recalibration outcomes and specialty fiber supply expansion rates. Forecasts reflect these conditions without claiming predictive certainty. Practitioners should keep alternative scenarios live as ITAR reform negotiations and EU AI Act enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Weapon Locating Radar Market