
 Man-Portable Military Communication Systems Market | 2026-2036
Man-Portable Military Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Man-Portable Military Communication Systems Market Foresight
Market Context with Strategic Players
Defense procurement channels is tilting toward software-defined and modular radio platforms that accommodate rapid waveform upgrades. L3Harris Technologies leverages its dominance in NSA-certified handheld radios to anchor large-scale U.S. Army modernization programs. Thales Group competes across European NATO markets with soldier-borne systems optimized for coalition interoperability. Elbit Systems Ltd. specializes in integrated tactical networking solutions that extend from individual dismounts to vehicle and command echelons.
Technical Definition and Structural Segments
Man-portable military communication systems encompass lightweight, battery-powered transceivers, antennas, and signal processing units designed for individual soldier or small-team carriage, typically operating across HF through UHF bands with output power under 20 watts for low-probability-of-intercept transmission. These systems enable secure voice, data, and video exchange in contested electromagnetic environments where fixed infrastructure is unavailable or compromised. Radios command the largest revenue share within product type segmentation due to embedded encryption and frequency-agile waveform requirements, while mesh networking represents the fastest-expanding technology dimension as militaries field self-healing networks that function without centralized hubs. Satellite communication integration is maturing as a premium capability tier, with margin pools concentrating in terminals that bridge tactical and strategic bandwidth.
Regulatory Framework and Forward Outlook
NSA certification requirements, NATO Standardization Office interoperability mandates, and national spectrum regulators such as FCC in the United States and Ofcom in the United Kingdom constrain product design and market access for non-compliant vendors. Export control regimes including ITAR and EAR further segment competitive participation by restricting technology transfer across allied and non-allied boundaries. Stakeholders must monitor the divergence between U.S. CMMC cybersecurity standards and emerging EU defense procurement certification paths, as compliance fragmentation threatens to bifurcate supplier qualification requirements and reshape competitive positioning in transatlantic markets.
Market Dynamics
Defense procurement is pivoting toward software-defined radio architectures that enable rapid waveform updates without hardware replacement, compressing refresh cycles from decade-long programs to continuous capability insertion.
Growth Catalysts
- Special Operations Forces Modernization:Dismounted soldier connectivity requirements are accelerating fielding of lightweight, multi-band transceivers. Special operations units in the United States and allied NATO forces prioritize man-packable systems with embedded NSA-certified encryption.
- ITAR Reform Discussions:Potential relaxation of certain International Traffic in Arms Regulations categories for allied nations is expanding addressable markets for U.S.-origin tactical radios. This regulatory momentum supports coalition interoperability mandates.
- Mesh Networking Proliferation:Self-healing network architectures eliminate reliance on fixed infrastructure. Military field trials demonstrate operational resilience in contested electromagnetic environments where centralized command nodes face targeting risk.
Market Restraints
- GaN Semiconductor Supply Concentration:Gallium nitride substrates essential for high-efficiency power amplifiers concentrate among limited foundry capacity in East Asia. This geographic supply chokepoint creates vulnerability for radio manufacturers dependent on advanced RF components.
- NSA Certification Timelines:Type-1 encryption module approval processes extend development cycles by 18-36 months. This certification friction delays product commercialization and locks out non-compliant vendors from U.S. defense procurement channels.
- Battery Chemistry Limitations:Lithium-ion energy density constraints impose weight penalties on dismounted soldiers. Alternative solid-state chemistries remain pre-commercial for military temperature and shock specifications.
Strategic Opportunities
- Integrated SATCOM Terminals:Convergence of tactical radio and satellite communication into single man-portable units addresses beyond-line-of-sight gaps. This technology fusion targets expeditionary forces requiring reach-back to strategic networks.
- CMMC 2.0 Implementation:Cybersecurity Maturity Model Certification requirements are creating qualification barriers that favor incumbent suppliers with established compliance infrastructure. Early certification investments yield preferential access to Pentagon modernization programs.
- Australian Defense Spending:The AUKUS security pact is accelerating Australian tactical communications recapitalization. This underpenetrated demand center seeks coalition-interoperable systems compatible with U.S. and U.K. waveform standards.
Industry Challenges
- Software-Defined Radio Talent Scarcity:FPGA programming and waveform development expertise concentrates among defense contractors with decades of classified program experience. This skill gap limits new market entrants.
- Legacy System Integration Complexity:Fielded SINCGARS and PRC-152 inventories impose backward compatibility requirements that constrain architectural innovation. Radio manufacturers must maintain multi-generation interoperability.
- Counter-Electronic Warfare Adaptation:Near-peer adversary jamming capabilities are forcing rapid firmware update cycles. Sustaining engineering costs escalate as threat signatures evolve faster than traditional acquisition timelines permit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Man-Portable Military Communication Systems Market |
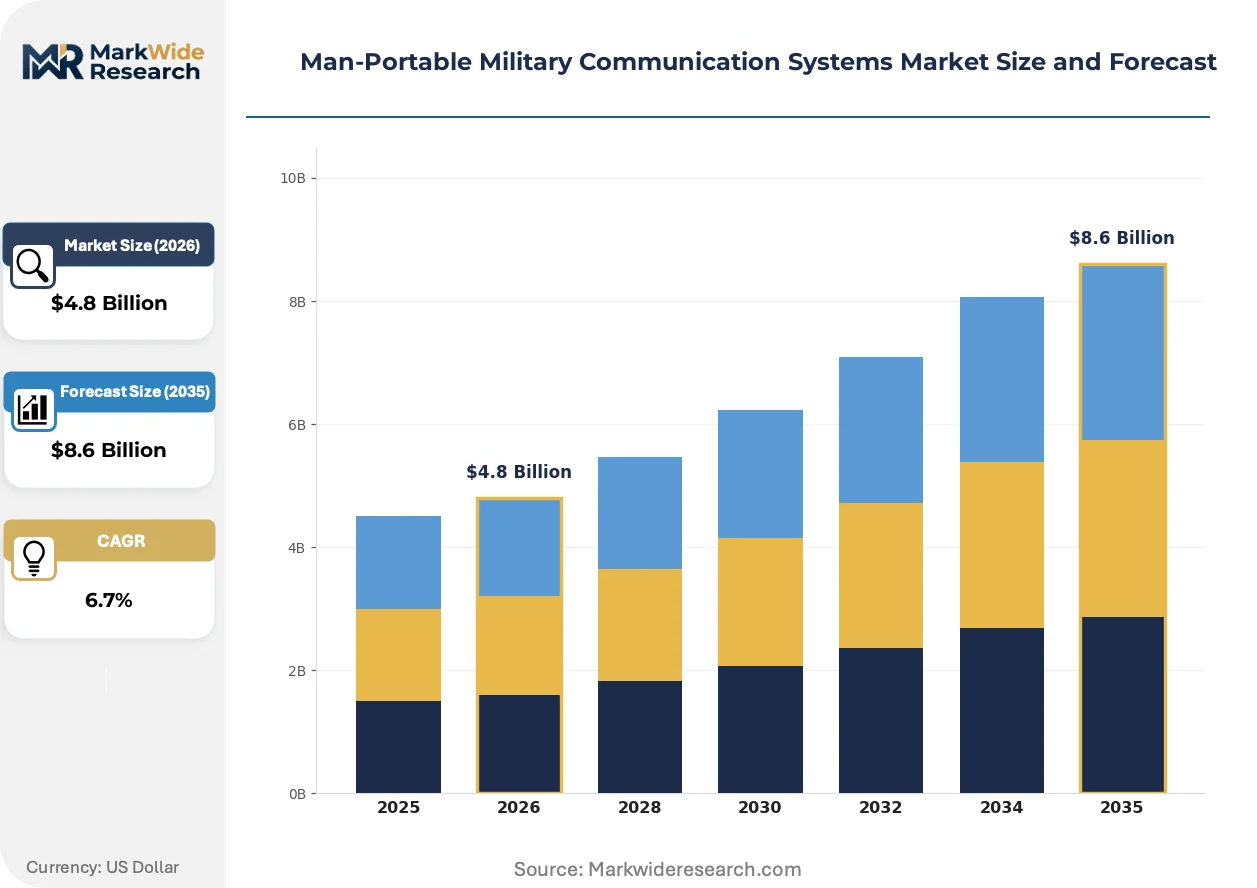
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radios, Antennas, Accessories, Signal Processing Units Technology: Frequency Hopping, Satellite Communication, Mesh Networking, VoIP End User: Military, Law Enforcement, Private Security, Emergency Services Deployment: On-Field, Training Camps, Operations Centers, Mobile Units |
| Companies Covered | L3Harris Technologies, Inc., General Dynamics Corporation, Raytheon Technologies Corporation, Thales Group, Elbit Systems Ltd., BAE Systems, Rockwell Collins, SAAB AB, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Man-Portable Military Communication Systems Market Shifts & Advancements
Radio architectures are abandoning fixed-function hardware for reprogrammable platforms, while procurement models compress vendor selection cycles and regulatory frameworks fragment across allied defense markets.
Software-defined radio technology is migrating from specialized military applications to standard procurement specifications. Defense ministries in NATO member states now mandate waveform reprogrammability as a baseline requirement. This migration is collapsing the distinction between hardware procurement and software sustainment, forcing traditional radio manufacturers to build continuous delivery capabilities.
CMMC cybersecurity standards in the United States are diverging from emerging EU defense procurement certification paths. This regulatory fragmentation is bifurcating supplier qualification requirements. Transatlantic vendors must maintain parallel compliance infrastructures, raising barriers for mid-tier competitors without dedicated regulatory affairs capacity.
Defense acquisition offices are compressing vendor evaluation cycles from multi-year source selections to rapid prototyping competitions. Program offices in the U.S. Army and Marine Corps now prioritize commercially derived solutions with military hardening. This behavioral shift is visible in special operations commands, where soldier feedback from combat evaluations directly shapes production commitments.
Man-Portable Military Communication Systems Market Segmentation
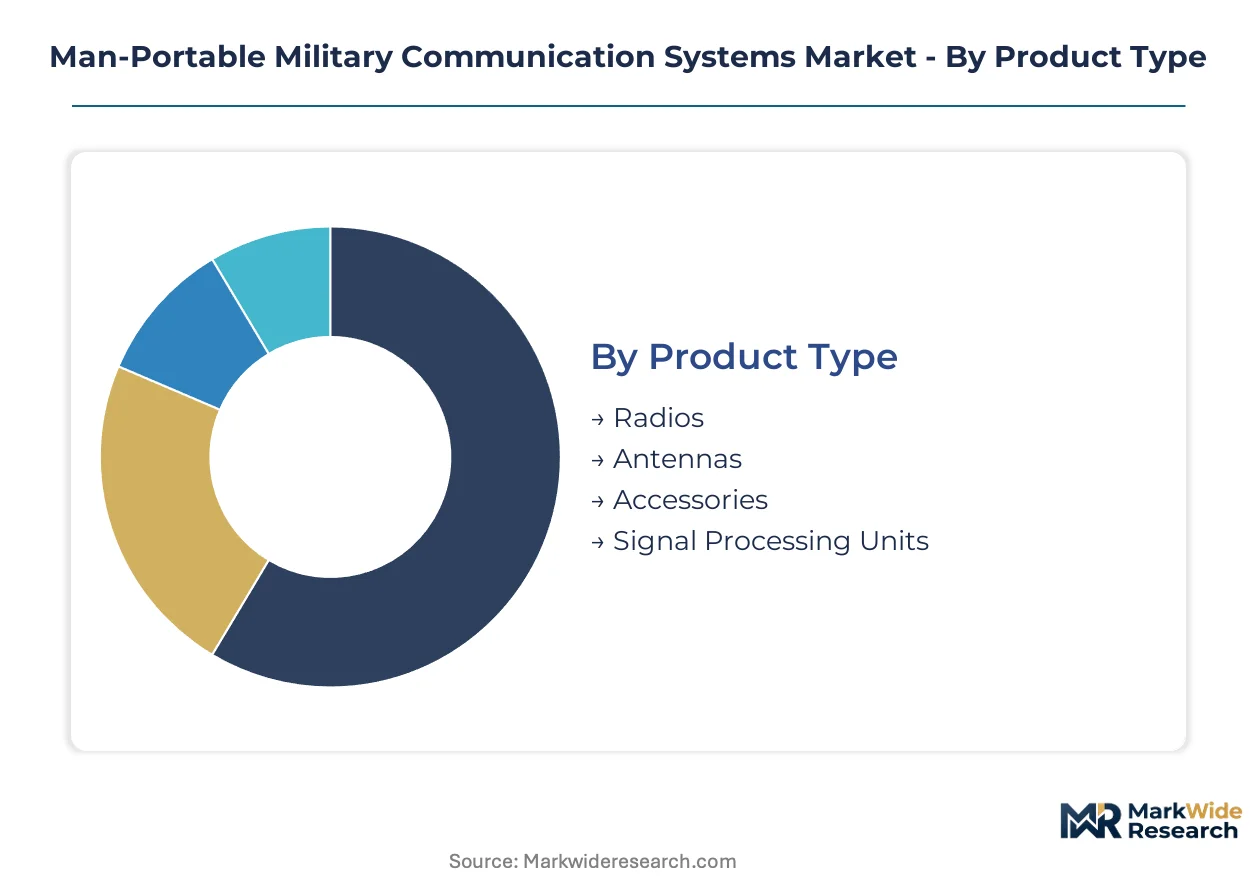
Segmentation in man-portable military communication systems reveals how procurement specifications diverge across operational environments and threat profiles. Technical requirements for dismounted special operations forces differ materially from those governing static command nodes or coalition interoperability mandates.
Product Type:
Mature hardware categories dominate procurement volumes while emerging subsystems reshape upgrade economics.
- Radios:Software-defined transceivers with embedded NSA-certified encryption modules form the procurement core. U.S. Army modernization programs concentrate demand in multi-band handheld units capable of rapid waveform reprogramming without hardware replacement.
- Antennas:Compact broadband designs with adaptive impedance matching enable frequency-agile operation across HF through UHF bands. Special operations forces drive demand for low-observable configurations that minimize electromagnetic signature detection risk.
- Accessories:Battery packs, carrying harnesses, and peripheral interfaces complete system integration.
- Signal Processing Units:FPGA-based modules execute waveform modulation and demodulation algorithms in real-time.
Radios retain volume leadership; signal processing units hold the steepest expansion curve.
Technology:
Cost tier differentiation separates baseline connectivity from premium beyond-line-of-sight capabilities.
- Frequency Hopping:Rapid pseudorandom channel switching at thousands of hops per second provides resistance against narrowband jamming. Legacy SINCGARS interoperability requirements sustain demand across NATO ground forces despite waveform obsolescence pressures.
- Satellite Communication:Compact terminals bridging tactical radio networks to strategic bandwidth represent the highest-margin capability tier. Expeditionary forces in the United States and United Kingdom prioritize man-packable terminals for reach-back in denied-area operations.
- Mesh Networking:Self-healing architectures eliminate single points of failure through distributed routing protocols.
- VoIP:Packetized voice transmission over tactical data networks enables bandwidth-efficient communications.
Frequency hopping sustains installed-base dominance; satellite communication commands premium pricing expansion.
End User:
Application intensity varies sharply between combat-deployed units and support organizations.
- Military:Ground combat forces, aviation units, and naval expeditionary elements constitute the primary demand center. Department of Defense procurement channels prioritize dismounted soldier connectivity with NSA Type-1 encryption for classified traffic.
- Law Enforcement:Tactical response teams and border security agencies require interoperable communications with military standards. FBI Hostage Rescue Team and similar units drive demand for hardened equipment without full export control restrictions.
- Private Security:Government-contracted protective services operate in contingency environments requiring military-grade reliability.
- Emergency Services:Disaster response and search-and-rescue organizations seek surge interoperability with military networks.
Military end users anchor procurement volumes; law enforcement represents the fastest-climbing adjacent segment.
Deployment:
Geographic dispersion of operational nodes determines infrastructure dependence and equipment portability requirements.
- On-Field:Dismounted patrols and forward observation posts operate without fixed infrastructure support. Contested electromagnetic environments in Eastern Europe and the Indo-Pacific drive demand for low-probability-of-intercept transmission modes.
- Training Camps:Garrison and simulation facilities require high-fidelity replication of operational waveform environments. U.S. Army Combat Training Centers sustain demand for interoperable equipment inventories that mirror deployed configurations.
- Operations Centers:Static command nodes integrate man-portable systems as backup and surge capacity.
- Mobile Units:Vehicle-mounted and dismountable configurations bridge mounted and dismounted operations.
On-field deployment commands equipment procurement priority; training camps sustain replacement cycle volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Department of Defense modernization programs are concentrating procurement authority in Washington, while allied governments accelerate parallel recapitalization efforts. Spectrum regulators in multiple jurisdictions impose divergent certification timelines that reshape supplier market access. Industrial clusters in defense technology hubs sustain concentrated engineering capacity for tactical radio development.
United States
Pentagon procurement channels prioritize NSA Type-1 encryption modules for dismounted soldier connectivity. CMMC 2.0 cybersecurity standards create compliance barriers that favor established defense contractors with classified infrastructure. The Baltimore-Washington corridor anchors concentrated engineering talent for software-defined radio development.
United Kingdom
Ministry of Defence modernization programs emphasize coalition interoperability with U.S. waveform standards. Strategic Command directives accelerate fielding of man-packable satellite communication terminals for expeditionary forces. Defence Science and Technology Laboratory facilities in Wiltshire drive prototype-to-production pipelines for tactical networking.
Germany
Bundeswehr special operations forces drive demand for lightweight multi-band transceivers with embedded encryption. Federal Office for Information Security certification requirements extend product qualification timelines for foreign suppliers. Defense industrial clusters in Bavaria and Baden-Württemberg maintain RF component manufacturing capacity.
Australia
AUKUS security pact commitments are accelerating tactical communications recapitalization across Australian Defence Force branches. Defence Strategic Review procurement reforms compress vendor selection cycles for coalition-compatible systems. Technology corridors in Canberra and Adelaide concentrate systems integration capabilities for dismounted soldier networks.
Israel
Israel Defense Forces operational requirements prioritize low-probability-of-intercept transmission modes for contested electromagnetic environments. Ministry of Defense export control administration maintains strict technology transfer oversight for tactical radio platforms. Defense technology clusters around Tel Aviv sustain specialized waveform development expertise.
Man-Portable Military Communication Systems Market Competitive Landscape
On the supply side, the industry is consolidating around defense contractors with decades of classified program experience and established NSA certification infrastructure. Tiered competitive dynamics separate prime integrators with platform-level contracts from subsystem specialists focused on encryption modules or antenna technologies. Two dominant competitive moves are reshaping positioning: strategic partnerships for coalition interoperability certification and vertical integration into GaN semiconductor fabrication to secure power amplifier supply.
Within the prime integrator tier, L3Harris Technologies, Inc. and General Dynamics Corporation exemplify contractors with sustained access to Pentagon modernization programs. Thales Group occupies a position bridging European NATO markets with U.S. interoperability requirements. These three entities represent the archetype of vendors capable of absorbing 18-36 month NSA certification timelines while maintaining continuous engineering investment.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| General Dynamics Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| Elbit Systems Ltd. |
| BAE Systems |
| Rockwell Collins |
| SAAB AB |
| Lockheed Martin |
| Others |
Supply & Pricing Matrix
The Trans-Pacific freight corridor from Yokohama to Long Beach anchors cost dynamics for GaN semiconductor substrates, concentrating supply-side leverage among East Asian foundries while downstream price differentiation separates NSA-certified encryption modules from commercial-grade alternatives.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with Type-1 NSA encryption modules commanding substantial premiums over commercial AES variants. Three-tier pricing structure across certified-military, dual-use, and commercial levels reflects waveform reprogrammability and embedded security architecture. Cost compression in the commercial tier is intensifying because software-defined radio commoditization erodes hardware margins. Special operations procurement units demonstrate lowest price sensitivity, prioritizing low-probability-of-intercept performance over unit economics.
Supply Chain Analysis
Extended payment terms from prime integrators to GaN substrate suppliers compress working capital cycles throughout the RF component tier. Manufacturing concentrates in Japan, Taiwan, and South Korea for high-efficiency power amplifiers, while final assembly draws from U.S. and Israeli defense industrial bases. Gallium nitride wafers, lithium-ion cells, and FPGA chipsets constitute critical input dependencies. Single-source vulnerability in East Asian foundry capacity threatens production continuity. Distribution runs through classified defense procurement channels with ITAR-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
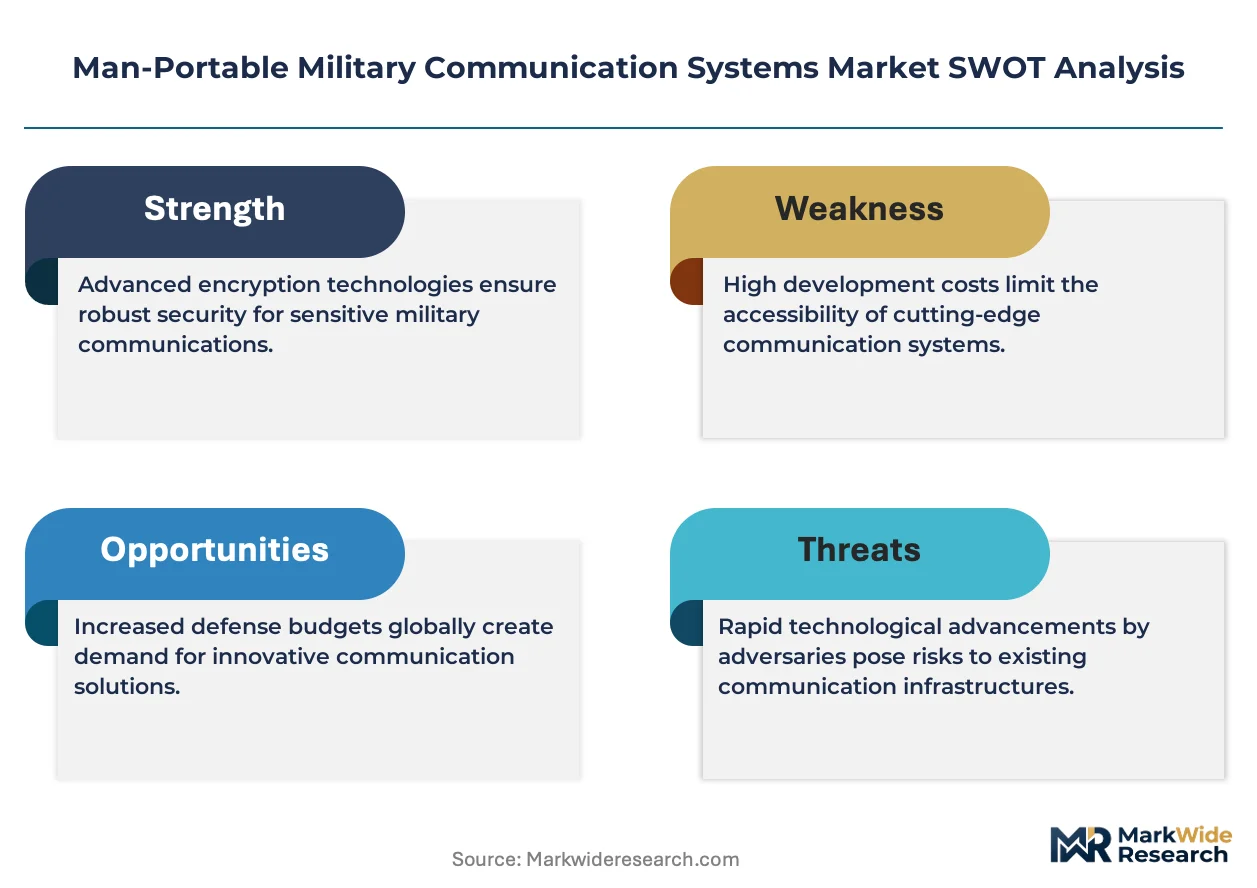
Incumbents must defend against software-defined radio commoditization as open-source waveform architectures threaten proprietary encryption value. Commercial technology adaptation poses the most credible substitution threat to traditional hardware-centric business models.
For Market Incumbents: Pre-empt open-source waveform displacement by accelerating proprietary encryption integration into modular radio platforms. Backward integration into GaN semiconductor fabrication secures power amplifier supply against East Asian foundry concentration. NSA certification infrastructure represents the most defensible moat against commercial technology encroachment. For New Entrants and Emerging Players: Australian Defence Force recapitalization under AUKUS commitments offers the most penetrable demand center for coalition-interoperable systems. Law enforcement tactical units present adjacent white-space with reduced export control barriers. SATCOM terminal miniaturization for expeditionary forces provides the strongest go-to-market angle for differentiated positioning. For Investors and Strategic Acquirers: Waveform development boutiques with classified program experience represent the highest-conviction acquisition archetype for capability consolidation. Long-term viability rests on sustained defense modernization budgets and software-defined architecture transition timelines. CMMC 2.0 certification backlog serves as the critical inflection signal for supplier qualification capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| NSA Type-1 Certification Investment | Locks in Pentagon procurement channel access for dismounted soldier radio programs. |
| GaN Fabrication Backward Integration | Captive supply of power amplifiers insulates against East Asian foundry chokepoints. |
| AUKUS Interoperability Partnership | Waveform standard alignment opens Australian Defence Force recapitalization contracts. |
| Mesh Networking Firmware Development | Self-healing protocol expertise differentiates bids for special operations modernization. |
| CMMC 2.0 Compliance Infrastructure | Cybersecurity maturity certification qualifies vendors for Army Futures Command programs. |
Research Methodology
A standing panel of program executive officers, tactical radio procurement leads, NSA certification engineers, and special operations communications officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with defense acquisition stakeholders and secondary validation against Pentagon budget justification documents, NATO Standardization Office technical standards, and FCC spectrum allocation filings. Bottom-up equipment procurement forecasts triangulated against top-down defense spending projections across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, technology tier, end-user segment, and deployment environment dimensions. CAGRs derived from equipment refresh cycle analysis and threat-driven modernization urgency. Forecast inputs incorporated GaN semiconductor supply constraints, NSA certification queue lengths, and AUKUS procurement acceleration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by commercial technology adaptors or open-source waveform consortia would shift outcomes. Macroeconomic defense budget contraction, ITAR regime tightening, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market