
 Global Composites in the Aerospace Interior Market | 2026-2036
Global Composites in the Aerospace Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Global Composites in the Aerospace Interior Market Analysis
The EU Green Deal's aviation decarbonization targets is expanding pressure on OEMs to reduce cabin weight. Hexcel Corporation leverages its carbon fiber prepreg portfolio to anchor supply relationships with tier-one seat manufacturers. Toray Industries, Inc. sustains leadership in PAN-based carbon fiber throughput for overhead bin applications. Solvay differentiates through high-performance thermoplastic resin systems that meet stringent smoke-toxicity protocols.
Composites in aerospace interiors comprise fiber-reinforced polymer matrices—typically carbon, glass, or aramid fibers embedded in epoxy, phenolic, or thermoplastic resins—engineered to achieve specific strength-to-weight ratios, fire resistance, and acoustic damping properties. These materials replace traditional aluminum and thermoset components to reduce aircraft empty weight and improve fuel efficiency. Thermoplastics within the product type category represent the fastest-expanding segment due to recyclability and shorter processing cycles that compress manufacturing lead times. Seat components dominate application-level demand, though cabin liners capture disproportionate margin pools where custom fire-rated laminates command specification premiums. Commercial aviation end users absorb the majority of volume, while business jets generate higher per-unit value through bespoke interior configurations.
FAA flammability standards under 14 CFR 25.853 and EASA CS-25 certification requirements directly determine which resin systems and fiber architectures gain airworthiness approval for interior applications. REACH restrictions on halogenated flame retardants and the EU AI Act's emerging material traceability mandates are reshaping supplier qualification protocols. ISO 9001 and AS9100 quality frameworks govern manufacturing stage compliance across processing, molding, and finishing operations. Stakeholders must monitor regulatory divergence between FAA and EASA on sustainable aviation material credits, as this will determine which fiber-recycling technologies achieve commercial scale first.
Market Dynamics
Carbon fiber thermoplastic prepregs are absorbing capital flows from legacy thermoset systems as narrow-body OEMs compress seat component lead times by half.
Growth Catalysts
- EU Green Deal aviation decarbonization mandates:OEMs face binding cabin weight reduction targets that accelerate composite substitution for aluminum interior panels.
- China's COMAC supply chain localization:Tier-one seat manufacturers are qualifying domestic prepreg sources to satisfy domestic content thresholds for C919 deliveries.
- Thermoplastic resin systems:Recyclability and out-of-autoclave processing are compressing manufacturing cycles for overhead bin applications.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs swing with oil-indexed feedstock contracts, squeezing carbon fiber margin structures.
- Japanese carbon fiber supply concentration:Three producers control over seventy percent of aerospace-grade tow capacity, creating single-source vulnerability.
- REACH halogenated flame retardant restrictions:Phosphorus-based alternatives require two-year requalification timelines that freeze specification decisions.
Strategic Opportunities
- India MRO hub expansion:Bangalore and Hyderabad maintenance facilities are retrofitting narrow-body fleets with lightweight interior kits for fuel efficiency gains.
- Cabin air quality certification convergence:EASA and FAA harmonization on smoke-toxicity testing protocols opens dual-approval pathways for phenolic resin laminates.
- Digital twin integration with thermoplastic welding:Real-time process control is enabling zero-defect production of complex seat frames without mechanical fasteners.
Industry Challenges
- Certification engineer scarcity:FAA DER and EASA DOA qualification holders command premium salaries that strain mid-tier supplier staffing.
- Autoclave capacity bottlenecks:Large-diameter pressure vessels for fuselage barrel sections are crowding out interior component curing schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Composites in the Aerospace Interior Market |
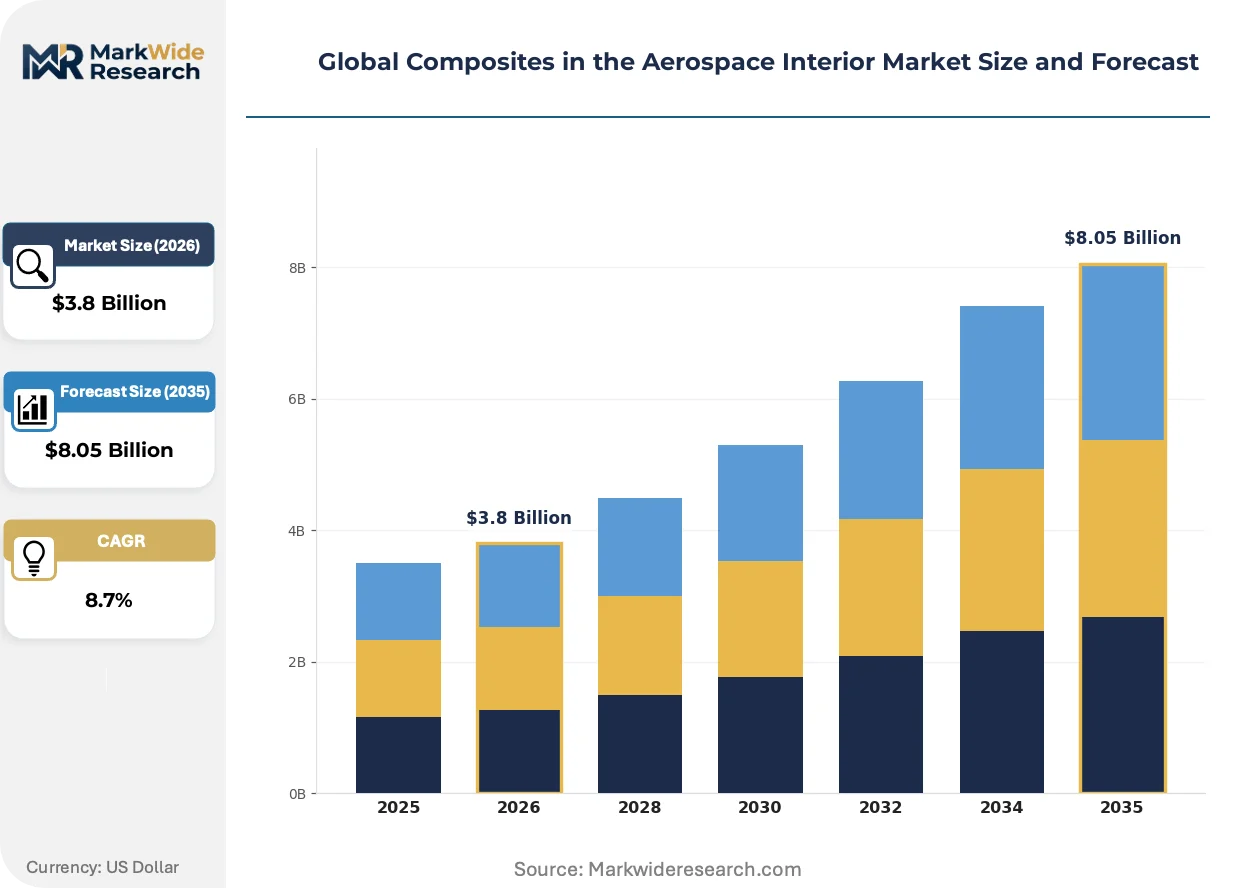
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Reinforced Plastics, Carbon Fiber, Glass Fiber Application: Seat Components, Cabin Liners, Overhead Bins, Paneling End User: Commercial Aviation, Business Jets, Helicopters, Military Aircraft Manufacturing Stage: Processing, Molding, Assembly, Finishing |
| Companies Covered | Hexcel Corporation, Toray Industries, Inc., Solvay, Mitsubishi Chemical Group Corporation, Spirit AeroSystems, SGL Carbon, Teijin Limited, Collins Aerospace, FDC Composites Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Composites in the Aerospace Interior Market Emerging Trajectories
Thermoplastic composites are rewriting process economics while regulatory pressure on cabin emissions intensifies material performance requirements.
Continuous fiber-reinforced thermoplastic (CFRTP) laminates are absorbing design responsibility from thermoset sandwich panels in sidewall and ceiling applications. Airbus and Boeing seat suppliers are trialing PEEK and PPS matrix systems for clip and bracket components to eliminate adhesive bonding steps. The shift is absorbing inventory carrying costs by enabling just-in-time welding rather than refrigerated prepreg storage.
REACH restrictions on halogenated flame retardants are forcing reformulation of legacy phenolic and epoxy systems used in cabin liners. Solvay and Huntsman have introduced phosphorus-nitrogen hybrid chemistries that maintain 60-second vertical burn compliance under 14 CFR 25.853. European seat manufacturers are absorbing eighteen-month requalification costs ahead of anticipated EASA mandate expansion.
Airline procurement teams are consolidating interior retrofit specifications across mixed fleets to compress supplier qualification overhead. Lufthansa Technik and ST Engineering are mandating common material datasets for A320 and 737 cabin modifications, displacing bespoke MRO kitting. The standardization is most visible in Southeast Asian maintenance hubs where third-party lessor requirements dominate specification decisions.
Global Composites in the Aerospace Interior Market Segmentation
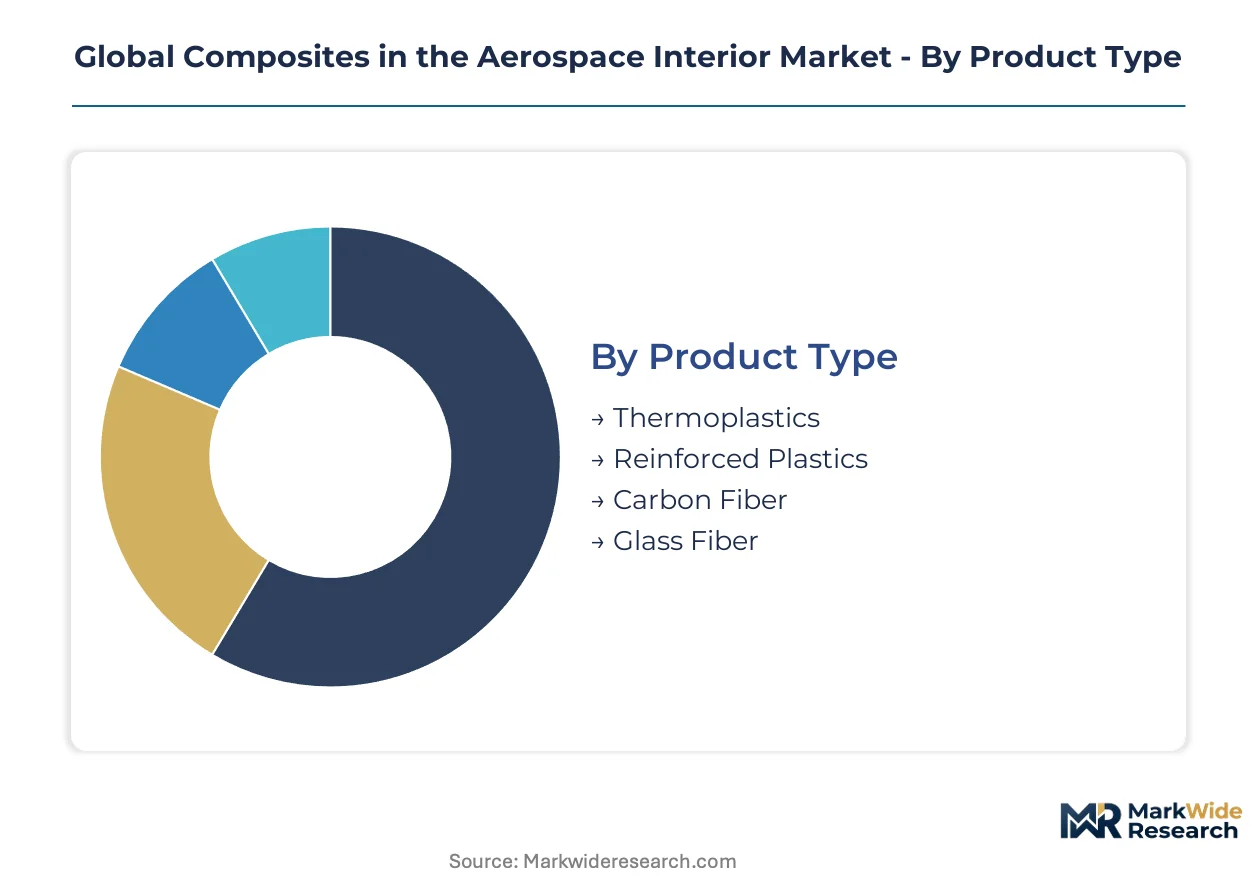
Material selection in aerospace interiors hinges on fire certification pathways and processing economics. Specification decisions cascade across seat architectures, cabin liner assemblies, and MRO retrofit programs. Each segmentation axis reveals distinct margin structures and supplier qualification barriers.
Product Type:
Resin chemistry and fiber architecture determine flammability compliance, recyclability, and autoclave throughput. Thermoplastic matrices are displacing legacy thermosets where out-of-autoclave processing compresses lead times.
- Thermoplastics:PEEK and PPS matrix systems enable fusion bonding without adhesive curing cycles. Airbus A350 seat suppliers in Germany and France are qualifying welded bracket geometries that eliminate mechanical fasteners. EASA smoke-toxicity protocols under CS-25 are accelerating phosphorus-nitrogen flame retardant formulations in this category.
- Carbon Fiber:PAN-based tow architectures deliver maximum stiffness-to-weight for overhead bin frames. Japanese suppliers control aerospace-grade precursor capacity, creating single-source exposure for tier-one laminators in Italy and Spain. REACH halogen restrictions are forcing resin reformulation without sacrificing 60-second vertical burn performance.
- Reinforced Plastics:Glass-polyester hybrids serve cost-sensitive cabin liner applications where stiffness requirements moderate. Indian MRO facilities in Bangalore specify these materials for narrow-body retrofit kits.
- Glass Fiber:E-glass and S-glass rovings dominate sidewall panel cores where dielectric properties matter. Chinese COMAC C919 interior suppliers are qualifying domestic glass fiber sources to satisfy local content mandates.
Mature deployment sits with glass fiber in sidewall applications. Newer deployment is concentrated in thermoplastic seat structures where welding automation reduces touch labor.
Application:
Component geometry and fire exposure zones dictate fiber architecture and resin selection. Seat frames face the most stringent 14 CFR 25.853 testing protocols.
- Seat Components:Structural frames, back shells, and tray tables absorb the highest composite penetration rates. PPS-based clips from Solvay are replacing aluminum in Recaro and Safran seat assemblies. FAA flammability certification for these parts requires full-scale oil burner testing that extends qualification timelines.
- Cabin Liners:Sidewall and ceiling panels command specification premiums where custom fire-rated laminates differentiate suppliers. Lufthansa Technik mandates common material datasets across A320 and 737 mixed fleets, compressing bespoke kitting margins.
- Overhead Bins:Stowage compartment shells prioritize acoustic damping and impact resistance. Toray carbon fiber prepregs anchor supply relationships with Korean and Japanese bin manufacturers serving Boeing programs.
- Paneling:Floor and partition panels balance weight reduction with durability under passenger loading cycles. Hexcel thermoplastic prepregs are penetrating this segment through tier-one distributor relationships in the US and UK.
Volume concentration rests with seat components across narrow-body production lines. Margin expansion is concentrating in cabin liners where custom laminate specifications resist commoditization.
End User:
Procurement scale and customization depth vary sharply across aviation segments. Commercial programs prioritize commonality; business aviation demands bespoke interior configurations.
- Commercial Aviation:Narrow-body OEMs drive thermoplastic adoption through compressed seat lead time targets. Airbus and Boeing tier-one suppliers in Mexico and Poland are scaling PEEK welding cells for A320 and 737 programs.
- Business Jets:Gulfstream and Dassault cabin completions specify ultra-lightweight carbon fiber for premium interior zones. Per-unit material values exceed commercial equivalents by multiples due to low-volume custom fabrication.
- Helicopters:Rotorcraft interiors prioritize impact resistance and corrosion immunity in marine environments. AgustaWestland and Airbus Helicopters programs in Italy and France specify glass-phenolic laminates for cabin shells.
- Military Aircraft:Defense procurement emphasizes ballistic protection and electromagnetic shielding in addition to flammability compliance. Lockheed Martin C-130 and Airbus A400M programs absorb specialized prepreg formulations with extended qualification cycles.
Procurement scale peaks with commercial aviation. Value capture per airframe climbs fastest in business jet completions where interior customization commands specification premiums.
Manufacturing Stage:
Process control requirements intensify through the value chain from raw material conversion to finished component certification. Each stage carries distinct capital intensity and quality system mandates.
- Processing:Prepreg slitting, kitting, and freezer storage govern material traceability under AS9100. Automated cutting tables at GKN and Spirit AeroSystems facilities in the US and UK reduce fiber waste and layup variability.
- Molding:Autoclave and out-of-autoclave consolidation determines void content and mechanical properties. Compression molding of thermoplastic organosheets is displacing thermoset autoclave cycles in seat frame production.
- Assembly:Adhesive bonding, mechanical fastening, and thermoplastic welding integrate subcomponents. Real-time process monitoring via digital twin integration is enabling zero-defect welding without NDT bottlenecks.
- Finishing:Surface preparation, coating application, and final inspection precede airworthiness release. REACH restrictions on solvent-based primers are forcing waterborne system qualifications that extend curing schedules.
Capital intensity concentrates in molding stage autoclave capacity. Process innovation is accelerating fastest in assembly stage thermoplastic welding where cycle time compression rewards automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of aerospace-grade composite interiors, yet Japanese and German suppliers control critical carbon fiber precursor capacity. China's COMAC program is redrawing sourcing maps through domestic qualification mandates.
United States
Boeing's 737 and 787 production lines in Washington and South Carolina absorb thermoplastic seat structures from tier-one distributors. FAA flammability standards under 14 CFR 25.853 govern resin system approvals for cabin applications. Wichita's Spirit AeroSystems facility anchors composite panel fabrication for narrow-body programs.
China
COMAC's C919 deliveries are forcing tier-one seat manufacturers to qualify domestic prepreg sources for local content thresholds. MIIT industrial guidance prioritizes carbon fiber self-sufficiency under dual carbon goals. Shanghai and Xi'an house the primary interior component qualification labs serving the C919 supply chain.
Germany
Airbus A350 and A320 seat suppliers in Hamburg and Toulouse-source PEEK welding systems for clip and bracket components. EU Green Deal aviation decarbonization mandates bind OEMs to cabin weight reduction targets. Bavaria's composite research clusters coordinate EASA smoke-toxicity protocol development with Frankfurt certification authorities.
Japan
Toray Industries and Teijin Limited control over seventy percent of aerospace-grade PAN-based carbon fiber capacity. METI industrial policy supports precursor plant expansion for narrow-body OEM demand. Nagoya's aerospace corridor concentrates prepreg slitting and kitting operations serving Boeing and Airbus tier-one contracts.
India
Bangalore and Hyderabad MRO facilities are retrofitting narrow-body fleets with lightweight interior kits for fuel efficiency gains. BIS standards alignment with EASA protocols accelerates material qualification timelines. Gujarat's emerging composite parks target tier-two supplier status for global seat manufacturers.
Global Composites in the Aerospace Interior Market Vendor Landscape
The competitive structure tilts toward precursor-controlled specialists with locked-in OEM relationships. Three Japanese carbon fiber producers dominate aerospace-grade tow capacity, creating tiered access for laminators and seat integrators. Strategic archetypes include PAN-precursor specialists, thermoplastic resin formulators, and tier-one aerostructures integrators. Capacity expansion and EASA/FAA dual-qualification partnerships represent the dominant competitive moves.
Among Japanese precursor specialists, Toray Industries, Inc. and Teijin Limited exemplify the capacity-constrained tier where aerospace-grade tow output determines downstream access. Solvay occupies a position among European resin formulators leveraging phosphorus-nitrogen hybrid chemistries for smoke-toxicity compliance. These anchors represent distinct qualification pathways: precursor control versus resin system innovation.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries, Inc. |
| Solvay |
| Mitsubishi Chemical Group Corporation |
| Spirit AeroSystems |
| SGL Carbon |
| Teijin Limited |
| Collins Aerospace |
| FDC Composites Inc. |
| Others |
Supply Flow & Price Mechanics
Captive precursor production in Japan anchors both supply security and pricing power for aerospace-grade carbon fiber, locking tier-one laminators into long-term offtake structures that resist spot-market volatility. This integration choice concentrates margin capture upstream while forcing seat manufacturers to absorb pass-through costs from PAN-based tow suppliers.
Pricing Analysis
Margin tightening in thermoplastic seat components reflects compressed OEM lead-time targets and REACH-driven resin reformulation costs. Three-tier pricing structure across aerospace-certified, commercial-grade, and MRO retrofit tiers separates EASA dual-qualified laminates from single-approval alternatives. Cost-down pressure on glass-polyester cabin liners accelerates because Indian MRO hubs consolidate specifications across mixed fleets. Commercial aviation procurement teams exhibit highest price sensitivity; business jet completion centers show lowest.
Supply Chain Analysis
MIIT domestic-content mandates for COMAC C919 deliveries are reshaping sourcing, forcing tier-one seat manufacturers to qualify Chinese prepreg sources against established Japanese suppliers. Aerospace-grade carbon fiber concentrates in Japan, Germany, and the United States; thermoplastic resin systems draw from Belgium, Switzerland, and US specialty chemical corridors. Raw material dependencies rest on acrylonitrile feedstocks, PEEK polymer pellets, and phosphorus-nitrogen flame retardant additives. Single-source vulnerability from Japanese PAN precursor concentration creates structural risk. Distribution runs through tier-one aerostructures integrators with locked-in OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around precursor-controlled specialists as REACH requalification timelines and certification engineer scarcity force sub-scale laminators toward exit or acquisition.
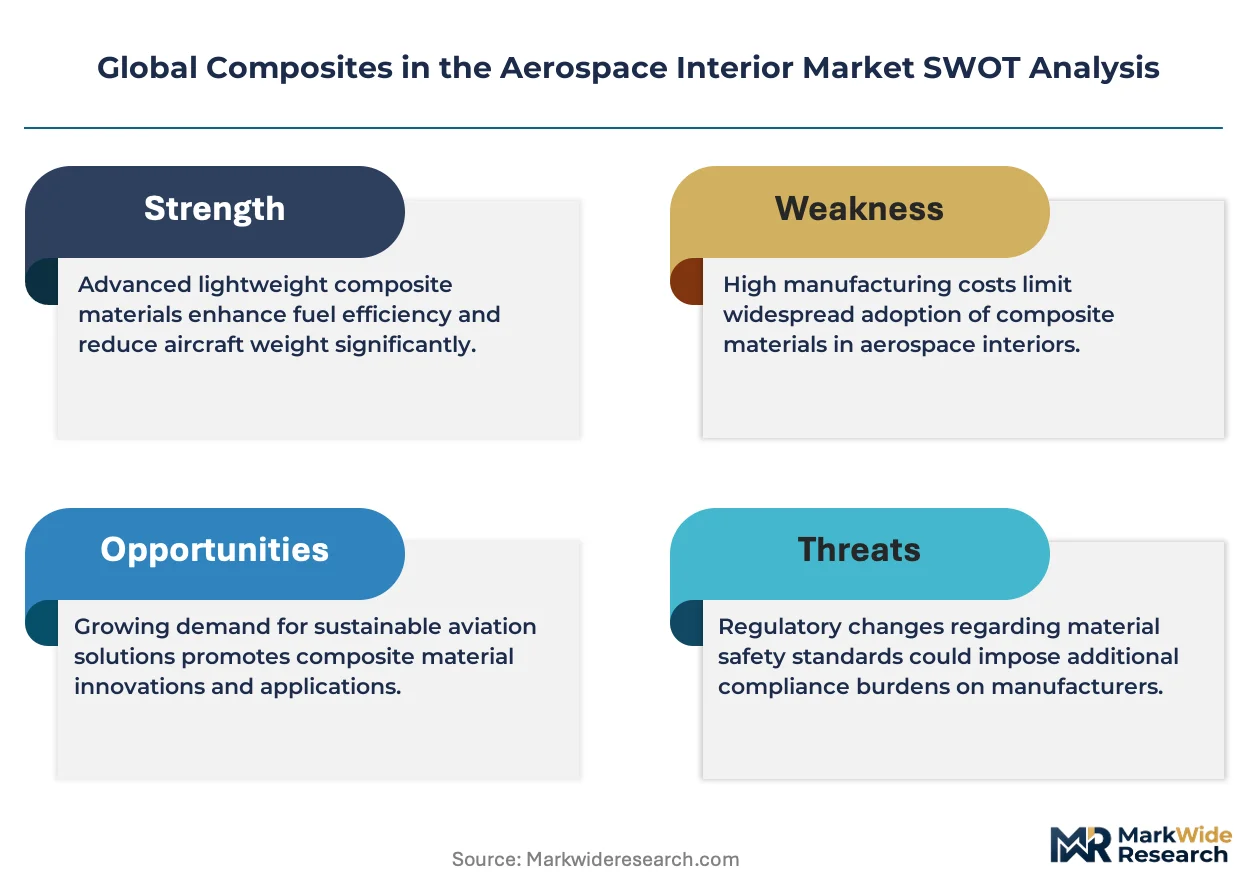
For Market Incumbents: Anchor supply relationships through backward integration into PAN precursor capacity or long-term offtake agreements with Toray and Teijin. Defend against thermoplastic welding automation by investing in digital twin process control for zero-defect production. Prioritize EASA-FAA dual-qualification partnerships to capture narrow-body OEM specification decisions before requalification windows close. For New Entrants and Emerging Players: Begin with glass-polyester cabin liner supply for Indian MRO retrofit programs, the most penetrable segment given BIS-EASA alignment and compressed qualification timelines. Target tier-two supplier status through Gujarat composite parks before advancing to seat component qualification. Pursue joint development agreements with COMAC C919 interior suppliers to satisfy domestic content thresholds without bearing full certification burden. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Japanese precursor specialists seeking European thermoplastic resin capabilities or tier-one aerostructures integrators filling portfolio gaps. Long-term viability favors suppliers with locked-in OEM relationships and dual-qualification assets. Watch for EASA-FAA harmonization on sustainable aviation material credits as the inflection signal determining which fiber-recycling technologies achieve commercial scale first.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Captive acrylonitrile supply secures margin capture against oil-indexed feedstock volatility. |
| EASA-FAA Dual-Qualification Partnership | Dual-approval pathways for phenolic laminates open specification decisions across Airbus and Boeing programs. |
| Thermoplastic Welding Automation | PEEK fusion bonding eliminates adhesive curing cycles and refrigerated prepreg inventory carrying costs. |
| Phosphorus-Nitrogen Resin Reformulation | REACH-compliant flame retardant chemistries maintain 60-second vertical burn certification without halogenated additives. |
| COMAC Supply Chain Localization | Domestic prepreg qualification satisfies MIIT content thresholds for C919 narrow-body deliveries. |
Methodological Framework
Independent corroboration across FAA certification databases, EASA CS-25 amendment records, and MIIT industrial guidance documents underwrites the qualitative findings. Primary interviews with tier-one seat procurement directors, composite plant managers at aerostructures integrators, and EASA DOA qualification holders combined with secondary validation from customs trade data, AS9100 registration databases, and REACH restriction amendment filings. Bottom-up segment sizing and top-down macro anchoring triangulate volume estimates.
Comparable-period anchoring to historical aerospace production rates and interior retrofit cycle timing established the forecast window boundaries. The analysis models product type, application, end user, and manufacturing stage dimensions across the projection horizon. CAGRs derive from segment-level growth rate blending against OEM delivery schedules and MRO fleet age profiles. Forecast inputs include narrow-body production line rates, thermoplastic welding adoption curves, and flammability standard amendment timelines.
Underlying measurement precision varies by segment; thermoplastic product types and commercial aviation end users carry tighter precision than emerging glass-polyester applications and helicopter configurations. Forecasts reflect assumptions around EASA-FAA regulatory convergence, acrylonitrile price stability, and COMAC delivery ramp schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market