
 Asia-Pacific Airborne Fire Control Radar Market | 2026-2036
Asia-Pacific Airborne Fire Control Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Airborne Fire Control Radar Market Analytics
The defense procurement channel is narrowing as regional governments consolidate vendor lists around certified systems integrators. Lockheed Martin leverages its F-35 radar supply agreements to anchor positions across Japan and Australia. Northrop Grumman sustains long-term maintenance contracts with South Korean and Indian air force programs. Raytheon Technologies competes through GaN-based phased array offerings tailored to regional platform requirements.
Asia-Pacific airborne fire control radar denotes airborne sensor systems engineered to detect, track, and engage aerial and surface targets through pulsed or continuous-wave radio frequency emissions, typically operating in X-band or Ku-band frequencies with detection ranges exceeding 150 kilometers against fighter-sized targets. These systems serve primary military functions including beyond-visual-range missile guidance, close air support coordination, and air defense suppression. Multirole radar configurations command the largest addressable base as platforms demand simultaneous air-to-air and air-to-ground modes. Phased array technology segments capture accelerating upgrade cycles as electronically scanned arrays displace mechanically steered apertures across legacy fleets. Mobile radar applications for rotary-wing and unmanned platforms represent the fastest-expanding demand pool as tactical UAV procurement intensifies across Southeast Asian defense budgets.
Japan's Ministry of Economy, Trade and Industry (METI) and Australia's Defence Export Controls framework shape market access through technology transfer protocols and foreign military sales licensing requirements. India's Defence Research and Development Organisation partners with the country's national aerospace regulator to enforce indigenous content thresholds that redirect procurement toward local assembly joint ventures. Stakeholders must monitor how Australia's AUKUS commitments and India's phased manufacturing programs recalibrate supplier qualification timelines without assuming uniform regulatory convergence across the region.
Market Dynamics
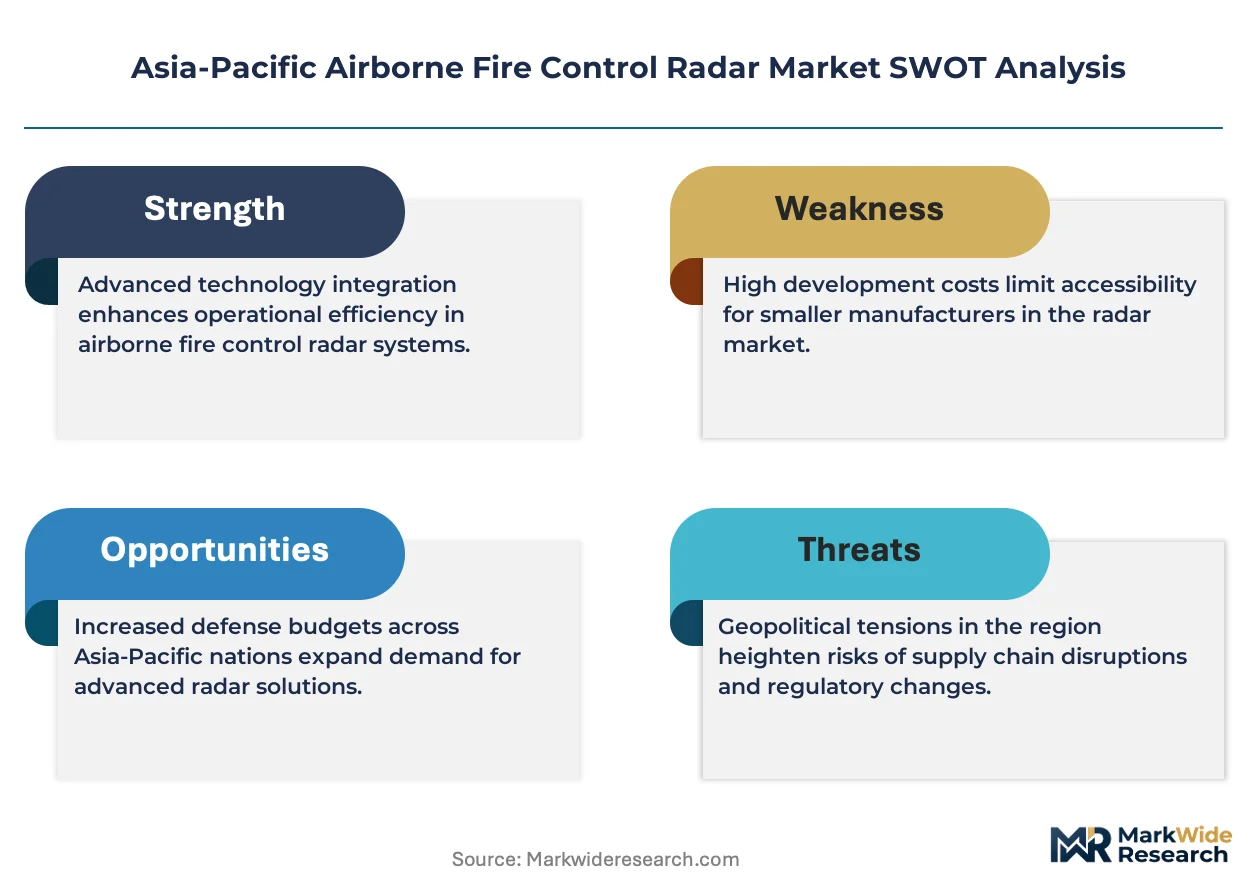
Phased array technology migration is compressing procurement cycles across Asia-Pacific air forces as mechanically steered radar systems face accelerated obsolescence timelines, forcing defense ministries to restructure multi-year capital allocation frameworks around GaN-based electronically scanned arrays.
Growth Catalysts
- India's phased manufacturing program:Indigenous content thresholds enforced by the Defence Research and Development Organisation redirect foreign OEM contracts toward local assembly joint ventures, expanding domestic industrial capacity.
- AUKUS technology sharing protocols:Australia's trilateral commitments with the United States and United Kingdom accelerate radar modernization funding and lower barriers to advanced subsystem imports.
- GaN semiconductor maturation:Gallium nitride transmit-receive modules deliver higher power density and thermal efficiency, enabling extended detection ranges against low-observable targets without platform redesign.
Market Restraints
- Export control fragmentation:Japan's METI licensing requirements and Australia's Defence Export Controls framework impose divergent technology transfer protocols, extending supplier qualification timelines.
- Specialized foundry concentration:Compound semiconductor fabrication for X-band radar components concentrates in a limited supplier base, creating single-source vulnerability for GaN wafer supply.
- Platform integration complexity:Retrofitting active electronically scanned arrays into legacy fighter airframes requires structural modifications to power and cooling systems, limiting upgrade feasibility for older fleets.
Strategic Opportunities
- Southeast Asian UAV procurement:Tactical unmanned platforms across Indonesia, Vietnam, and Thailand create demand for miniaturized fire control radars with reduced SWaP constraints.
- Dual-use weather surveillance:Military-derived phased array technology is hybridizing into civilian meteorological applications, opening adjacent revenue streams for defense contractors.
- South Korean KF-21 program:Indigenous fighter development generates captive demand for domestic radar integration partnerships and technology co-development arrangements.
Industry Challenges
- Electromagnetic spectrum certification:Frequency allocation coordination between military and civilian aviation authorities delays operational clearance for new radar modes.
- Software-defined architecture migration:Transitioning from hardware-fixed to programmable signal processing requires retraining maintenance personnel and rewriting technical documentation across air force engineering corps.
- Supply chain reconfiguration:Geopolitical risk mitigation mandates are forcing tier-two component suppliers to establish redundant manufacturing footprints, compressing margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Airborne Fire Control Radar Market |
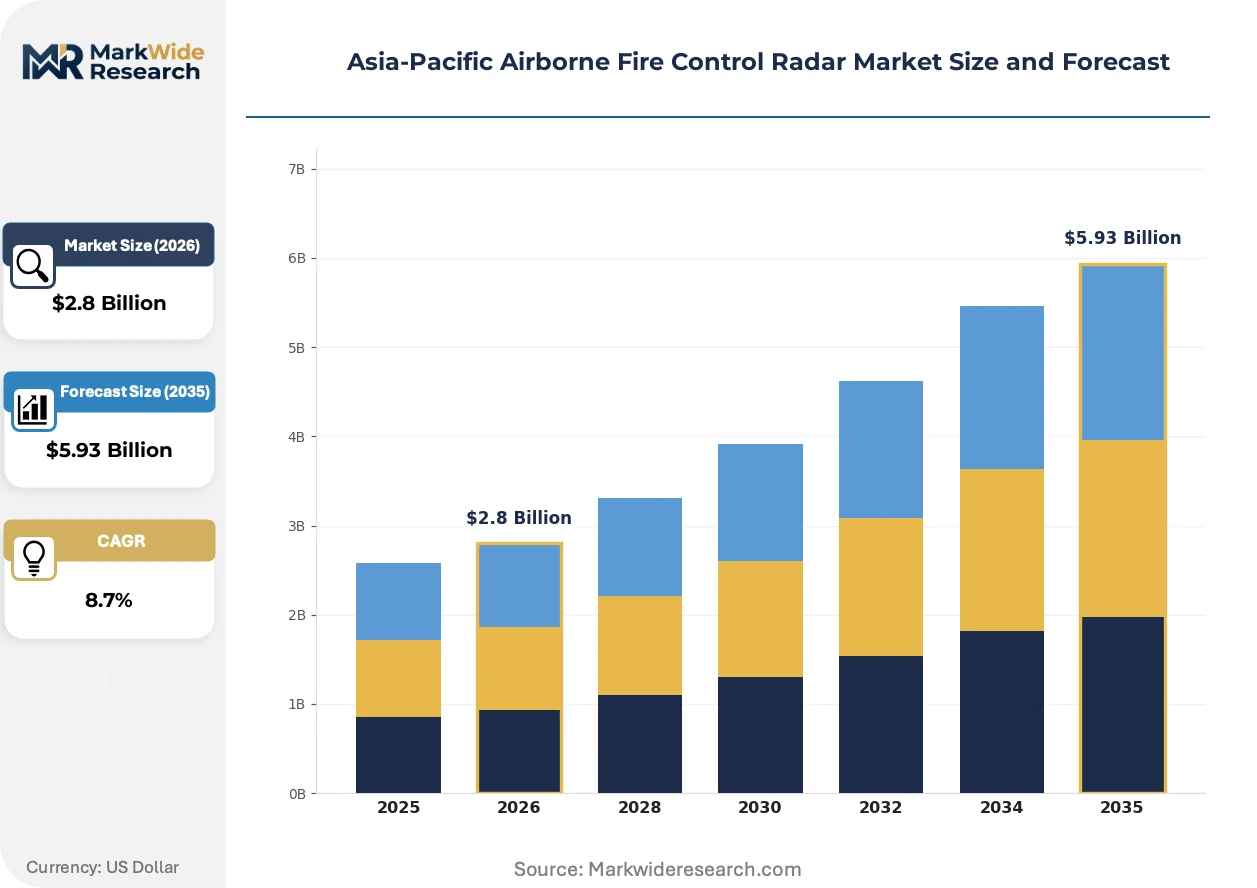
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Radar, Mobile Radar, Multirole Radar, Dual-Band Radar Application: Military Operations, Search and Rescue, Surveillance, Target Acquisition End User: Defense Forces, Government Agencies, Aerospace Manufacturers, Security Contractors Technology: Phased Array, Monopulse, Frequency Modulated, Doppler |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, Raytheon Technologies, Thales Group, BAE Systems, Leonardo S.p.A., Saab AB, Elbit Systems, Aselsan A.S., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Airborne Fire Control Radar Market Evolving Landscape
Digital beamforming architectures are displacing analog phased array implementations across next-generation programs, compressing development timelines while expanding software-upgrade pathways for fielded systems.
Active electronically scanned array technology is hybridizing mechanically steered and fully solid-state architectures into transitional configurations that preserve existing airframe interfaces while enabling incremental capability insertion. South Korea's KF-21 and India's Tejas Mk2 programs are adopting these hybrid arrays to mitigate integration risk. This approach is compressing the traditional 15-year radar development cycle into 8-10 year windows.
Australia's Defence Export Controls framework is tightening technology transfer oversight for radar subsystems with embedded GaN components, extending licensing review periods from 90 to 180 days. Japanese and South Korean defense contractors are responding by pre-positioning technical data packages in-country to accelerate re-export approvals. The policy shift most affects maintenance contract renewals requiring source code access.
Air forces are consolidating vendor relationships around certified systems integrators capable of delivering platform-agnostic radar solutions with unified logistics support. Australia's F-35 and Super Hornet fleets now source common line-replaceable units through single prime contractors, displacing the previous multi-vendor spares model. This concentration is most visible in Japan and Australia, where defense procurement agencies have reduced qualified supplier lists by 40 percent over five years.
Asia-Pacific Airborne Fire Control Radar Market Segmentation
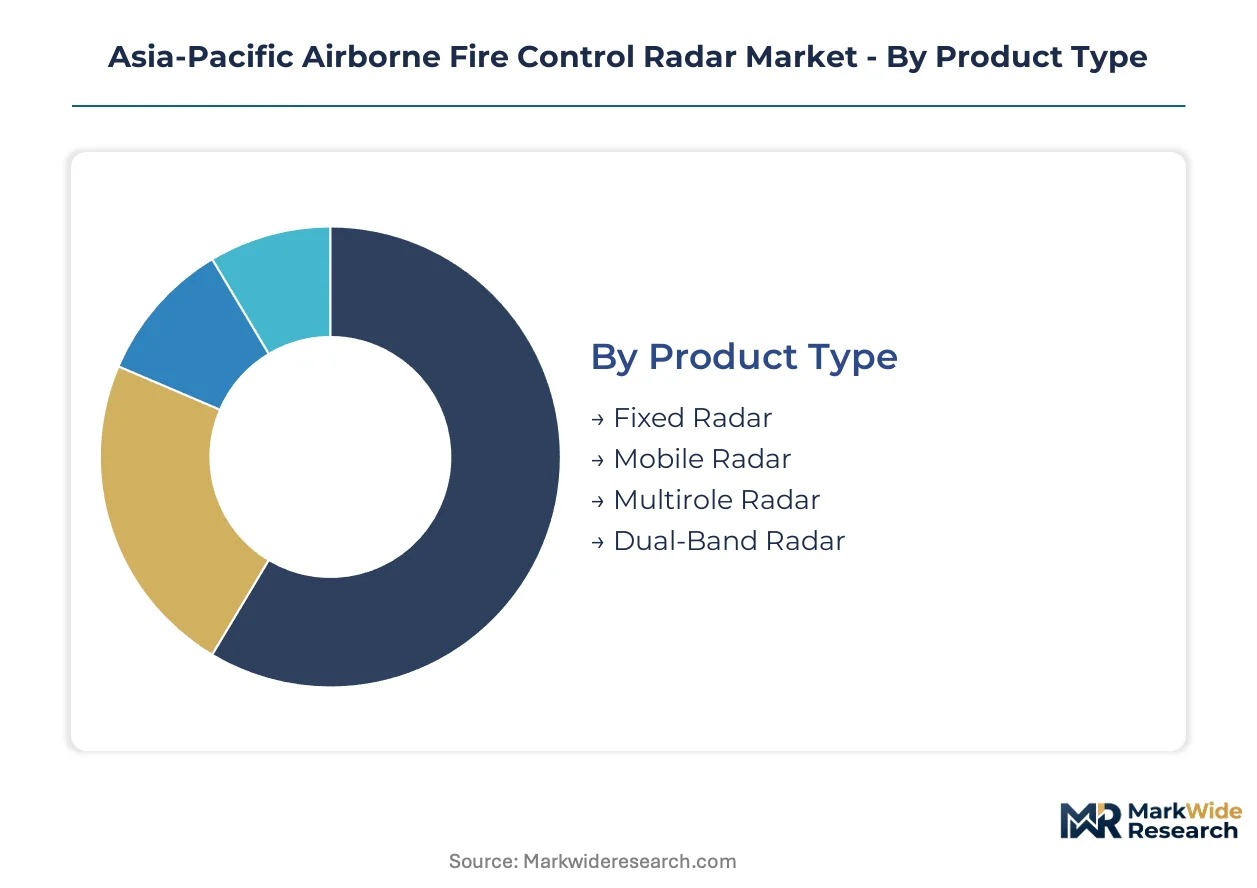
Asia-Pacific airborne fire control radar procurement diverges sharply across mission profiles and platform architectures, with defense ministries optimizing sensor configurations for fighter modernization versus rotary-wing and unmanned system integration. Segmentation reveals how technology maturation and operational requirements reshape vendor qualification criteria across national procurement channels.
Product Type:
Mature mechanically steered configurations coexist with emerging solid-state architectures as air forces navigate upgrade cycles against budget constraints.
- Multirole Radar:Simultaneous air-to-air and air-to-ground modes dominate fighter platform specifications. India's Tejas Mk2 and Australia's F-35 integration programs concentrate procurement volume here, driven by operational flexibility requirements across contested airspace scenarios.
- Mobile Radar:Reduced SWaP designs for rotary-wing and tactical UAV applications represent the steepest demand expansion curve. Southeast Asian unmanned platform procurement across Indonesia, Vietnam, and Thailand accelerates adoption of compact electronically scanned arrays.
- Fixed Radar:Mechanically steered legacy systems persist in transport and tanker fleets where upgrade priority ranks lower.
- Dual-Band Radar:Hybrid X/Ku-band configurations address electronic warfare resilience requirements in contested environments.
Multirole radar retains volume leadership; mobile radar holds the steepest expansion curve.
Application:
Cost tier stratification separates mission-critical combat systems from auxiliary surveillance configurations, with pricing scaling to detection range and track-while-scan channel density.
- Military Operations:Beyond-visual-range missile guidance and air defense suppression modes define core combat functionality. Japan's F-35 and South Korea's KF-21 programs anchor procurement concentration, with GaN-based arrays displacing legacy mechanically steered systems under accelerated obsolescence timelines.
- Surveillance:Wide-area maritime and border monitoring applications hybridize military-derived phased array technology into dual-use meteorological platforms, opening adjacent revenue streams for defense contractors serving civilian agencies.
- Target Acquisition:Precision strike coordination for close air support missions demands high-resolution synthetic aperture radar modes.
- Search and Rescue:Secondary mission modes on multirole platforms leverage existing fire control hardware for humanitarian operations.
Military operations commands the premium tier; surveillance applications are climbing fastest as dual-use technology transfer accelerates.
End User:
Customer type concentration centers on sovereign defense procurement agencies, with industrial policy mandates fragmenting vendor access across national qualification frameworks.
- Defense Forces:National air force modernization programs constitute the primary demand pool, with India's Defence Research and Development Organisation enforcing indigenous content thresholds that redirect foreign OEM contracts toward local assembly joint ventures.
- Aerospace Manufacturers:Prime contractors integrate vendor-supplied radar subsystems into complete platform deliveries, with Australia's AUKUS commitments accelerating subsystem import licensing for F-35 and Super Hornet production.
- Government Agencies:Coast guard and border security organizations adopt modified fire control radars for maritime domain awareness.
- Security Contractors:Private sector maintenance and logistics providers capture aftermarket service revenue under long-term performance-based contracts.
Defense forces dominate contract value; aerospace manufacturers are gaining procurement influence as platform integration complexity rises.
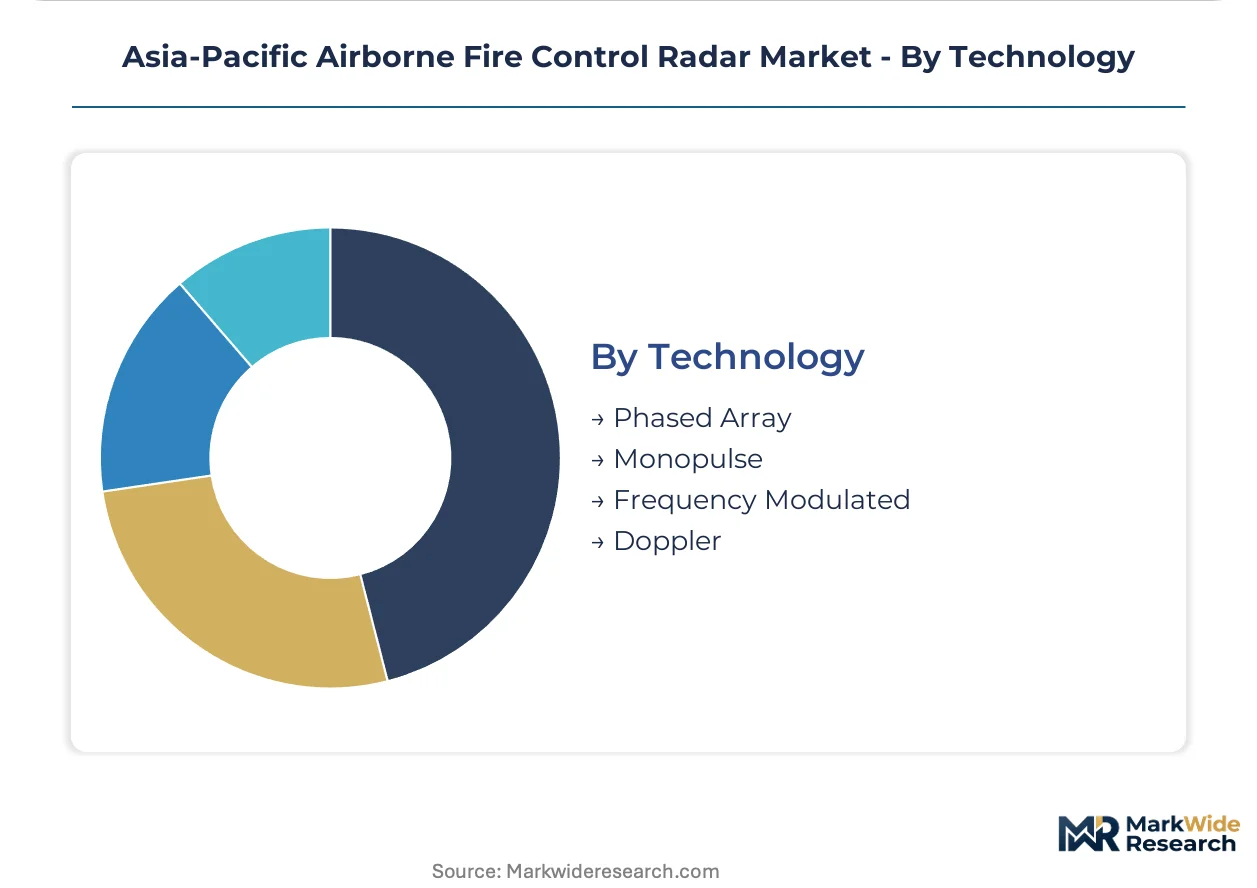
Technology:
Supply concentration in compound semiconductor fabrication shapes technology adoption trajectories, with GaN wafer availability constraining phased array deployment timelines.
- Phased Array:Electronically scanned architectures with programmable beam steering displace mechanically steered apertures across legacy fleet upgrades. Active electronically scanned array adoption compresses traditional development cycles while enabling software-defined capability insertion without hardware replacement.
- Doppler:Pulse-Doppler processing for moving target indication remains essential for look-down/shoot-down engagements against low-flying threats in clutter environments.
- Monopulse:Angle measurement precision for missile guidance applications persists in hybrid array configurations.
- Frequency Modulated:Continuous-wave variants for low-probability-of-intercept operations see limited tactical adoption.
Phased array technology captures the steepest growth trajectory; Doppler signal processing retains foundational status across all deployed configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australia's AUKUS-aligned procurement channels while India's indigenous manufacturing mandates compress margins for foreign OEMs. Japan and South Korea anchor premium-tier demand through F-35 and KF-21 programs. Southeast Asian markets fragment across budget-constrained unmanned platform procurement.
Japan
F-35 radar integration and indigenous F-X fighter development drive procurement volume. METI licensing requirements extend technology transfer review periods for GaN-based subsystems. Tokyo's defense industrial corridor hosts prime contractor facilities coordinating with Lockheed Martin on joint production arrangements.
Australia
AUKUS commitments accelerate F-35 and Super Hornet modernization funding. Defence Export Controls framework tightens oversight for radar subsystems with embedded compound semiconductors. Adelaide and Melbourne defense clusters concentrate platform integration activity under consolidated vendor relationships.
India
Tejas Mk2 and Advanced Medium Combat Aircraft programs generate phased array demand. DRDO indigenous content thresholds redirect foreign contracts toward local assembly joint ventures. Bengaluru's aerospace hub hosts HAL facilities partnering with international OEMs on radar subsystem co-development.
South Korea
KF-21 indigenous fighter development creates captive demand for domestic radar integration. MFDS export certification protocols govern technology transfer for GaN transmit-receive modules. Sacheon and Seoul defense corridors concentrate prime contractor engineering for electronically scanned array production.
Indonesia
Tactical UAV procurement across maritime surveillance missions drives compact fire control radar adoption. National defense procurement agency budget constraints favor reduced SWaP configurations. Bandung's aerospace manufacturing zone hosts maintenance facilities for regional unmanned platform fleets.
Asia-Pacific Airborne Fire Control Radar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in transmit-receive module and signal processor supply. Market structure consolidates around certified systems integrators capable of delivering unified logistics support across multi-platform fleets. Three archetypes dominate: US primes with F-35 supply agreements, European sensor houses with modular open architectures, and emerging domestic champions in India and South Korea. Competitive moves center on technology licensing partnerships and local assembly joint ventures to satisfy indigenous content mandates.
Among US-based primes, Lockheed Martin Corporation and Northrop Grumman Corporation occupy anchor positions through long-term fighter platform supply agreements. Raytheon Technologies exemplifies the GaN technology specialist archetype competing on semiconductor performance. These three represent the consolidated tier that regional procurement agencies have reduced by 40 percent over five years, concentrating vendor relationships around certified integrators with platform-agnostic radar solutions.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Raytheon Technologies |
| Thales Group |
| BAE Systems |
| Leonardo S.p.A. |
| Saab AB |
| Elbit Systems |
| Aselsan A.S. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on GaN wafer foundries determines both tiered pricing spreads across AESA configurations and supply chain regionalization patterns. Japan's METI export licensing extensions and Australia's Defence Export Controls tightening compress margins for foreign OEMs while redirecting procurement toward pre-qualified domestic integrators.
Pricing Analysis
Configured-to-order AESA systems for F-35 and KF-21 platforms command substantial premiums over standard mechanically steered retrofits. Three-tier pricing structure separates GaN-based active arrays from hybrid transitional configurations and legacy mechanically steered systems. Cost compression in standard-tier retrofits is intensifying because India's DRDO indigenous content mandates force foreign OEMs into local joint ventures with reduced margin structures. Defense forces in Southeast Asia exhibit highest price sensitivity due to budget-constrained UAV procurement, while AUKUS-aligned Australian programs show lowest sensitivity under consolidated prime contractor arrangements.
Supply Chain Analysis
Compound semiconductor foundry capacity concentrates in Taiwan, the United States, and South Korea for X-band GaN transmit-receive module production. The supply chain draws from high-purity gallium substrates, silicon carbide wafers, and specialized ceramic packaging materials. Single-source vulnerability in GaN epitaxy services creates chokepoint exposure for phased array deployment timelines. Distribution runs through certified systems integrators holding platform-agnostic radar contracts with unified logistics support across multi-fleet air forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as regional defense procurement agencies consolidate vendor lists around certified integrators, reducing qualified suppliers by 40 percent across Japan and Australia over five years.
For Market Incumbents: Insulate long-term maintenance revenue through source code escrow arrangements and in-country technical data pre-positioning to accelerate re-export approvals under tightening Australian Defence Export Controls. Backward integration into GaN module assembly mitigates foundry concentration risk while preserving margin structures against emerging domestic champions in India and South Korea. For New Entrants and Emerging Players: Southeast Asian UAV procurement gaps in Indonesia, Vietnam, and Thailand offer the most penetrable entry corridor for reduced-SWaP compact radar configurations. Target maritime surveillance applications with dual-use meteorological hybridization to bypass traditional defense procurement qualification timelines. Partner with regional unmanned platform OEMs for integrated sensor-package offerings rather than standalone radar sales. For Investors and Strategic Acquirers: Australia's AUKUS technology sharing protocol reshapes the acquisition landscape by lowering barriers for US and UK subsystem suppliers while elevating qualification requirements for third-country vendors. Long-term viability centers on platform-agnostic radar architectures with software-defined upgrade pathways. Monitor India's phased manufacturing program indigenous content threshold escalations as the critical signal for joint venture restructuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures transmit-receive module supply for AESA production under METI licensing constraints. |
| Local Assembly Joint Venture | Satisfies DRDO indigenous content thresholds for Indian fighter modernization programs. |
| Software-Defined Architecture Migration | Enables field-upgradeable capability insertion without hardware replacement across F-35 fleets. |
| Dual-Use Meteorological Licensing | Opens adjacent revenue streams through civilian weather radar applications in Southeast Asia. |
| Technical Data Pre-Positioning | Accelerates Australian Defence Export Controls re-export approvals for maintenance contract renewals. |
Research Methodology
The analysis maps phased array technology segments, mechanically steered legacy configurations, and mobile radar applications for unmanned platforms, each validated through air force procurement officers, defense systems integrators, radar subsystem engineers, and compound semiconductor supply specialists. Primary interviews triangulate against secondary sources including METI licensing databases, Australia's Defence Export Controls determinations, DRDO indigenous content circulars, and MFDS export certification records. Bottom-up platform procurement forecasts reconcile with top-down defense budget allocation trajectories across the analysis window.
Fixed assumptions include sustained AUKUS technology sharing protocol implementation, progressive DRDO indigenous content threshold escalation, and stable GaN semiconductor fabrication capacity expansion. The projection horizon models technology adoption by platform type, mission profile application, end-user procurement channel, and national regulatory framework cluster. CAGRs derive from segmented platform delivery schedules and upgrade cycle compression rates informed by KF-21 and Tejas Mk2 development timelines.
Practitioners should monitor METI licensing review period extensions, Australian Defence Export Controls GaN component reclassifications, and DRDO joint venture mandate expansions for early signals of supply chain restructuring. Quarterly review of defense budget appropriation committee deliberations and foundry capacity utilization disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Airborne Fire Control Radar Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Global Missile Interceptor Market