
 Global Aircraft Tugs Market | 2026-2036
Global Aircraft Tugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Tugs Market Intelligence
The procurement preference for outsourcing to specialized ground handling service providers is hardening the operational model at major airports. TLD Group leverages its extensive global service network to support these third-party operators. JBT Corporation competes by offering integrated ground support solutions, including both equipment and telematics. In contrast, Goldhofer AG specializes in heavy-duty towbarless tractors for wide-body aircraft.
An aircraft tug is a specialized ground support vehicle designed to move aircraft on the ground, either by pushing or pulling. These vehicles are engineered with high torque at low speeds, with drawbar pull ratings often exceeding 70,000 pounds for handling wide-body jets. Electric tugs are displacing diesel models in the product mix, driven by airport emissions mandates and lower operational costs. Remote control capabilities represent a high-growth niche for towbarless tugs used in aircraft maintenance operations.
Regulations from bodies like the US Federal Aviation Administration (FAA) and standards associated with the EU Green Deal govern equipment safety and emissions. In parallel, China's MEE is setting stricter pollution controls at airports, directly shaping the technology choices for ground support fleets. Decisions on the pace of electrification versus investing in autonomous guidance capabilities will define competitive advantage for airport operators and service providers.
Market Dynamics
The central force shaping the aircraft tugs market is the non-negotiable transition to electric powertrains, a shift compelled by a global convergence of airport emissions mandates and the operational cost advantages of electrification over diesel.
Growth Catalysts
- Airport Expansion:Construction and capacity upgrades at hubs in the Middle East and Southeast Asia, particularly in the UAE and Singapore, necessitate new fleets of ground support equipment to handle projected air traffic increases.
- Remote Control Technology:The integration of remote control systems in towbarless tugs for maintenance, repair, and overhaul (MRO) operations is creating new demand by enhancing safety and operational precision in crowded hangars.
- Regulatory Mandates:The EU Green Deal framework is accelerating the replacement cycle for older diesel tugs as European airports and ground handlers invest in compliant electric models to meet emissions targets.
Market Restraints
- High Capital Outlay:The significant upfront investment required for electric tugs, compounded by the cost of installing dedicated high-capacity charging infrastructure, deters some airport operators and service providers.
- Performance Limitations:Current battery technology can exhibit reduced range and performance in extreme hot or cold climates, posing operational reliability risks for airports in desert or arctic regions.
- Legacy Fleet Longevity:The durability and long service life of existing diesel tugs make their replacement economically challenging, slowing the adoption rate of newer, more expensive technologies until the end of their functional lifespan.
Strategic Opportunities
- Autonomous Guidance Systems:Developing and integrating semi-autonomous or fully autonomous navigation capabilities for apron operations represents a significant opportunity to reduce labor dependency and improve turnaround efficiency.
- Tugs-as-a-Service (TaaS):Offering subscription or leasing models that bundle the tug, maintenance, and charging infrastructure can lower the entry barrier for smaller airports and third-party ground handlers.
- Retrofit Solutions:There is a market for certified kits to convert existing diesel-powered tugs to electric or hybrid-electric, particularly in developing regions where full fleet replacement is not yet viable.
Industry Challenges
- Interoperability with Legacy Systems:Integrating smart, connected tugs with disparate and often outdated airport management software and air traffic control systems presents a significant technical and logistical hurdle for operators.
- Technician Skill Gaps:A shortage of maintenance personnel trained in high-voltage electrical systems and advanced diagnostic software for electric tugs creates operational bottlenecks and increases service costs.
- Charging Infrastructure Standardization:The absence of a universal charging connector and protocol standard for electric ground support equipment complicates infrastructure planning and limits equipment interoperability for ground handlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Tugs Market |
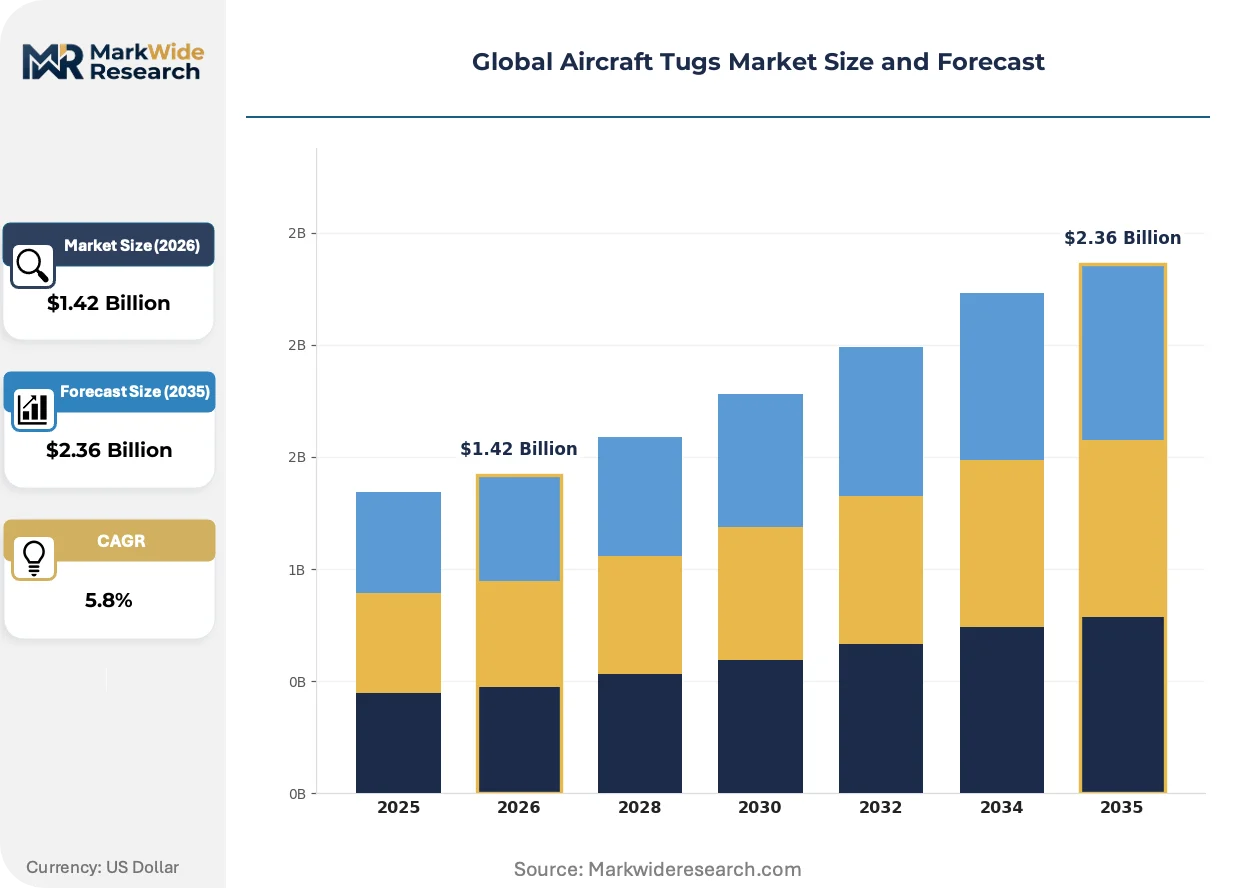
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tugs, Diesel Tugs, Hybrid Tugs, Pushback Tractors, Towbarless Tugs Technology: Automated Guidance, Manual Control, Remote Control, GPS Integration, Sensor-Assisted Navigation Application: Aircraft Positioning, Cargo Handling, Ground Support Equipment Movement, Maintenance Assistance, Refueling Support End User: Airlines, Ground Handling Service Providers, Airport Authorities, Aircraft Maintenance Organizations |
| Companies Covered | Textron GSE, JBT Corporation, TLD Group, TREPEL Aircraft Equipment GmbH, Kalmar Motor AB, MULAG Fahrzeugwerk, Mototok International GmbH, Tronair Inc., Goldhofer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Tugs Market Strategic Shifts & Innovations
The convergence of electrification and digitalization is redefining the role of aircraft tugs from standalone vehicles to integrated nodes in a data-driven ground operations ecosystem. This evolution prioritizes total operational efficiency and environmental compliance over simple drawbar pull capacity.
Advanced electric powertrains, combining high-density lithium-ion battery packs with high-torque permanent magnet motors, form the new technological core of modern aircraft tugs. Ground handling service providers at major international airports are leading the adoption, driven by performance and emissions goals. This electric powertrain architecture is overtaking legacy diesel-hydraulic systems in the majority of new procurement tenders for both towbar and towbarless tugs.
Regulatory frameworks are directly steering technology investment. China's Ministry of Ecology and Environment (MEE) has implemented stringent air quality regulations at key airports, including those in the Beijing-Tianjin-Hebei region. This policy directly compels the retirement of older, higher-emission diesel equipment. The conventional heavy-duty tug segment is most impacted, forcing operators to accelerate fleet modernization with compliant electric models to secure operating rights.
The preference for outsourcing ground handling to specialized service providers is solidifying as a dominant operational model. This trend moves the equipment acquisition decision away from airlines and toward third-party operators who prioritize total cost of ownership and fleet utilization. This pattern is particularly visible in competitive European hubs, where ground handlers use fleet-wide telematics to optimize asset deployment and secure service contracts.
Global Aircraft Tugs Market Segmentation
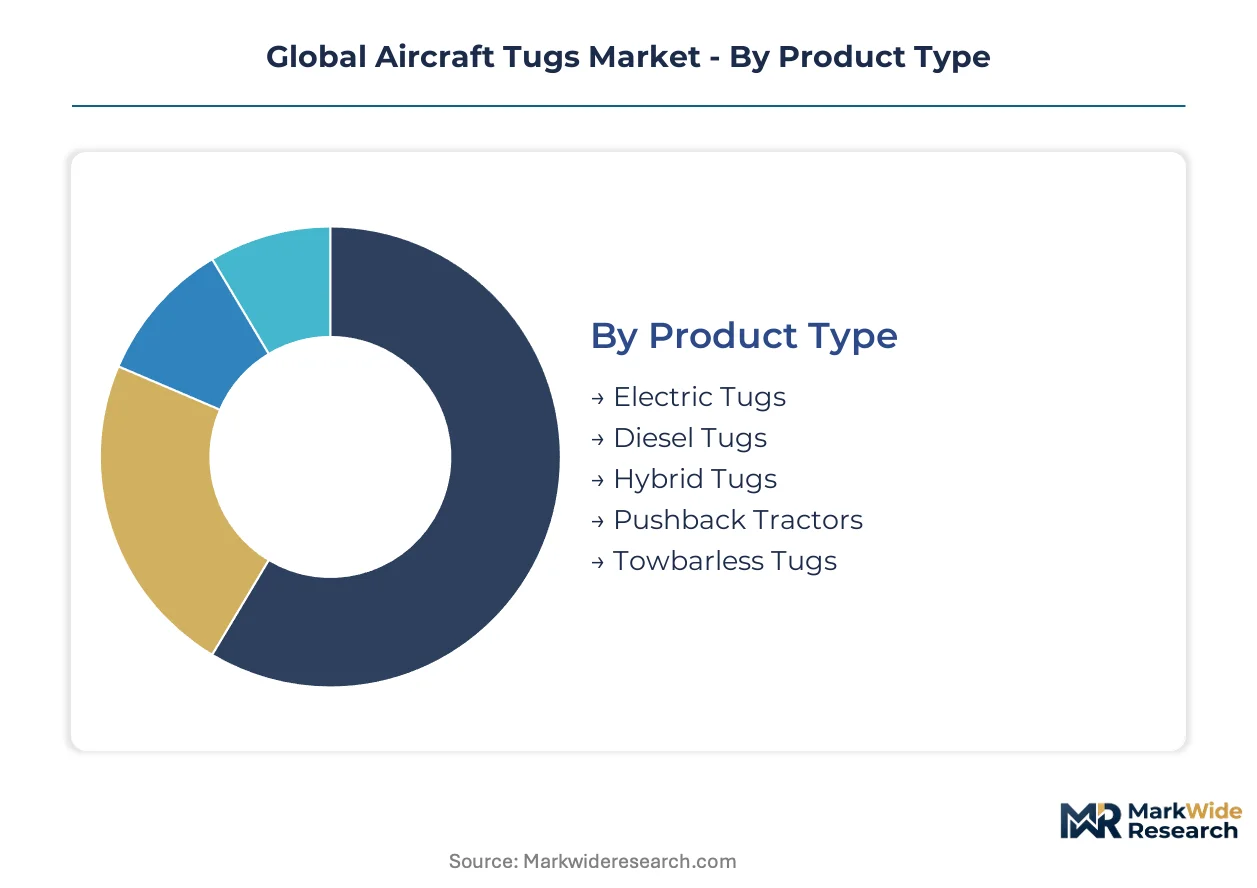
The Global Aircraft Tugs Market exhibits distinct segmentation across product type, technology, application, and end-user categories. Understanding these segments is crucial for manufacturers to align product development with specific operational needs and for service providers to optimize fleet composition.
Product Type:
Buyers in the aircraft tugs market differentiate their procurement strategies based on the operational capabilities and environmental compliance offered by various product types.
- Electric Tugs:These vehicles utilize battery-powered electric motors, offering zero direct emissions and reduced noise levels, aligning with stringent airport environmental mandates like the EU Green Deal. Demand is concentrating in major international airports in Europe and North America, driven by operational cost advantages.
- Towbarless Tugs:Designed to cradle the aircraft nose gear, these tugs eliminate the need for a towbar, enhancing maneuverability and reducing turnaround times, particularly for wide-body aircraft. This segment sees significant demand in MRO operations where remote control capabilities improve precision in confined hangar spaces.
- Diesel Tugs:Powered by internal combustion engines, these traditional tugs provide high drawbar pull and long operational endurance but face increasing pressure from emissions regulations. Procurement patterns are shifting away from these models in highly regulated regions.
- Hybrid Tugs:These tugs combine diesel engines with electric powertrains, offering a balance between range and emissions reduction. Hybrid models provide a transitional solution for airports with evolving environmental targets.
- Pushback Tractors:Specialized vehicles primarily used for moving aircraft away from the gate. These tractors are essential for efficient ground operations at busy airport terminals.
Volume sits with Diesel Tugs; growth tilts toward Electric Tugs.
Technology:
The technological sophistication embedded in aircraft tugs directly influences operational efficiency and safety protocols.
- Remote Control:This technology allows operators to maneuver towbarless tugs from a distance, significantly enhancing safety and precision during complex aircraft movements in maintenance hangars. This capability represents a high-growth niche for MRO providers.
- Automated Guidance:Systems that enable tugs to navigate autonomously or semi-autonomously on the apron, reducing human error and optimizing routing. This technology is a strategic opportunity for airports aiming to reduce labor dependency and improve turnaround efficiency.
- Manual Control:The traditional method of operating aircraft tugs, relying entirely on direct human input from the driver's cabin. This remains the most widespread technology for basic ground movements.
- GPS Integration:Incorporating Global Positioning System data into tug operations for precise location tracking, route optimization, and fleet management. This enhances telematics capabilities for ground handlers.
- Sensor-Assisted Navigation:Utilizing various sensors (e.g., LiDAR, radar, ultrasonic) to detect obstacles and ensure safe operation, particularly in crowded apron environments. This technology supports both manual and automated systems.
Manual Control systems currently dominate operational deployments, but Remote Control solutions are expanding most quickly due to MRO applications.
Application:
The specific tasks performed by aircraft tugs dictate the required power, maneuverability, and precision of the equipment.
- Aircraft Positioning:This core application involves moving aircraft to and from gates, maintenance bays, and parking areas. It demands high drawbar pull and precise control.
- Maintenance Assistance:Tugs used within hangars and MRO facilities for precise repositioning of aircraft during repair and overhaul procedures. Remote control capabilities are highly valued in this segment.
- Cargo Handling:While primarily handled by specialized loaders, tugs assist in moving cargo dollies and other ground support equipment related to cargo operations. This application requires robust towing capabilities.
- Ground Support Equipment Movement:Tugs are utilized to move various pieces of ground support equipment, including baggage carts, catering trucks, and mobile stairs, across the airport apron. This is a common utility application.
- Refueling Support:Tugs may assist in positioning aircraft or moving refueling equipment, though this is a less direct application compared to others. This task requires careful coordination and safety protocols.
Aircraft Positioning remains the primary application, while Maintenance Assistance exhibits the steepest expansion trajectory with advanced tugs.
End User:
End-user segments exhibit distinct purchasing criteria influenced by fleet size, regulatory obligations, and operational models.
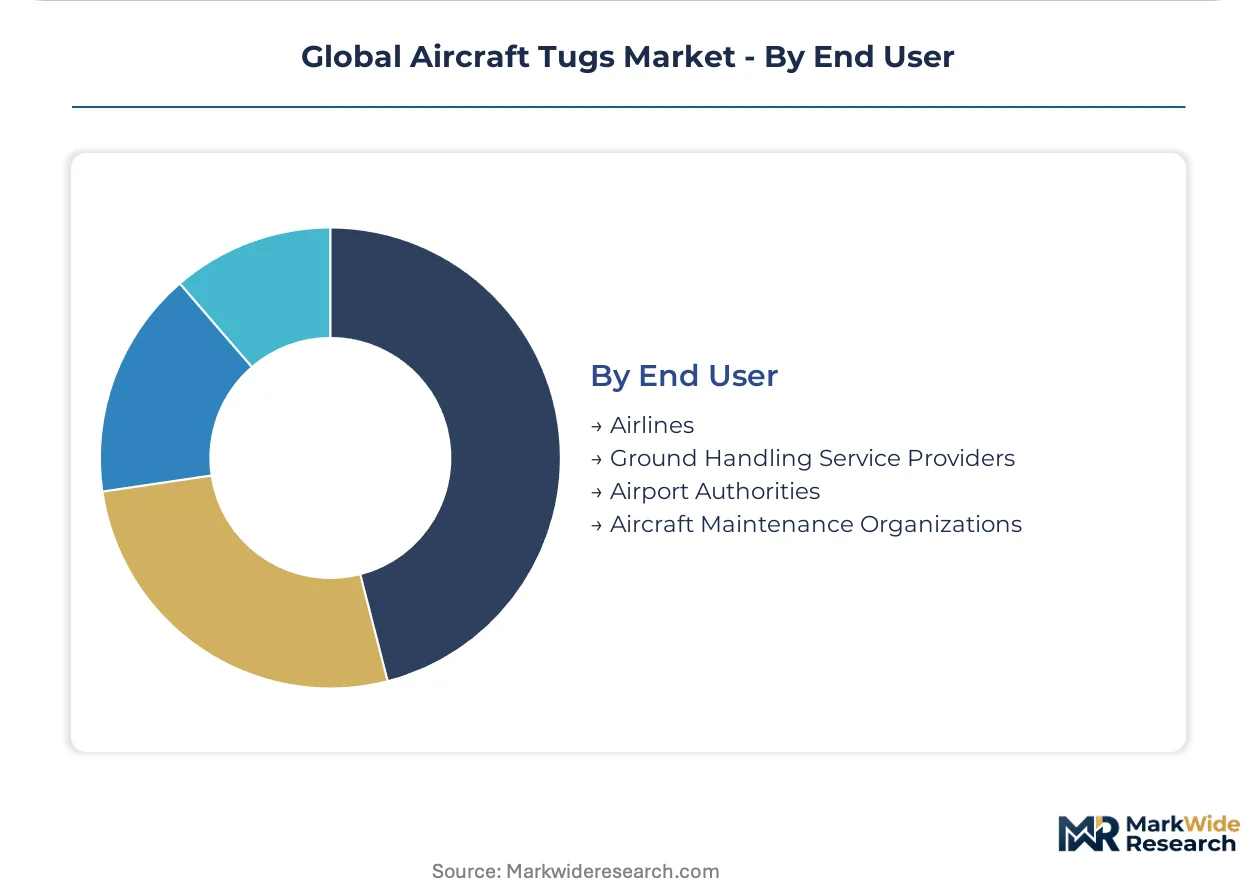
- Ground Handling Service Providers:These specialized third-party operators manage a significant portion of ground operations at major airports, driving demand for efficient and compliant tug fleets. Their procurement patterns prioritize total cost of ownership and fleet utilization.
- Airport Authorities:As owners and operators of airport infrastructure, these entities procure tugs for their own operational needs and often influence equipment standards and electrification mandates. China's MEE regulations directly shape their technology choices.
- Airlines:While many airlines outsource ground handling, some maintain their own ground support equipment fleets, particularly at their main hubs or for specialized operations. Their purchasing decisions are often tied to specific fleet requirements.
- Aircraft Maintenance Organizations:MRO facilities require specialized tugs for precise movement of aircraft within hangars and maintenance zones. Remote control towbarless tugs are particularly sought after by these organizations.
Ground Handling Service Providers represent the largest end-user segment, with Airport Authorities increasingly driving procurement of compliant electric models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai World Central (DWC) in the United Arab Emirates exemplifies a key growth zone where airport expansion necessitates significant investment in ground support equipment. This strategic hub, alongside other rapidly developing aviation centers, drives demand for advanced aircraft tugs. Global regulatory shifts further influence procurement, particularly towards electric models.
United States
Demand for aircraft tugs in the United States is driven by high air traffic volumes and extensive MRO operations across numerous major airports. The US Federal Aviation Administration (FAA) mandates stringent safety and operational standards for ground support equipment. Key aviation hubs like Atlanta Hartsfield-Jackson and Dallas/Fort Worth International Airports consistently upgrade their fleets to enhance efficiency.
Germany
Germany's aircraft tug market benefits from the EU Green Deal framework, which accelerates the adoption of electric and hybrid models at its major airports. This regulatory push encourages ground handling service providers to invest in compliant, lower-emission equipment. Frankfurt Airport and Munich Airport, significant European aviation hubs, lead in the deployment of advanced electric tug technologies.
China
China's rapid airport expansion and stringent environmental policies from the Ministry of Ecology and Environment (MEE) compel the modernization of aircraft tug fleets. The MEE's pollution controls directly shape technology choices, favoring electric models over traditional diesel equipment. The Beijing-Tianjin-Hebei region, with its dense air traffic and environmental focus, represents a core market for new tug procurements.
United Arab Emirates
The United Arab Emirates experiences substantial demand for aircraft tugs due to ambitious airport expansion projects and projected increases in air traffic. Local environmental mandates in the UAE encourage the adoption of more sustainable ground support solutions. Major international airports in Dubai and Abu Dhabi are continuously investing in advanced tugs to manage their growing operational complexities.
Singapore
Singapore, as a premier aviation hub in Southeast Asia, drives demand for aircraft tugs through its expanding MRO operations and high-volume passenger and cargo traffic. The country's sustainability initiatives influence procurement towards electric and remote-controlled tugs. Changi Airport and Seletar Aerospace Park are key areas where advanced towbarless tugs enhance precision and efficiency in aircraft movement.
Global Aircraft Tugs Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining a competitive landscape that balances established players with emerging innovators. The market exhibits a tiered structure, with large, diversified ground support equipment providers competing alongside niche manufacturers focused on specific tug technologies. Strategic archetypes include integrated solution providers, electrification pioneers, and heavy-duty specialists. Companies pursue competitive advantage through both portfolio diversification and strategic partnerships to expand their global service networks.
Integrated solution providers, such as JBT Corporation, exemplify companies offering comprehensive ground support equipment alongside telematics and service solutions. TLD Group, with its extensive global service network, represents another archetype focused on supporting third-party operators across diverse regions. Furthermore, Goldhofer AG occupies a position as a specialist in heavy-duty towbarless tractors, catering to the specific demands of wide-body aircraft movement. These companies collectively anchor the market's competitive dynamics, showcasing varied approaches to product development and market engagement.
| Leading Market Players |
|---|
| Textron GSE |
| JBT Corporation |
| TLD Group |
| TREPEL Aircraft Equipment GmbH |
| Kalmar Motor AB |
| MULAG Fahrzeugwerk |
| Mototok International GmbH |
| Tronair Inc. |
| Goldhofer AG |
Cost & Logistics Intelligence
Outsourced ground handling models anchor equipment supply positions, influencing pricing power for specialized aircraft tugs. This operational choice prioritizes total cost of ownership for third-party operators, impacting procurement decisions.
Pricing Analysis
Premium pricing for electric aircraft tugs reflects specialized features and rapid deployment capabilities, with contract-based models often bundling equipment, maintenance, and telematics services for ground handling providers. Price differentiation stems from brand reputation and the breadth of integrated after-sales support networks. Pricing softness affects conventional diesel tugs due to increasing regulatory pressure and diminishing demand. Airport authorities procuring compliant electric models exhibit lower price sensitivity compared to smaller third-party ground handlers.
Supply Chain Analysis
Certification for ground support equipment, particularly for safety-critical aircraft movements, gates supply chain participation, with manufacturing for advanced aircraft tugs concentrating in Germany and the United States. Key raw material dependencies include high-density lithium-ion battery cells and specialized permanent magnet motors. Single-source vulnerability for these advanced components represents a structural supply chain risk. Distribution runs through direct sales channels to major airport authorities and specialized ground handling service providers, complemented by global service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft tugs market operates as a cost-of-compliance story, where stringent emissions mandates like the EU Green Deal create a significant barrier-to-entry moat for non-compliant equipment and new players.
For Market Incumbents:Extend global service networks and integrated telematics solutions to support third-party ground handlers, who prioritize total cost of ownership. Invest aggressively in autonomous guidance R&D to counter the threat of labor dependency and improve turnaround efficiency. Pursue upstream control over battery technology or charging infrastructure to mitigate supply chain risks. Secure certifications for new electric models to reinforce market position against evolving emissions mandates.
For New Entrants and Emerging Players:Online leasing platforms represent a viable digital-channel route to offer Tugs-as-a-Service (TaaS) models, lowering entry barriers for smaller airports and third-party handlers. Target the MRO segment with specialized remote-control towbarless tugs, where precision and safety are paramount. Focus on developing regions with certified retrofit solutions to convert existing diesel fleets, addressing the legacy fleet longevity restraint. Emphasize lower operational costs and environmental compliance as key go-to-market differentiators.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized technology providers, particularly those pioneering electric and autonomous tug solutions, indicating long-term viability over the next 5-10 years. Target acquisition archetypes include electrification specialists with proven battery management systems and remote control technology firms. Monitor the standardization of charging infrastructure as a key inflection indicator for accelerated market adoption. Investment in companies offering Tugs-as-a-Service models can capture recurring revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Autonomous Guidance Systems | Reduces labor dependency for airport operators and improves apron turnaround efficiency. |
| Expand Tugs-as-a-Service (TaaS) Offerings | Lowers upfront capital outlay for smaller ground handlers and expands market access. |
| Invest in High-Density Battery R&D | Extends operational range for electric tugs, addressing performance limitations in extreme climates. |
| Acquire Remote Control Technology Firms | Enhances precision and safety for MRO operations, a high-growth niche for towbarless tugs. |
| Secure Global Emissions Certifications | Ensures market access in regions with stringent regulations like the EU Green Deal and China's MEE. |
Research Approach
Multi-period observation of aircraft traffic volumes and ground support equipment procurement trends anchored the trend analysis, supplemented by interviews with ground handling service providers, airport authorities, MRO facility managers, and equipment manufacturers. Secondary validation utilized public records, including FAA regulations, EU Green Deal documents, and China's MEE policy statements. This approach combined bottom-up market sizing with top-down validation to ensure data integrity.
An input-output matrix framework modeled market dynamics across the analysis window, integrating volume and value projections. Segmentation dimensions included product type, technology, application, end-user, and key regional markets. Compound annual growth rates derived from historical data and anticipated technology adoption curves. Industry-specific forecast inputs included global air traffic growth projections and electric tug replacement cycles.
Inputs from equipment manufacturers and airport authority reports were available through the study window; gaps in emerging market adoption rates introduce uncertainty bands. Forecasts reflect assumptions on regulatory enforcement and technological advancements. A model refresh is warranted upon material change in global aviation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
America Freighter Aircraft Market
Aircraft
US Business Jet Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
UK Aviation Market
Aircraft
North America Aviation Market
Aircraft
Latin America General Aviation Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Light and Very Light Jets Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Docking System Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
India Winglets Market