
 Defense Communication System Market | 2026-2036
Defense Communication System Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Communication System Market Intelligence
Software-defined radio architectures is reconfiguring how defense communication platforms integrate across multi-domain operations. L3Harris Technologies leverages its waveform portfolio to sustain program wins in tactical radio modernization. Thales anchors European supply chains through NATO-certified encryption modules. Elbit Systems dominates Israeli and allied exports with ruggedized manpack terminals.
Defense communication systems encompass encrypted voice, data, and video transmission equipment operating across HF, VHF, UHF, and satellite frequency bands with interoperability mandated by STANAG and MIL-STD specifications. These systems enable real-time command coordination between dismounted soldiers, vehicles, aircraft, and naval vessels across contested electromagnetic environments. Network-centric systems now capture the largest procurement budgets as militaries shift from platform-centric to information-centric warfare doctrines. Software defined radio represents the fastest-expanding technology segment because single hardware units reconfigure across multiple waveforms, reducing logistics tail and obsolescence risk.
FCC spectrum allocations in the United States, NATO STANAG standardization requirements across Europe, and Australia's Defence Strategic Review procurement guidelines collectively shape product certification pathways and market access conditions. Compliance with these frameworks determines eligibility for national security contracts and allied interoperability certification. Stakeholders must monitor emerging quantum-resistant encryption mandates and spectrum reallocation decisions that will determine next-generation platform specifications.
Market Dynamics
Software-defined radio architectures are collapsing hardware variety into reconfigurable platforms, forcing defense procurement offices to rewrite technical specifications and supplier qualification criteria across NATO allied forces.
Growth Catalysts
- STANAG 4372 interoperability mandates:NATO standardization requirements compel member states to procure compatible waveform systems, creating pooled demand across 32 allied nations.
- Multi-domain operations doctrine:Military commands require seamless voice-data-video handoffs between dismounted soldiers, armored vehicles, and airborne platforms in contested electromagnetic environments.
- Quantum-resistant encryption transition:NIST post-quantum cryptography standards are accelerating replacement cycles for legacy tactical radios before cryptanalytic vulnerabilities materialize.
Market Restraints
- GaN and GaAs substrate supply concentration:Advanced semiconductor foundries in Taiwan and South Korea control critical RF component fabrication, exposing defense primes to single-source chokepoints.
- FCC spectrum reallocation uncertainty:Commercial 5G encroachment on 3.1-3.45 GHz bands threatens military training and operational spectrum availability in the United States.
- Interoperability certification timelines:NATO C3 Agency validation cycles extend 18-24 months, delaying field deployment of upgraded waveform software even after hardware delivery.
Strategic Opportunities
- Australia Defence Strategic Review procurement:Canberra's AUKUS alignment is opening integrated communication system tenders requiring US-Australian-British trilateral certification.
- LEO satellite constellation integration:Tactical terminals combining traditional UHF/VHF with Starlink and OneWeb downlinks are creating new product categories for expeditionary forces.
- AI-enabled spectrum management:Machine learning algorithms for dynamic frequency selection in jamming environments represent unclaimed intellectual property territory.
Industry Challenges
- Cleared workforce scarcity:Defense contractors face acute shortages of engineers holding TS/SCI clearances required for classified waveform development.
- Backward compatibility requirements:New SDR platforms must maintain legacy narrowband interoperability, bloating software baselines and verification testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Communication System Market |
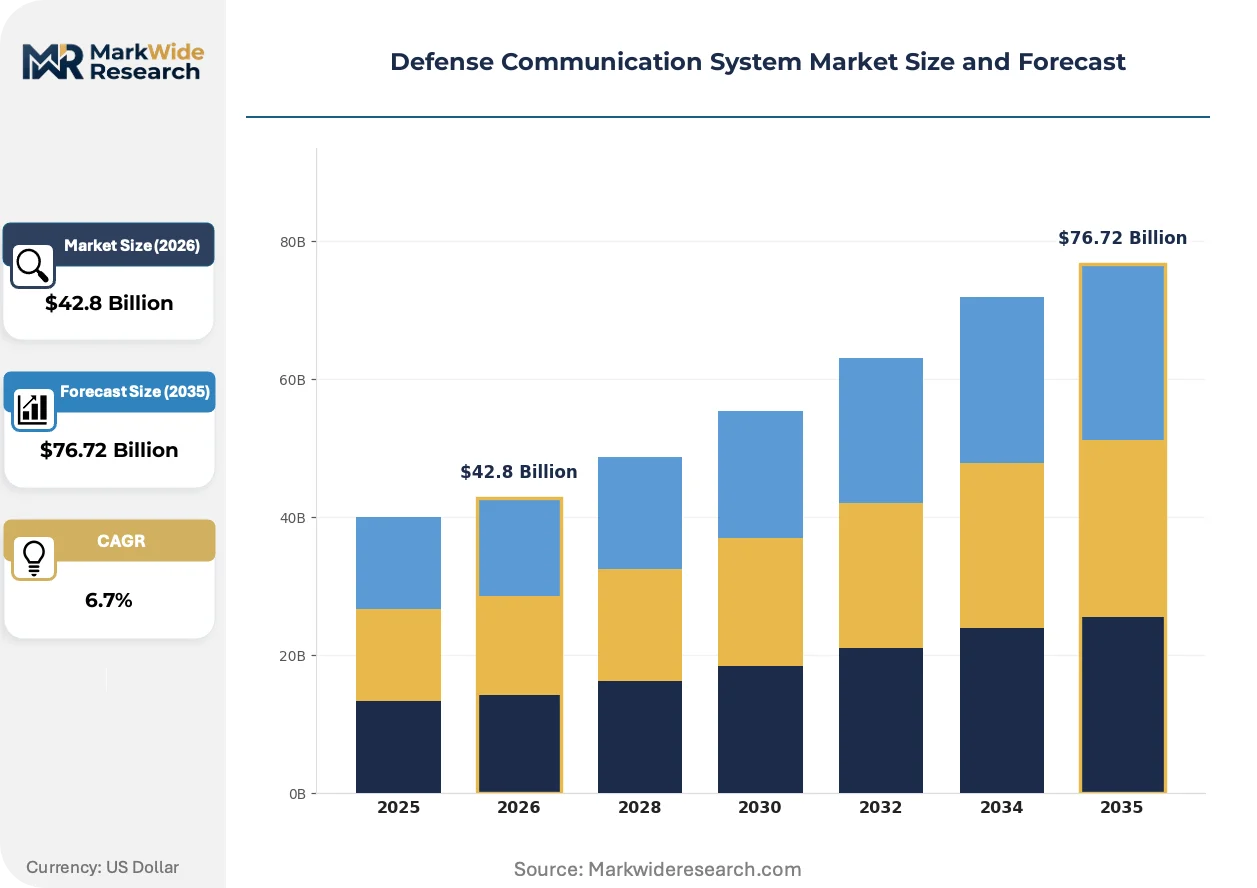
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $76.72 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
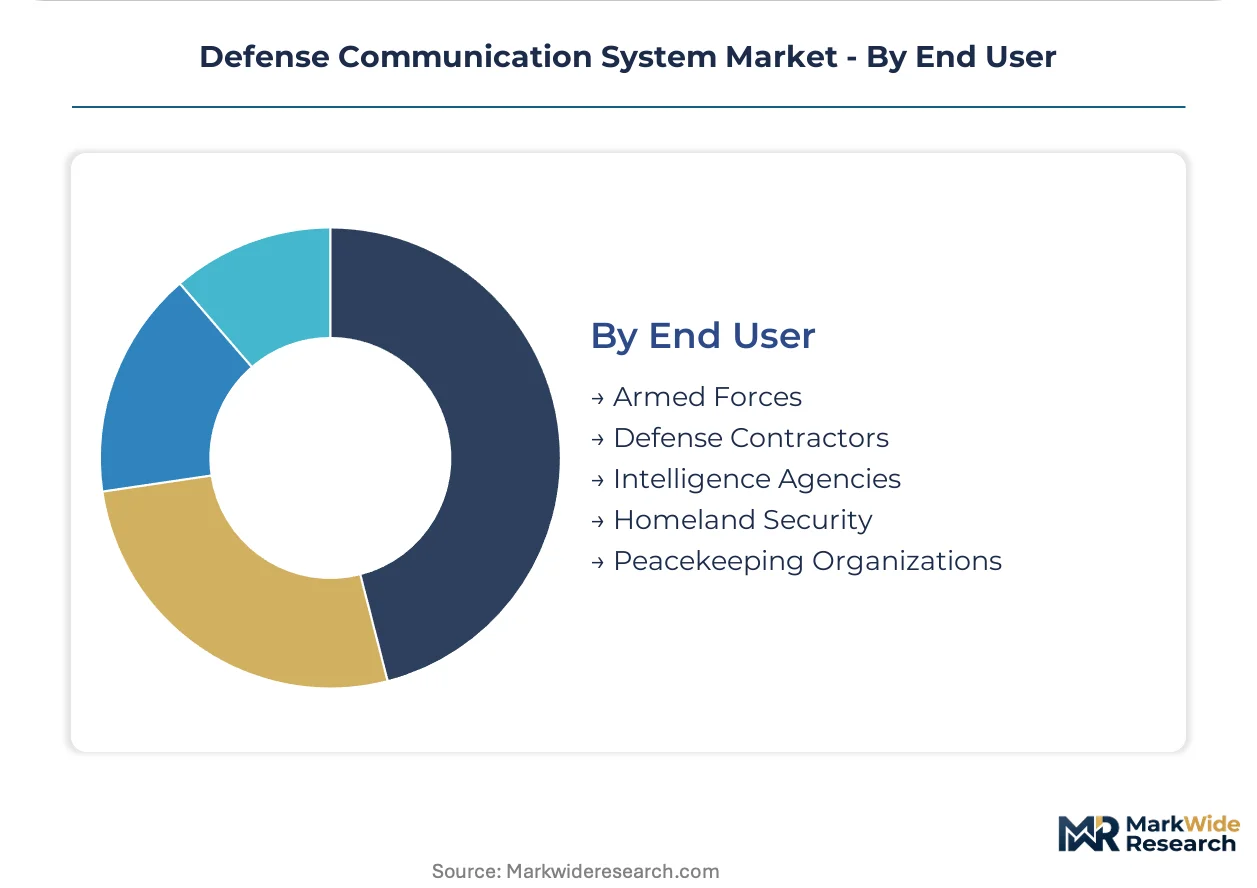
| Segmentation | Product Type: Radio Systems, Satellite Communication, Network-Centric Systems, Tactical Data Links, Command & Control Systems Technology: Software Defined Radio, Microwave Transmission, Laser Communication, IP-Based Communication, Digital Signal Processing Application: Battlefield Surveillance, Command Coordination, Secure Voice Transmission, Data Encryption, Remote Reconnaissance End User: Armed Forces, Defense Contractors, Intelligence Agencies, Homeland Security, Peacekeeping Organizations |
| Companies Covered | Airbus, Leonardo, L3Harris Technologies, General Dynamics, Elbit Systems, Thales, BAE Systems, Northrop Grumman, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Communication System Market Strategic Shifts & Innovations
Defense communication procurement is pivoting from platform-specific hardware to software-centric ecosystems, with waveform portability and cryptographic agility now determining competitive viability more than RF performance specifications alone.
Software-defined radio is collapsing the traditional separation between HF, VHF, and UHF hardware stacks into unified programmable transceivers. Marine expeditionary units and special operations commands are fielding single manpack units that reconfigure between satellite, terrestrial, and mesh networking modes within seconds. This compression is eliminating redundant logistics chains and obsoleting dedicated single-band inventory.
EU AI Act risk classification frameworks are extending to autonomous spectrum sensing algorithms embedded in tactical radios. Defense ministries in France and Germany must now document training data provenance and decision transparency for machine learning modules that select frequencies or detect hostile jamming. European SDR developers are responding by partitioning AI functions into modular, certifiable subsystems rather than monolithic firmware.
Consolidated enterprise buying is displacing unit-level procurement across allied defense forces. British Army and Royal Navy communication contracts now route through Defence Digital as single enterprise agreements, compressing vendor count and extending payment terms. Australia mirrors this pattern through the Defence Strategic Review's centralized ICT procurement reforms, concentrating purchasing power with prime integrators.
Defense Communication System Market Segmentation
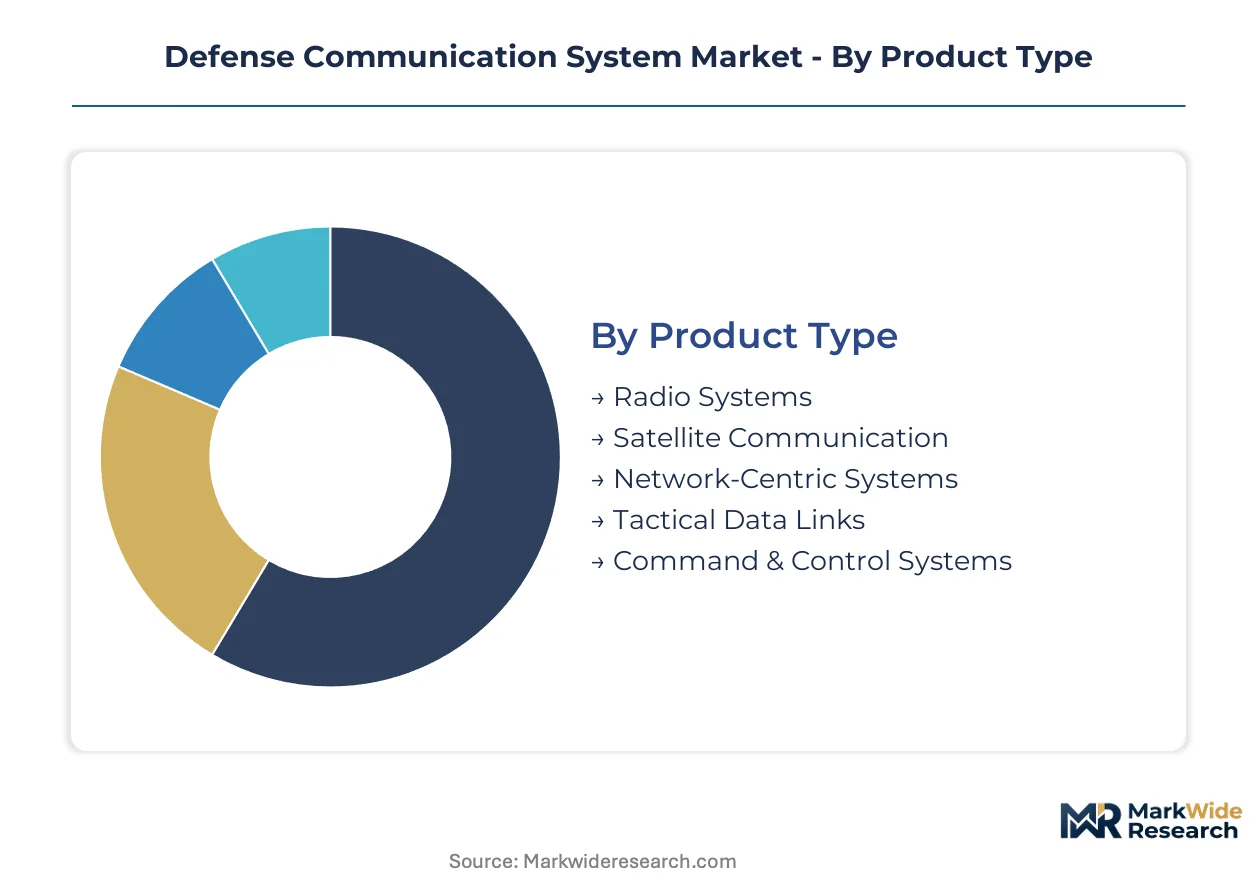
Defense communication procurement cycles vary dramatically across product categories, with tactical radios refreshing every 7-10 years while satellite infrastructure spans 15-20 year lifecycles. Understanding these replacement rhythms helps suppliers align R&D investment with predictable budget windows and certification milestones.
Product Type:
Radio Systems turn over fastest due to obsolescence pressure from spectrum reallocation and encryption upgrades, while Command & Control Systems exhibit the longest deployment cycles tied to platform integration timelines.
- Radio Systems:Handheld, vehicular, and airborne transceivers operating across HF through UHF bands with programmable waveforms. Demand clusters in United States Army modernization programs and British Army Morpheus initiatives, driven by STANAG 4372 interoperability mandates requiring compatible procurement across NATO allies.
- Network-Centric Systems:IP-based tactical networks enabling data fusion across dismounted soldiers, sensors, and command nodes. Australian Defence Strategic Review procurement concentrates here, with AUKUS-aligned trilateral certification requirements shaping vendor selection criteria.
- Satellite Communication:Terminals and modems for military Ka, X, and UHF satellite bands including emerging LEO constellation integration.
- Tactical Data Links:Standardized message formats and protocols for real-time exchange of track, target, and status data between platforms.
- Command & Control Systems:Integrated decision-support infrastructure linking sensors, shooters, and commanders across operational theaters.
Radio Systems dominate installed base across NATO inventories. Network-Centric Systems are where expansion concentrates as militaries shift from platform-centric to information-centric warfare doctrines.
Technology:
Cost tier differentiation separates premium software-defined architectures from commodity microwave backhaul, with procurement budgets bifurcating between transformational waveform programs and sustainment of legacy transmission infrastructure.
- Software Defined Radio:Reconfigurable transceiver platforms supporting multiple waveforms through firmware updates rather than hardware replacement. United States Special Operations Command and Marine expeditionary units prioritize manpack SDR units that switch between satellite, terrestrial, and mesh modes within seconds, collapsing logistics chains previously requiring separate single-band inventory.
- Digital Signal Processing:Computational modules enabling adaptive filtering, error correction, and spectrum sensing in contested electromagnetic environments. Israeli Defense Forces and allied export markets concentrate procurement here, driven by requirements for operation in dense jamming conditions.
- Microwave Transmission:Point-to-point and point-to-multipoint links for backbone communications and relay applications.
- Laser Communication:Free-space optical links offering high bandwidth and low probability of intercept for satellite and airborne applications.
- IP-Based Communication:Packet-switched networking protocols replacing circuit-switched legacy architectures in tactical environments.
Software Defined Radio captures premium pricing tiers. Digital Signal Processing is climbing fastest as artificial intelligence integration demands expand computational throughput requirements.
Application:
Volume concentration follows operational tempo, with Command Coordination systems deployed at every echelon while Remote Reconnaissance applications serve specialized units with limited procurement quantities.
- Command Coordination:Voice, data, and video networks enabling real-time decision-making across distributed headquarters and forward operating bases. British Army and Royal Navy enterprise contracts route through Defence Digital as single agreements, compressing vendor count and extending payment terms for integrators capable of unified service delivery.
- Secure Voice Transmission:Encrypted narrowband and wideband communications for tactical and strategic levels. United States FCC spectrum allocations and NIST post-quantum cryptography standards are accelerating replacement cycles before cryptanalytic vulnerabilities materialize.
- Battlefield Surveillance:Sensor networks and unattended ground sensors transmitting target and environmental data.
- Data Encryption:Cryptographic modules and key management infrastructure protecting classified information at rest and in transit.
- Remote Reconnaissance:Beyond-line-of-sight datalinks for unmanned systems and special operations teams.
Command Coordination represents the largest procurement volume. Secure Voice Transmission is gaining share fastest as quantum-resistant encryption transition compresses replacement timelines.
End User:
Customer type determines certification pathway complexity, with Armed Forces requiring full NATO interoperability validation while Intelligence Agencies operate under separate compartmentalized security protocols.
- Armed Forces:Army, navy, air force, and marine corps services requiring interoperable tactical and strategic communications. United States, United Kingdom, and Australia concentrate demand through joint-alliance exercises that drive common technical standards and pooled procurement.
- Defense Contractors:Prime integrators and subsystem suppliers requiring development and test infrastructure. Cleared workforce scarcity constrains this segment, with acute shortages of engineers holding TS/SCI clearances required for classified waveform development.
- Intelligence Agencies:National technical means and human intelligence operations with specialized security requirements.
- Homeland Security:Border security, emergency response, and critical infrastructure protection agencies.
- Peacekeeping Organizations:United Nations and coalition forces requiring rapidly deployable communications in austere environments.
Armed Forces anchor procurement volume across all product categories. Defense Contractors represent the steepest expansion trajectory as governments outsource integration complexity to prime vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli defense electronics flow into NATO allied inventories through trilateral procurement frameworks, while Australian demand channels through AUKUS-aligned certification requirements. United States waveform standards propagate through joint exercises, embedding technical specifications into allied procurement cycles.
United States
Army modernization programs and Special Operations Command drive manpack radio procurement with multi-domain interoperability requirements. FCC spectrum allocations and NIST post-quantum cryptography standards compress replacement timelines for legacy tactical systems. Huntsville, Alabama and San Diego, California host concentrated defense electronics clusters where prime integrators co-locate with military test facilities.
United Kingdom
British Army Morpheus initiatives and Royal Navy enterprise contracts route through Defence Digital as unified procurement agreements. Ministry of Defence STANAG certification requirements mandate waveform compatibility with NATO allied forces. Bristol and Portsmouth anchor submarine and surface vessel communication system integration, with supply chains extending into Scottish electronics manufacturing.
Australia
Canberra's Defence Strategic Review prioritizes integrated communication systems requiring trilateral US-UK-Australian certification. Department of Defence procurement guidelines favor AUKUS-aligned technical standards for joint-alliance operability. Adelaide and Canberra concentrate systems integration activity, with Western Australian facilities supporting Indo-Pacific expeditionary force requirements.
Germany
Bundeswehr digitalization programs and NATO collective defense commitments drive software-defined radio procurement across army and air force services. BSI federal cybersecurity regulations and EU AI Act risk classifications shape certification pathways for autonomous spectrum management modules. Munich and Ulm host RF component manufacturing clusters serving European defense primes.
Israel
Israel Defense Forces operational tempo and export-oriented defense industry sustain demand for ruggedized tactical terminals and electronic warfare-resistant waveforms. Israeli Ministry of Defense procurement maintains independent technical standards while aligning with select NATO interoperability protocols. Haifa and Beersheba concentrate defense electronics R&D, with Negev Desert test ranges validating contested-environment performance.
Defense Communication System Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. Prime integrators with cleared workforce access and NATO certification authority capture enterprise-level contracts, while subsystem specialists secure component supply positions. Two strategic archetypes dominate: waveform-portfolio holders leveraging software-defined architectures, and encryption-module specialists anchoring European supply security. Competitive moves concentrate on strategic partnerships for spectrum access and technology licensing for quantum-resistant cryptographic integration.
Within the prime integrator tier, L3Harris Technologies and Thales occupy positions defined by waveform certification breadth and NATO encryption module supply respectively. Elbit Systems exemplifies the export-oriented specialist archetype, with ruggedized terminal portfolios shaped by Israeli Defense Forces operational requirements. General Dynamics and BAE Systems represent platform-embedded communication system integrators, with positions tied to vehicle and naval manufacturing line integration.
| Leading Market Players |
|---|
| Airbus |
| Leonardo |
| L3Harris Technologies |
| General Dynamics |
| Elbit Systems |
| Thales |
| BAE Systems |
| Northrop Grumman |
| Raytheon Technologies |
| Others |
Cost & Logistics Intelligence
GaN and GaAs substrate fabrication concentrates in Taiwan and South Korean foundries, concentrating margin capture with RF component suppliers while defense primes absorb downstream integration risk and certification cost burdens.
Pricing Analysis
Next-generation software-defined radio platforms command 40-60% premiums over legacy narrowband hardware, while prior-generation inventory liquidates at distressed valuations through secondary defense markets. Three-tier pricing structure across premium SDR architectures, standard programmable transceivers, and economy legacy replacements dominates procurement frameworks. Price differentiation stems from NATO STANAG 4372 certification tier and waveform portfolio breadth. Cost compression in standard-tier hardware intensifies as commercial 5G component reuse expands. Intelligence agencies and special operations commands exhibit lowest price sensitivity due to mission-critical performance requirements, while peacekeeping organizations face acute budget constraints.
Supply Chain Analysis
TSMC and Samsung Foundry hold concentrated capacity for GaN-on-SiC RF power amplifiers, with ASE Technology and Amkor providing advanced packaging for defense-grade thermal cycling requirements. Taiwan, South Korea, and the United States anchor upstream semiconductor fabrication. Supply chains draw from gallium nitride epitaxial wafers, ceramic packaging substrates, and cryptographically secure firmware modules. Single-source vulnerability in advanced foundry access represents structural risk given export control restrictions on 14nm and below processes. Distribution runs through prime integrator direct contracts with national defense procurement offices, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat business where NATO STANAG certification authority creates entrenched switching costs that compound over multi-decade program lifecycles.
For Market Incumbents: Insulate waveform portfolio positions through accelerated NIST post-quantum cryptography integration before replacement cycles peak. Pursue backward integration into GaN RF component supply through captive foundry partnerships in allied geographies. Threat of cleared workforce scarcity demands immediate certification pipeline investments. Channel control through Defence Digital enterprise agreements represents the critical lever for British and Australian market access. For New Entrants and Emerging Players: AI-enabled spectrum management modules for contested electromagnetic environments represent the most penetrable entry point, as established primes underinvest in machine learning firmware architectures. Australian AUKUS-aligned tenders requiring trilateral certification create accessible procurement windows for specialist subsystem vendors. Satellite-terrestrial hybrid terminals for expeditionary forces offer secondary white-space opportunity. Go-to-market positioning through prime integrator subcontracting relationships bypasses direct NATO certification barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense electronics platforms lacking quantum-resistant encryption roadmaps. Long-term viability centers on waveform software recurring revenue models displacing transactional hardware sales. Acquisition targets with TS/SCI-cleared engineering benches and existing NATO C3 Agency validation records command structural scarcity premiums. Signal to watch is FCC spectrum reallocation decisions compressing replacement timelines for legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Integration | NIST post-quantum standards accelerate replacement cycles across NATO tactical radio inventories. |
| LEO Satellite Constellation Partnership | Starlink and OneWeb terminal integration creates new expeditionary product categories for special operations. |
| Cleared Workforce Pipeline Investment | TS/SCI engineering scarcity constrains classified waveform development capacity across all primes. |
| GaN RF Component Backward Integration | Taiwan and South Korean foundry concentration creates supply security vulnerability for defense primes. |
| Enterprise Procurement Channel Control | Defence Digital and Australian centralized ICT reforms concentrate purchasing power with certified integrators. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NATO procurement databases, FCC spectrum allocation filings, and defense ministry budget appropriations documentation. Primary interviews engaged program managers at United States Special Operations Command, British Army Morpheus initiative leads, and Australian Defence Strategic Review implementation officers. Secondary validation drew from NIST cryptographic standards publications, STANAG specification repositories, and congressional defense appropriations subcommittee records. Bottom-up unit shipment modeling triangulated against top-down national defense communication budget allocations.
Forecast inputs include software-defined radio refresh cycles, quantum-resistant encryption mandate implementation timelines, and AUKUS trilateral procurement alignment progress. Modeled segmentation spans product type, technology generation, application mission profile, and end-user security classification tier. CAGRs derive from replacement rhythm analysis tied to platform obsolescence curves and interoperability certification milestone schedules. Industry-specific inputs incorporate FCC spectrum reallocation probability assessments and NATO collective defense spending commitment trajectories across the analysis window.
Practitioners should monitor NIST post-quantum cryptography standard finalization, Taiwan semiconductor export control policy shifts, and Australian Defence Strategic Review tender award patterns for early signals of forecast revision. Assumptions reflect current NATO interoperability mandates, cleared workforce availability projections, and allied defense budget growth commitments. Quarterly review of STANAG certification backlog durations and GaN substrate spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Flight Tracking System Market