
 Military Aircraft Avionics Market | 2026-2036
Military Aircraft Avionics Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Avionics Market Intelligence
The defense procurement channel is narrowing as prime contractors consolidate subsystem sourcing. Honeywell International Inc. leverages its integrated flight control portfolio to anchor long-term platform contracts. L3Harris Technologies Inc. competes aggressively in communications and electronic warfare segments. Thales Group sustains its position through European sovereign programs and export-oriented radar systems.
Military aircraft avionics encompass the electronic systems governing flight management, situational awareness, communications, and threat response in armed forces aircraft, typically operating across MIL-STD-1553 and MIL-STD-1760 data bus architectures with hardened components rated for electromagnetic interference and nuclear event survivability. Flight control systems dominate current procurement volumes as fly-by-wire retrofits expand across aging fighter fleets. Electronic warfare systems represent the fastest-expanding technology segment as peer-conflict scenarios drive demand for integrated electronic attack and self-protection suites. Communications systems concentrate margin pools where software-defined radio implementations enable multi-band, multi-mode interoperability without hardware swaps.
The FAA and DOD shape U.S. market access through airworthiness certification and cybersecurity mandates under DFARS 252.204-7012, while EU Green Deal emissions benchmarks and CE marking requirements influence European platform integration timelines. India's BIS and CDSCO equivalent standards for defense imports, alongside Israel's MOD procurement directives, create fragmented but navigable compliance landscapes for international suppliers. Stakeholders must monitor which regulatory frameworks platform integrators prioritize in next-generation combat aircraft solicitations.
Market Dynamics
Platform integrators now consolidate subsystem sourcing around software-defined architectures, compressing supplier tiers and privileging vendors with integrated flight control-to-mission system portfolios. This procurement narrowing is reshaping competitive positioning across NATO modernization programs.
Growth Catalysts
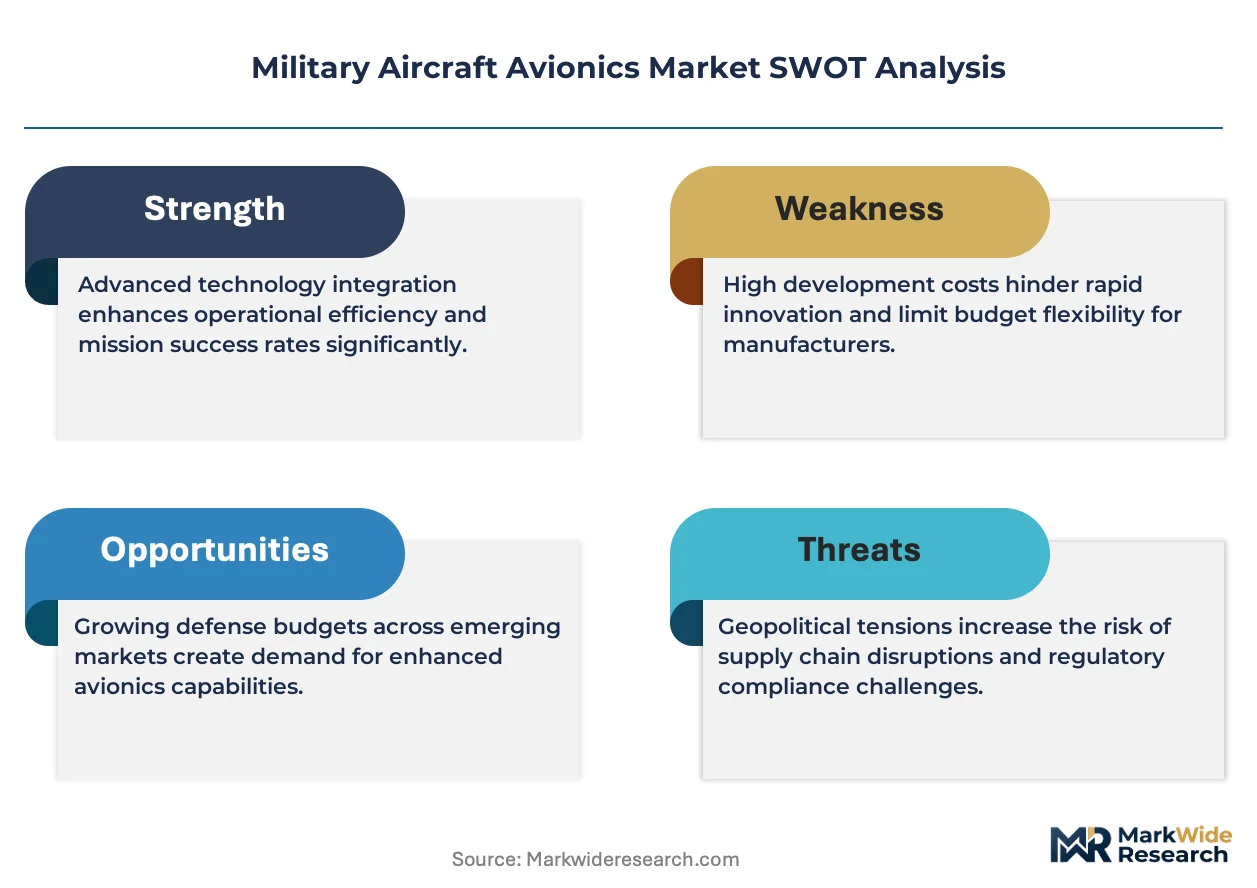
- DFARS 252.204-7012 cybersecurity mandates:U.S. DOD procurement specifications now require hardened supply chain attestations, accelerating vendor consolidation toward primes with pre-certified architectures.
- Peer-conflict scenario planning:NATO member states prioritize electronic warfare suite integration, driving demand for self-protection systems in fighter retrofit programs.
- GPS-denied navigation:Alternative positioning technologies are displacing legacy INS-GPS dependencies in contested environment doctrine, opening procurement for magnetic navigation and celestial aiding systems.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet dependencies for motor actuators and sensors concentrate in Chinese processing facilities, creating input cost volatility and sovereign risk exposure.
- MIL-STD-1553 legacy architecture lock-in:Aging platform data bus standards impose technical limitations on bandwidth and interoperability, forcing expensive bridge hardware for new sensor integration.
- EU Green Deal emissions benchmarks:Platform lifecycle carbon accounting requirements add compliance friction to European fleet modernization timelines, stretching procurement cycles.
Strategic Opportunities
- Indian defense import localization:BIS and DGFT indigenization mandates create white space for joint venture avionics assembly, particularly in flight control computers and display processors.
- Software-defined radio convergence:Multi-band waveform flexibility is hybridizing with cognitive electronic attack capabilities, enabling single-box replacements for discrete legacy radios and jammers.
- Israeli MOD export-oriented procurement:Ministry of Defense directives prioritizing combat-proven subsystem exports create channel innovation through government-to-government bundled avionics packages.
Industry Challenges
- DO-178C and DO-254 certification timelines:Civil-military dual-use software and hardware assurance standards impose 18-36 month validation cycles, compressing development windows for iterative upgrades.
- Systems engineering talent scarcity:Flight control law development and safety-critical software verification functions face acute skill gaps as aerospace engineering pipelines shift toward commercial autonomy.
- Legacy platform integration complexity:Fly-by-wire retrofits onto 1970s airframe architectures require bespoke mechanical-to-digital interface development, fragmenting engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Avionics Market |
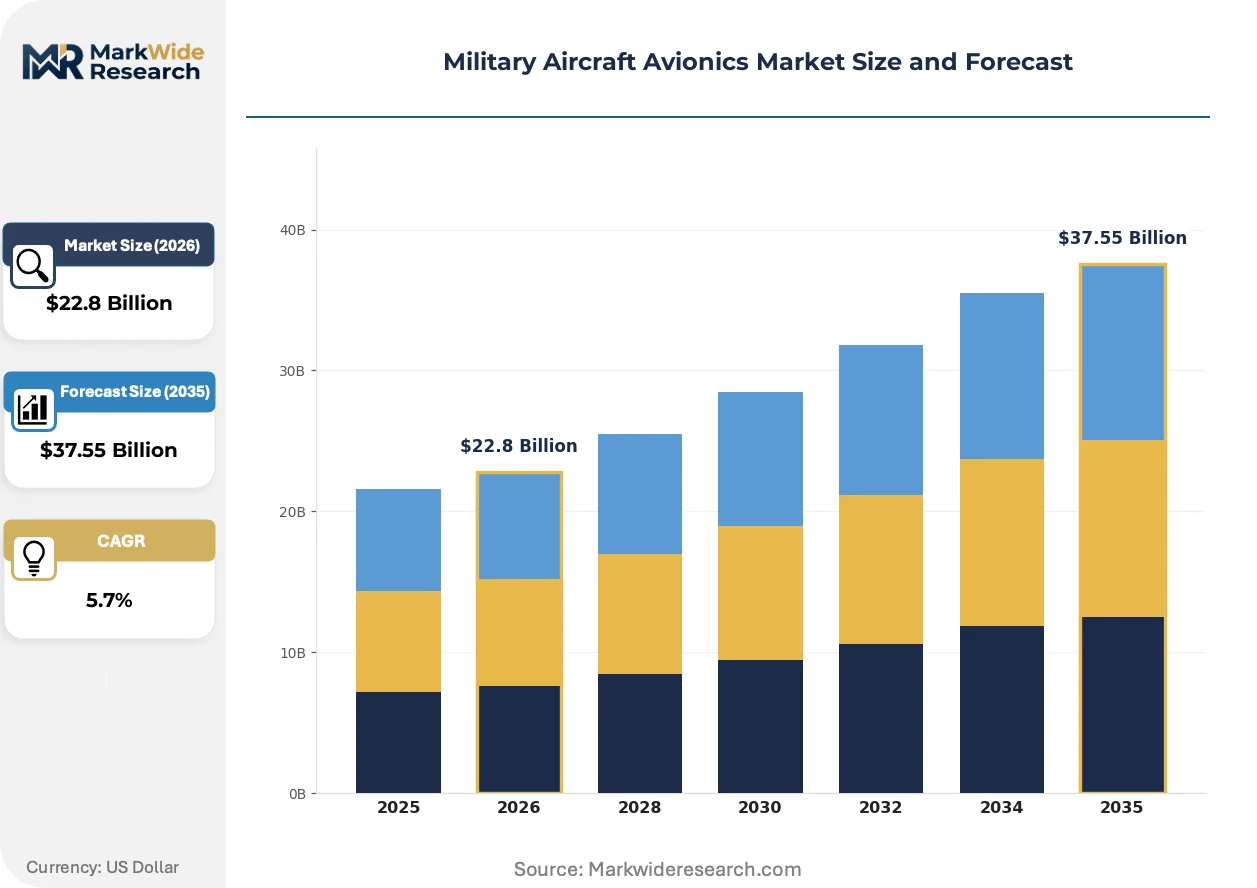
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Systems, Communications Systems, Navigation Systems, Electronic Warfare Systems Technology: Software-Defined Radio, GPS, Inertial Navigation, Radar Technology End User: Defense Forces, Government Agencies, Private Contractors, International Military Installation: Retrofit, Line Fit, Upgrade, Refresh |
| Companies Covered | Honeywell International Inc., L3Harris Technologies Inc., Thales Group, BAE Systems, RTX Corporation, Northrop Grumman Corporation, Leonardo S.p.A., Elbit Systems Ltd., Curtiss-Wright Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Avionics Market Strategic Shifts & Innovations
Avionics architectures are compressing discrete functions into federated computing fabrics, with hardware abstraction layers enabling software-only capability upgrades. This consolidation is displacing federated black-box paradigms that dominated fourth-generation fighter designs.
Open systems architecture standards are hybridizing proprietary military computing with commercial semiconductor roadmaps. U.S. Army Future Vertical Lift and U.S. Air Force Next Generation Air Dominance programs mandate modular open systems approaches, enabling competitive subsystem swapping without platform recertification. This technology convergence is compressing prime contractor margin capture in traditionally captive upgrade cycles.
EU AI Act risk classification frameworks are extending to autonomous targeting and sensor fusion algorithms, creating new validation burdens for machine-learning-enabled electronic warfare systems. European platform integrators must demonstrate human oversight and traceability for AI-driven threat response. Combat aircraft segments with planned loyal wingman or unmanned collaborative teaming architectures face the steepest compliance ramps.
Defense procurement offices are unbundling long-term sustainment from initial platform acquisition, creating discrete competitions for avionics obsolescence management and incremental capability insertion. U.S. Naval Air Systems Command and UK Defence Equipment and Support now structure separate performance-based logistics contracts for mission computer and display system refresh. This buying-pattern shift is most visible in F-35 and Eurofighter Typhoon fleet management programs, where sovereign partners negotiate independent software update authority.
Military Aircraft Avionics Market Segmentation
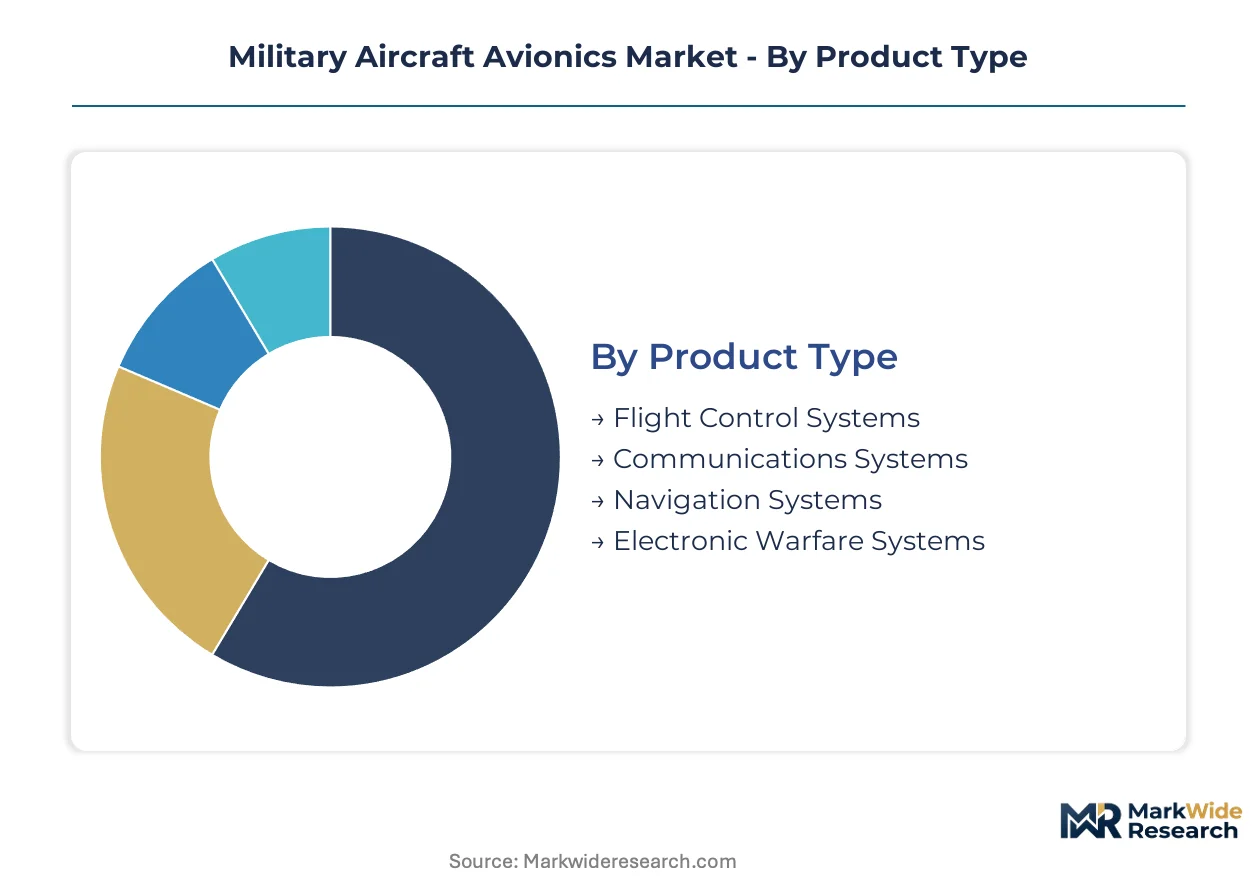
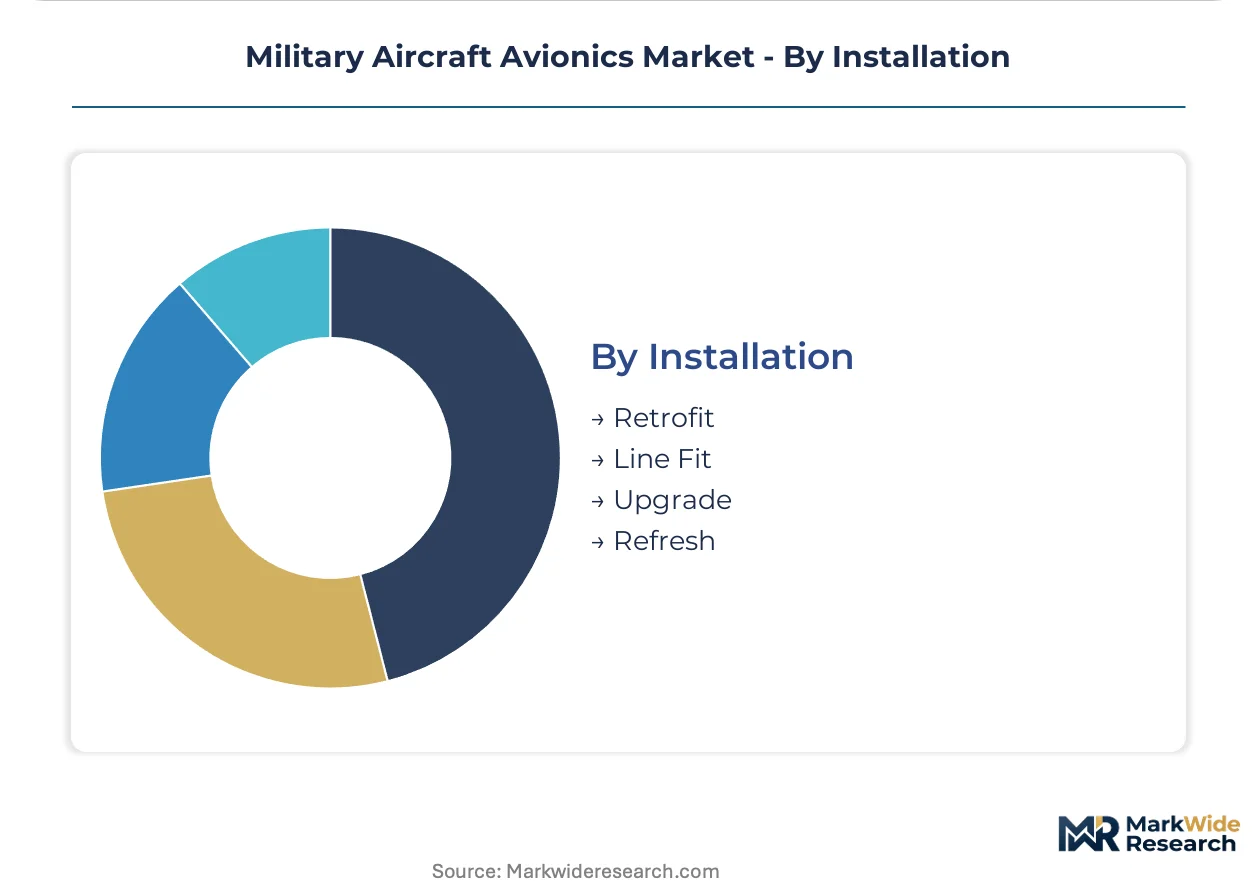
Avionics procurement patterns diverge sharply across product architectures, technology maturity, and installation contexts. Platform integrators configure subsystem portfolios differently for new production lines versus aging fleet sustainment, creating distinct competitive arenas within each segment axis.
Product Type:
Mature fly-by-wire implementations coexist with emerging electronic warfare suites as procurement priorities shift from flight safety to contested-environment survivability.
- Flight Control Systems:Digital fly-by-wire architectures with triple-redundant processing channels govern aircraft stability and maneuver authority. NATO fighter retrofit programs in the United States and the United Kingdom concentrate procurement volumes as aging mechanical linkages reach obsolescence thresholds.
- Electronic Warfare Systems:Integrated electronic attack and self-protection suites combine radar warning receivers with active jamming and decoy dispensers. Israeli MOD export directives and U.S. peer-conflict scenario planning accelerate demand for cognitive jamming capabilities against frequency-agile threats.
- Communications Systems:Multi-band, anti-jam datalinks and voice channels operating across VHF through Ku-band.
- Navigation Systems:Hybrid INS-GPS architectures with magnetic and celestial aiding for GPS-denied environments.
Flight control systems retain volume leadership; electronic warfare systems hold the steepest expansion curve.
Technology:
Cost tiers separate legacy hardware-defined implementations from software-reconfigurable platforms that compress upgrade cycles.
- Software-Defined Radio:FPGA-based waveform processors enable multi-band, multi-mode communications through software updates alone. U.S. Army Future Vertical Lift mandates and UK sovereign communications programs drive procurement toward open-architecture SDR implementations that displace discrete legacy radios.
- Radar Technology:Active electronically scanned arrays with gallium nitride transmit-receive modules deliver multi-function performance. Israeli combat-proven AESA exports and U.S. Next Generation Air Dominance requirements concentrate investment in scalable aperture designs.
- GPS:Military-code receivers with anti-spoofing and anti-jam enhancements.
- Inertial Navigation:Ring laser gyro and fiber optic gyro platforms with drift compensation.
Radar technology commands premium pricing tiers; software-defined radio expands most quickly across platform categories.
End User:
Customer type determines certification rigor and procurement channel structure, from sovereign defense ministries to outsourced fleet management.
- Defense Forces:National military branches with platform-integrated procurement authority and long-term sustainment obligations. U.S. Naval Air Systems Command performance-based logistics contracts and UK Defence Equipment and Support separate avionics refresh competitions from initial platform acquisition.
- International Military:Foreign military sales and direct commercial sales channels with sovereign technology release constraints. Indian BIS localization mandates and Israeli government-to-government bundled packages reshape supplier engagement models.
- Government Agencies:Coast guard, border patrol, and paramilitary aviation units with dual-use certification paths.
- Private Contractors:Outsourced fleet operators and training platform providers with commercial derivative aircraft.
Defense forces dominate committed procurement volumes; international military sales gain share fastest as indigenous production mandates proliferate.
Installation:
Application context separates green-field line-fit opportunities from complex retrofit engineering with airframe-specific integration constraints.
- Retrofit:Post-production avionics replacement onto operational aircraft with bespoke mechanical-to-digital interface development. F-35 partner nation sovereign software update negotiations and Eurofighter Typhoon national capability insertion programs exemplify retrofit complexity.
- Line Fit:Factory-integrated avionics specified during original platform production with prime contractor subsystem consolidation. U.S. Air Force Next Generation Air Dominance modular open systems mandates compress traditional captive upgrade cycles.
- Upgrade:Mid-life capability insertion with partial subsystem replacement.
- Refresh:Obsolescence-driven like-for-like replacement with form-fit-function constraints.
Retrofit installations absorb the largest engineering resource allocation; line-fit opportunities concentrate margin capture for integrated portfolio vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States and Israeli procurement channels, where combat-proven subsystem exports command premium terms. European sovereign programs operate under stricter cost ceilings imposed by EU Green Deal compliance and fragmented national budgets. Emerging procurement channels in India and Japan reshape traditional supplier engagement models through localization mandates and technology transfer requirements.
United States
U.S. Naval Air Systems Command structures performance-based logistics contracts for F-35 fleet avionics refresh, separating sustainment from initial acquisition. DFARS 252.204-7012 cybersecurity mandates harden supply chain attestations toward pre-certified prime architectures. Greater Phoenix and Dallas-Fort Worth aerospace clusters concentrate flight control computer development and military-code GPS receiver production for Next Generation Air Dominance programs.
United Kingdom
UK Defence Equipment and Support unbundles Eurofighter Typhoon avionics obsolescence management into discrete sovereign software update competitions. Ministry of Defence procurement specifications prioritize software-defined radio implementations for multi-band interoperability across Joint Strike Fighter and Tempest platforms. Bristol and Lancashire engineering centers anchor BAE Systems integration work for NATO collaborative combat aircraft architectures.
Israel
Israeli Ministry of Defense directives prioritize combat-proven electronic warfare suite exports through government-to-government bundled packages. MOD procurement channels channel AESA radar and self-protection system development toward foreign military sales eligibility. Haifa and Beersheba defense technology corridors concentrate Elbit Systems and Rafael integration facilities for cognitive jamming and magnetic navigation subsystems.
India
Indian Air Force MiG-21 and Jaguar fleet modernization drives demand for fly-by-wire retrofits and display processor replacements under BIS and DGFT indigenization mandates. Defense Acquisition Council rules require minimum 50% local content for avionics imports above threshold contract values. Bengaluru and Hyderabad aerospace clusters host joint venture assembly for flight control computers and inertial navigation platforms.
Japan
Japan Ministry of Defense F-X fighter program specifications mandate modular open systems architectures compatible with U.S. interoperability standards. METI industrial policy directs avionics subsystem sourcing toward domestic suppliers with technology licensing pathways from allied primes. Nagoya and Komaki manufacturing bases concentrate Mitsubishi Heavy Industries integration work for radar and electronic warfare suite development.
Military Aircraft Avionics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in narrower margin pools. The supplier base compresses around vendors with integrated flight control-to-mission system portfolios capable of pre-certified DFARS architectures. Three archetypes dominate: diversified aerospace conglomerates with captive avionics divisions, pure-play defense electronics specialists, and sovereign champions serving national procurement channels. Competitive dynamics center on strategic partnerships for technology licensing and backward integration into sensor and processing hardware.
Within the diversified conglomerate tier, Honeywell International Inc. and RTX Corporation exemplify integrated portfolio positioning across flight control and navigation domains. L3Harris Technologies Inc. occupies a specialist position in communications and electronic warfare segments. Thales Group anchors European sovereign program access through radar and mission system integration. These three represent distinct competitive vectors: U.S. prime contractor consolidation, communications-centric specialization, and continental European national champion status.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| L3Harris Technologies Inc. |
| Thales Group |
| BAE Systems |
| RTX Corporation |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| Curtiss-Wright Corporation |
| Others |
Cost & Logistics Intelligence
Greater Phoenix aerospace clusters concentrate flight control computer manufacturing capacity, creating downstream pricing leverage for vendors with pre-certified DFARS 252.204-7012 architectures against buyers facing cybersecurity compliance deadlines.
Pricing Analysis
Configured-to-order pricing for mission-specific avionics suites commands substantial premiums over standard catalog configurations. Three-tier pricing structure across combat-proven, NATO-qualified, and commercial-derivative certification levels reflects differentiation by airworthiness pedigree and sovereign technology release tiers. Cost compression in commercial-derivative segments is intensifying because platform integrators unbundle sustainment from initial acquisition. Defense forces with sovereign software update authority exhibit lowest price sensitivity; outsourced fleet operators face acute margin pressure.
Supply Chain Analysis
Export-control regimes under ITAR and EAR restrict gallium nitride semiconductor and ring laser gyro component flows to non-allied nations. Manufacturing concentrates in the United States, Israel, and the United Kingdom for AESA radar modules; China dominates rare earth magnet processing for motor actuators. Permanent magnet dependencies create single-source vulnerability for fighter retrofit programs. Distribution runs through prime contractor consolidated sourcing with tier-one subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined radio architectures threaten to commoditize legacy hardware-defined communications suites, forcing incumbents to defend integration value around pre-certified cybersecurity attestations.
For Market Incumbents: Harden DFARS 252.204-7012 pre-certification moats through backward integration into FPGA waveform processing hardware. Anchor long-term platform contracts by bundling flight control computers with sovereign software update authority. Combat open systems architecture mandates that compress traditional captive upgrade cycles. For New Entrants and Emerging Players: Indian joint venture assembly for flight control computers under BIS and DGFT indigenization mandates represents the most penetrable entry point for foreign suppliers. Israeli government-to-government bundled export channels offer second-mover access to combat-proven subsystem markets. Pursue technology licensing pathways from allied primes rather than green-field certification investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified aerospace conglomerates with integrated flight control-to-mission system portfolios capable of modular open systems compliance. Long-term viability hinges on capturing sovereign software update authority in F-35 and Eurofighter Typhoon fleet management programs. Watch for EU AI Act risk classification enforcement as inflection indicator for autonomous targeting algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| DFARS Cybersecurity Pre-Certification | Hardened supply chain attestations anchor prime contractor consolidation toward pre-certified architectures under U.S. DOD mandates. |
| Software-Defined Radio Convergence | FPGA-based waveform processors displace discrete legacy radios through multi-band flexibility in U.S. Army Future Vertical Lift programs. |
| Indian Joint Venture Localization | BIS and DGFT indigenization mandates create white space for flight control computer assembly in Bengaluru aerospace clusters. |
| Sovereign Software Update Authority | Unbundled sustainment contracts separate avionics refresh competitions from initial platform acquisition in F-35 partner nations. |
| GPS-Denied Navigation Development | Magnetic and celestial aiding systems displace legacy INS-GPS dependencies in contested environment doctrine procurement. |
Research Approach
The analysis maps flight control systems, electronic warfare suites, communications architectures, and navigation platforms, each validated through program managers at U.S. Naval Air Systems Command, UK Defence Equipment and Support procurement officers, Israeli MOD export directors, and Indian Defense Acquisition Council officials. Primary fieldwork combined with secondary validation from MIL-STD-1553 and MIL-STD-1760 specification databases, DFARS cybersecurity directive filings, EU AI Act risk classification frameworks, and BIS localization mandate records. Bottom-up platform procurement tracking and top-down defense budget allocation analysis provide triangulation.
Assumptions held fixed include NATO member state fleet modernization commitment levels and Chinese rare earth processing capacity; varied parameters encompass EU Green Deal compliance friction and Indian indigenization enforcement intensity. Segmentation dimensions span product architecture, technology maturity tier, end-user procurement channel, and installation context across the projection horizon. CAGRs derive from platform production forecasts weighted by avionics content per aircraft and retrofit cycle timing. Forecast inputs include F-35 partner nation sovereign software update negotiations and Eurofighter Typhoon national capability insertion program timelines.
Practitioners should monitor ITAR/EAR export control expansion and EU AI Act enforcement ramps for early signals of supply chain disruption or compliance burden escalation. Forecasts reflect these documented assumptions regarding defense procurement continuity and allied technology sharing frameworks. Material shifts in Chinese rare earth export restrictions or NATO collective defense spending commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Electronic Flight Instrument System Market
Avionics
Aircraft EMI Shielding Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Display for Avionics Application Market
Avionics
Customized Avionic Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Aerospace Avionics Market
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Avionics LRU Repair and Test Services Market