
 Europe Commercial Aircraft in-Flight Entertainment System Market | 2026-2036
Europe Commercial Aircraft in-Flight Entertainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Aircraft in-Flight Entertainment System Market Foresight
Aftermarket service revenue is tilting toward software-defined content delivery platforms as hardware refresh cycles lengthen across European airline fleets. Thales Group leverages its Toulouse engineering base to sustain dominance in line-fit AVOD architectures for Airbus platforms. Panasonic Avionics Corporation anchors its European position through dedicated MRO facilities in London Heathrow's supplier cluster. Collins Aerospace differentiates via integrated connectivity suites that bundle Ka-band satellite links with seatback streaming endpoints.
Europe Commercial Aircraft in-Flight Entertainment Systems comprise seatback displays, wireless streaming servers, content management platforms, and satellite connectivity terminals engineered to deliver audio, video, and interactive services at altitudes exceeding 10,000 meters. These systems employ ARINC 429 and Ethernet avionics protocols to interface with aircraft cabin management computers while meeting DO-160G environmental testing standards for electromagnetic interference and rapid decompression scenarios. AVOD configurations retain the largest installed base among European flag carriers, though streaming-centric architectures without dedicated seatback hardware are gaining share among ultra-low-cost operators seeking reduced weight and simplified maintenance. Retrofit installations represent the fastest-growing installation category as aging A320ceo and 737NG fleets receive cabin modernization ahead of lease-end transitions.
EASA's cabin equipment certification framework, combined with EU Cybersecurity Act requirements for connected aviation systems, elevates compliance costs for non-European suppliers seeking market access. REACH chemical restrictions and RoHS electronics standards further constrain component sourcing for display assemblies and printed circuit boards deployed across European-registered aircraft. Stakeholders must monitor the interplay between EASA's evolving connectivity bandwidth allocations and airline content licensing models as satellite constellation density reshapes real-time streaming economics.
Market Dynamics
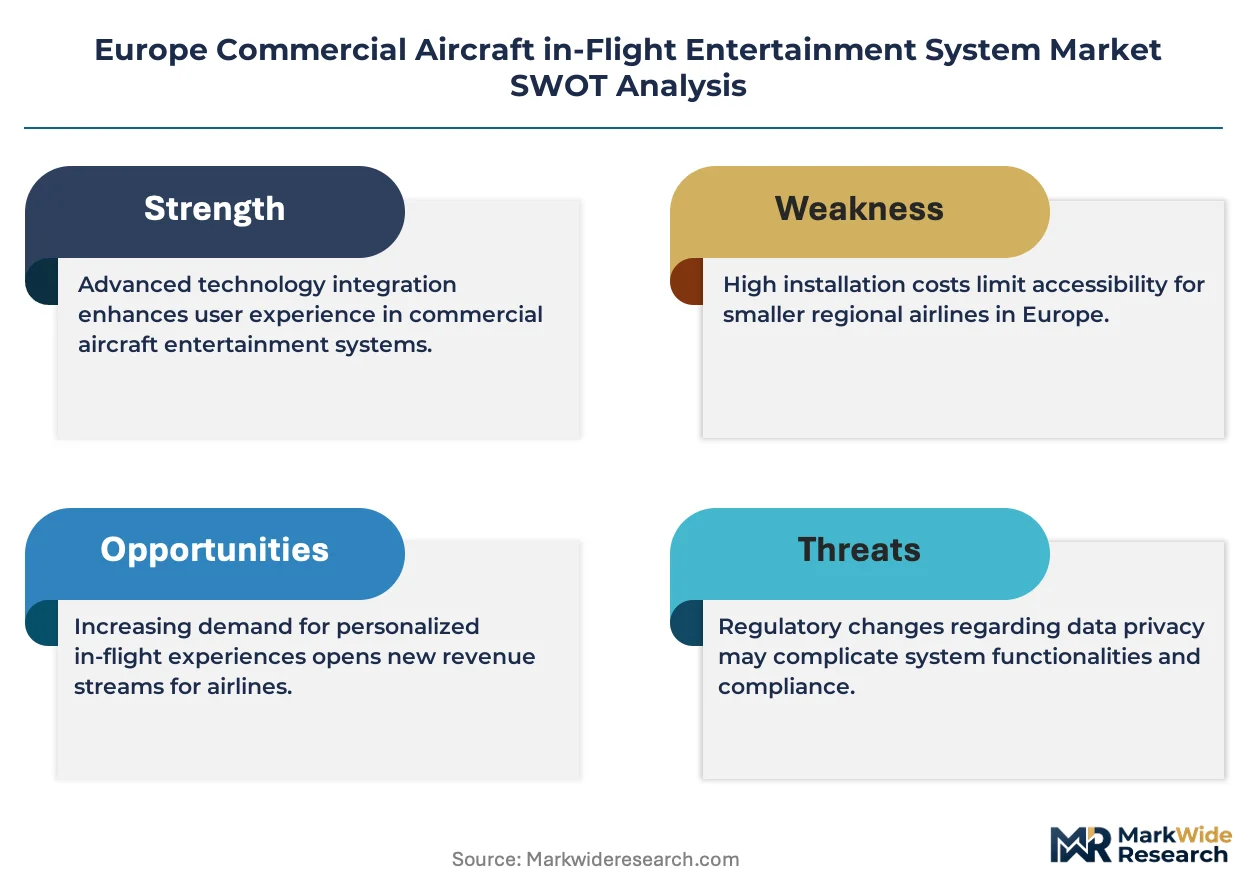
EASA's cybersecurity certification mandates for connected cabin systems are compressing supplier qualification timelines and forcing hardware-software decoupling in European airline procurement cycles.
Growth Catalysts
- Ka-band satellite density:Low Earth orbit constellation expansion across European airspace is enabling real-time streaming economics that favor wireless IFE architectures over seatback hardware.
- REACH and RoHS compliance:Chemical and electronics standards are filtering out non-compliant Asian component suppliers, creating protected market access for certified European integrators.
- Narrowbody fleet modernization:Eastern European low-cost carriers are accelerating retrofit schedules for aging A320ceo aircraft ahead of lease-end transitions and resale preparation.
Market Restraints
- Display panel supply concentration:Active-matrix OLED and high-brightness LCD sourcing depends on concentrated Asian fabrication capacity, exposing European integrators to shipping volatility and tariff exposure.
- EASA certification backlog:Cybersecurity validation protocols for connected cabin systems extend hardware approval timelines by twelve to eighteen months versus legacy disconnected architectures.
- Wireless streaming substitution:Passenger-owned device prevalence is eroding airline willingness to fund seatback screen installation and maintenance on short-haul routes under two hours.
Strategic Opportunities
- Polish and Romanian carrier expansion:Ultra-low-cost operators in these markets remain underpenetrated by streaming-centric IFE platforms, presenting first-mover positioning for Ka-band bundled offerings.
- EU Cybersecurity Act tailwinds:Common Criteria certification requirements for aviation IoT systems create compliance barriers that favor established European suppliers with Toulouse and Hamburg engineering presence.
- Content-as-a-service convergence:Licensing platform integration with predictive analytics engines enables per-passenger personalization that hardware-locked AVOD cannot match.
Industry Challenges
- Embedded systems cybersecurity expertise:Aviation software engineers with DO-178C and ARINC 653 safety-critical certification command salary premiums that strain mid-tier supplier staffing models.
- Legacy aircraft integration complexity:Retrofit installation on A320ceo and 737NG fleets requires custom wiring harness fabrication and cabin management computer interface adaptation that prolongs aircraft downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Aircraft in-Flight Entertainment System Market |
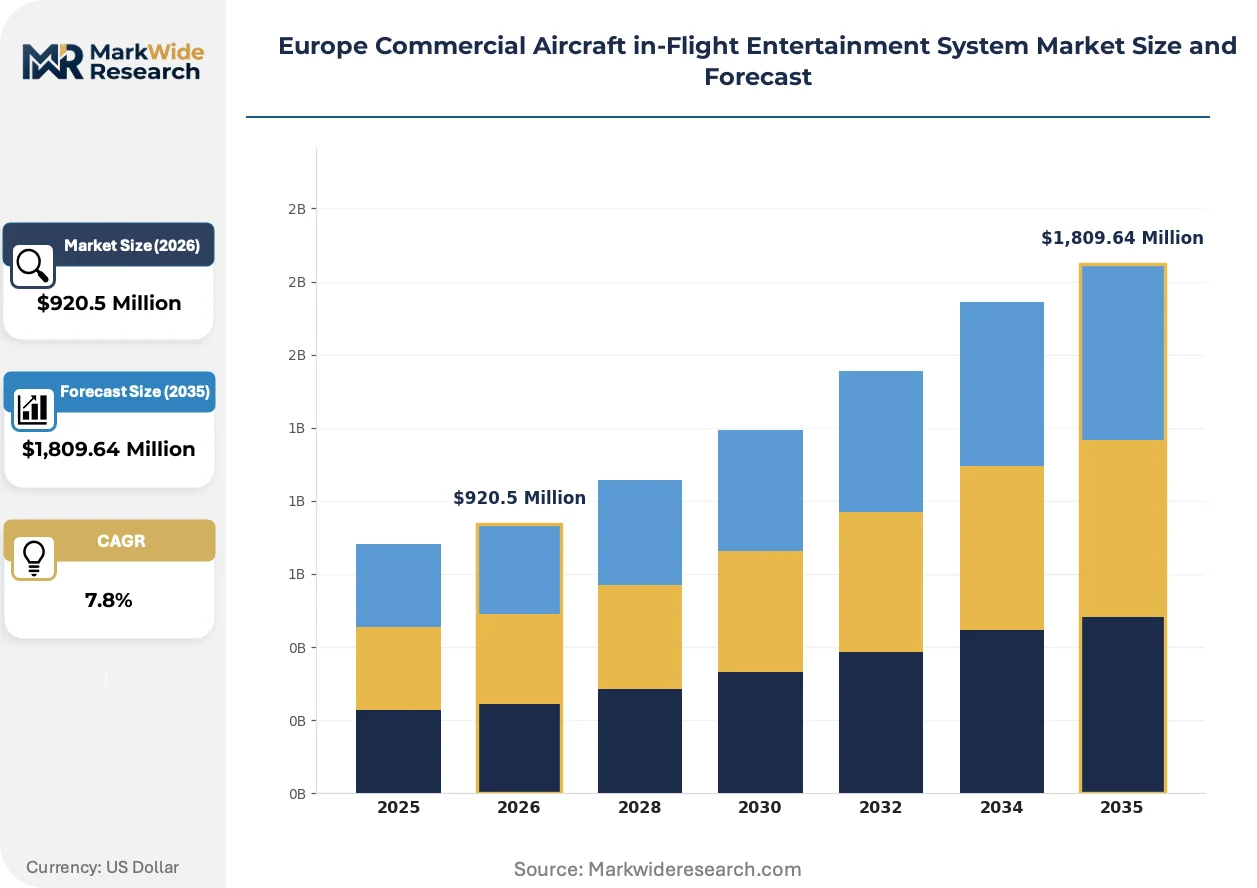
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,809.64 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AVOD, SVOD, Live Television, In-Flight Gaming Technology: Streaming, Satellite-based, Wi-Fi, In-Flight Connectivity End User: Airlines, Charter Services, Private Jets, Cargo Operators Installation: Line-fit, Retrofit, Upgrades, Custom Solutions |
| Companies Covered | Thales Group, Panasonic Avionics Corporation, Collins Aerospace, Safran SA, Burrana, Latecoere, Northern Avionics srl, IMAGIK International Corp, Donica Aviation Engineering Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Aircraft in-Flight Entertainment System Market Shifts & Advancements
Software-defined content delivery is collapsing the traditional hardware refresh cycle, compressing airline capital deployment from seven-year replacement schedules toward continuous software subscription models.
Edge computing nodes deployed in galley-located servers are collapsing the latency gap between seatback and streaming architectures, enabling ultra-low-cost carriers to eliminate display hardware while preserving interactive gaming and live television functionality. Wizz Air and Ryanair procurement teams are evaluating these architectures for 2025 narrowbody deliveries.
EU Cybersecurity Act implementation through EASA delegated authority is mandating Common Criteria EAL4+ evaluation for all cabin network equipment, forcing suppliers to re-engineer legacy streaming servers and extend certification budgets. French and German flag carriers are prioritizing pre-certified platforms to avoid program delays on A321XLR cabin fit-outs.
Airline technical procurement teams are consolidating vendor relationships around full-stack connectivity-entertainment bundles, displacing point-solution IFE specialists who lack satellite ground infrastructure partnerships. This pattern concentrates most visibly at Airbus final assembly lines in Toulouse and Hamburg, where line-fit decisions increasingly favor integrated Ka-band and streaming platform providers.
Europe Commercial Aircraft in-Flight Entertainment System Market Segmentation
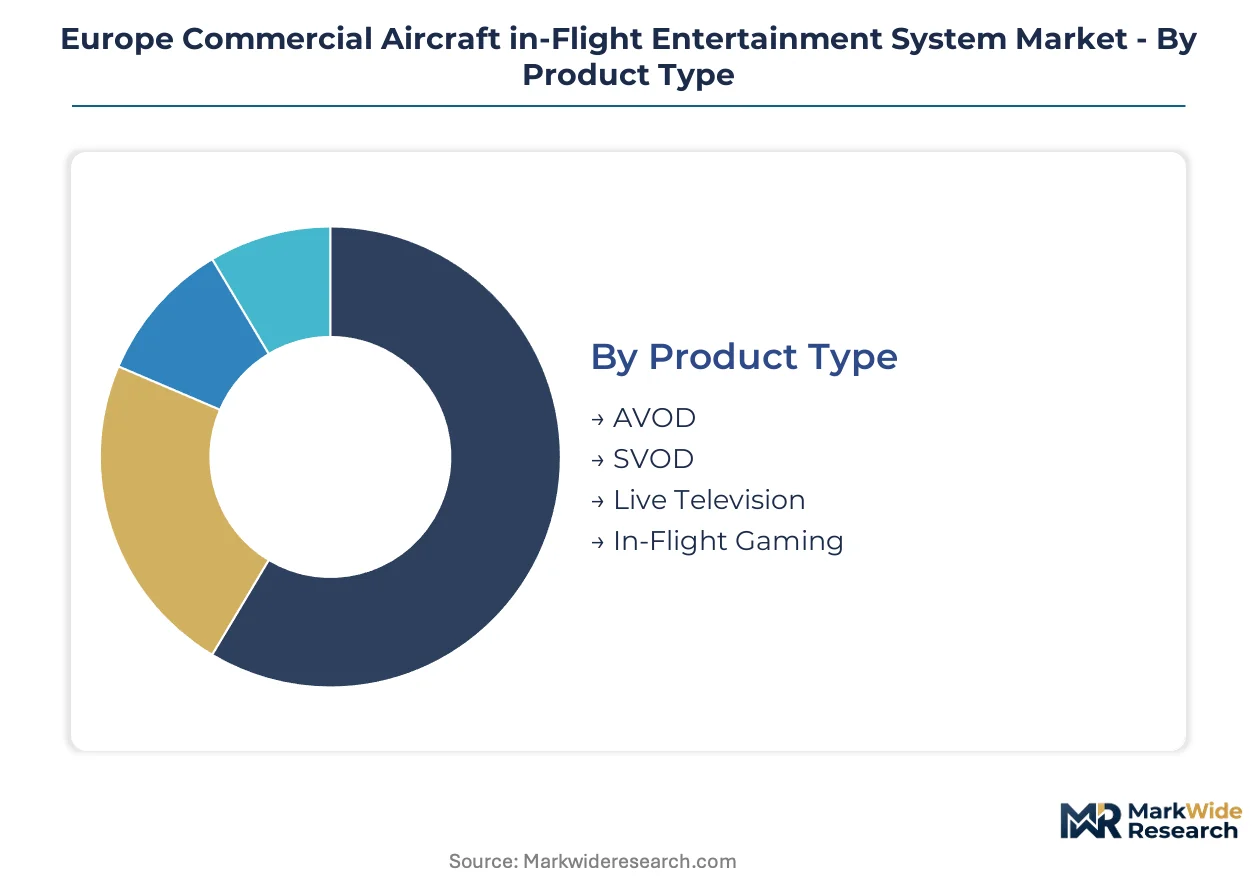
IFE procurement patterns diverge sharply across product architectures and installation modes. European carriers weight hardware-software bundles differently depending on fleet age, route economics, and EASA certification timelines for connected cabin systems.
Product Type:
Cost tier differentiation separates premium hardware-intensive platforms from lightweight streaming alternatives favored by budget operators.
- AVOD:Seatback displays with dedicated storage servers deliver on-demand libraries through ARINC 429 avionics interfaces. French and German flag carriers concentrate procurement for A321XLR line-fit programs where passenger experience justifies weight penalties.
- SVOD:Subscription-integrated streaming platforms bypass dedicated seatback hardware, reducing aircraft empty weight by 300-500 kilograms per narrowbody. Eastern European low-cost carriers in Poland and Romania are driving demand as they modernize A320ceo fleets ahead of lease transitions.
- Live Television:Real-time broadcast reception requires Ka-band satellite terminals and dedicated content licensing agreements.
- In-Flight Gaming:Interactive entertainment modules demand low-latency connectivity architectures and localized edge computing nodes.
AVOD commands the established base. The steepest expansion runs through SVOD.
Technology:
Application architecture determines whether content delivery depends on aircraft-installed hardware or passenger-owned devices.
- Streaming:Server-based content distribution to personal tablets and smartphones eliminates display maintenance costs. Wizz Air and Ryanair procurement teams are evaluating these architectures for narrowbody deliveries where reduced downtime drives operating economics.
- Satellite-based:Direct broadcast reception via Ku-band or Ka-band terminals enables live content independent of ground infrastructure. Demand concentrates in transatlantic routes where over-ocean connectivity gaps persist.
- Wi-Fi:Cabin wireless access points create local networks for cached content distribution without satellite dependency.
- In-Flight Connectivity:Integrated communication suites bundle entertainment with operational data links and passenger broadband.
Satellite-based systems retain the widest route coverage. Streaming architectures are climbing the fastest as hardware refresh cycles compress.
End User:
Customer type dictates certification urgency and customization depth across the procurement spectrum.
- Airlines:Scheduled carriers dominate volume, with narrowbody fleet operators in France, Germany, and the UK driving line-fit integration schedules at Airbus final assembly lines. EASA cybersecurity mandates are extending qualification timelines for connected cabin deployments.
- Charter Services:Seasonal operators require rapid reconfiguration capabilities between leisure and corporate mission profiles.
- Private Jets:Business aviation clients demand bespoke interfaces and premium content licensing tiers.
- Cargo Operators:Freighter conversions occasionally retain passenger cabin infrastructure for combi operations or crew rest provisions.
Airlines command the established base. The steepest expansion runs through Charter Services as Eastern European leisure markets mature.
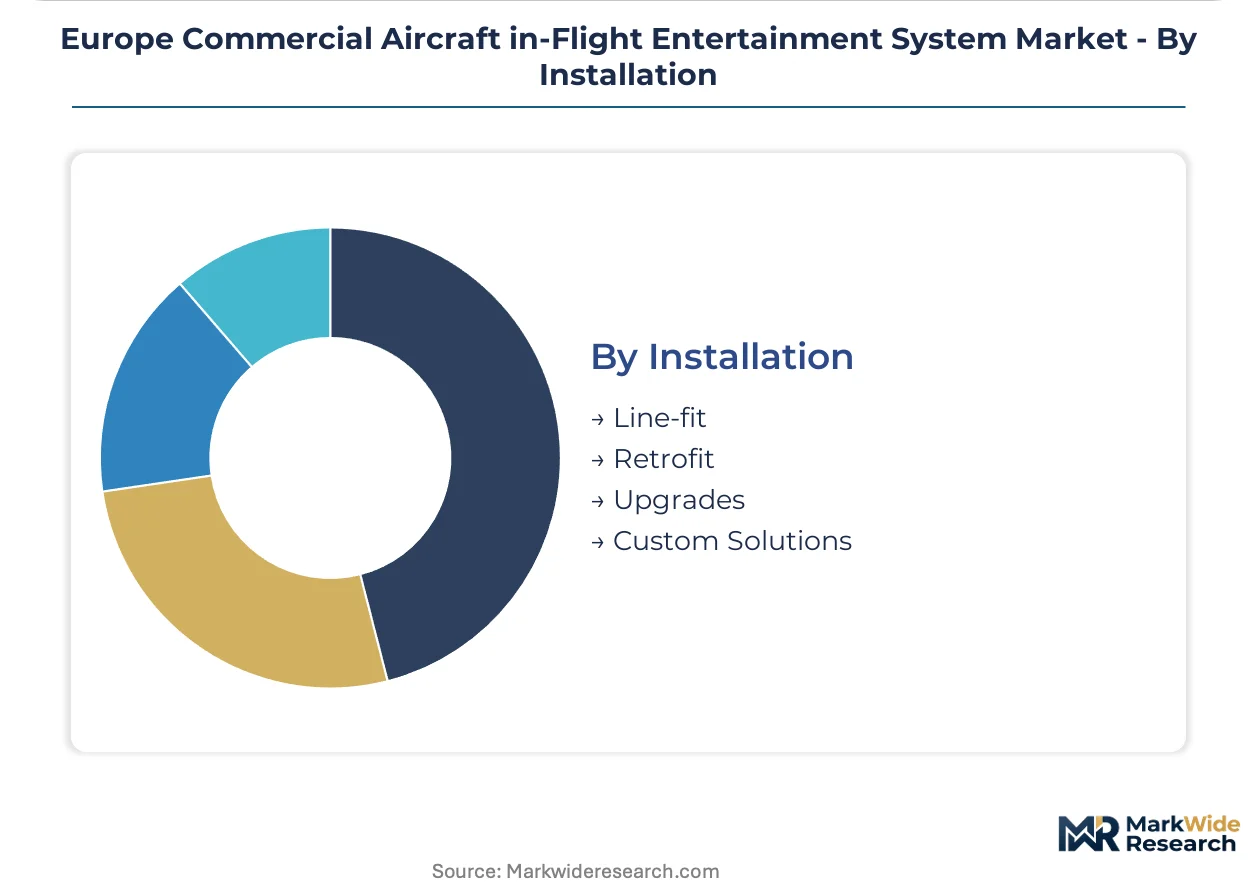
Installation:
Volume concentration shifts toward retrofit activity as aging narrowbody fleets approach mid-life cabin modernization.
- Line-fit:Factory-integrated systems at Toulouse and Hamburg final assembly lines offer lowest total installed cost and shortest delivery timelines. Airbus procurement consolidation favors suppliers with integrated connectivity-entertainment bundles.
- Retrofit:Post-delivery installation on A320ceo and 737NG fleets requires custom wiring harness fabrication and cabin management computer adaptation. Eastern European carriers are accelerating these programs ahead of lease-end transitions and resale preparation.
- Upgrades:Mid-life hardware refreshes extend system viability without full architecture replacement.
- Custom Solutions:Bespoke configurations serve VIP and head-of-state aircraft with unique security and interface requirements.
Line-fit commands the established base. The steepest expansion runs through Retrofit as fleet renewal cycles lag behind cabin experience demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern European low-cost carriers demonstrate the highest price elasticity, deferring seatback hardware investments until lease-end transitions force modernization decisions. Western European flag carriers absorb premium AVOD costs without volume contraction. France and Germany concentrate line-fit procurement power at Airbus final assembly locations.
France
Airbus Toulouse final assembly lines drive concentrated demand for factory-integrated AVOD systems on A321XLR programs. EASA cybersecurity mandates through delegated EU Cybersecurity Act authority extend supplier qualification timelines. The Occitanie aerospace cluster around Toulouse-Blagnac anchors Thales Group engineering resources for line-fit integration schedules.
Germany
Lufthansa Group fleet renewal programs sustain premium hardware procurement despite industry-wide streaming migration. REACH and RoHS compliance requirements filter component sourcing through certified European supply chains. The Hamburg Airbus final assembly line concentrates procurement decisions for narrowbody line-fit configurations.
United Kingdom
British Airways and Virgin Atlantic maintain AVOD commitments on long-haul fleets while evaluating streaming architectures for short-haul subsidiaries. CAA alignment with EASA cybersecurity protocols creates regulatory coherence for cross-border operations. London Heathrow's supplier cluster hosts Panasonic Avionics Corporation MRO facilities serving transatlantic route equipment.
Poland
Wizz Air and LOT Polish Airlines accelerate A320ceo retrofit schedules ahead of lease-end transitions and secondary market resale preparation. EU Cybersecurity Act implementation creates compliance barriers favoring established European integrators over non-certified competitors. Warsaw Chopin Airport maintenance bases concentrate cabin modernization activity for Eastern European operator networks.
Romania
Ryanair subsidiary Buzz and Blue Air legacy fleet positions drive demand for lightweight streaming architectures without seatback hardware. EASA certification backlog for connected cabin systems delays new entrant market access. Bucharest Henri Coandă International Airport technical bases support rapid reconfiguration capabilities for seasonal charter operators.
Europe Commercial Aircraft in-Flight Entertainment System Market Competitive Landscape
Full-stack connectivity-entertainment bundlers and point-solution IFE specialists split the market along integration depth lines. Consolidation pressure concentrates procurement decisions at Airbus final assembly lines in Toulouse and Hamburg, where line-fit schedules favor suppliers with satellite ground infrastructure partnerships. Three archetypes dominate: European engineering-centric integrators with EASA certification heritage, Asia-Pacific hardware fabricators with display panel supply advantages, and connectivity-first platforms leveraging Ka-band constellation density. Competitive moves center on strategic partnerships with satellite operators and portfolio diversification into predictive analytics-enabled content licensing.
Within the European engineering-centric tier, Thales Group and Collins Aerospace exemplify full-stack positioning through Toulouse and Hamburg engineering presence. Panasonic Avionics Corporation anchors the connectivity-integrated archetype with dedicated European MRO infrastructure. Safran SA occupies a position spanning cabin systems integration with aerospace equipment manufacturing heritage. These three represent distinct strategic postures without implying specific market share claims or operational details beyond their evident geographic and structural characteristics.
| Leading Market Players |
|---|
| Thales Group |
| Panasonic Avionics Corporation |
| Collins Aerospace |
| Safran SA |
| Burrana |
| Latecoere |
| Northern Avionics srl |
| IMAGIK International Corp |
| Donica Aviation Engineering Co Ltd |
| Others |
Supply & Pricing Matrix
Display panel fabrication concentration in South Korea and Taiwan directly determines margin distribution across European IFE integrators, with OLED and high-brightness LCD sourcing bottlenecks shifting value capture toward certified subsystem assemblers who control qualification timelines.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture as hardware refresh cycles extend beyond seven years. Three-tier pricing structure across premium, standard, and economy levels separates line-fit AVOD configurations from retrofit streaming architectures and bare-bones Wi-Fi-only offerings. Cost compression in entry-tier hardware is intensifying because Eastern European low-cost carriers prioritize weight reduction over interactive features. Ultra-low-cost operators exhibit the highest price sensitivity, while French and German flag carriers absorb premium positioning without volume contraction.
Supply Chain Analysis
Dual-use technology export controls on advanced display drivers and satellite communication chipsets constrain component flows from Asian fabrication hubs to European integrators. Active-matrix OLED substrates, Ka-band transceiver modules, and ARINC 429 avionics processors draw from concentrated manufacturing bases in South Korea, Japan, and Taiwan. Single-source vulnerability in OLED driver integrated circuits exposes integrators to allocation constraints during aerospace demand surges. Distribution runs through Airbus-approved supplier clusters at Toulouse-Blagnac and Hamburg Finkenwerder final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined content delivery platforms represent the fastest-expanding recurring-revenue layer, with subscription-based licensing outpacing seatback hardware sales as airlines prioritize operational flexibility over capital deployment.
For Market Incumbents: Build certification moats through EASA Common Criteria EAL4+ pre-validation for streaming server architectures. Deepen backward integration into edge computing node design to collapse latency advantages held by connectivity specialists. Ka-band satellite operator partnerships represent the critical lever for defending line-fit procurement decisions at Airbus final assembly lines. For New Entrants and Emerging Players: Polish and Romanian A320ceo retrofit programs represent the most penetrable entry point for streaming-centric IFE platforms without seatback hardware. Wizz Air and Buzz procurement evaluations for 2025 narrowbody deliveries offer a near-term anchor customer opportunity. A satellite-ground infrastructure partnership with established constellation operators provides the essential go-to-market credential. For Investors and Strategic Acquirers: Capital is best deployed toward European engineering-centric integrators with Toulouse or Hamburg physical presence and pre-certified cybersecurity platforms. The five-to-ten year viability window favors suppliers who have already absorbed EASA certification costs. Monitor EASA bandwidth allocation rulings for connected cabin systems as the inflection signal for real-time streaming economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Pre-Investment | EASA EAL4+ validation compresses supplier qualification timelines for Airbus line-fit programs. |
| Ka-band Satellite Partnership | Constellation density agreements enable real-time streaming architectures that displace seatback hardware. |
| Edge Computing Node Development | Localized server deployment collapses latency gaps between streaming and traditional AVOD systems. |
| Content-as-a-Service Platform Launch | Predictive analytics integration enables per-passenger personalization beyond hardware-locked libraries. |
| Retrofit Installation Capability Buildout | A320ceo and 737NG fleet modernization creates sustained demand outside factory line-fit channels. |
Research Methodology
A standing panel of airline technical procurement directors, avionics certification engineers, MRO facility managers, and satellite connectivity specialists provided ongoing calibration throughout the research cycle. Primary fieldwork combined structured interviews with secondary validation against EASA regulatory filings, Airbus supplier qualification databases, and customs records for avionics component trade flows. Bottom-up fleet installation modeling and top-down aerospace electronics market sizing were triangulated for convergence.
Scenario-bracketing around satellite constellation deployment timelines and narrowbody fleet renewal cycles bounded the projection range. Segmentation dimensions spanned product architecture, installation mode, technology type, and carrier business model across the analysis window. CAGRs were derived from installed base evolution and replacement rate assumptions, with specific inputs including EASA cybersecurity certification backlog estimates and Ka-band coverage expansion schedules.
Practitioners should monitor EASA delegated authority rulings on EU Cybersecurity Act implementation and LEO satellite operator bankruptcy filings for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Global Commercial Avionics Systems Market
Avionics
Display for Avionics Application Market
Avionics
Global Helicopter Avionics Market
Avionics
Aircraft EMI Shielding Market
Avionics
Global Avionics Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Military Avionic Systems Market
Avionics
Aircraft Computers Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Customized Avionic Systems Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
Commercial Electronic Flight Bag Market