
 Global Aerospace Bearings Market | 2026-2036
Global Aerospace Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Bearings Market Foresight
Power-by-the-hour leasing and asset-light fleet management is reshaping how airlines source aerospace bearings, shifting procurement risk toward MRO providers and tier-one distributors. SKF Group leverages its integrated service network to capture recurring revenue from long-term maintenance contracts. RBC Bearings specializes in engineered solutions for helicopter rotor systems and defense platforms. NTN Corporation anchors its position through captive supply relationships with Japanese airframe manufacturers.
Aerospace bearings are precision-engineered rolling-element or plain bearings manufactured from vacuum-melted steels, silicon nitride ceramics, or hybrid material stacks, designed to operate at temperatures exceeding 300°C while sustaining radial and axial loads in turbine engines and flight control systems. Roller bearings dominate commercial engine applications due to their load-carrying capacity and established FAA certification pathways. Ceramic technology is displacing metallic equivalents in next-generation geared turbofans where weight reduction and thermal stability command premium positioning. Self-lubricating bearings occupy niche but expanding roles in spacecraft and UAV propulsion where external lubrication is impractical.
FAA airworthiness directives and EASA certification specifications mandate traceable material sourcing and fatigue-life documentation for all safety-critical bearing installations. The EU Green Deal's sustainable aviation fuel mandates and noise regulations indirectly tighten bearing efficiency requirements by pushing engine OEMs toward higher bypass ratios and operating temperatures. Stakeholders must monitor how CSRD disclosure rules and emerging EPA emissions standards for aircraft engines reshape supplier qualification timelines and capital allocation toward certified ceramic bearing capacity.
Market Dynamics
Power-by-the-hour leasing contracts are compressing procurement cycles and transferring inventory risk from airlines to MRO networks, fundamentally restructuring how bearing specifications are negotiated and certified across the value chain.
Growth Catalysts
- Geared turbofan proliferation:Pratt & Whitney and Rolls-Royce next-generation engines demand silicon nitride ceramic bearings that withstand thermal loads exceeding 300°C, creating certified supplier pull-through.
- FAA airworthiness directives:Mandatory fatigue-life documentation for safety-critical installations is forcing fleet-wide replacement schedules that refresh installed bearing bases at predictable intervals.
- China's COMAC C919 ramp:Indigenous narrowbody production is localizing demand for ARJ21 and C919 engine and flight control bearings, concentrating procurement with domestic-qualified suppliers.
Market Restraints
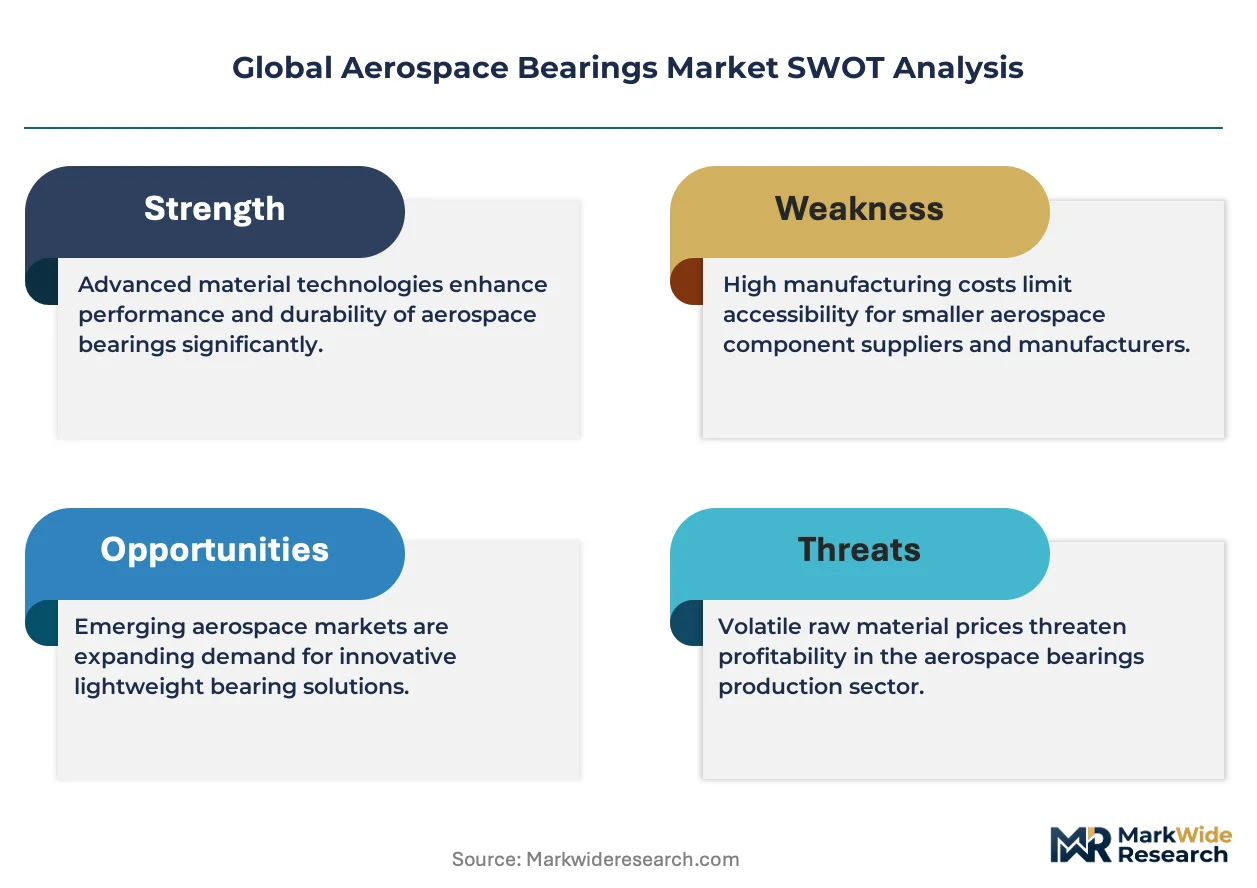
- Vacuum-melted steel supply concentration:Premium aerospace-grade steel production clusters in Germany, Japan, and the United States, exposing bearing manufacturers to alloying element price volatility and export licensing delays.
- EASA CS-25 certification timelines:Extended validation periods for new ceramic bearing architectures delay revenue recognition and tie up engineering resources across 18-36 month windows.
- Magnetic bearing substitution:Active magnetic bearing systems eliminate contact friction entirely in auxiliary power units and some turbine applications, threatening rolling-element penetration in sub-threshold load conditions.
Strategic Opportunities
- Urban air mobility platforms:eVTOL manufacturers require compact, lightweight bearings for tilt-rotor and distributed electric propulsion systems operating on 10,000+ cycle maintenance intervals.
- EU Green Deal SAF mandates:Sustainable aviation fuel compatibility requirements are pushing engine OEMs toward higher bypass ratios that demand thermally stable bearing materials with documented carbon footprint traceability.
- Additive manufacturing convergence:Hybrid bearing races produced through selective laser melting enable integrated cooling channels and weight-optimized geometries impossible with conventional machining.
Industry Challenges
- Metallurgical engineering talent scarcity:Vacuum induction melting and ceramic sintering expertise concentrates among retiring specialists, constraining capacity expansion at precision bearing foundries.
- Legacy fleet documentation gaps:Pre-digital bearing installation records complicate MRO traceability compliance under tightening FAA and EASA audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Bearings Market |
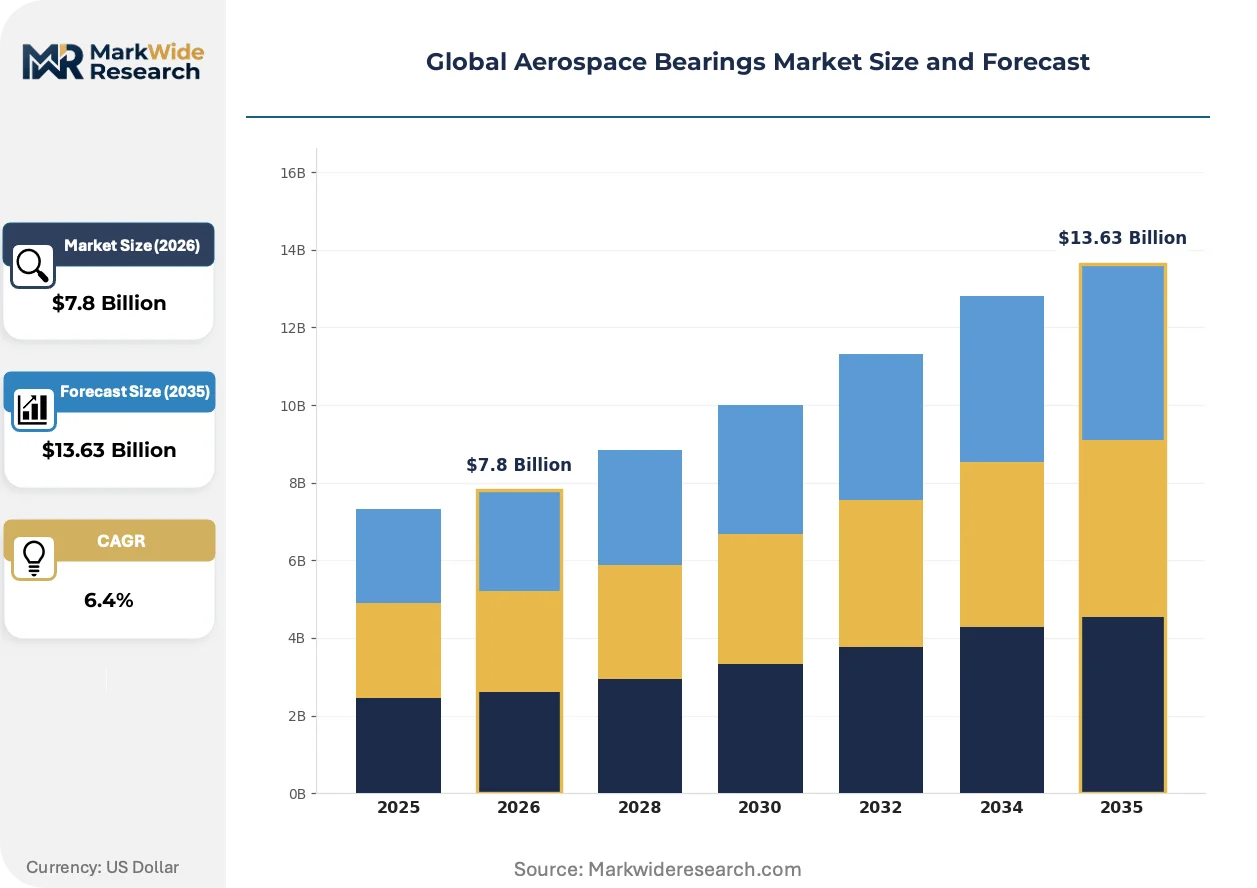
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Needle Bearings, Spherical Bearings Technology: Ceramic, Hybrid, Metallic, Magnetic, Self-Lubricating Application: Commercial Aircraft, Military Aircraft, Spacecraft, Helicopters, Unmanned Aerial Vehicles End User: OEMs, MRO Providers, Defense Contractors, Engine Manufacturers, Avionics Suppliers |
| Companies Covered | JTEKT Corporation, NSK Ltd., SKF Group, Kaman Corporation, RBC Bearings Incorporated, The Timken Company, NTN Corporation, National Precision Bearings, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Bearings Market Shifts & Advancements
Digital thread integration is collapsing the gap between design simulation and field performance data, enabling predictive maintenance models that redefine bearing lifecycle value.
Silicon nitride ceramic rolling elements are digitizing condition monitoring architectures by embedding fiber-optic temperature and vibration sensors directly into bearing races during sintering. Engine OEMs including GE Aerospace and Safran are qualifying these smart bearings for LEAP and Passport powerplants. Real-time telemetry is digitizing fleet management economics, allowing operators to extend overhaul intervals based on actual load history rather than conservative time-based schedules.
EU CSRD disclosure rules are mandating granular supply chain emissions reporting for all components above specified material thresholds, including aerospace bearings. Bearing manufacturers must now document Scope 3 carbon intensity from vacuum-melted steel and ceramic powder sourcing through to end-of-life recycling. German and French tier-one suppliers are responding by consolidating procurement with ISO 14064-certified material providers and investing in electric furnace upgrades.
Airline engineering departments are unbundling bearing procurement from engine OEM maintenance contracts, directly negotiating with SKF, NTN, and RBC for line-replaceable unit availability. This disintermediation concentrates purchasing power with fleet managers at Delta, Lufthansa, and Air China who operate 500+ aircraft platforms. Long-term framework agreements with fixed pricing and guaranteed availability are displacing spot-market purchasing, particularly for narrowbody fleet workhorse engines.
Global Aerospace Bearings Market Segmentation
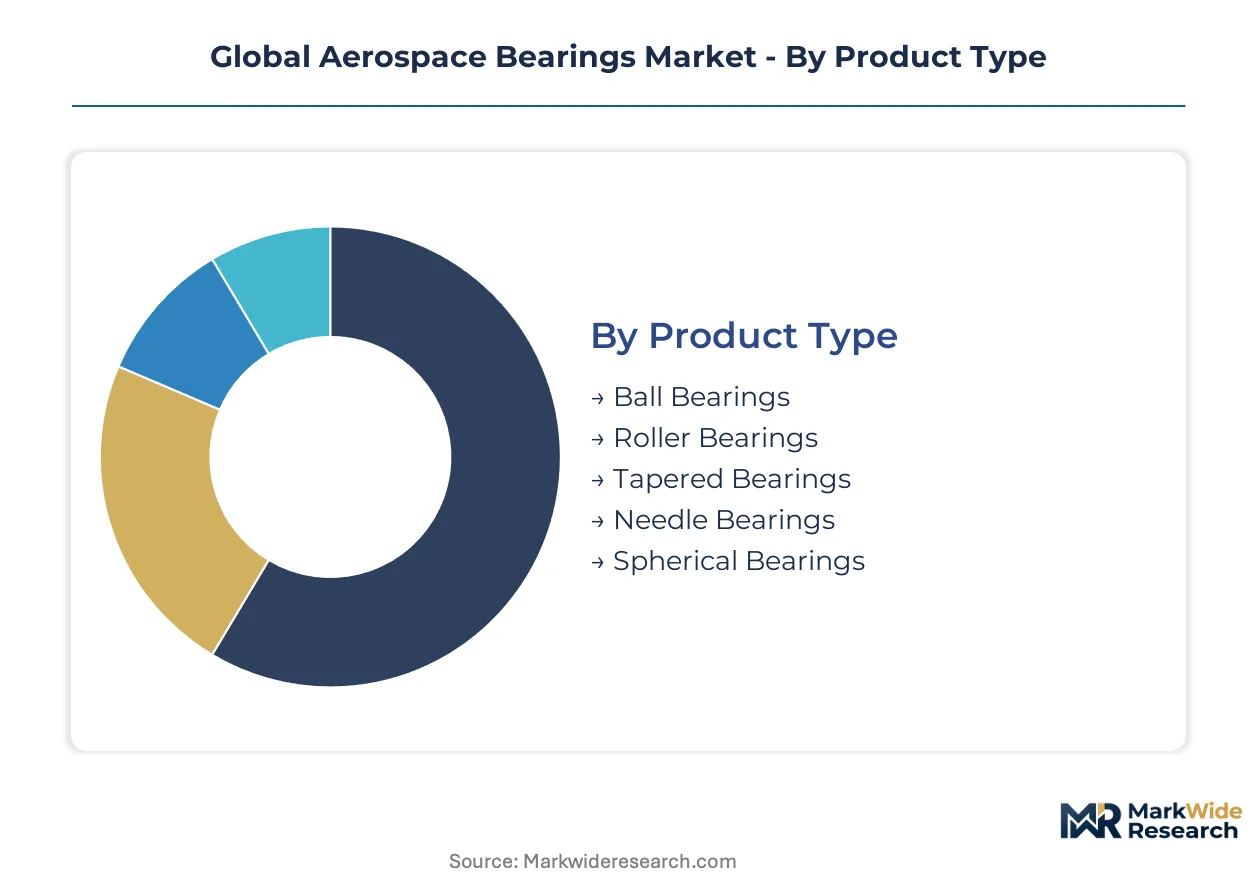
Aerospace bearings demand diverges sharply across product architectures and operational environments. After-sales service intensity varies by segment, with MRO-linked categories commanding premium pricing and long-term contractual lock-in.
Product Type:
After-sales service intensity peaks with roller and ball bearing categories, where fatigue-life monitoring and scheduled replacement generate recurring revenue streams.
- Roller Bearings:Cylindrical and spherical roller configurations dominate commercial turbofan engine main shaft applications. Demand concentrates at Pratt & Whitney and Rolls-Royce assembly facilities in the United States and United Kingdom as geared turbofan architectures multiply bearing load ratings.
- Ball Bearings:Deep-groove and angular-contact designs handle combined radial-axial loads in auxiliary power units and flight control actuators. Procurement clusters with Boeing and Airbus final assembly lines in Washington State and Toulouse, driven by airframe OEM direct sourcing strategies.
- Tapered Bearings:Conical raceway geometry manages heavy combined loads in landing gear struts and flap mechanisms.
- Needle Bearings:Compact cylindrical rollers suit space-constrained helicopter rotor hubs and UAV control linkages.
- Spherical Bearings:Self-aligning outer rings accommodate misalignment in wing-fold mechanisms and thrust vectoring systems.
Roller bearings hold the largest share; momentum sits with ball bearings as electric actuation expands flight control applications.
Technology:
Cost tier stratification separates certified ceramic architectures from commodity metallic alternatives, with hybrid stacks occupying the mid-tier value position.
- Ceramic:Silicon nitride rolling elements withstand operating temperatures exceeding 300°C in next-generation geared turbofans. FAA and EASA certification pathways for ceramic main shaft bearings are tightening material traceability requirements at GE Aerospace and Safran qualification programs.
- Hybrid:Ceramic balls paired with metallic races balance thermal performance and cost in auxiliary systems. Japanese and German tier-one suppliers dominate hybrid production, capturing procurement from narrowbody engine OEMs seeking weight reduction without full ceramic pricing.
- Metallic:Vacuum-melted steel bearings retain cost advantage in legacy fleet maintenance and non-critical applications.
- Magnetic:Active magnetic levitation eliminates contact friction in auxiliary power units, threatening rolling-element penetration below threshold load conditions.
- Self-Lubricating:Polymer-impregnated porous metal matrices operate without external lubrication in spacecraft and long-endurance UAV propulsion.
Metallic technology retains volume leadership; ceramic architectures are gaining share fastest as thermal efficiency mandates intensify.
Application:
Volume concentration tracks airframe production rates, with commercial platforms generating scale economies that military and space categories cannot replicate.
- Commercial Aircraft:Narrowbody and widebody platforms consume the majority of precision bearing output. China's COMAC C919 ramp is localizing demand for ARJ21 and C919 engine bearings, concentrating procurement with domestic-qualified suppliers in Shanghai and Xi'an manufacturing clusters.
- Military Aircraft:Fighter and transport programs specify bearings with extended fatigue life under combat load spectra. Defense procurement in the United States and Russia emphasizes supply security over unit cost, sustaining premium pricing for ITAR-controlled bearing grades.
- Spacecraft:Launch vehicle and satellite applications demand ultra-low outgassing materials and extreme temperature cycling resistance.
- Helicopters:Main and tail rotor systems require bearings with high oscillation durability and damage tolerance.
- Unmanned Aerial Vehicles:Civil and military drone platforms prioritize weight reduction and maintenance interval extension.
Commercial aircraft anchors installed base value; UAV applications are expanding most quickly as beyond-visual-line-of-sight operations proliferate.
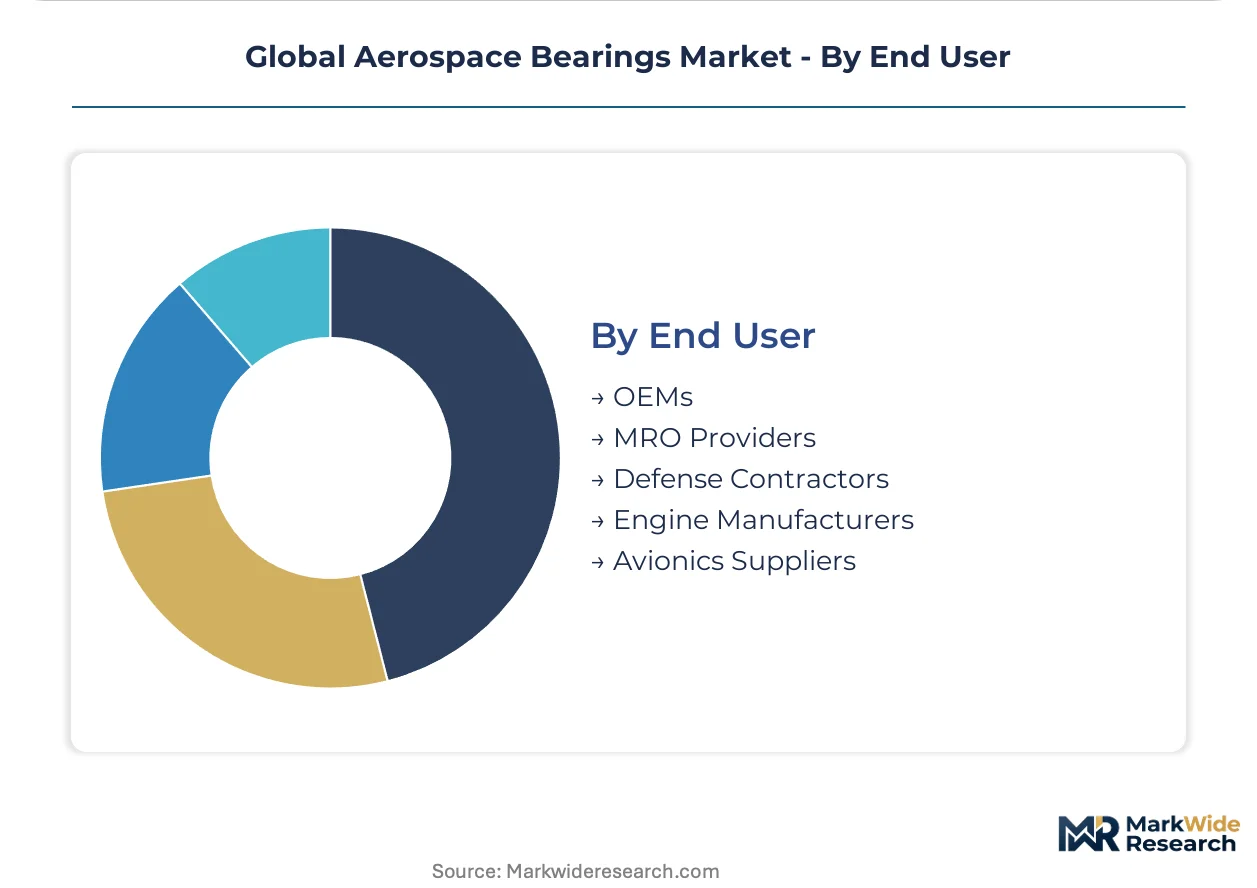
End User:
Customer type determines contract structure, with OEMs negotiating multi-year framework agreements while MRO providers manage spot-market volatility.
- OEMs:Airframe and engine manufacturers specify bearings at design stage, locking in decade-long supply relationships. Boeing and Airbus qualification protocols in the United States and France demand exhaustive test documentation that barriers alternative suppliers.
- MRO Providers:Maintenance networks absorb inventory risk under power-by-the-hour contracts, consolidating procurement with SKF and NTN distribution hubs. Lufthansa Technik and Delta TechOps in Germany and the United States are unbundling bearing sourcing from engine OEM maintenance agreements.
- Defense Contractors:National security specifications mandate domestic content ratios and traceable supply chains.
- Engine Manufacturers:GE Aerospace, Rolls-Royce, and Pratt & Whitney captive bearing specifications flow down to tier-two machine shops.
- Avionics Suppliers:Flight control and environmental system integrators specify miniature precision bearings for actuator and sensor applications.
OEMs command specification authority; MRO providers are capturing procurement volume fastest as fleet management models shift risk downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and EASA certification specifications are redirecting capital toward qualified manufacturing clusters in the United States, Germany, and China. These three countries host the dominant airframe and engine production ecosystems that determine bearing procurement specifications.
United States
Pratt & Whitney and GE Aerospace engine programs in Connecticut and Ohio drive ceramic bearing demand for geared turbofan architectures. FAA mandates on fatigue-life documentation accelerate fleet replacement schedules at Delta TechOps and Southwest Airlines maintenance hubs. Wichita, Kansas and Seattle, Washington concentrate precision machining capacity for Boeing airframe qualification protocols.
Germany
Rolls-Royce Deutschland and MTU Aero Engines specify silicon nitride bearings for thermal loads exceeding 300°C in next-generation powerplants. EU Green Deal sustainable aviation fuel mandates push MTU toward higher bypass ratio designs requiring certified ceramic suppliers. Bavaria and Baden-Württemberg host Schaeffler AG and tier-one distributors serving Lufthansa Technik MRO networks.
China
COMAC C919 narrowbody production localizes demand for ARJ21 and C919 engine bearings at Shanghai and Xi'an manufacturing clusters. MIIT domestic content requirements concentrate procurement with qualified Chinese suppliers for flight control systems. The country's dual carbon goals accelerate ceramic bearing adoption in indigenous turbofan development programs.
Japan
NTN Corporation and JTEKT Corporation anchor captive supply relationships with Mitsubishi Heavy Industries and Kawasaki airframe production. METI industrial policy supports precision bearing foundry expansion for SpaceJet and defense applications. Nagoya and Osaka industrial corridors specialize in vacuum-melted steel processing for hybrid bearing architectures.
United Kingdom
Rolls-Royce Derby and Bristol facilities source certified bearings for Trent engine families serving Emirates and Singapore Airlines fleets. UK Ministry of Defence procurement mandates traceable supply chains for Eurofighter Typhoon and Tempest platforms. Midlands aerospace cluster concentrates heat treatment and finishing capacity for legacy fleet MRO.
Global Aerospace Bearings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. SKF Group leverages integrated distribution networks to capture power-by-the-hour maintenance contracts, while RBC Bearings and NTN Corporation defend positions through application-specific engineering relationships. Three archetypes dominate: full-service distributors with global MRO reach, ceramic technology specialists with FAA-EASA certification assets, and captive suppliers aligned with national airframe manufacturers. Consolidation pressure intensifies as engine OEMs reduce approved vendor lists, while additive manufacturing partnerships reshape race geometry capabilities.
Within the full-service distributor archetype, SKF Group exemplifies channel control through long-term framework agreements. Among Japanese precision manufacturers, JTEKT Corporation and NSK Ltd. occupy positions defined by captive relationships with domestic airframe builders. NTN Corporation anchors the Asia-Pacific supply vector through vertically integrated steel processing and ceramic sintering capabilities. These three company structures represent distinct competitive postures: global service integration, national industrial policy alignment, and upstream materials control.
| Leading Market Players |
|---|
| JTEKT Corporation |
| NSK Ltd. |
| SKF Group |
| Kaman Corporation |
| RBC Bearings Incorporated |
| The Timken Company |
| NTN Corporation |
| National Precision Bearings |
| Schaeffler AG |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors absorb premium logistics costs for vacuum-melted steel shipments, compressing margins at German and Japanese foundries while amplifying price spreads between FAA-certified ceramic bearings and commodity metallic alternatives across tier-one distributor networks.
Pricing Analysis
Certification grade creates the primary spread between silicon nitride ceramic bearings and vacuum-melted steel equivalents, with EASA-FAA dual-qualified suppliers commanding substantial premiums over single-certified competitors. Three-tier pricing structure separates premium ceramic architectures from hybrid mid-tier offerings and economy metallic grades for legacy fleet maintenance. Pricing pressure stems from power-by-the-hour contracts transferring inventory risk to MRO providers, forcing distributors toward volume-based contract structures. Least price sensitivity concentrates at engine OEM specification stages, while aftermarket procurement teams at airline maintenance hubs exhibit acute cost consciousness.
Supply Chain Analysis
Schaeffler AG and NTN Corporation captive foundries anchor precision bearing capacity across Germany, Japan, and the United States, with Chinese domestic suppliers expanding share for COMAC-qualified applications. Raw material flows draw from vacuum-melted steel production in Essen and specialty ceramic powder processing in Nagoya industrial corridors. Single-source vulnerability concentrates at silicon nitride rolling element suppliers qualified for Pratt & Whitney geared turbofan programs. Distribution runs through SKF and NTN regional hubs serving Lufthansa Technik and Delta TechOps maintenance networks under long-term framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace bearings track commercial aviation delivery cycles, with OEM backlog recovery and fleet renewal rates determining demand inflection across the projection horizon.
For Market Incumbents: Build certification moats around silicon nitride ceramic architectures before EASA tightens material traceability requirements. Secure captive vacuum-melted steel supply through backward integration into German or Japanese foundry capacity. Magnetic bearing substitution in auxiliary power units threatens rolling-element penetration below threshold loads. For New Entrants and Emerging Players: Pursue urban air mobility bearing specifications where eVTOL tilt-rotor demands outpace established supplier qualification bandwidth. Target UAV propulsion segments requiring self-lubricating architectures with 10,000-plus cycle maintenance intervals. Partner with additive manufacturing specialists for selective laser melting of hybrid bearing races with integrated cooling channels. For Investors and Strategic Acquirers: Ceramic technology specialists with FAA-EASA dual certification represent the highest-conviction acquisition archetype for portfolio exposure to geared turbofan proliferation. Long-term viability hinges on supplier consolidation as engine OEMs reduce approved vendor lists. Watch Pratt & Whitney and Rolls-Royce supplier qualification announcements as inflection signals for certified capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Certification Investment | EASA-FAA dual qualification opens Pratt & Whitney and GE Aerospace supplier positions. |
| Captive Steel Foundry Acquisition | Backward integration into vacuum-melted capacity insulates against alloying element volatility. |
| Additive Manufacturing Partnership | Selective laser melting enables weight-optimized bearing races with integrated cooling geometries. |
| MRO Distribution Network Expansion | Hub proximity to Delta TechOps and Lufthansa Technik captures power-by-the-hour contract flow. |
| Urban Air Mobility Qualification | eVTOL tilt-rotor specifications demand compact bearings outside traditional aviation certification pathways. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings on certification pathway evolution. Discussions with engine OEM procurement directors, MRO network supply chain managers, FAA certification engineers, and ceramic foundry technical directors inform demand segmentation. Secondary sources include EASA CS-25 specification databases, FAA airworthiness directive archives, and customs trade flows for vacuum-melted steel and silicon nitride powder. Bottom-up bearing unit demand models triangulate against top-down aerospace production forecasts.
Calibration against historical C919 and LEAP engine delivery trajectories validates growth assumptions across the projection horizon. Segmentation dimensions span product architecture, material technology, application platform, and end-user contract type. CAGRs derive from installed base replacement schedules, fleet expansion rates, and technology substitution curves for ceramic versus metallic architectures. Forecast inputs incorporate COMAC production ramp timelines and EU Green Deal sustainable aviation fuel mandate impacts on engine thermal efficiency requirements.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price volatility, interest rate environments affecting aircraft leasing, or geopolitical export licensing restrictions would shift the trajectory. Cross-checking against IATA passenger traffic recovery benchmarks and Boeing-Airbus order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Aircraft Cabin Management System Market
Aerospace & Defense
Europe Passive Electronic Components in Aerospace and Defense Market
Aerospace & Defense
Saudi Arabia Maritime Security Market
Aerospace & Defense
Aircraft Windshield Wiper and Washer System Market
Aerospace & Defense
Armored Personnel Carrier Market
Aerospace & Defense
Laser Telemetry Binoculars Market
Aerospace & Defense
Satellite Communications Service Market
Aerospace & Defense
Parabolic Flight Tourism Market
Aerospace & Defense
Aircraft Attitude Indicators Market
Aerospace & Defense
Europe Drone Services Market
Aerospace & Defense
Europe Military Satellite Market
Aerospace & Defense
Military Sensors Cybersecurity Solutions Market
Aerospace & Defense
Stealth Technology Market
Aerospace & Defense
Manportable Radar Market
Aerospace & Defense
Space Ground Station Equipment Market
Aerospace & Defense
Global Airport Baggage Handling System Market