
 Display for Avionics Application Market | 2026-2036
Display for Avionics Application Market Size, Share, and Industry Trends Forecast 2026-2036
Display for Avionics Application Market Insights
High-brightness sunlight-readable specifications is bifurcating the competitive landscape into MIL-STD-3009 qualified suppliers and commercial aviation specialists. Honeywell International Inc. leverages its integrated flight deck architecture to dominate integrated cockpit systems for business jets and military trainers. Thales Group sustains European defense and commercial programs through its Avionics division's proprietary LCD bonding processes. Garmin Ltd. competes aggressively in the retrofit and general aviation segment with purpose-built displays that prioritize weight reduction and power efficiency.
Displays for avionics applications are ruggedized flat-panel systems engineered to operate across temperature extremes from -55°C to +85°C, with luminance exceeding 1000 cd/m² for sunlight readability and NVIS compatibility for night operations. Their primary purpose is to present flight-critical data—attitude, altitude, navigation, engine parameters—to pilots under electromagnetic interference and vibration stress. OLED technology is capturing share in next-generation fighter cockpits where contrast ratio and response time outweigh lifetime concerns, while LCD with LED backlighting remains the volume backbone for commercial transport due to proven reliability and lower qualification burden. Capacitive touch interfaces are displacing resistive legacy panels in new programs, though haptic feedback integration lags behind automotive benchmarks because of FAA human factors certification complexity.
FAA Technical Standard Orders (TSO-C113, TSO-C165) govern display airworthiness, while EASA CS-25 and MIL-STD-3009 establish optical and environmental performance baselines that determine supplier eligibility. RTCA DO-178C software assurance and DO-254 hardware assurance requirements extend development timelines and concentrate procurement among vendors with established certification track records. Stakeholders must monitor the tension between touch-interface modernization and regulatory conservatism, as human factors validation for gesture-based controls remains unresolved across major airworthiness authorities.
Market Dynamics
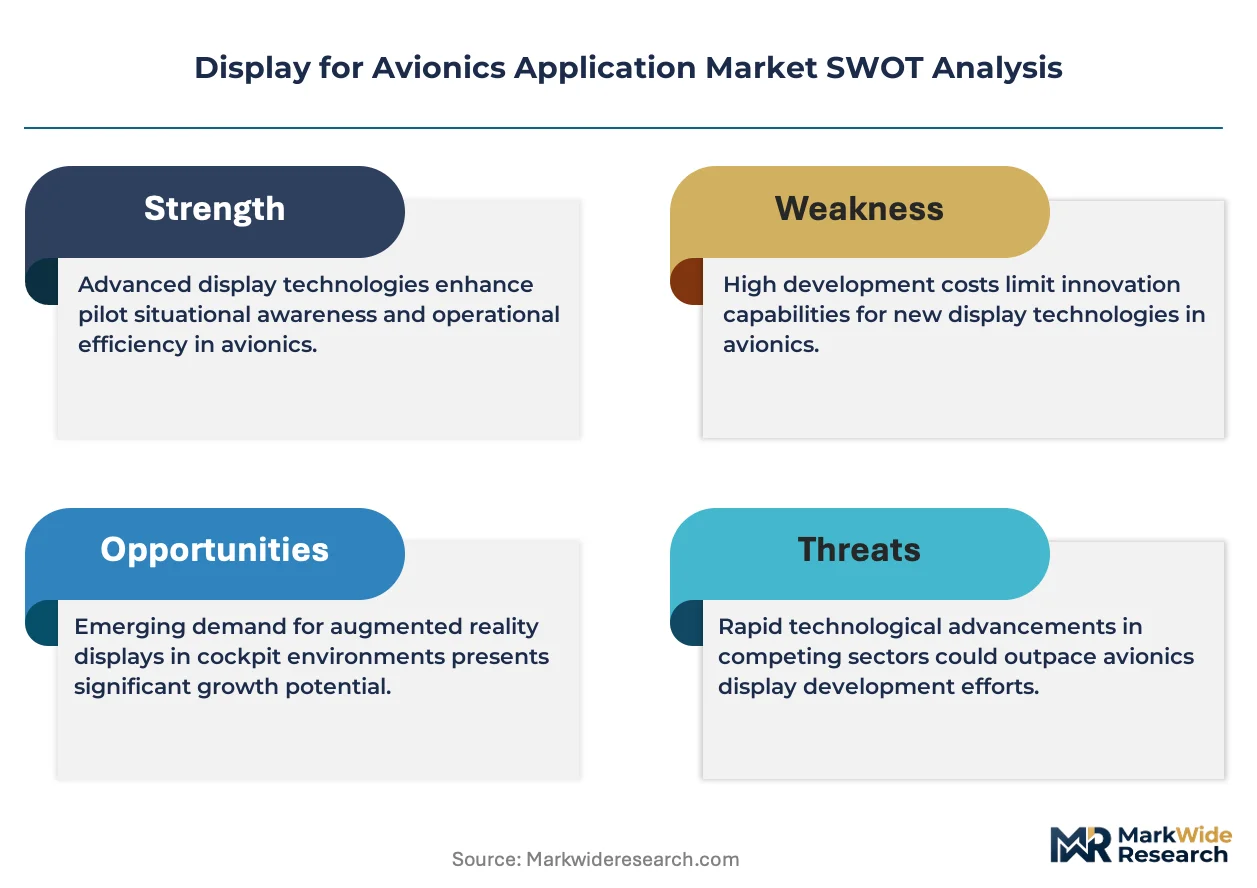
Touch-interface modernization is colliding with FAA human factors certification complexity, forcing suppliers to maintain parallel development tracks for capacitive and resistive architectures while awaiting regulatory clarity on gesture-based controls.
Growth Catalysts
- FAA TSO-C113/TSO-C165 certification pathways:Updated technical standard orders for active matrix displays are accelerating cockpit retrofit programs across aging narrow-body fleets in the United States.
- OLED technology maturation:Next-generation fighter programs are specifying emissive displays for helmet-mounted cueing systems, creating qualification precedent for wider military adoption.
- EASA CS-AWF luminance mandates:Tightened readability thresholds for all-weather flight operations are compelling European carriers to accelerate primary flight display replacements.
Market Restraints
- Indium supply concentration:Over 70% of refined indium for transparent conductive oxides originates from Chinese smelters, exposing LCD and OLED manufacturers to geopolitical supply disruption.
- DO-178C software assurance burden:RTCA guidelines extend development timelines by 18-24 months, concentrating procurement among incumbents with established certification portfolios.
- NVIS filter cost structure:Night vision imaging system compatibility requires specialized thin-film deposition processes that add 30-40% to display module cost.
Strategic Opportunities
- Urban air mobility cockpit standardization:Emerging eVTOL OEMs are specifying reduced pilot workload through single-pilot-optimized display architectures, bypassing legacy dual-crew design constraints.
- India defense indigenization:The country's Ministry of Defence production-linked incentive schemes are creating local assembly requirements for avionics subsystems, including qualified display suppliers.
- Capacitive-haptic convergence:Integration of piezoelectric feedback layers with projected capacitive touch is enabling eyes-down time reduction that meets FAA advisory circular guidance on pilot attention.
Industry Challenges
- DO-254 hardware assurance talent scarcity:Verification engineers with RTCA-level FPGA and ASIC qualification experience command premium compensation, constraining supplier scaling.
- Legacy ARINC 429 integration friction:Newer display architectures must maintain backward compatibility with 1970s-era digital data buses prevalent in retrofitted commercial transport aircraft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display for Avionics Application Market |
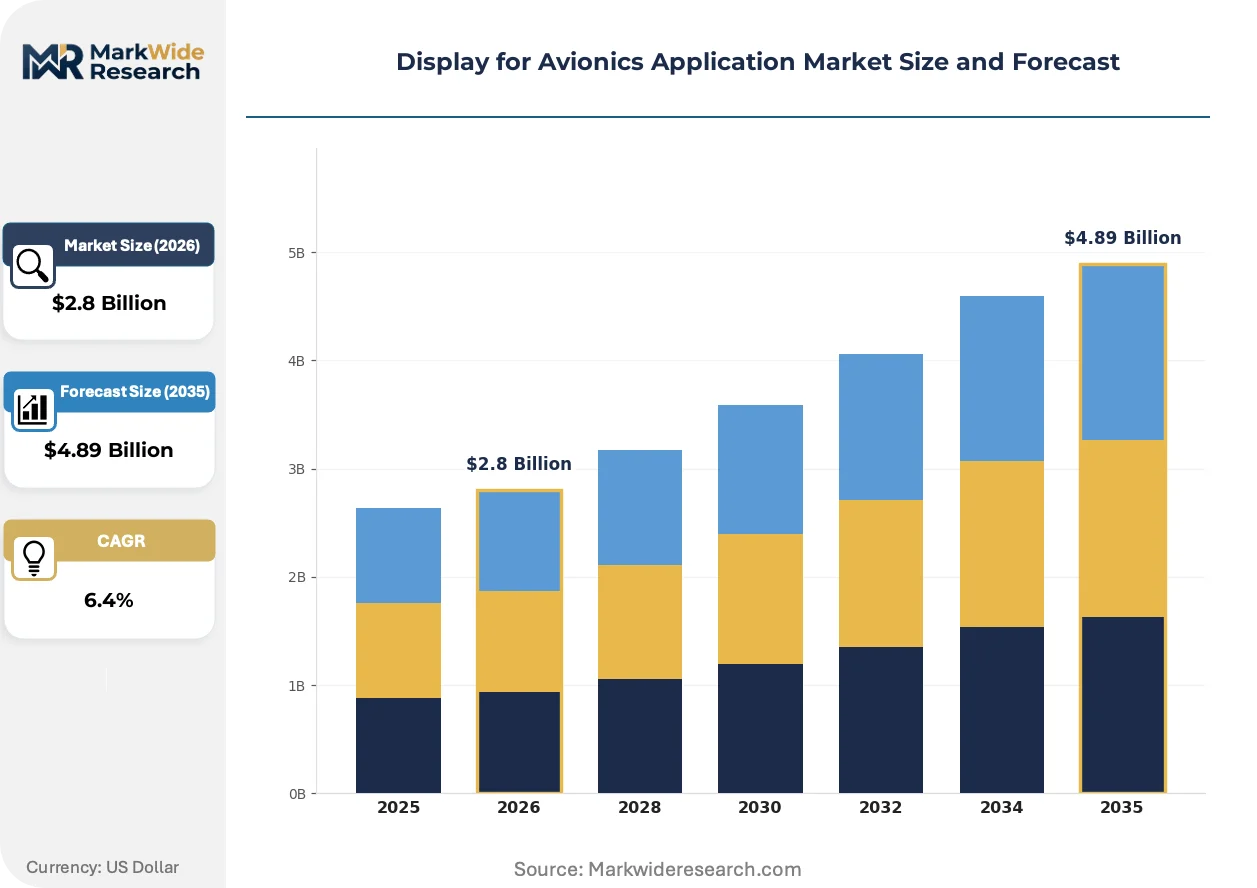
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, LED, TFT, E-Ink, MicroLED Technology: Resistive Touch, Capacitive Touch, Optical Touch, Haptic Feedback, Anti-Glare, Night Vision Application: Flight Control Systems, Navigation Interfaces, Communication Panels, Cockpit Instrumentation, Weather Monitoring, Traffic Collision Avoidance End User: Aircraft Manufacturers, Avionics Integrators, Defense Contractors, Commercial Airlines, Private Jet Operators |
| Companies Covered | Honeywell International Inc., Thales Group, Garmin Ltd., RTX Corp., Elbit Systems Ltd., L3Harris Technologies Inc., BAE Systems Plc, Aspen Avionics Inc., Avidyne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display for Avionics Application Market Trends and Innovations
Avionics display architectures are fragmenting along mission-criticality lines, with commercial transport favoring evolutionary LCD-LED reliability and military platforms accepting OLED risk-reward profiles for performance gains.
MicroLED emitters are decomposing the traditional backlight-LCD-filter stack into self-illuminating pixel arrays, eliminating color filter absorption losses. Fighter program offices in the United States and United Kingdom are funding pilot-scale microLED integration for helmet-mounted displays, where luminance and contrast ratio requirements exceed conventional panel capabilities. This technology is decomposing established supply relationships by requiring compound semiconductor foundry partnerships unfamiliar to legacy aerospace display assemblers.
EASA's updated CS-25 Amendment 26 introduces stricter electromagnetic interference susceptibility testing for cockpit displays, mandating shielding validation across expanded frequency spectra. European airframe integrators are redesigning display housing architectures to accommodate ferrite-loaded composites, adding weight that conflicts with fuel efficiency targets. Business jet manufacturers based in Switzerland and France are most affected, as their compact cockpit designs offer minimal margin for additional shielding volume.
Airline technical procurement teams are compressing supplier qualification cycles by accepting TSO-authorization equivalency rather than demanding airframe-specific PMA pathways. This pattern concentrates vendor selection among holders of multiple TSO designations, marginalizing specialty suppliers with narrow certification portfolios. The shift is most visible in the United States, where major carriers operate mixed fleets spanning multiple OEM platforms and prioritize common spares strategies.
Display for Avionics Application Market Segmentation
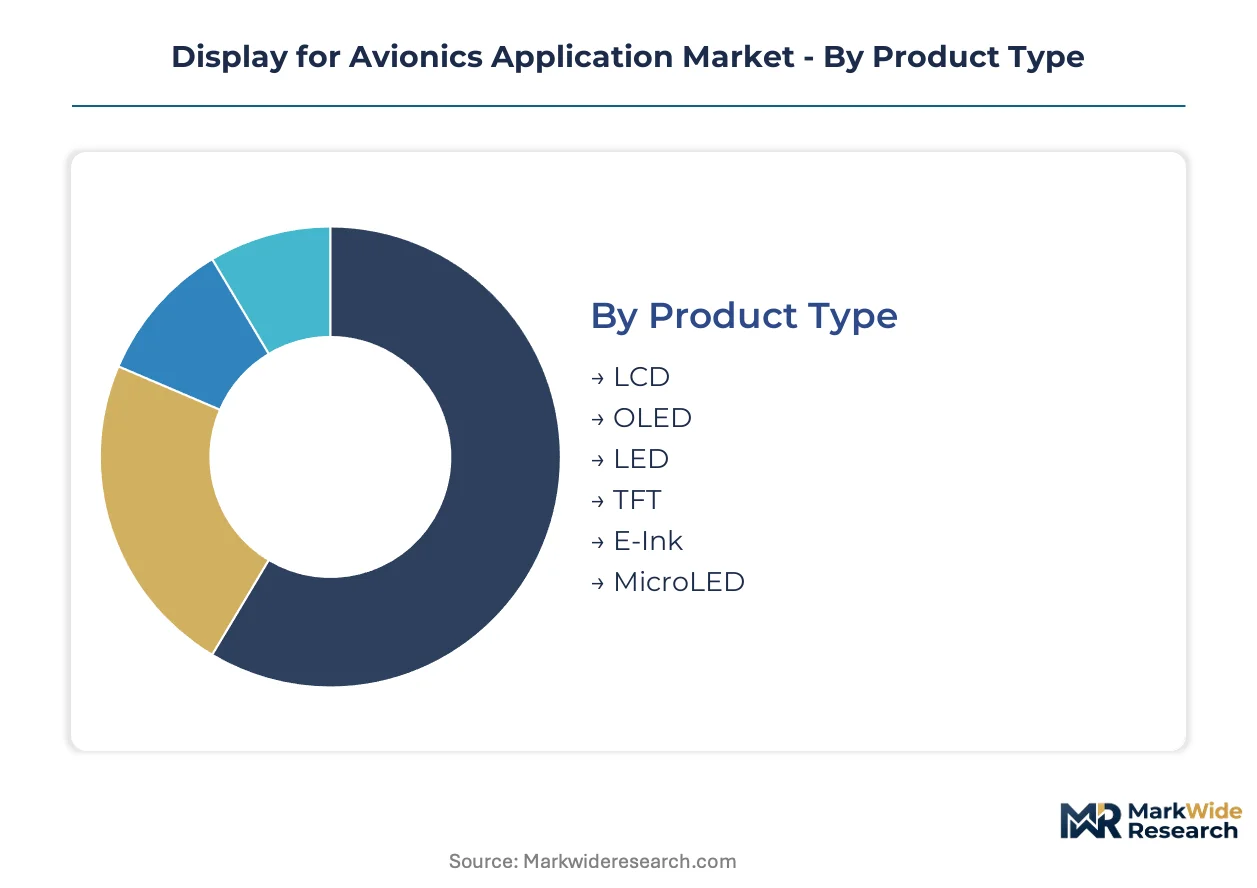
Avionics display procurement splits along certification-grade lines, with FAA TSO-C113 pathways favoring proven LCD-LED architectures while experimental categories absorb emerging emissive technologies. Understanding segment boundaries reveals where supplier qualification portfolios concentrate versus where technical risk tolerance permits new entrants.
Product Type:
Domestic demand in the United States concentrates in LCD and LED variants qualified under MIL-STD-3009, while export-led growth in European fighter programs is pulling OLED and MicroLED through prototype-to-production transitions.
- LCD:Thin-film transistor active matrix designs with LED edge-lit or direct-lit backbones deliver 1000+ cd/m² luminance for sunlight readability. Commercial transport procurement in the United States and European Union favors this architecture for its established DO-254 hardware assurance pathway and lower re-qualification burden during fleet retrofits.
- OLED:Organic emissive layers eliminate backlight assemblies, enabling thinner form factors and infinite contrast ratios critical for helmet-mounted cueing systems. Next-generation fighter programs in the United Kingdom and United States are specifying these displays despite lifetime degradation concerns, creating qualification precedent for wider military adoption.
- LED:Direct-view LED arrays serve large-format cockpit situational awareness displays in military transport and mission aircraft where viewing angle and uniformity outweigh pixel density requirements.
- TFT:Thin-film transistor backplane technology underpins most active matrix LCD production, with amorphous silicon and low-temperature polysilicon variants splitting between cost-sensitive general aviation and high-resolution primary flight displays.
- E-Ink:Bistable electrophoretic displays consume power only during image updates, finding niche application in electronic flight bag secondary panels and checklist viewers where sunlight readability exceeds refresh rate needs.
- MicroLED:Gallium nitride emitter arrays eliminate color filters and liquid crystal layers entirely, with pilot-scale integration funded by United States and United Kingdom defense research offices for helmet-mounted displays exceeding conventional panel luminance limits.
LCD commands the established base. The steepest expansion runs through MicroLED as compound semiconductor foundries enter aerospace supply chains.
Technology:
Cost tiers separate resistive legacy architectures from capacitive modernization programs, with premium haptic and night vision layers adding 30-40% to module pricing for military-specified configurations.
- Resistive Touch:Pressure-sensitive membrane stacks maintain dominance in retrofit programs where FAA human factors certification for existing cockpit layouts resists interface changes. Aging narrow-body fleets in the United States continue specifying this technology to avoid re-validation costs.
- Capacitive Touch:Projected capacitance arrays enable multi-point gesture recognition and optical clarity superior to resistive alternatives. New business jet and eVTOL programs in Switzerland and France are specifying these interfaces, though haptic feedback integration lags automotive benchmarks due to certification complexity.
- Optical Touch:Infrared frame-based sensing overlays retrofit-compatible touch capability onto existing display surfaces without panel replacement, serving mixed-fleet operators seeking common spares strategies.
- Haptic Feedback:Piezoelectric actuator layers provide tactile confirmation of virtual button presses, reducing eyes-down time in single-pilot-optimized cockpits emerging from urban air mobility design constraints.
- Anti-Glare:Etched surface treatments and circular polarizer films scatter specular reflections without luminance loss, mandated by EASA CS-AWF all-weather flight standards tightening across European commercial operations.
- Night Vision:Thin-film interference filters suppress near-infrared emissions to prevent saturation of image intensifier tubes, adding specialized deposition process costs for military and law enforcement aircraft.
Resistive touch retains the installed base. Capacitive-haptic convergence is climbing the fastest as urban air mobility OEMs specify reduced pilot workload architectures.
Application:
Volume concentrates in cockpit instrumentation replacements driven by FAA TSO-C113 retrofit mandates, while margin pools in flight control and traffic avoidance systems where failure-mode analysis requirements filter supplier eligibility.
- Flight Control Systems:Primary flight displays presenting attitude, altitude, and airspeed data operate under the strictest DO-178C software assurance and DO-254 hardware assurance requirements. These systems command premium pricing and concentrate procurement among vendors with established FAA certification track records.
- Navigation Interfaces:Moving map and flight management system displays integrate GPS, inertial reference, and ground-based augmentation data. European carriers accelerating primary flight display replacements under EASA CS-25 Amendment 26 EMI mandates are bundling navigation interface upgrades.
- Communication Panels:Radio management and datalink displays handle frequency selection and ACARS messaging with lower criticality classification, permitting shorter qualification cycles and broader supplier participation.
- Cockpit Instrumentation:Engine indicating and crew alerting system displays consolidate previously discrete gauges into integrated graphical formats, driving retrofit demand across aging narrow-body and wide-body fleets.
- Weather Monitoring:Multifunction displays presenting radar, lightning, and satellite precipitation data require specialized graphics processing for real-time rendering of three-dimensional storm cells.
- Traffic Collision Avoidance:Dedicated displays or integrated overlays present TCAS resolution advisories with distinct visual and aural alerting protocols mandated by international airworthiness standards.
Cockpit instrumentation commands the established base. Flight control systems are gaining share fastest as fly-by-wire architectures proliferate from commercial transport into business aviation and advanced air mobility platforms.
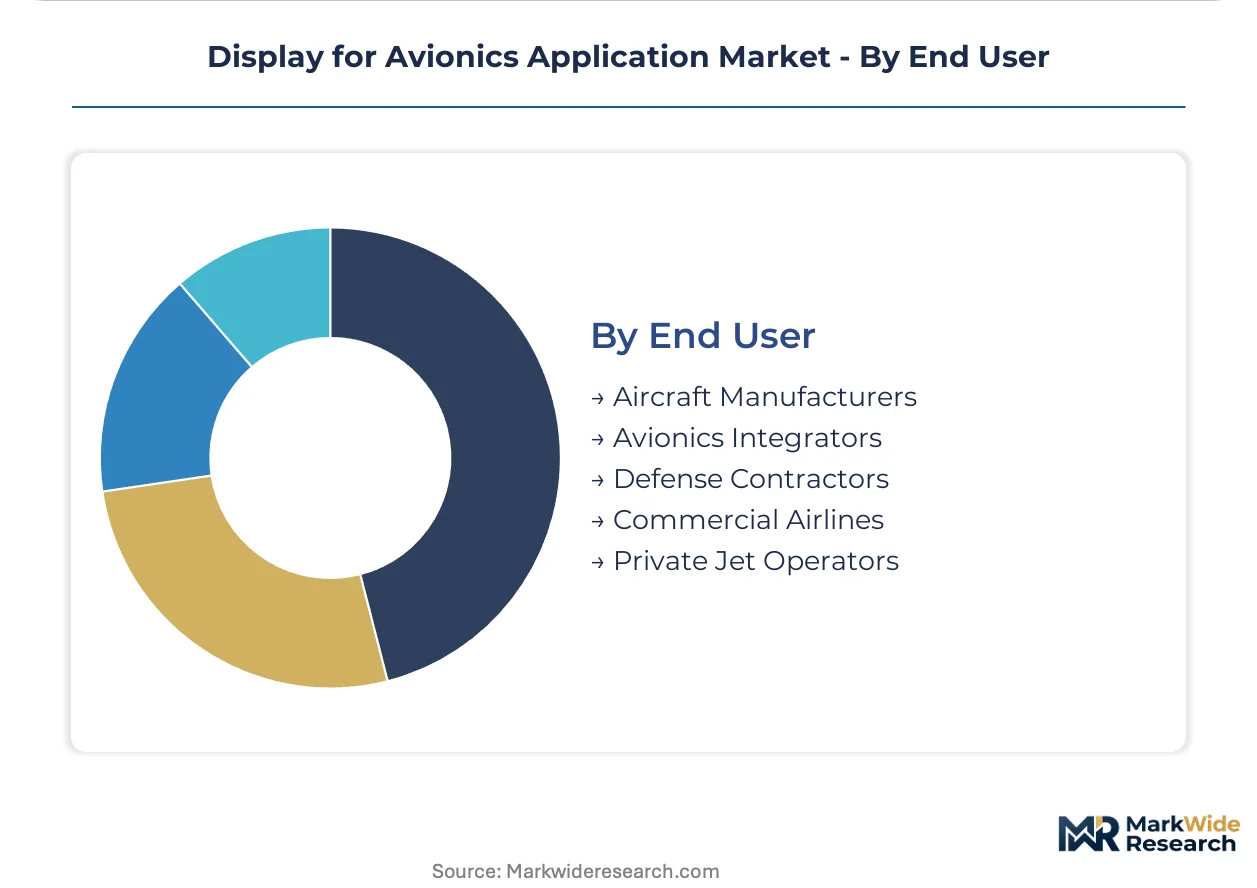
End User:
Customer type determines procurement rhythm, with defense contractors operating multi-year program cycles and commercial airlines compressing supplier qualification through TSO-authorization equivalency rather than airframe-specific PMA pathways.
- Aircraft Manufacturers:Boeing and Airbus tier-one supply agreements set performance specifications and qualification protocols that cascade through sub-tier display assemblers, concentrating volume among vendors with integrated flight deck architecture capabilities.
- Avionics Integrators:Specialized firms combining displays with processing, software, and certification documentation serve retrofit markets and smaller OEMs lacking in-house cockpit system development resources.
- Defense Contractors:Lockheed Martin, BAE Systems, and Dassault Aviation program offices fund technology maturation for next-generation fighter and trainer displays, with MIL-STD-3009 qualification requirements filtering supplier pools.
- Commercial Airlines:United, Delta, and Lufthansa technical procurement teams prioritize common spares strategies across mixed fleets, favoring multi-TSO holders over specialty suppliers with narrow certification portfolios.
- Private Jet Operators:Fractional ownership and charter fleet managers specify Garmin and Collins Aerospace retrofit packages that minimize aircraft downtime through slide-in replacement form factors.
Commercial airlines command the established base. Defense contractors are expanding most quickly as Indo-Pacific rearmament programs and European NATO modernization accelerate display upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt heavily toward the United States as a net importer of qualified avionics displays, while France and the United Kingdom maintain trade surpluses in defense-aerospace segments. Currency volatility and indium supply chain exposures are reshaping procurement patterns across major aviation hubs.
United States
Boeing's supplier ecosystem and Pentagon procurement programs sustain display upgrade cycles across commercial and military fleets. FAA TSO-C113 and TSO-C165 certification pathways concentrate qualified supplier pools, filtering eligibility through established airworthiness track records. The Pacific Northwest and Wichita clusters host tier-one integrators managing cockpit modernization programs for narrow-body retrofits.
France
Dassault Aviation and Thales Group anchor defense and business jet display demand through proprietary LCD bonding processes and integrated flight deck architectures. EASA CS-25 Amendment 26 EMI mandates are compelling shielding redesigns that add weight to compact cockpit layouts. The Île-de-France and Provence-Alpes-Côte d'Azur corridors concentrate avionics subsystem assembly and qualification facilities.
United Kingdom
BAE Systems program offices fund microLED helmet-mounted display maturation for next-generation fighter platforms, creating qualification precedent for compound semiconductor foundry partnerships. Ministry of Defence procurement is accelerating NATO modernization display cycles. The South West England and Greater London clusters house prime contractors and research offices driving emissive technology transitions.
Germany
Airbus tier-one supply agreements cascade performance specifications through sub-tier display assemblers concentrated in Bavaria and Baden-Württemberg. EASA CS-AWF luminance mandates are tightening readability thresholds for all-weather flight operations. The Munich and Hamburg metropolitan areas host avionics integrators serving A320 family cockpit retrofit demand.
India
Ministry of Defence production-linked incentive schemes are creating local assembly requirements for avionics subsystems, including qualified display suppliers. Defense indigenization programs are pulling technology transfer agreements from Israeli and French primes. The Bangalore and Hyderabad clusters are emerging as certification-capable assembly hubs for military trainer and transport aircraft displays.
Display for Avionics Application Market Competitive Landscape
Concentration sits with integrated flight deck architects and defense primes holding multiple FAA TSO and MIL-STD-3009 qualifications. Three archetypes dominate: tier-one aerospace conglomerates with captive avionics divisions, specialized display subsystem suppliers with narrow certification portfolios, and emerging compound semiconductor foundries entering through microLED partnerships. Competitive moves center on technology licensing for emissive displays and backward integration into indium tin oxide deposition capabilities.
Among defense-aerospace conglomerates, Honeywell International Inc., Thales Group, and Garmin Ltd. exemplify contrasting strategic positions. Honeywell represents the integrated flight deck architect archetype spanning commercial transport and military trainer segments. Thales occupies a position emphasizing European defense and proprietary manufacturing processes. Garmin anchors the retrofit-specialist tier, prioritizing weight reduction and power efficiency for general aviation and business jet aftermarket demand.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Garmin Ltd. |
| RTX Corp. |
| Elbit Systems Ltd. |
| L3Harris Technologies Inc. |
| BAE Systems Plc |
| Aspen Avionics Inc. |
| Avidyne Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between tier-one avionics integrators and compound semiconductor foundries lock in indium tin oxide deposition capacity while freezing unit pricing for multi-year fighter program cycles. This contract architecture shields LCD-LED module suppliers from spot-market indium volatility but transfers qualification burden onto buyers through take-or-pay minimums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation rests on MIL-STD-3009 certification grade and NVIS filter integration, with night-vision-compatible modules commanding 30-40% premiums over commercial-grade alternatives. Cost compression in standard-tier LCD panels is intensifying because EASA CS-25 Amendment 26 EMI shielding mandates add ferrite-loaded composite expenses. Defense contractors show least price sensitivity due to program-funded qualification amortization, while regional airline retrofitters face acute budget constraints.
Supply Chain Analysis
Extended lead times for RTCA DO-254 qualified FPGA verification engineers now stretch hardware assurance timelines by 18-24 months. Geographic supply concentrates in the United States for integrated flight deck architectures, Japan for amorphous silicon TFT backplanes, and China for refined indium smelting. Raw material dependencies include indium for transparent conductive oxides, gallium nitride for microLED emitters, and specialized thin-film deposition equipment. Single-source vulnerability in Chinese indium refining exposes manufacturers to geopolitical disruption. Distribution runs through Boeing and Airbus tier-one supply agreements that cascade specifications to sub-tier assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against microLED technology maturation that threatens to decompose established LCD-LED supply relationships through compound semiconductor foundry partnerships.
For Market Incumbents: Fortify certification portfolio breadth by adding FAA TSO-C165 pathways alongside existing TSO-C113 holdings, creating barrier against specialty suppliers with narrow designations. Deepen backward integration into indium tin oxide deposition capabilities to offset Chinese smelter concentration risk. Prioritize capacitive-haptic convergence R&D to meet urban air mobility single-pilot workload reduction specifications before regulatory clarity solidifies. For New Entrants and Emerging Players: EASA CS-AWF fast-track qualification for all-weather flight luminance mandates offers entry wedge into European commercial retrofit demand. Target India's Ministry of Defence production-linked incentive schemes where local assembly requirements are pulling technology transfer agreements from Israeli and French primes. Pursue optical touch overlay retrofit compatibility as go-to-market angle for mixed-fleet operators seeking common spares strategies without panel replacement. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors compound semiconductor foundry partnerships with defense research office funding relationships. Long-term viability hinges on positioning for microLED helmet-mounted display proliferation from fighter programs into wider military adoption. Acquisition target archetype: specialized display subsystem suppliers holding dual FAA TSO and MIL-STD-3009 qualifications with established DO-254 hardware assurance track records. Signal to watch: EASA human factors guidance on gesture-based controls as inflection indicator for capacitive interface standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Tin Oxide Deposition | Captive supply of transparent conductive oxides reduces exposure to Chinese smelter concentration. |
| Dual TSO-C113/TSO-C165 Certification Investment | Multiple FAA designations qualify suppliers for both retrofit and new-production cockpit programs. |
| MicroLED Foundry Partnership Formation | Compound semiconductor alliances enable helmet-mounted display qualification for fighter programs. |
| Capacitive-Haptic Convergence Development | Piezoelectric feedback integration meets FAA advisory circular guidance on pilot attention reduction. |
| India Defense PLI Scheme Localization | Bangalore and Hyderabad assembly hubs satisfy Ministry of Defence indigenization requirements. |
Research Methodology
Operator-level perspectives from avionics procurement managers at commercial airlines, DO-254 verification engineers at tier-one integrators, and fighter program office technology leads anchored the qualitative base. Primary interviews combined with secondary validation through FAA TSO authorization databases, EASA certification bulletins, and Pentagon program budget justification documents. Bottom-up triangulation across display module shipment volumes and top-down reconciliation against airframe production schedules ensured cross-verification.
Sensitivity analysis tested forecast robustness across indium price volatility scenarios and certification timeline compression assumptions. The analytical framework modeled product type, application criticality, end-user procurement rhythm, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by MIL-STD-3009 qualification prevalence and EASA CS-25 Amendment 26 adoption curves. Fighter program microLED funding commitments and urban air mobility eVTOL cockpit specifications served as technology transition inputs.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement growth or accelerated EASA EMI mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding indium supply stability and RTCA software assurance timeline norms. Specific risks that could revise projections include Chinese export restriction implementation, FAA human factors guidance delays on gesture controls, and compound semiconductor foundry capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Aircraft EMI Shielding Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Military Avionic Systems Market
Avionics
Electronic Flight Instrument System Market
Avionics
Aerospace Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Global Avionics Market
Avionics
Military Aircraft Avionics Market