
 Risedronate Sodium Market | 2026-2036
Risedronate Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Risedronate Sodium Market Insights
Oral bioavailability enhancement technology is narrowing the efficacy gap between originator and generic risedronate formulations. Teva Pharmaceutical Industries Ltd leverages its generic manufacturing scale to occupy cost-sensitive hospital procurement channels. Pfizer Inc. sustains brand loyalty through extended-release formulation expertise. Eli Lilly and Company anchors its position in the osteoporosis segment through integrated bone-health portfolios.
Risedronate sodium, a third-generation bisphosphonate with the molecular formula C7H10NO7P2Na, functions primarily as an osteoclast-mediated bone resorption inhibitor used in osteoporosis and Paget's disease management. The compound requires precise pH-dependent absorption in the upper gastrointestinal tract, driving formulation complexity around gastric coating technologies. Tablets dominate volume due to established reimbursement pathways, while intravenous delivery modes capture premium positioning in hospital settings where patient compliance barriers persist. Osteoporosis indications anchor the mature revenue base, whereas bone metastasis applications represent the fastest-expanding clinical frontier as oncologists integrate bisphosphonates into supportive care protocols.
FDA bioequivalence standards and EMA quality guidelines shape generic entry timelines and manufacturing investment thresholds for risedronate sodium producers. Health Canada and the UK's MHRA enforce additional pharmacovigilance requirements that elevate post-market surveillance costs across North American and European supply chains. Stakeholders must monitor evolving osteoporosis screening guidelines from national health agencies, as expanded diagnostic criteria would directly reshape patient pool calculations and channel inventory planning.
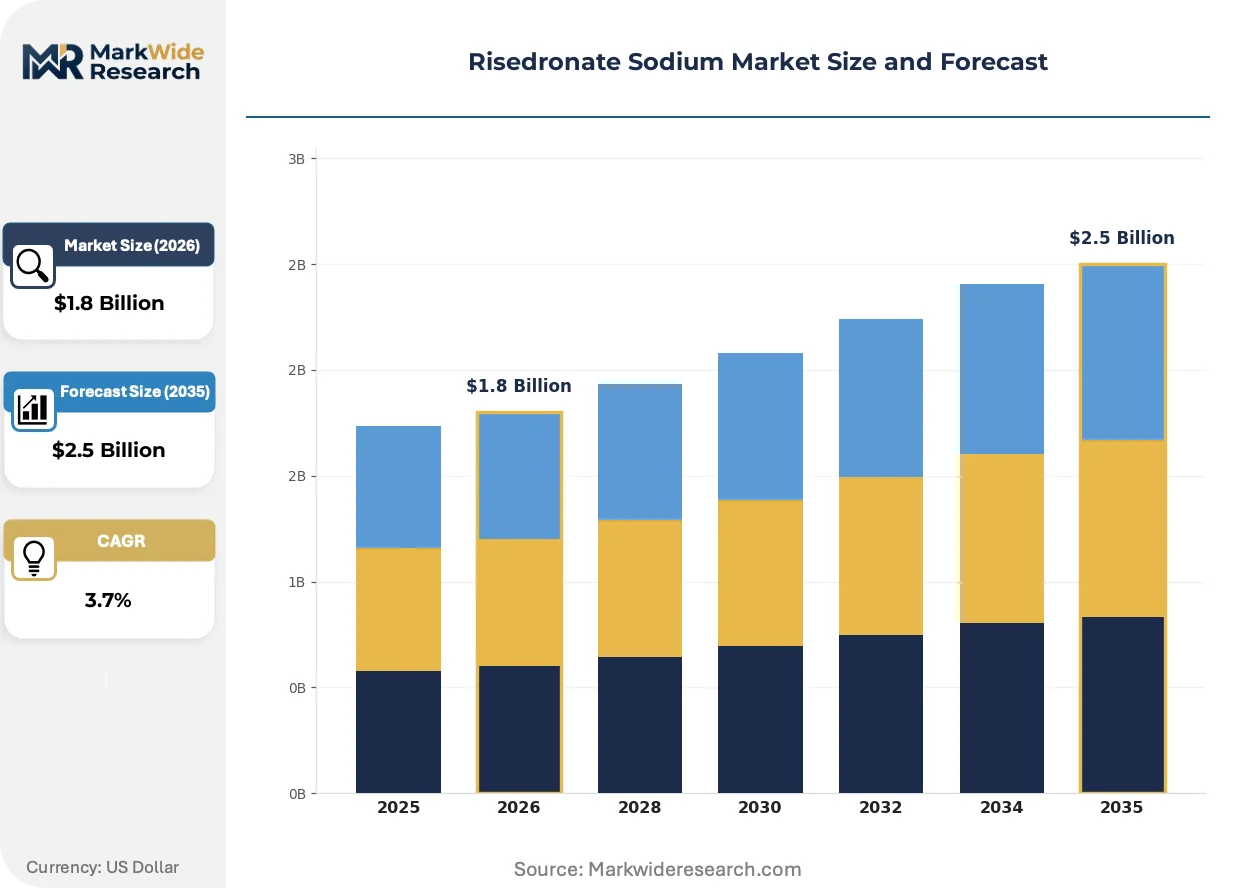
Market Dynamics
FDA bioequivalence tightening for generic risedronate formulations is compressing manufacturing timelines and elevating capital requirements for oral bisphosphonate producers. This regulatory pressure cascades through hospital procurement channels and generic substitution protocols.
Growth Catalysts
- Medicare Part D coverage expansion:Sustained reimbursement for oral bisphosphonate therapies drives volume concentration in United States post-menopausal osteoporosis protocols.
- EMA quality guideline harmonization:Standardized manufacturing benchmarks accelerate cross-border generic approvals and reduce regulatory duplication across European supply chains.
- Gastric coating technology advancement:Enhanced pH-dependent absorption systems improve bioavailability and narrow efficacy differentials between formulation generations.
Market Restraints
- Active pharmaceutical ingredient concentration:Specialty chemical synthesis for bisphosphonate moieties concentrates among limited contract manufacturers in India and China.
- Upper GI absorption limitation:Strict fasting requirements and esophageal irritation risks constrain dosing flexibility and patient adherence metrics.
- Intravenous zoledronate substitution:Annual infusion protocols capture compliance-challenged patients who abandon oral risedronate regimens.
Strategic Opportunities
- Bone metastasis supportive care:Oncologist integration of bisphosphonates into cancer protocols creates expansion beyond traditional osteoporosis indications.
- Hospital outpatient infusion centers:Shift toward supervised administration environments captures patients with swallowing difficulties or polypharmacy complexity.
- Health Canada pharmacovigilance alignment:Streamlined adverse event reporting reduces post-market surveillance costs for North American market entry.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in pH-responsive polymer coating systems limits generic developer pipeline velocity.
- Bioequivalence study complexity:FDA-mandated crossover trials for highly variable drugs extend development timelines and inflate clinical program costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risedronate Sodium Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Solution, Injection, Others Indication: Osteoporosis, Paget's Disease, Bone Metastasis, Hypercalcemia Delivery Mode: Oral, Parenteral, Intravenous, Directly Administered End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Pfizer Inc., Eli Lilly and Company, Merck & Co., Inc., Amgen Inc., GlaxoSmithKline Plc., Novartis AG, Daiichi Sankyo Co., Ltd., Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risedronate Sodium Market Trends and Innovations
Oral bisphosphonate delivery systems are undergoing material science transformation as manufacturers pursue absorption optimization and patient compliance engineering. Formulation innovation now determines competitive positioning as bioequivalence thresholds tighten.
Modified-release polymer matrices incorporating methacrylic acid copolymers are collapsing the bioavailability variance between originator and generic risedronate tablets. Hospital formularies in Germany and France are accelerating adoption of these enhanced generics for cost-sensitive osteoporosis protocols. The technology is collapsing premium pricing power for extended-release brand formulations.
REACH substance registration requirements for bisphosphonate intermediates are forcing European API manufacturers to consolidate supply relationships and upgrade environmental release controls. Chemical synthesis steps involving phosphorus pentachloride face heightened scrutiny. German and Swiss contract manufacturers are responding with closed-loop solvent recovery investments.
Hospital procurement consortia are consolidating oral bisphosphonate purchasing through centralized tendering platforms that unbundle formulation premiums from clinical outcomes. United States group purchasing organizations are displacing individual hospital negotiations with multi-year volume commitments. This concentration is most visible in Medicare-dependent health systems across Florida and Texas.
Risedronate Sodium Market Segmentation
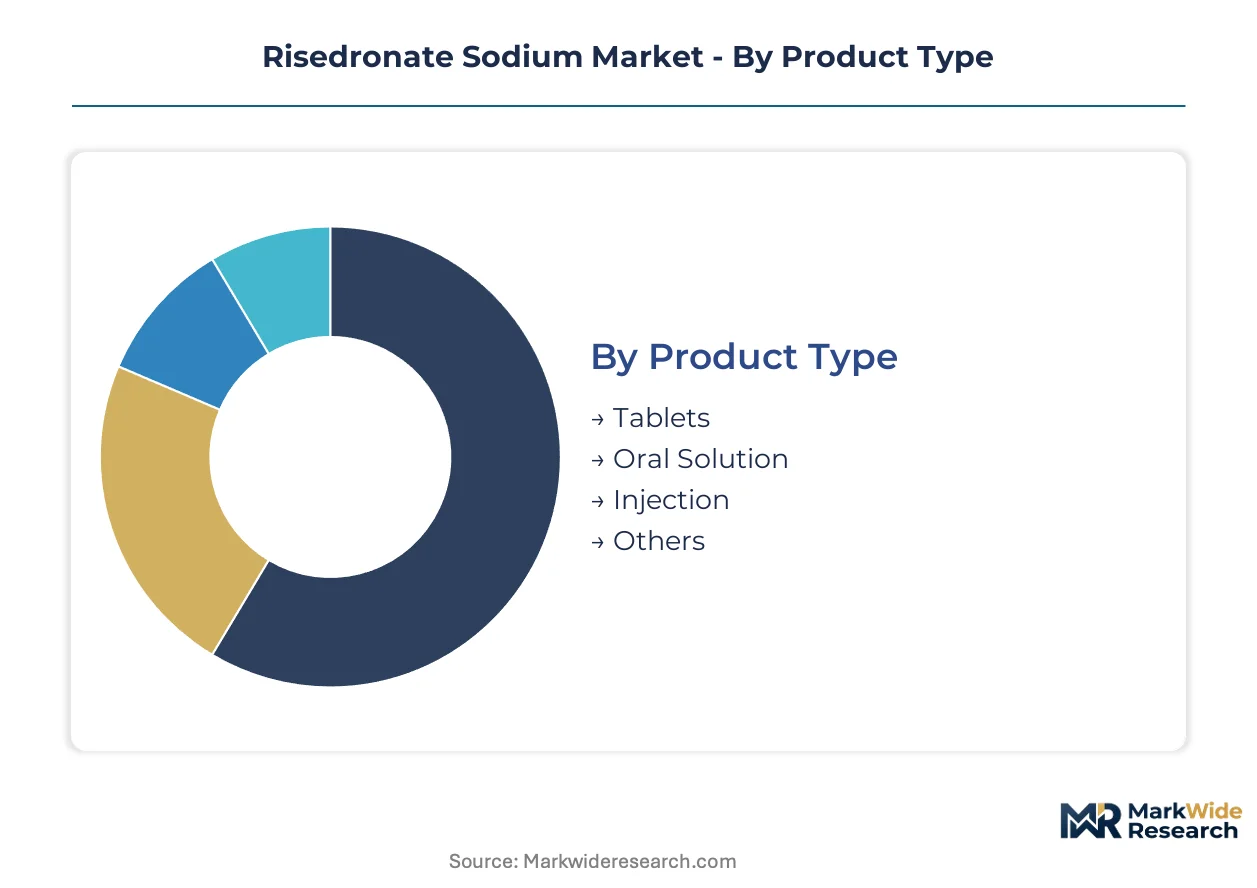
Segmentation in risedronate sodium markets reveals how formulation technology and administration setting determine reimbursement pathways and procurement concentration. Each dimension carries distinct after-sales service intensities, from hospital formulary management to homecare patient adherence programs.
Product Type:
After-sales service intensity varies sharply across formulation formats, with injectable products demanding cold-chain logistics support and tablet formulations requiring patient education infrastructure.
- Tablets:Film-coated immediate-release and extended-release variants incorporate methacrylic acid copolymer systems for pH-dependent gastric protection. Demand concentrates in United States Medicare Part D channels where monthly pharmacy refill programs drive volume; strict fasting requirements necessitate dedicated patient adherence hotlines.
- Injection:Lyophilized powder for reconstitution requires sterile water dilution and intravenous administration protocols. Hospital outpatient centers in Germany and France capture this segment as oncologists integrate bisphosphonates into bone metastasis supportive care; batch-specific stability counseling elevates pharmacist engagement hours.
- Oral Solution:Buffered liquid formulation for patients with swallowing difficulties or esophageal strictures.
- Others:Emerging transdermal patches and sublingual formulations in early clinical development.
Tablets hold the largest share; momentum sits with Injection as hospital infusion protocols expand.
Indication:
Cost tier stratification separates mature osteoporosis reimbursement from premium-priced oncology applications where supportive care budgets absorb higher per-dose expenditure.
- Osteoporosis:Post-menopausal and glucocorticoid-induced bone loss protocols anchor the revenue base with established diagnostic criteria and screening programs. United States health systems drive volume through dual-energy X-ray absorptiometry referral networks; generic substitution pressures compress originator pricing power.
- Bone Metastasis:Skeletal-related event prevention in breast, prostate, and lung cancer patients commands premium positioning. Academic medical centers in the United Kingdom and Switzerland lead protocol adoption; oncology pharmacy stewardship programs mandate specialized handling certification.
- Paget's Disease:Deformed bone remodeling indication with localized prevalence clusters.
- Hypercalcemia:Malignancy-associated calcium elevation requiring rapid intervention.
Osteoporosis holds the largest share; Bone Metastasis is climbing the fastest as oncologist prescribing expands.
Delivery Mode:
Volume concentration patterns track patient compliance barriers, with directly administered formats capturing polypharmacy populations who cannot sustain self-managed oral regimens.
- Oral:Weekly and monthly tablet schedules dominate ambulatory prescription volume. Retail pharmacy chains in Florida and Texas process the highest refill densities; Medicare Advantage plans incentivize 90-day supply fulfillment to reduce gaps in therapy.
- Intravenous:Annual zoledronate-equivalent infusion protocols capture compliance-challenged patients who abandon oral risedronate. Hospital-based infusion centers in California and New York standardize pre-medication with acetaminophen to manage infusion reactions; nursing documentation requirements exceed oral administration by factor of three.
- Parenteral:Subcutaneous depot formulations in limited commercial availability.
- Directly Administered:Supervised dosing in long-term care or clinical trial settings.
Oral holds the largest share; Intravenous is gaining share fastest as health systems invest in supervised administration infrastructure.
End User:
Customer type determines procurement scale and contract negotiation leverage, with hospital consortia extracting volume discounts unavailable to fragmented homecare channels.
- Hospitals:Inpatient and outpatient departments manage formulary placement through pharmacy and therapeutics committees. Group purchasing organizations across the United States consolidate oral bisphosphonate tendering; multi-year contracts with Teva and Pfizer displace individual hospital negotiations.
- Clinics:Rheumatology and endocrinology private practices handle initial diagnosis and therapy initiation. Specialty physician networks in Germany emphasize fracture liaison service coordination; bone health coordinators track adherence metrics across practice locations.
- Homecare:Visiting nurse services for homebound patients with mobility limitations.
- Pharmacies:Community and mail-order dispensing with medication therapy management programs.
Hospitals hold the largest share; Clinics show steepest expansion trajectory as specialty care networks consolidate osteoporosis management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and Medicare reimbursement protocols concentrate buyer power in the United States, while European tendering platforms and Asian manufacturing clusters shape supply-side dynamics across distinct regulatory environments.
United States
Medicare Part D coverage expansion and group purchasing organization consolidation drive volume concentration in Florida and Texas health systems. FDA bioequivalence tightening for generic oral bisphosphonates elevates manufacturing compliance costs. Hospital outpatient infusion centers in California and New York capture compliance-challenged patients through supervised administration protocols.
Germany
Rheumatology specialty networks and fracture liaison services anchor osteoporosis management in Bavaria and North Rhine-Westphalia. EMA quality guideline harmonization accelerates cross-border generic approvals while REACH substance registration forces API manufacturers to upgrade environmental controls. Hospital procurement consortia in Berlin-Brandenburg consolidate oral bisphosphonate tendering through centralized platforms.
India
Contract manufacturing concentration for bisphosphonate active pharmaceutical ingredients centers on Hyderabad and Ahmedabad chemical synthesis clusters. CDSCO manufacturing standards alignment with ICH guidelines streamlines export-oriented production. Dr. Reddy's Laboratories and regional API specialists supply intermediate compounds to European and North American formulation facilities.
Japan
Aging demographics and universal health coverage sustain osteoporosis screening program penetration in Kanto and Kansai regions. PMDA pharmacovigilance requirements and post-market surveillance protocols elevate compliance investment for bisphosphonate marketers. Daiichi Sankyo anchors domestic formulation supply while academic medical centers in Tokyo integrate bone metastasis protocols into oncology supportive care.
United Kingdom
NHS England osteoporosis pathway standardization and fracture risk assessment tool deployment drive diagnostic protocol harmonization across England and Scotland. MHRA pharmacovigilance requirements parallel EMA frameworks with additional post-market surveillance obligations. Academic medical centers in London and Manchester lead bone metastasis bisphosphonate integration into cancer supportive care regimens.
Risedronate Sodium Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers and procurement segments. The vendor base stratifies between scale-driven generic manufacturers, originator brand defenders, and integrated bone-health portfolio operators. Three archetypes dominate: procurement-anchored volume suppliers, extended-release technology specialists, and oncology-supportive care integrators. Competitive moves center on hospital formulary placement contests and gastric coating technology licensing arrangements.
Within the generic manufacturing tier, Teva Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories exemplify scale-driven API-to-formulation integrators. Pfizer Inc. occupies a position among originator-brand defenders leveraging extended-release expertise. Eli Lilly and Company anchors the integrated bone-health portfolio archetype through cross-therapeutic category presence. These three named entities represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Amgen Inc. |
| GlaxoSmithKline Plc. |
| Novartis AG |
| Daiichi Sankyo Co., Ltd. |
| Dr. Reddy's Laboratories |
| Others |
Pricing and Supply Chain Analysis
Hyderabad and Ahmedabad chemical synthesis clusters anchor global bisphosphonate API capacity, with fermentation and phosphorus pentachloride processing throughput dictating downstream formulation pricing power for oral risedronate tablets. Contract manufacturers in these Indian hubs leverage scale economies to compress cost-plus contract terms for European and North American generic marketers.
Pricing Analysis
Cost-plus contracts with methanol and phosphorus trichloride indexation dominate API procurement between Indian manufacturers and European formulation facilities. Three-tier pricing structure across originator extended-release, enhanced generic with methacrylic acid copolymer coating, and standard immediate-release tablets reflects bioequivalence certification tiers and gastric coating sophistication. Pricing pressure stems from hospital procurement consortia in Florida and Texas consolidating tender volumes through multi-year commitments. Medicare-dependent health systems exhibit highest price sensitivity; oncology supportive care channels for bone metastasis applications show lowest sensitivity due to premium positioning.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk planning for risedronate sodium intermediates. API synthesis concentrates in India, China, and Switzerland, with formulation finishing in Germany, the United States, and Japan. Phosphorus pentachloride, methacrylic acid copolymers, and hydroxyapatite reference standards constitute critical input dependencies. REACH substance registration requirements for bisphosphonate intermediates create regulatory chokepoint vulnerability. Distribution runs through hospital group purchasing organizations in the United States and centralized tendering platforms in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as bone metastasis supportive care protocols create prescriber-segment niches outside traditional osteoporosis management. Oncologist adoption curves diverge from rheumatology prescribing patterns, opening positioning space for formulation specialists.
For Market Incumbents: Harden formulary placement through extended-release technology licensing to hospital procurement consortia facing FDA bioequivalence compliance deadlines. Secure backward integration into phosphorus pentachloride supply through captive relationships with Ahmedabad chemical manufacturers. Defend against intravenous zoledronate substitution by embedding patient adherence infrastructure in Medicare Advantage 90-day supply programs.
For New Entrants and Emerging Players: Establish a beachhead in oral solution formulations for dysphagia and esophageal stricture patient populations underserved by tablet-centric incumbents. Target fracture liaison service coordination contracts in German rheumatology specialty networks where bone health coordinator penetration remains incomplete. Pursue go-to-market positioning through hospital outpatient infusion center partnerships for compliance-challenged patient handoffs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation-science specialists with pH-responsive polymer coating capabilities over commodity generic manufacturers. Five-to-ten year viability hinges on gastric coating innovation pipelines and bone metastasis protocol integration depth. Acquisition target archetype: mid-scale API-to-formulation integrators with CDSCO-aligned manufacturing and European export registration. Signal to watch: EMA quality guideline harmonization acceleration triggering cross-border generic approval velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Gastric Coating Technology Licensing | Methacrylic acid copolymer expertise narrows bioequivalence variance for enhanced generic entrants. |
| Hospital Procurement Consortium Partnership | Multi-year volume commitments with Florida and Texas Medicare systems secure formulary placement. |
| Bone Metastasis Protocol Integration | Oncology pharmacy stewardship certification opens premium positioning in academic medical centers. |
| API Manufacturing Scale-Up | Hyderabad and Ahmedabad capacity expansion reduces phosphorus pentachloride dependency exposure. |
| Regulatory Approval Pathway Optimization | FDA bioequivalence study design expertise compresses development timelines for variable drug products. |
Research Methodology
The analysis maps oral bisphosphonate formulation tiers, pH-dependent absorption technologies, and bone metastasis supportive care protocols, each validated through drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary interview intelligence triangulates against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient pool modeling and top-down manufacturer revenue reconciliation anchor volume and value estimates.
Assumptions held fixed include Medicare Part D reimbursement stability, EMA quality guideline harmonization trajectory, and REACH substance registration compliance timelines; variables tested include intravenous zoledronate substitution rates and bone metastasis protocol adoption velocity. Segmentation dimensions span product type, indication, delivery mode, and end user, with regional regulatory clusters modeled separately. CAGRs derive from patient population epidemiology, screening guideline expansion scenarios, and prescriber behavior shift analysis across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, EMA regulatory stringency, or phosphorus intermediate commodity pricing would shift the trajectory. Forecasts reflect documented assumptions and industry stakeholder consensus as of the analysis window. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Germany Pharmaceuticals Market