
 PDE Inhibitors Market | 2026-2036
PDE Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
PDE Inhibitors Market Outlook
REACH compliance is decoupling European manufacturing economics from legacy synthesis routes, forcing reformulation investments that favor scaled producers. Pfizer leverages its vertical integration into active pharmaceutical ingredient supply to sustain margin capture across branded and authorized generic channels. Eli Lilly and Company anchors its position through R&D intensity in next-generation dual-action compounds. Bayer AG competes on manufacturing scale, particularly in injectable formulations for hospital segments.
Phosphodiesterase inhibitors are a class of enzymes that hydrolyze cyclic nucleotides, with selective PDE5 inhibitors operating through nitric oxide-mediated smooth muscle relaxation at specific tissue sites. These compounds serve primary therapeutic purposes in vascular smooth muscle modulation, with oral bioavailability parameters determining clinical utility across cardiovascular and urological indications. Selective PDE5 Inhibitors dominate current prescription volumes due to established safety profiles and broad payer coverage, while Dual-Action PDE Inhibitors represent the fastest-expanding development pipeline as developers target comorbid cardiovascular-pulmonary presentations. Combination Therapies command premium positioning where formulary access permits multi-mechanism protocols in specialty clinics.
The FDA's bioequivalence standards and the EMA's centralized marketing authorization procedures jointly determine market access timelines for new entrants, with divergence in reference product requirements creating parallel development tracks. The EPA's pharmaceutical effluent guidelines and OSHA's containment standards for potent compound handling shape manufacturing location decisions and capital deployment. Stakeholders must monitor evolving pharmacovigilance requirements for cardiovascular signal detection as indication expansion broadens exposure populations beyond traditional risk profiles.
Market Dynamics
The FDA's streamlined approval pathways for repurposed indications are compressing development timelines and reshaping competitive entry economics across the PDE inhibitor landscape.
Growth Catalysts
- Medicare Reimbursement Alignment:United States federal coverage policies favor established PDE5 inhibitor brands, channeling prescription volumes toward reimbursed formulations and accelerating at-home administration adoption.
- REACH-Driven Reformulation:European chemical safety mandates are forcing synthesis route modernization, creating competitive advantage for scaled producers with capital to absorb compliance investments.
- Urology Clinic Expansion:Specialty outpatient facilities are expanding oral tablet dispensing capacity, capturing patient preference for privacy-preserving administration models.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters in specific Asian manufacturing zones, exposing formulation networks to single-source disruption risk and customs processing volatility.
- Cardiovascular Signal Detection Burden:EMA pharmacovigilance requirements for expanded indication populations are extending post-market surveillance obligations and inflating regulatory maintenance costs.
- Generic Substitution Pressure:Authorized generic channels at major retail pharmacy chains are compressing branded pricing power and narrowing therapeutic differentiation windows.
Strategic Opportunities
- Dual-Action Pipeline Positioning:Next-generation compounds targeting comorbid cardiovascular-pulmonary presentations offer white space beyond saturated urology indications, with R&D intensity concentrated at specialty biopharma developers.
- Injectable Hospital Segments:Acute care formulations for surgical recovery and critical care applications remain underpenetrated relative to oral dominance, rewarding manufacturing scale investments.
- Combination Therapy Protocols:Multi-mechanism regimens in specialty clinics command premium positioning where formulary access permits integrated prescribing.
Industry Challenges
- Potent Compound Handling Certification:OSHA containment standards for high-potency active pharmaceutical ingredients are extending facility qualification timelines and constraining contract manufacturing availability.
- Legacy Synthesis Retooling:REACH compliance deadlines are forcing capital-intensive process redevelopment, with mid-scale producers facing stranded asset risk on outdated equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PDE Inhibitors Market |
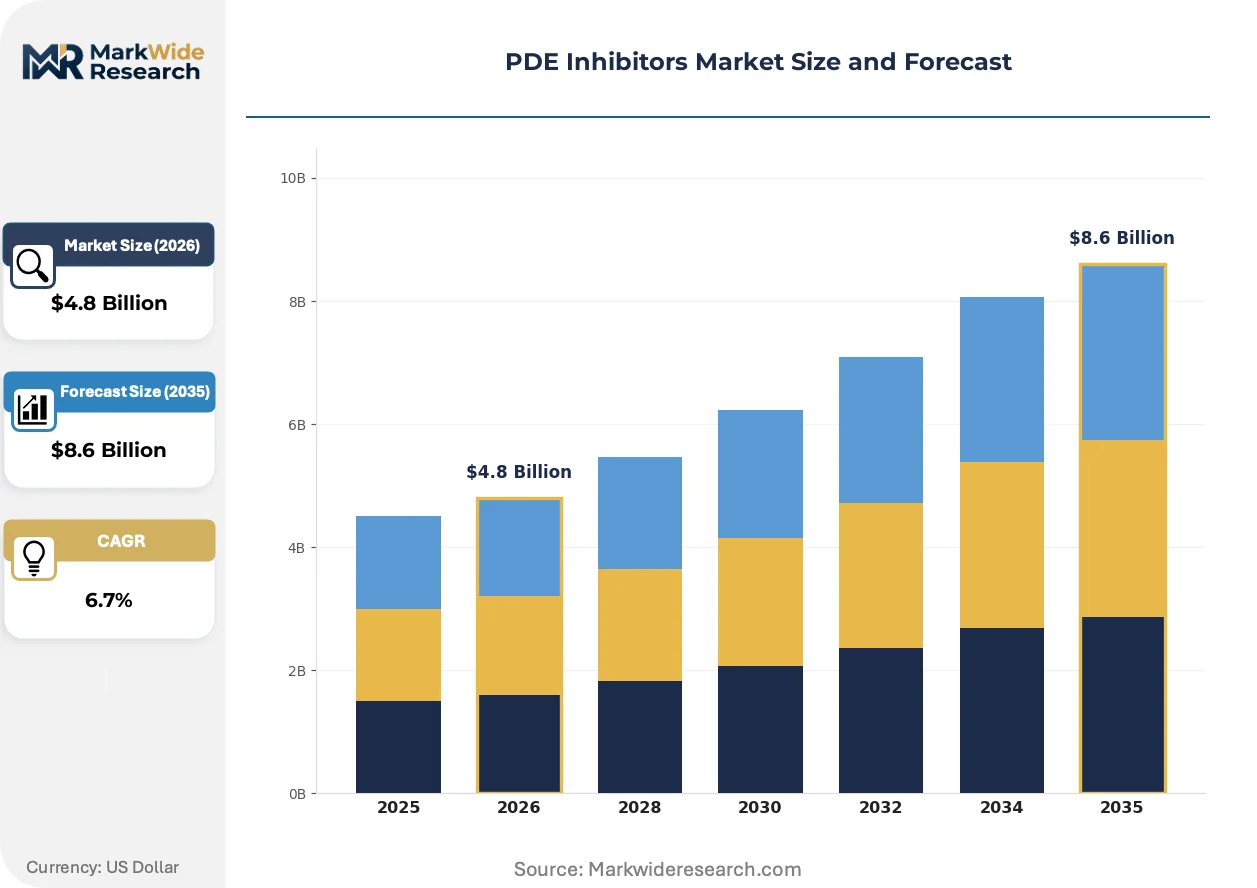
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective PDE5 Inhibitors, Non-Selective PDE Inhibitors, Dual-Action PDE Inhibitors, Combination Therapies Application: Cardiovascular Diseases, Erectile Dysfunction, Respiratory Disorders, Neurological Disorders End User: Hospitals, Specialty Clinics, Home Care Settings, Research Laboratories Formulation: Tablets, Injections, Topical Creams, Inhalation Solutions |
| Companies Covered | Pfizer, Bayer AG, Eli Lilly and Company, AstraZeneca, GlaxoSmithKline, Sanofi, Novartis AG, AbbVie Inc., Takeda Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PDE Inhibitors Market Strategic Shifts
Oral bioavailability optimization and nitric oxide pathway modulation are converging to reshape formulation development priorities, with delivery technology and regulatory science advancing in parallel.
Dual-action PDE inhibitor compounds are absorbing development resources previously directed toward single-mechanism candidates. Specialty cardiovascular and pulmonology clinics are piloting these formulations at accelerated enrollment rates. This absorption pattern is compressing the addressable market for legacy PDE5 monotherapies in comorbid patient populations.
REACH authorization procedures are decoupling European manufacturing economics from legacy synthesis routes. ECHA substance evaluation timelines are forcing parallel track development for alternative chemical pathways. Formulation houses with captive API production are responding by internalizing intermediate manufacturing stages.
At-home administration preference is displacing clinic-based injection protocols across urology and vascular medicine practices. Telehealth prescribing platforms are capturing prescription origination volume previously held by specialty office visits. This channel rotation is most visible in United States markets with established direct-to-patient pharmacy distribution infrastructure.
PDE Inhibitors Market Segmentation
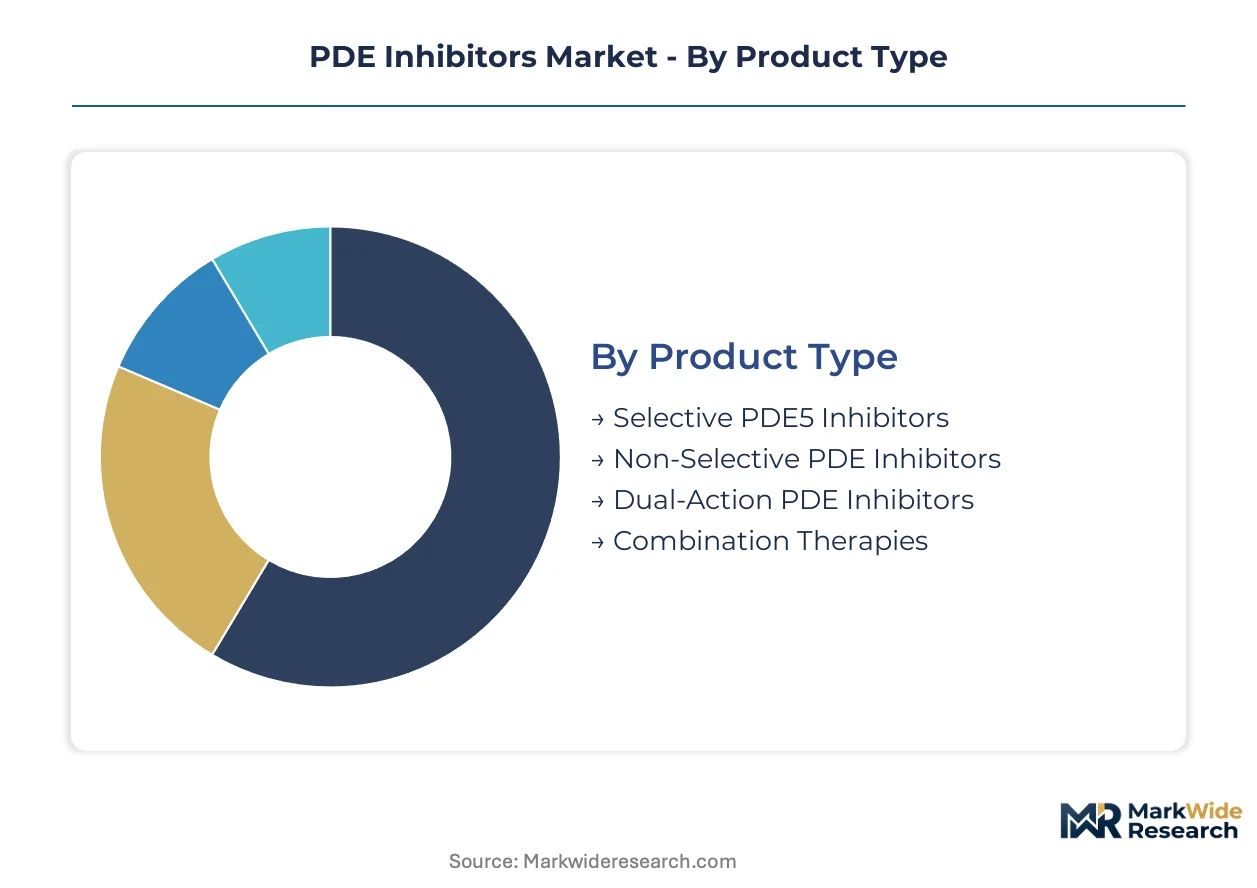
PDE inhibitor segmentation reveals distinct capital deployment profiles across molecular architectures and delivery modalities. Formulation complexity and regulatory burden vary sharply by product category, reshaping where manufacturers concentrate capacity investments.
Product Type:
Selective PDE5 inhibitors demand the heaviest upfront synthesis investment due to chiral purity requirements and nitric oxide pathway specificity. Dual-action compounds require parallel toxicology programs.
- Selective PDE5 Inhibitors:Single-mechanism compounds with established bioequivalence pathways dominate current prescription volumes. United States Medicare reimbursement policies channel demand toward these formulations, though generic substitution compresses branded pricing power in retail pharmacy chains.
- Dual-Action PDE Inhibitors:Next-generation molecules targeting comorbid cardiovascular-pulmonary presentations absorb increasing R&D resources. Specialty cardiovascular clinics in Germany and pulmonology centers in the United States are piloting these at accelerated enrollment rates.
- Non-Selective PDE Inhibitors:Broad-spectrum compounds retain niche positioning in neurological applications where tissue specificity is less critical.
- Combination Therapies:Multi-mechanism regimens command premium positioning in specialty clinics where formulary access permits integrated prescribing protocols.
Most installed capacity flows through Selective PDE5 Inhibitors. Expansion is steepest in Dual-Action PDE Inhibitors.
Application:
Erectile dysfunction applications generate the highest patient volumes, while cardiovascular disease programs carry the longest development timelines and largest safety databases.
- Erectile Dysfunction:Oral tablet demand concentrates in at-home administration models, with telehealth prescribing platforms capturing prescription origination volume previously held by urology office visits. Privacy-preserving administration preferences reinforce this channel rotation.
- Cardiovascular Diseases:Indication expansion into heart failure and pulmonary hypertension populations broadens exposure beyond traditional risk profiles, triggering EMA pharmacovigilance requirements for cardiovascular signal detection that extend post-market surveillance obligations.
- Respiratory Disorders:Inhalation delivery development targets acute care and chronic obstructive pulmonary disease maintenance protocols.
- Neurological Disorders:Blood-brain barrier penetration challenges limit current penetration, with research-stage programs targeting cognitive vascular insufficiency.
Patient volume concentrates in Erectile Dysfunction. Regulatory complexity peaks in Cardiovascular Diseases.
End User:
Hospital procurement operates on tender-based volume contracts, while home care channels reward direct-to-patient distribution infrastructure.
- Home Care Settings:Oral tablet formulations and privacy-preserving administration models are displacing clinic-based protocols. Direct-to-patient pharmacy distribution networks in the United States capture this channel rotation most visibly.
- Specialty Clinics:Urology and cardiovascular outpatient facilities expand oral tablet dispensing capacity. These sites pilot dual-action compounds and combination therapies where formulary access permits premium positioning.
- Hospitals:Injectable formulations for surgical recovery and critical care applications reward manufacturing scale investments, particularly in German and United States acute care networks.
- Research Laboratories:Early-phase development and mechanistic studies support pipeline expansion, with concentration in Boston and Basel clusters.
Prescription origination is shifting fastest toward Home Care Settings. Injectable volume remains concentrated in Hospitals.
Formulation:
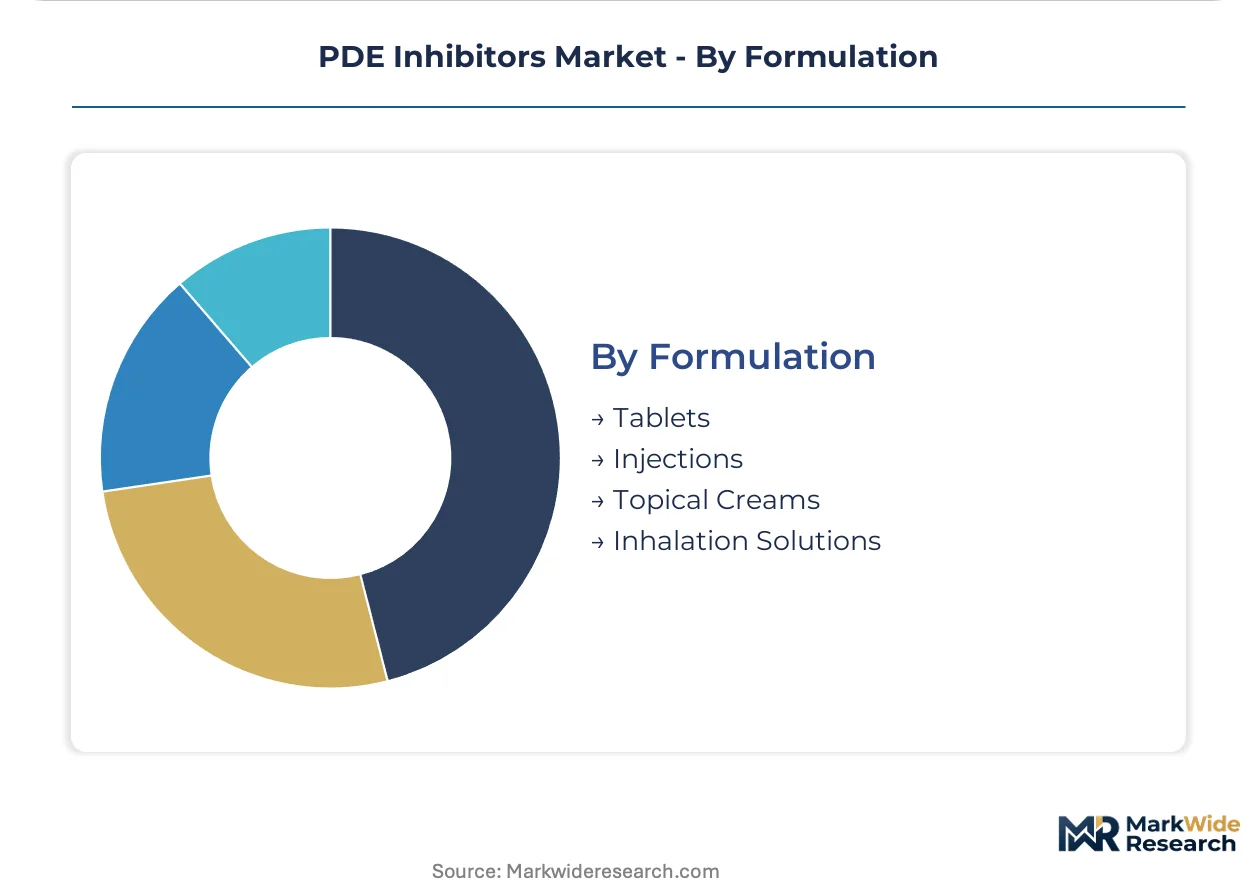
Tablet production requires oral bioavailability optimization and stability testing, while injectable manufacturing demands potent compound handling certification under OSHA containment standards.
- Tablets:Oral solid dosage forms dominate urology and cardiovascular maintenance prescribing. At-home administration preference reinforces tablet demand, with formulation houses optimizing nitric oxide pathway modulation and bioavailability parameters.
- Injections:Acute care formulations for surgical recovery and critical care applications remain underpenetrated relative to oral dominance. Bayer AG competes on manufacturing scale in this segment.
- Topical Creams:Localized delivery targets dermatological and urological applications with reduced systemic exposure.
- Inhalation Solutions:Respiratory-targeted delivery requires specialized particle engineering and device compatibility testing.
Production volume runs predominantly through Tablets. Capacity investment is concentrating in Injections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized urology and cardiovascular research clusters anchor geographic demand distribution for PDE inhibitors. Talent concentration in Boston, Basel, and the Research Triangle shapes pipeline development velocity. Regulatory divergence between FDA and EMA pathways creates parallel commercialization tracks.
United States
Medicare reimbursement policies channel prescription volumes toward established PDE5 inhibitor brands, accelerating at-home administration adoption. The FDA's streamlined approval pathways for repurposed indications compress development timelines for dual-action compounds. Boston's biopharma corridor concentrates R&D intensity in next-generation cardiovascular-pulmonary presentations.
Germany
Specialty cardiovascular clinics in Munich and pulmonology centers in Heidelberg pilot dual-action PDE inhibitors at accelerated enrollment rates. REACH authorization procedures force synthesis route modernization, favoring scaled producers with captive API production. The EMA's centralized marketing authorization procedures determine market access timelines for new entrants.
Switzerland
Basel's pharmaceutical research infrastructure supports mechanistic studies and early-phase development for pipeline expansion. Swissmedic's regulatory framework aligns with EMA standards while offering specialized pathways for innovative formulations. The country's chemical manufacturing heritage underpins process chemistry expertise for complex synthesis routes.
Japan
PMDA's pharmacovigilance requirements for cardiovascular signal detection extend post-market surveillance obligations as indication expansion broadens exposure populations. Tokyo's specialty clinics drive demand for privacy-preserving oral tablet administration models. METI's industrial policy supports domestic formulation capacity for hospital injectable segments.
India
CDSCO's bioequivalence standards and accelerating generic approval timelines position the country as a formulation export hub. Hyderabad and Ahmedabad clusters concentrate API production capacity, though single-source concentration exposes networks to disruption risk. The PLI scheme incentivizes backward integration into active pharmaceutical ingredient manufacturing.
PDE Inhibitors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the PDE inhibitor landscape. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with vertical integration into API supply, mid-scale formulation houses with regional manufacturing footprints, and emerging biopharma developers concentrating R&D resources in dual-action pipelines. Two dominant competitive moves define current positioning: strategic partnerships for distribution access in Medicare-aligned channels, and capacity expansion in injectable formulations for hospital segments.
Among diversified pharmaceutical conglomerates, Pfizer exemplifies the vertically integrated archetype with upstream control over active pharmaceutical ingredient supply. Eli Lilly and Company occupies a position within the R&D-intensive tier, anchoring development resources in next-generation dual-action compounds. Bayer AG represents the manufacturing scale archetype, with particular concentration in injectable formulations for acute care applications.
| Leading Market Players |
|---|
| Pfizer |
| Bayer AG |
| Eli Lilly and Company |
| AstraZeneca |
| GlaxoSmithKline |
| Sanofi |
| Novartis AG |
| AbbVie Inc. |
| Takeda Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Branded-generic divergence in PDE inhibitors splits the market into Medicare-reimbursed originators and authorized generic channels, with this bifurcation manifesting in both pricing power concentration and API sourcing consolidation. Formulation houses with captive active pharmaceutical ingredient production capture margin across both tiers, while pure-play generic manufacturers compete on volume scale and regulatory filing velocity.
Pricing Analysis
Bundled reimbursement protocols in United States Medicare channels sustain premium positioning for established PDE5 inhibitor brands, while unbundled cash-pay segments at retail pharmacy chains drive commodity substitution. Price differentiation rests on FDA bioequivalence certification tiers and vertical integration depth into API supply. Cost compression in authorized generic channels intensifies as major retail chains consolidate procurement volumes. Hospital formulary committees exhibit lowest price sensitivity due to bundled surgical recovery protocols, while direct-to-consumer telehealth platforms face highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from United States and European formulation houses mandate multi-supplier qualification for active pharmaceutical ingredient vendors, constraining contract manufacturing availability. API production concentrates in India, China, and selected Swiss chemical manufacturing zones. Finished formulation draws from specialized chiral synthesis intermediates, nitric oxide pathway modulators, and high-potency containment equipment. Single-source vulnerability in Asian manufacturing clusters exposes networks to customs processing volatility and geopolitical friction. Distribution runs through direct-to-patient pharmacy networks in North America and tender-based hospital procurement systems in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PDE inhibitors function as a stable compounder anchored by Medicare reimbursement durability and chronic disease indication expansion. Demographic aging and cardiovascular-pulmonary comorbidity prevalence sustain prescription volume trajectories across economic cycles.
For Market Incumbents: Extend formulary access through dual-action pipeline advancement and backward integration into high-potency API manufacturing. Generic substitution pressure from authorized channels threatens branded pricing power; defend through Medicare-aligned distribution partnerships and telehealth platform integration. Capacity addition in REACH-compliant European synthesis facilities addresses regulatory tailwinds. For New Entrants and Emerging Players: FDA streamlined approval pathways for repurposed indications in the United States open a window for cardiovascular-pulmonary dual-action compounds. Injectable hospital segments for surgical recovery remain underpenetrated relative to oral dominance. Target specialty cardiovascular clinics in Germany and pulmonology centers in the United States with acute care formulation partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers face stranded asset risk on outdated REACH-noncompliant equipment bases. Long-term viability favors developers with R&D intensity in next-generation mechanisms and manufacturing scale in injectable segments. Acquisition target archetype: formulation houses with captive API production and established FDA bioequivalence pathways. Signal to watch: EMA pharmacovigilance requirement expansion for cardiovascular signal detection in broader patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Action Pipeline Advancement | Next-generation compounds targeting comorbid presentations absorb R&D resources previously directed toward single-mechanism candidates. |
| REACH-Compliant Synthesis Retooling | European chemical safety mandates force capital-intensive process redevelopment that favors scaled producers with captive API production. |
| Injectable Capacity Expansion | Acute care formulations for surgical recovery reward manufacturing scale investments in German and United States hospital networks. |
| Telehealth Platform Integration | Direct-to-patient pharmacy distribution infrastructure captures prescription origination volume from privacy-seeking patient populations. |
| Backward Integration into API Supply | Upstream control over active pharmaceutical ingredient manufacturing sustains margin capture across branded and authorized generic channels. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounds qualitative assessment in operational reality. Secondary validation draws from FDA filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov enrollment data, and Medicare formulary databases. Bottom-up prescription volume modeling triangulates against top-down reimbursement expenditure analysis.
Bottom-up patient flow analysis by treatment line, dosage form, administration route, and regional regulatory cluster generates volume foundations. Top-down expenditure tracking across Medicare, commercial payer, and out-of-pocket channels anchors value estimates. CAGRs derive from segmented growth rate application across the projection horizon. Forecast inputs include EMA pharmacovigilance requirement evolution and FDA repurposed indication approval velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH authorization timeline acceleration or API supply disruption scenarios. Deviation in Medicare reimbursement policy alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market