
 Empty Capsules Market | 2026-2036
Empty Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Empty Capsules Market Intelligence
Market Context
Pharmaceutical distribution through contract manufacturing organizations is rewriting procurement patterns for empty capsules across Europe and Asia. Lonza Group leverages its integrated biologics network to sustain capsule supply agreements with multinational drug makers. ACG Worldwide anchors South Asian production capacity through dedicated manufacturing sites in India. Qualicaps competes in the Japanese market with specialized enteric coating technologies.
Technical Definition and Segments
Empty capsules are cylindrical, two-piece shells manufactured from gelatin or plant-derived polymers, typically sized 000 to 5 with wall thickness of 0.10 to 0.15 millimeters, designed to encase powders, granules, or liquids for oral administration. Gelatin capsules retain dominant volume share due to established dissolution profiles and lower unit costs, though hydroxypropyl methylcellulose capsules are gaining fastest in nutraceutical applications where vegetarian labeling commands shelf price premiums. Pullulan capsules occupy a narrower position in cosmetic and premium supplement segments where oxygen barrier properties justify material cost differentials.
Regulatory Frame
FDA, EMA, and CDSCO each enforce pharmacopeial standards for dissolution, disintegration, and residual moisture that determine capsule qualification for drug master files. These frameworks shape demand by disqualifying non-compliant suppliers and accelerating validation timelines for manufacturers holding pre-approved regulatory dossiers. Stakeholders must monitor evolving monograph revisions and bioequivalence requirements to anticipate specification shifts before formulation commitments lock.
Market Dynamics
Plant-based capsule polymers are compressing the cost premium against gelatin alternatives as CDSCO and EMA tighten residual moisture and dissolution specifications, forcing nutraceutical formulators to revalidate supplier qualifications across dual-source procurement programs.
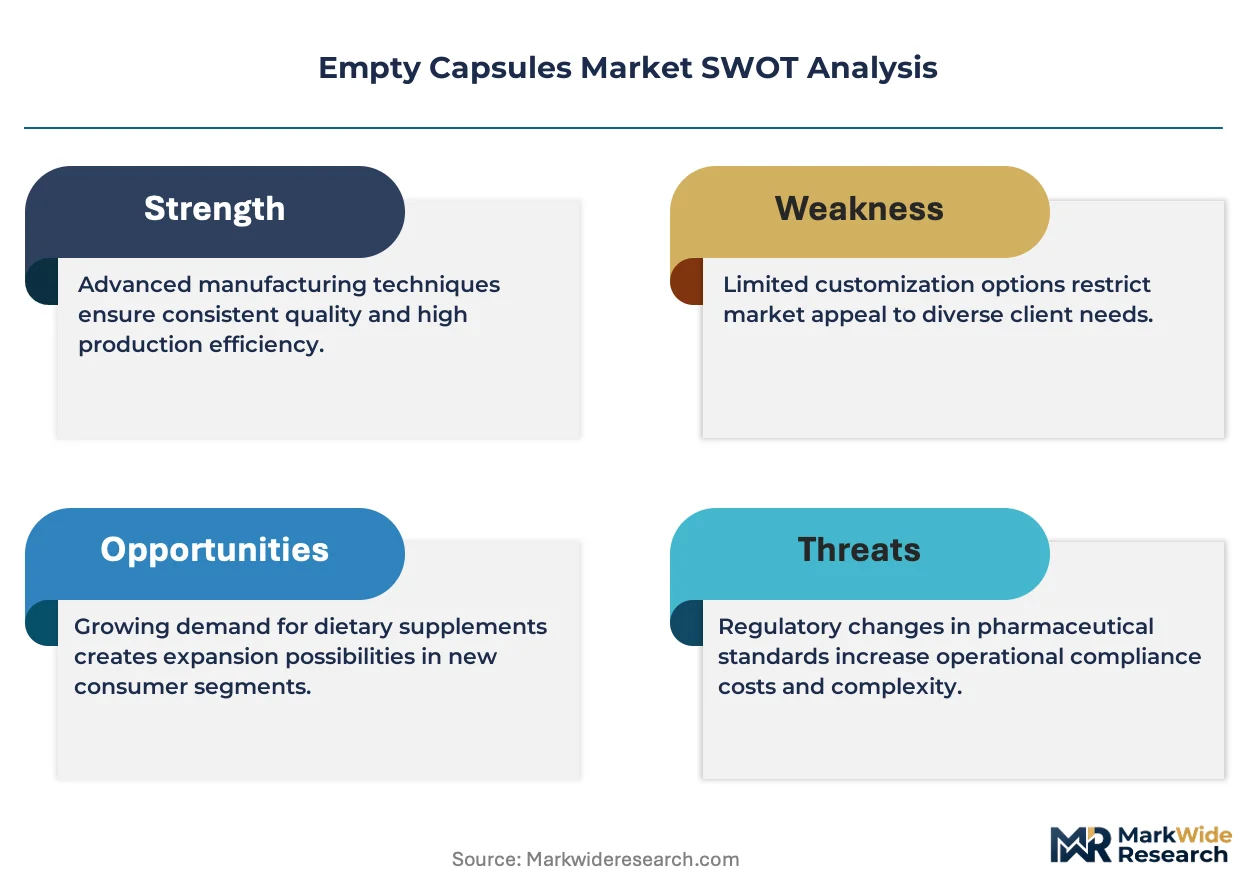
Growth Catalysts
- EMA Pharmacopeial Revisions:Tightened monograph standards for disintegration profiles are disqualifying legacy gelatin suppliers and accelerating validation timelines for HPMC-certified manufacturers.
- Halal Certification Mandates:Muslim-majority markets in Southeast Asia and the Middle East now require plant-derived shells for pharmaceutical and nutraceutical imports, redirecting procurement toward pullulan and HPMC variants.
- Biologics Cold-Chain Expansion:Temperature-stable capsule polymers with modified release properties are capturing formulation contracts for biologic oral delivery programs.
Market Restraints
- Gelatin Price Volatility:Bovine and porcine hide supply fluctuations in Brazil and Argentina transmit directly to capsule unit economics, compressing margin buffers for commodity-grade producers.
- Pullulan Raw Material Concentration:Tapioca starch fermentation capacity clusters in Thailand and southern China, creating single-source vulnerability for oxygen-barrier premium capsules.
- Cross-Linking Limitations:Aldehyde-sensitive APIs remain incompatible with standard gelatin dissolution profiles, restricting capsule format adoption for certain oncology and anti-infective formulations.
Strategic Opportunities
- Indian CDSCO Pre-Approval Pathways:Accelerated drug master file qualification timelines for capsules meeting revised moisture specifications are opening first-mover positioning for validated suppliers.
- Personalized Nutrition Compounding:Small-batch HPMC capsule production for direct-to-consumer supplement subscriptions is bypassing traditional wholesale-pharmacy distribution.
- EU Green Deal Biopolymer Incentives:Fermentation-derived pullulan qualifies for sustainable manufacturing tax credits under circular economy frameworks, offsetting capital intensity for new production lines.
Industry Challenges
- Multinational Validation Timelines:Dual-source qualification for FDA and EMA dossiers requires 18-24 month stability studies, locking formulation commitments before competitive sourcing can mature.
- Specialized Coating Technician Scarcity:Enteric coating application for targeted-release capsules demands polymer-chemistry expertise that outpaces vocational training program output in India and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Empty Capsules Market |
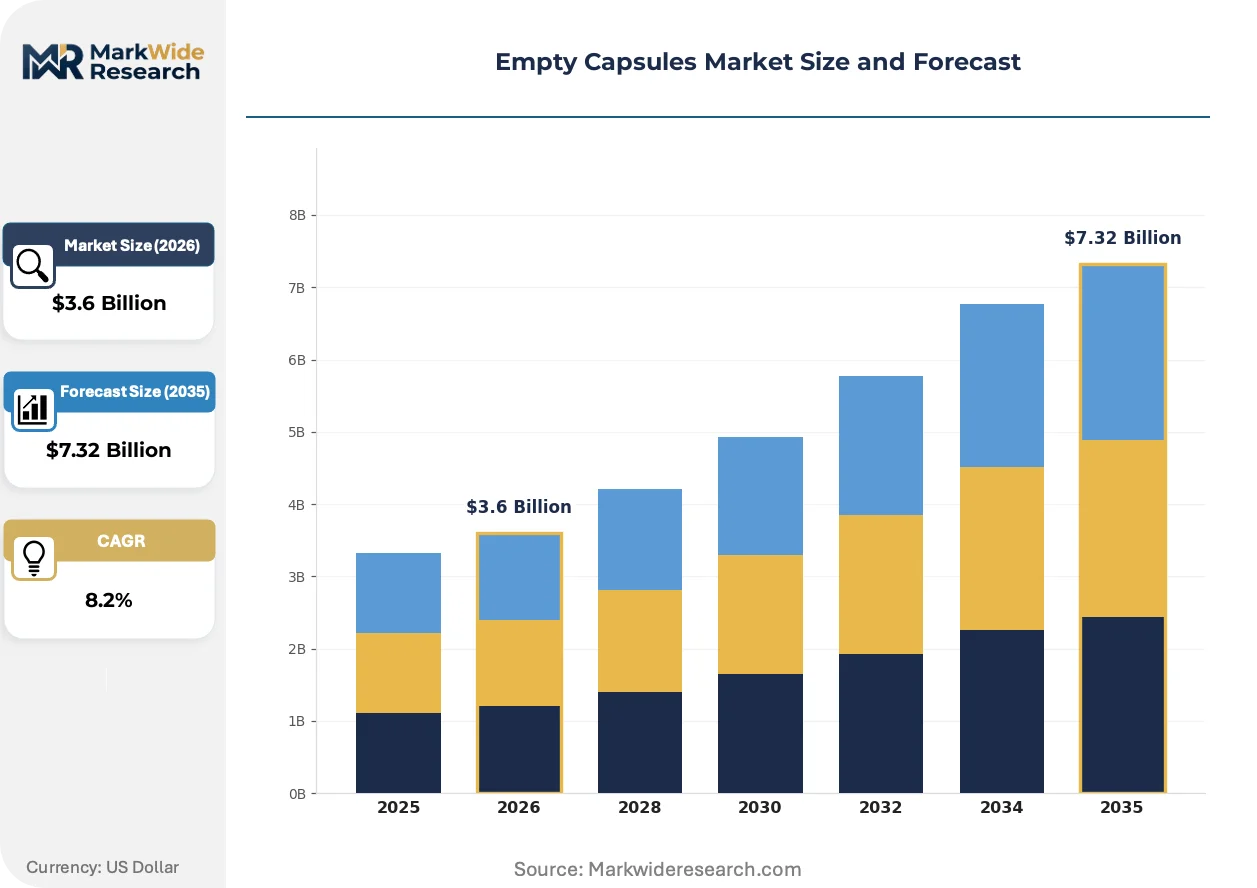
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $7.32 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin Capsules, Hydroxypropyl Methylcellulose Capsules, Pullulan Capsules, Starch Capsules, Others Application: Pharmaceuticals, Nutraceuticals, Veterinary, Cosmetics, Food Supplements End User: Contract Manufacturers, Formulation Companies, Pharmacies, Nutraceutical Producers, Cosmetic Manufacturers Packaging Type: Blister Packs, Bottles, Sachets, Bulk Packaging, Strips |
| Companies Covered | Lonza Group, ACG Worldwide, Qualicaps, CapsCanada Corporation, Suheung Co. Ltd., Natural Capsules Limited, HealthCaps India Ltd., Sunil Healthcare Ltd., Catalent Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Empty Capsules Market Strategic Shifts & Innovations
Capsule manufacturing is converging with precision fermentation and advanced coating deposition, collapsing traditional boundaries between excipient supply and finished-dose engineering.
Continuous HPMC extrusion with inline moisture control is collapsing batch-to-batch variability that previously required post-production sorting and rejection. Nutraceutical contract manufacturers in Germany are adopting these systems to meet EMA certification windows without holding excessive safety stock. The technology compresses working capital requirements while tightening dissolution specification compliance.
EMA's revised gelatin monograph and residual solvent testing protocols are disqualifying suppliers lacking validated analytical methods. Pharmaceutical sponsors now require capsule vendors to submit method-transfer documentation before formulation development begins. The policy shift concentrates procurement among manufacturers with pre-established regulatory dossiers.
Direct purchasing relationships between supplement brands and capsule producers are displacing traditional excipient distributors in North American and European markets. Large nutraceutical marketers now specify polymer grade, wall thickness, and printing requirements in master service agreements rather than accepting distributor-assigned stock. The pattern is most pronounced in subscription-based wellness companies seeking supply chain transparency for consumer messaging.
Empty Capsules Market Segmentation
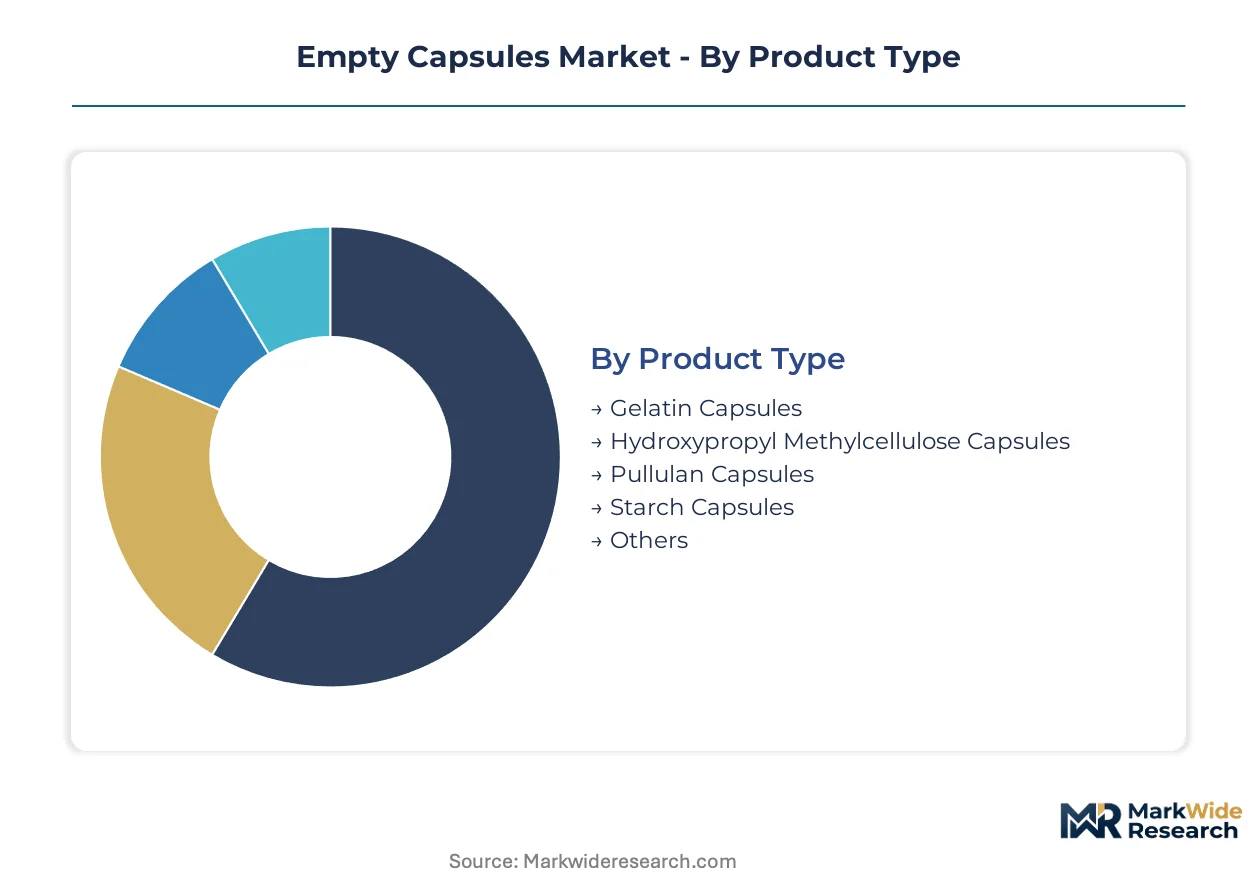
Empty capsule procurement patterns diverge sharply across material chemistry, end-use specifications, and regulatory exposure. Formulators select shell polymers based on dissolution kinetics, certification requirements, and API compatibility rather than unit cost alone.
Product Type:
Mature gelatin-based manufacturing competes against emerging plant-derived alternatives as EMA and CDSCO tighten pharmacopeial standards.
- Gelatin Capsules:Bovine and porcine collagen derivatives dominate current volume through established dissolution profiles and lower raw material costs. Pharmaceutical sponsors in Germany and India retain gelatin for non-halal formulations where cross-linking stability matters.
- Hydroxypropyl Methylcellulose Capsules:Cellulose ether polymers enable vegetarian and halal certifications that command shelf price premiums in nutraceutical channels. CDSCO's revised moisture specifications are accelerating validation timelines for HPMC-certified suppliers in Mumbai and Hyderabad manufacturing clusters.
- Pullulan Capsules:Fermented tapioca starch polymers deliver superior oxygen barrier properties for oxidation-sensitive APIs and premium cosmetic applications.
- Starch Capsules:Modified potato and corn starch variants serve cost-sensitive veterinary and food supplement segments with limited regulatory stringency.
- Others:Carrageenan and pectin-based experimental shells occupy niche positions in personalized nutrition compounding.
Gelatin Capsules retain volume leadership; Hydroxypropyl Methylcellulose Capsules hold the steepest expansion curve.
Application:
Regulatory intensity separates high-specification pharmaceutical demand from commoditized food and cosmetic uses.
- Pharmaceuticals:Oral solid dosage forms for prescription drugs require FDA and EMA drug master file qualification with validated dissolution and disintegration profiles. Multinational sponsors in Basel and Boston specify polymer grade in quality agreements.
- Nutraceuticals:Dietary supplements and functional foods drive pullulan and HPMC volume as halal certification mandates reshape procurement in Southeast Asian import markets.
- Veterinary:Animal health formulations tolerate wider specification bands, enabling starch and lower-grade gelatin sourcing from Brazilian tannery byproduct streams.
- Cosmetics:Oxygen-barrier capsules for ingestible beauty products concentrate demand in Japanese and South Korean premium channels.
- Food Supplements:Sports nutrition and meal replacement powders favor bulk-packaged gelatin shells with minimal certification overhead.
Pharmaceuticals anchor revenue concentration; Nutraceuticals expand most quickly as certification requirements proliferate.
End User:
Supply chain position determines specification authority and volume commitment scale.
- Contract Manufacturers:CDMOs in India and Germany consolidate procurement across multiple sponsor programs, requiring dual-source qualification for FDA and EMA dossiers. Lonza Group and ACG Worldwide anchor this channel through integrated manufacturing networks.
- Formulation Companies:Mid-size drug developers specify capsule polymers during pre-formulation stages, locking supplier commitments before stability studies begin.
- Pharmacies:Compounding pharmacies in North American markets source small-batch HPMC for personalized hormone and nutrient protocols.
- Nutraceutical Producers:Direct-to-consumer supplement brands now bypass distributors to specify polymer grade and printing requirements in master service agreements.
- Cosmetic Manufacturers:Premium skincare houses in Tokyo and Seoul commission custom pullulan shells with brand-specific colorants and oxygen barrier tuning.
Contract Manufacturers dominate procurement volume; Nutraceutical Producers are gaining share fastest through disintermediation.
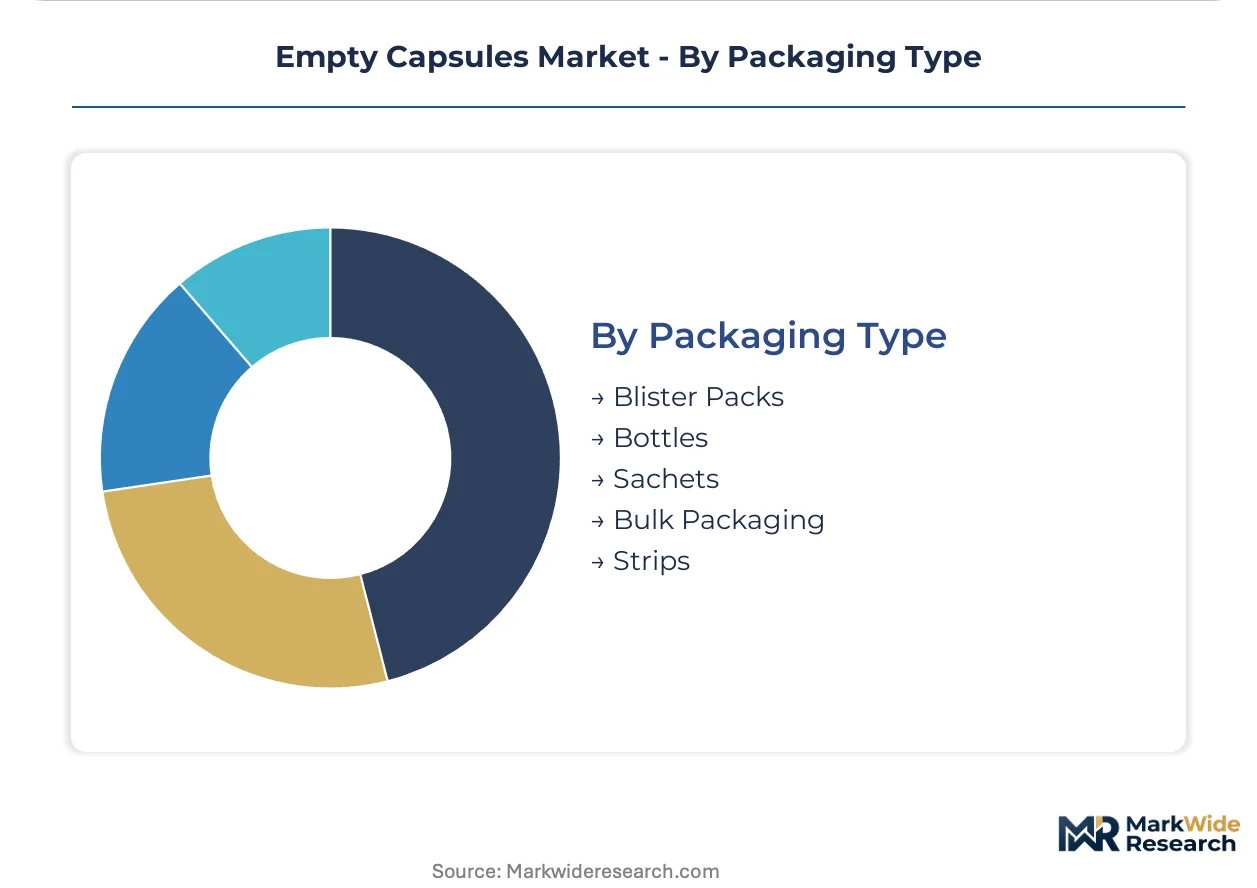
Packaging Type:
Distribution channel requirements shape secondary packaging selection and unit economics.
- Blister Packs:Unit-dose aluminum-PVC configurations dominate pharmaceutical retail in European and North American markets with child-resistance and tamper-evidence mandates.
- Bottles:High-count HDPE and glass containers serve chronic medication programs and wholesale pharmacy distribution with desiccant integration for moisture-sensitive HPMC contents.
- Sachets:Single-serve foil laminates expand in travel-size nutraceutical and cosmetic sampling programs across Asian convenience retail.
- Bulk Packaging:50,000-unit drums and supersacks supply contract manufacturing lines with minimal handling cost for high-volume gelatin formulations.
- Strips:Paper-backed peelable formats serve veterinary and emerging market pharmaceutical channels with basic environmental protection.
Blister Packs retain format leadership; Sachets climb the fastest on direct-to-consumer wellness brand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA pharmacopeial revisions and CDSCO moisture specifications are redirecting procurement toward validated HPMC and pullulan suppliers across manufacturing clusters in Germany, India, Japan, the United States, and South Korea.
United States
FDA drug master file qualification timelines favor capsule manufacturers with pre-validated dissolution profiles. Boston-area biotech sponsors specify polymer grade during pre-formulation stages, locking supplier commitments before stability studies begin. New Jersey contract manufacturing corridors consolidate procurement across multiple sponsor programs.
Germany
EMA tightened monograph standards for disintegration profiles disqualify legacy gelatin suppliers. Bavarian nutraceutical contract manufacturers adopt continuous HPMC extrusion systems to meet certification windows without excessive safety stock. Frankfurt-Rhine-Main logistics hubs distribute EMA-qualified capsules across European pharmaceutical networks.
India
CDSCO accelerated drug master file pathways for capsules meeting revised moisture specifications open first-mover positioning. Mumbai and Hyderabad manufacturing clusters expand HPMC-certified production capacity. Gujarat-based tannery byproduct streams supply lower-grade gelatin for veterinary formulations.
Japan
PMDA oxygen-barrier specifications for oxidation-sensitive APIs concentrate pullulan demand in premium cosmetic and pharmaceutical channels. Osaka-Kobe industrial corridors host specialized enteric coating application facilities. Tokyo-headquartered supplement brands commission custom shell specifications for direct-to-consumer distribution.
South Korea
MFDS halal certification mandates for pharmaceutical imports redirect procurement toward plant-derived shells. Seoul-Incheon biologics clusters seek temperature-stable capsule polymers with modified release properties. Busan-Ulsan fermentation capacity expands tapioca starch processing for regional pullulan supply.
Empty Capsules Market Key Industry Players
On the supply side, the industry is consolidating around integrated biologics networks and specialized coating capabilities. Three archetypes dominate: multinational CDMOs with captive capsule supply, regional specialists in plant-derived polymers, and fermentation-based pullulan producers. Competitive moves center on dual-source qualification for FDA and EMA dossiers, plus continuous extrusion technology licensing to compress batch variability.
Within the integrated CDMO tier, Lonza Group and Catalent Inc. exemplify network-scale procurement consolidation across sponsor programs. ACG Worldwide anchors South Asian production capacity through its India-based manufacturing footprint. Among coating specialists, Qualicaps occupies a position in Japanese and Asia-Pacific markets where enteric deposition expertise commands formulation contracts.
| Leading Market Players |
|---|
| Lonza Group |
| ACG Worldwide |
| Qualicaps |
| CapsCanada Corporation |
| Suheung Co. Ltd. |
| Natural Capsules Limited |
| HealthCaps India Ltd. |
| Sunil Healthcare Ltd. |
| Catalent Inc. |
| Others |
Cost & Logistics Intelligence
Tapioca starch fermentation capacity in Thailand and southern China anchors pullulan capsule economics, concentrating margin capture among oxygen-barrier specialists while gelatin producers in Brazil and Argentina absorb hide supply volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pullulan oxygen-barrier shells from HPMC vegetarian-certified grades from commodity gelatin volumes. Price differentiation rests on halal certification tier and EMA pre-validation status, with CDSCO moisture specification compliance commanding sourcing premiums. Cost compression in standard-grade gelatin is intensifying because Brazilian tannery byproduct supply fluctuations transmit directly to unit economics. Contract manufacturers show least price sensitivity due to dual-source qualification lock-in, while veterinary formulators remain most sensitive.
Supply Chain Analysis
Export-control restrictions on pharmaceutical-grade HPMC polymer technology limit capacity expansion licensing from German and Japanese equipment suppliers to Indian manufacturing clusters. Geographic supply concentration centers on India, Germany, and Japan for finished shells, with raw material dependencies on Thai tapioca starch, Brazilian bovine hides, and Chinese cellulose ether precursors. Single-source vulnerability runs through concentrated tapioca fermentation infrastructure. Distribution runs through direct master service agreements between capsule producers and nutraceutical brands, displacing traditional excipient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based polymer disruption is compressing gelatin's volume dominance as EMA pharmacopeial revisions disqualify legacy suppliers, creating first-mover windows for validated HPMC and pullulan producers.
For Market Incumbents: Insulate market position through backward integration into tapioca starch fermentation capacity in Thailand and captive HPMC polymer production in India. CDSCO accelerated validation timelines threaten non-compliant suppliers. Certification investment in dual FDA-EMA dossiers locks formulation commitments before competitive sourcing matures. For New Entrants and Emerging Players: Southeast Asian halal-mandate markets offer underpenetrated demand for pullulan and HPMC shells as MFDS and import authorities tighten plant-derived requirements. Personalized nutrition compounding for North American subscription wellness brands presents the most penetrable white-space. Go-to-market through direct polymer-grade specification in master service agreements bypasses distributor gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian CDMOs holding captive capsule supply and EMA-prevalidated manufacturing footprints. Long-term viability favors fermentation-based pullulan producers qualifying for EU Green Deal sustainable manufacturing tax credits. Watch for CDSCO moisture specification enforcement as inflection signal for supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous HPMC Extrusion Technology Licensing | Bavarian contract manufacturers adopt inline moisture control to compress batch variability and working capital. |
| Dual-Source Qualification for FDA-EMA Dossiers | Multinational sponsors lock supplier commitments before stability studies begin, favoring pre-validated manufacturers. |
| Backward Integration into Tapioca Fermentation | Pullulan producers in Busan-Ulsan expand regional starch processing to offset Thai supply concentration risk. |
| Halal Certification Investment | Southeast Asian import mandates redirect procurement toward plant-derived shell specialists. |
| Direct-to-Consumer Supply Chain Disintermediation | Subscription wellness brands specify polymer grade and printing requirements, bypassing traditional distributors. |
Research Approach
A spread of perspectives from CDSCO regulatory affairs leads, EMA quality agreement managers, nutraceutical procurement directors, and pharmaceutical formulation scientists converged on the working assumptions for supply-demand balances. Primary fieldwork combined structured interviews with secondary validation through FDA drug master file databases, EMA submission records, CDSCO manufacturing license registries, and customs trade data for gelatin and HPMC polymer flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by material chemistry, end-use application, regulatory certification tier, and geographic manufacturing cluster. CAGRs were derived from weighted capacity expansion timelines and formulation commitment lock-in patterns. Industry-specific inputs included EMA pharmacopeial revision implementation schedules and CDSCO accelerated validation pathway uptake rates.
Practitioners should monitor EMA monograph enforcement intensity and CDSCO moisture specification audit outcomes for early signals of supplier disqualification waves. Forecasts reflect assumptions on regulatory timeline adherence and polymer technology licensing flows. Material shifts in halal certification mandate geographic coverage or tapioca starch supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Immunosuppressive Drugs Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market