
 HPV Vaccines Market | 2026-2036
HPV Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
HPV Vaccines Market Outlook
Aluminum adjuvant reformulation is decoupling cost structures from legacy Merck & Co., Inc. supply models. Merck & Co., Inc. dominates nonavalent production through captive antigen manufacturing and FDA-validated facilities. GlaxoSmithKline plc leverages its AS04 adjuvant platform to differentiate bivalent positioning in European tenders. Serum Institute of India anchors emerging-market volume through WHO prequalified bivalent supply at price points below multinational benchmarks.
Human papillomavirus vaccines are prophylactic biologics containing purified L1 major capsid proteins self-assembled into virus-like particles, typically formulated with aluminum-containing adjuvants and administered via intramuscular injection to induce neutralizing antibodies against oncogenic HPV serotypes. Nonavalent formulations now lead value generation due to broader serotype coverage, while intramuscular delivery remains the standard route with subcutaneous alternatives gaining traction in resource-limited settings where cold-chain constraints complicate needle disposal. Adolescent programs represent the mature volume base, though young adult catch-up cohorts in Asia-Pacific markets are expanding faster as national immunization schedules extend upper age limits.
FDA batch release requirements and WHO prequalification standards shape manufacturing compliance costs and market access timelines for new entrants. EMA's evolving guidance on vaccine interchangeability influences procurement flexibility across European national programs. India's CDSCO and PLI scheme are accelerating domestic bivalent and quadrivalent capacity, altering import dependency patterns. Stakeholders must monitor regulatory divergence between stringent-authority and prequalification pathways as this determines which manufacturers can supply government tenders versus private channels.
Market Dynamics
Nonavalent formulations are displacing bivalent and quadrivalent alternatives in procurement tenders, compressing manufacturing economics toward higher-complexity antigen production and captive adjuvant supply chains.
Growth Catalysts
- WHO prequalification pathway:Lower-income markets are accelerating product registration timelines through this streamlined approval mechanism, expanding addressable patient pools in Sub-Saharan Africa and Southeast Asia.
- School-based immunization mandates:Brazil's national adolescent health program is widening the routine vaccination cohort, creating predictable demand visibility for multiyear supply contracts.
- Domestic manufacturing scale-up:India's PLI scheme is incentivizing localized bivalent and quadrivalent capacity, reducing import dependency and enabling price-competitive tender participation.
Market Restraints
- Aluminum adjuvant supply concentration:Legacy dependence on Merck's captive production infrastructure limits cost competition and creates single-source vulnerability for nonavalent formulations.
- Cold-chain infrastructure gaps:Intramuscular delivery requirements complicate last-mile distribution in rural India and northern Brazil, constraining effective reach.
- Regulatory divergence costs:EMA's evolving interchangeability guidance creates compliance friction for manufacturers seeking to supply both European tenders and WHO prequalification channels simultaneously.
Strategic Opportunities
- Young adult catch-up expansion:Asia-Pacific national immunization schedules extending upper age limits are opening new cohorts in South Korea and Thailand previously excluded from routine programs.
- Subcutaneous delivery alternatives:Needle-free and reduced cold-chain formulations are penetrating resource-limited settings where disposal logistics and refrigeration constraints limit intramuscular adoption.
- CDSCO accelerated approval:India's streamlined domestic regulatory pathway is enabling faster market entry for indigenous manufacturers targeting government procurement.
Industry Challenges
- Antigen manufacturing skill scarcity:Yeast-based VLP production expertise concentrates in FDA-validated facilities, limiting workforce mobility and new entrant capability building.
- Batch release timeline compression:FDA lot release requirements and WHO prequalification standards impose parallel compliance burdens that extend time-to-revenue for novel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPV Vaccines Market |
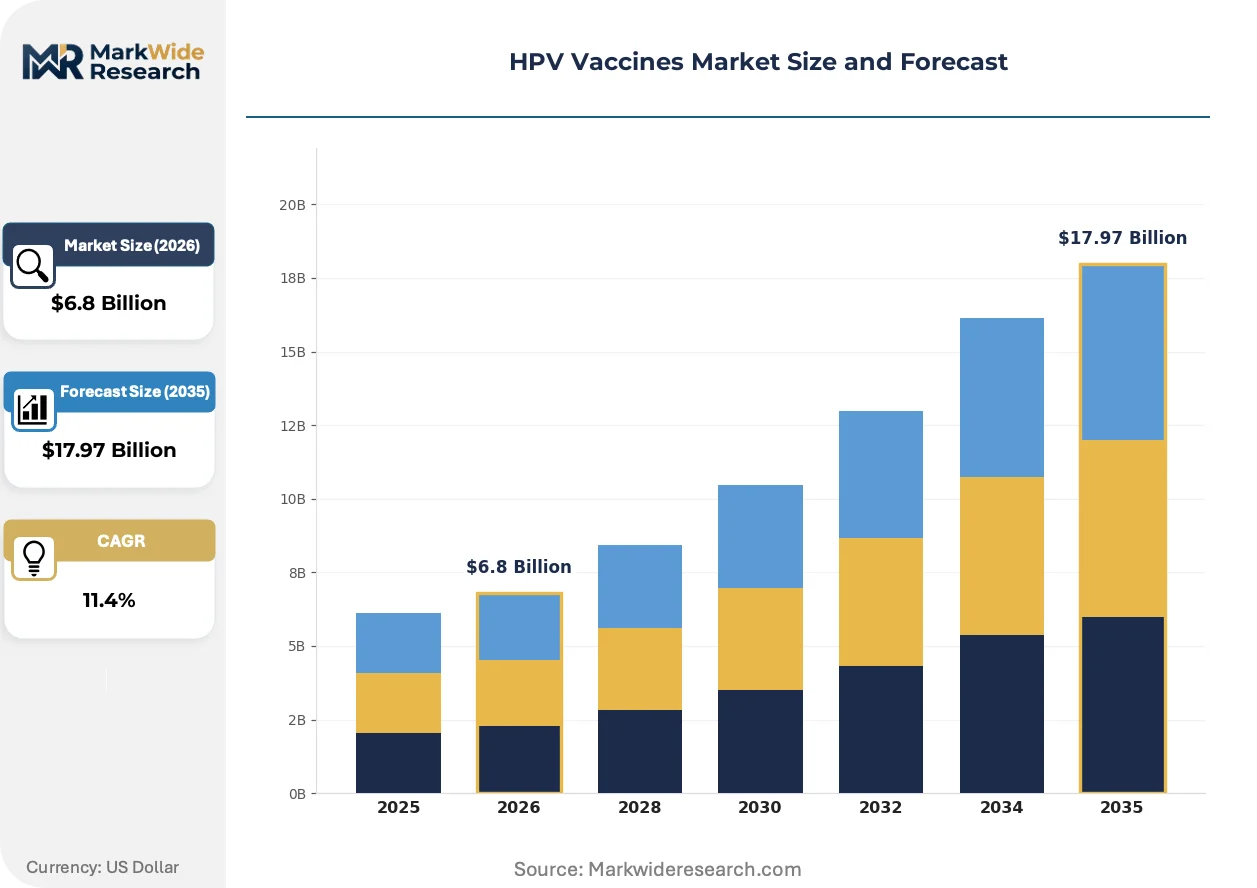
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrivalent, Bivalent, Nonavalent, Others Delivery Mode: Intramuscular, Subcutaneous, Oral, Nasal End User: Hospitals, Clinics, Pharmacies, Preventive Health Centers Age Group: Adolescents, Young Adults, Adults, Seniors |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Serum Institute of India, Bharat Biotech, Xiamen Innovax Biotech Co., Ltd., Walvax Biotechnology Co., Ltd., Wantai BioPharm, Sanofi, INOVIO Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPV Vaccines Market Strategic Shifts
Manufacturing technology and regulatory pathway evolution are compressing competitive moats around legacy supply structures while opening procurement flexibility for new market entrants.
Nonavalent L1 VLP self-assembly platforms are consolidating manufacturing economics around broader serotype coverage. National immunization programs in high-burden markets are prioritizing these formulations in tender specifications despite higher per-dose costs. This technology is consolidating competitive positioning toward manufacturers with integrated antigen and adjuvant production capabilities.
EMA's vaccine interchangeability guidance revision is altering procurement flexibility across European national programs. The framework permits mixed-schedule administration under specified conditions, reducing lock-in effects for single-supplier contracts. Tender authorities in France and Germany are responding with shorter contract durations and multi-source qualification requirements.
Public procurement consolidation is compressing supplier fragmentation in emerging markets. Government tender authorities in India and Brazil are aggregating demand into multiyear framework agreements, displacing fragmented private-channel distribution. This concentration is most visible in India's state-level immunization programs, where centralized purchasing is squeezing distributor margins and favoring direct manufacturer relationships.
HPV Vaccines Market Segmentation
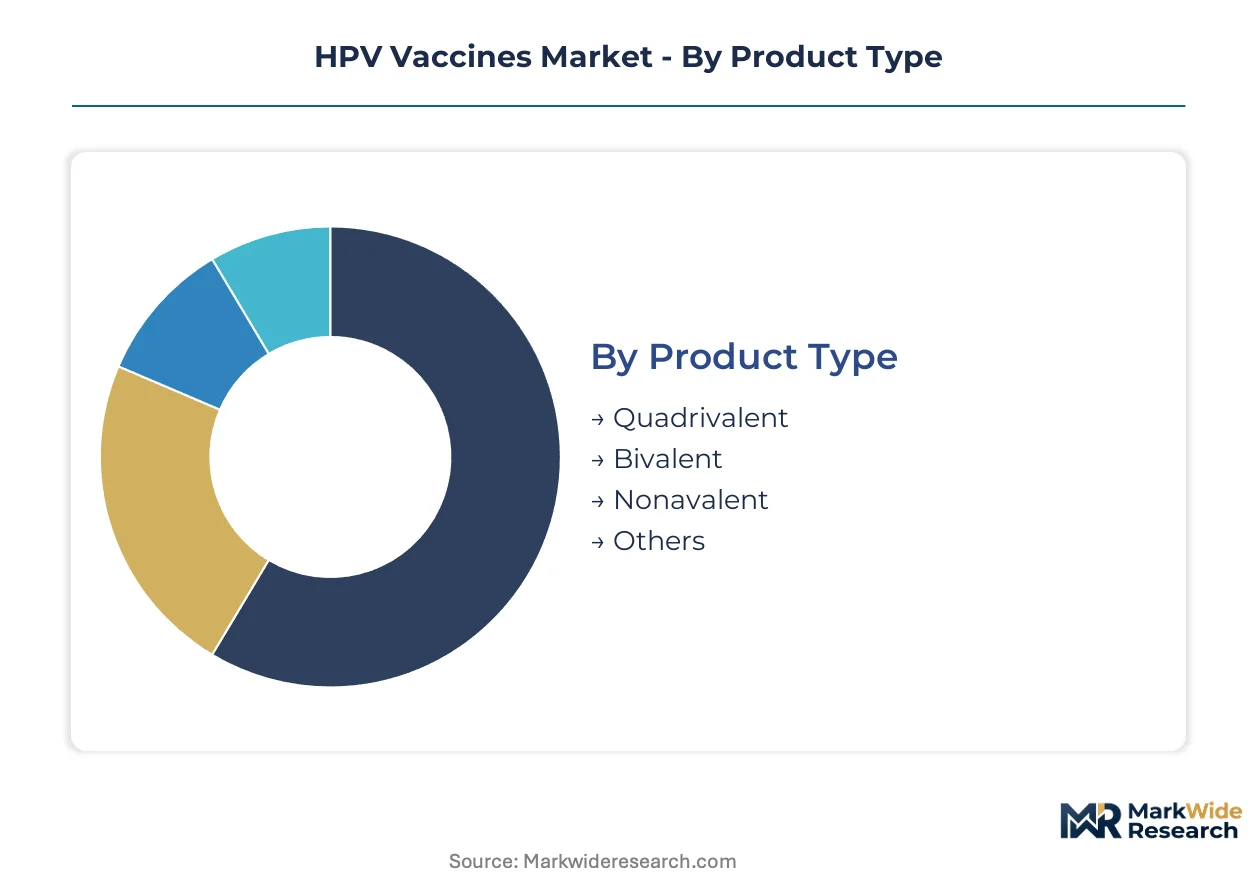
HPV vaccine procurement patterns diverge sharply across formulation complexity, administration logistics, and patient demographics. Understanding these splits reveals where manufacturing investments concentrate and which channels offer entry points for new suppliers.
Product Type:
Capital intensity escalates with serotype coverage due to antigen manufacturing complexity and adjuvant integration requirements.
- Nonavalent:Nine-valent L1 VLP formulations incorporate aluminum-containing adjuvants targeting oncogenic serotypes 6, 11, 16, 18, 31, 33, 45, 52, and 58. Procurement tenders in Brazil and national immunization programs across Europe are consolidating demand around this segment despite per-dose premiums. FDA-validated facilities with captive yeast-based production dominate supply.
- Bivalent:AS04-adjuvanted formulations targeting serotypes 16 and 18 leverage GlaxoSmithKline's proprietary adjuvant platform. India's PLI scheme is accelerating domestic capacity for this segment, with Serum Institute of India anchoring WHO-prequalified supply at price points below multinational benchmarks.
- Quadrivalent:Four-valent coverage of serotypes 6, 11, 16, and 18 retains procurement relevance in cost-constrained tenders.
- Others:Investigational therapeutic vaccines and next-generation VLP platforms remain pre-commercial.
Most installed capacity flows through Nonavalent. Expansion is steepest in Bivalent.
Delivery Mode:
Route selection determines cold-chain infrastructure requirements and last-mile distribution economics across immunization programs.
- Intramuscular:Standard administration into deltoid or vastus lateralis muscle requires needle disposal protocols and refrigeration maintenance. Brazil's school-based programs and India's state immunization schedules depend on this route, though cold-chain gaps in northern Brazil and rural India constrain effective reach.
- Subcutaneous:Reduced needle-length requirements and simplified disposal logistics are gaining procurement interest in resource-limited settings. Thailand's national health security office is piloting subcutaneous alternatives where intramuscular cold-chain constraints limit adolescent coverage.
- Oral:Thermostable formulations eliminating injection requirements remain developmental.
- Nasal:Mucosal delivery platforms targeting immune response at infection site are preclinical.
Procurement volumes concentrate in Intramuscular. Subcutaneous is climbing the fastest as tender specifications evolve.
End User:
Channel structure determines pricing transparency and manufacturer relationship depth in procurement workflows.
- Hospitals:Tertiary care institutions with integrated cold-chain infrastructure handle complex adolescent dosing schedules and adverse event monitoring. India's government medical colleges anchor state-level immunization program delivery.
- Clinics:Outpatient facilities with vaccination capacity serve private-pay catch-up cohorts and travel medicine demand.
- Pharmacies:Retail channels with refrigeration capability are expanding in South Korea's young adult segments as upper age limits extend.
- Preventive Health Centers:Brazil's municipal health posts and India's primary health centers aggregate routine adolescent demand through school-linked outreach.
Demand aggregates most heavily through Preventive Health Centers. Pharmacies are gaining share fastest as age-eligibility broadens.
Age Group:
Immunization schedule positioning determines dose volume predictability and procurement contract duration.
- Adolescents:Routine two-dose schedules for 9-14 year-olds anchor national program procurement with multiyear demand visibility. Brazil's national adolescent health program and India's universal immunization program specify this cohort.
- Young Adults:Three-dose catch-up schedules for 15-26 year-olds are expanding fastest as South Korea and Thailand extend upper age limits in national schedules.
- Adults:27-45 year eligibility remains limited to private channels and select travel medicine indications.
- Seniors:No established immunization rationale limits commercial relevance.
Procurement contracts concentrate in Adolescents. Young Adults show steepest expansion trajectory as schedule revisions propagate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Serum Institute of India anchors emerging-market supply chains through WHO-prequalified bivalent production at price points below multinational benchmarks. Brazil's school-based immunization mandates and India's PLI-driven manufacturing scale-up are redrawing procurement geography.
United States
FDA-validated facilities with captive yeast-based antigen production dominate nonavalent supply to national immunization programs. The FDA's batch release requirements shape manufacturing compliance costs for new market entrants. Boston-area biotech clusters concentrate VLP platform expertise and adjuvant formulation R&D.
India
CDSCO's accelerated approval pathway enables faster market entry for indigenous manufacturers targeting government procurement. The PLI scheme incentivizes localized bivalent and quadrivalent capacity, reducing import dependency patterns. Pune and Hyderabad host expanding WHO-prequalified production facilities serving domestic tenders.
Brazil
ANVISA-regulated school-based immunization mandates widen the adolescent patient pool through municipal health post networks. The national adolescent health program creates predictable demand visibility for multiyear supply contracts. São Paulo's state-level immunization schedules anchor routine vaccination cohort procurement.
China
NMPA oversight shapes domestic vaccine registration timelines for bivalent and quadrivalent candidates. Xiamen and Kunming biotech corridors concentrate indigenous VLP manufacturing capacity targeting public health procurement. Cold-chain infrastructure gaps in western provinces constrain last-mile distribution reach.
Germany
EMA's evolving vaccine interchangeability guidance influences procurement flexibility across European national programs. The framework permits mixed-schedule administration, reducing lock-in effects for single-supplier tenders. Bavaria's pharmaceutical manufacturing belt hosts adjuvant formulation and fill-finish operations.
HPV Vaccines Market Competitive Environment
Global majors compete with regional champions across antigen manufacturing complexity and adjuvant platform differentiation. The supplier base concentrates around three archetypes: integrated multinationals with captive FDA-validated facilities, emerging-market volume specialists leveraging WHO prequalification, and domestic champions serving protected procurement channels. Consolidation pressures favor backward integration into yeast-based VLP production and in-house aluminum adjuvant supply.
Among integrated multinationals, Merck & Co., Inc. and GlaxoSmithKline plc exemplify the premium-tier positioning built on proprietary adjuvant platforms and stringent-authority validated manufacturing. Serum Institute of India occupies a distinct volume-driven archetype, anchoring emerging-market supply through WHO-prequalified production at price-competitive benchmarks. Xiamen Innovax Biotech Co., Ltd. represents the domestic champion model, leveraging NMPA pathways to serve protected procurement channels.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Serum Institute of India |
| Bharat Biotech |
| Xiamen Innovax Biotech Co., Ltd. |
| Walvax Biotechnology Co., Ltd. |
| Wantai BioPharm |
| Sanofi |
| INOVIO Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Nonavalent-bivalent cost divergence splits procurement economics between premium serotype coverage and budget-constrained public health programs, with aluminum adjuvant sourcing and WHO prequalification status determining which manufacturers can access government tenders versus private channels. This bifurcation concentrates pricing power with integrated producers holding captive yeast-based VLP infrastructure while squeezing margins for import-dependent suppliers.
Pricing Analysis
Aluminum hydroxide and AS04 adjuvant cost pass-through dominates per-dose economics, with Merck's captive supply insulating nonavalent pricing from raw material volatility while GlaxoSmithKline's proprietary platform sustains bivalent premiums in European tenders. Price differentiation hinges on serotype coverage breadth and WHO prequalification status, with prequalified bivalent supply from Serum Institute of India commanding 40-60% discounts below multinational benchmarks. Cost compression intensifies in quadrivalent segments as India's PLI scheme expands domestic capacity. Government tender authorities in Brazil and India exhibit highest price sensitivity, while private clinics in South Korea and Thailand absorb moderate premiums for expanded age-eligibility formulations.
Supply Chain Analysis
India's PLI scheme and Brazil's local-content preferences for ANVISA-registered products are reshaping sourcing patterns away from legacy import dependency. Manufacturing gravity centers on the United States for FDA-validated nonavalent supply, India for WHO-prequalified bivalent volume, and China for NMPA-regulated domestic procurement. Yeast-derived L1 VLP production, aluminum-containing adjuvant formulation, and cold-chain distribution infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in Merck's captive adjuvant infrastructure for nonavalent formulations. Distribution runs through government immunization programs and multiyear framework agreements, with direct manufacturer relationships displacing fragmented distributor networks in high-volume markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where nonavalent procurement specifications are hardening serotype coverage requirements and consolidating demand around manufacturers with integrated antigen-adjuvant capabilities.
For Market Incumbents: Cement backward integration into yeast-based VLP production and captive aluminum adjuvant supply to defend against Serum Institute of India's price-competitive WHO-prequalified volume. Lock in multiyear framework agreements with Brazil's national adolescent health program and India's state immunization schedules before domestic capacity fully matures. Prioritize EMA interchangeability certification to capture procurement flexibility in European tenders as contract durations shorten. For New Entrants and Emerging Players: The price-point gap between premium nonavalent and economy bivalent procurement creates white-space opportunity for quadrivalent specialists targeting cost-constrained tenders in Southeast Asia and Sub-Saharan Africa. Prioritize WHO prequalification pathway acceleration over stringent-authority validation to access government immunization programs. Pilot subcutaneous delivery formulations in Thailand and northern Brazil where intramuscular cold-chain gaps constrain coverage. For Investors and Strategic Acquirers: Consolidation pressure builds where antigen manufacturing skill scarcity and FDA batch release timeline compression favor acquirers with existing validated infrastructure over greenfield entrants. Long-term viability favors integrated manufacturers with dual WHO prequalification and stringent-authority capabilities. Monitor EMA interchangeability guidance implementation as the signal for procurement flexibility inflection in European national programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | India's PLI scheme accelerates domestic bivalent capacity, reducing import dependency for government tenders. |
| Regulatory Approval Pathway | WHO prequalification unlocks access to Gavi-eligible markets and national immunization program procurement. |
| Backward Integration | In-house yeast-based VLP production and captive adjuvant supply defend margin position against price-competitive entrants. |
| Product Formulation Extension | Subcutaneous delivery alternatives penetrate cold-chain-constrained settings in rural India and northern Brazil. |
| Long-term Supply Agreement | Multiyear framework contracts with Brazil's municipal health posts provide demand visibility for capacity planning. |
Study Parameters
Bottom-up immunization program modeling reconciled against top-down manufacturer supply tracking forms the analytical core of this study. Primary interviews with vaccine development executives, national immunization program managers, regulatory affairs leads at CDSCO and ANVISA, and hospital procurement directors in India and Brazil were cross-validated against secondary sources including WHO prequalification listings, FDA batch release records, EMA interchangeability guidance documents, and government tender databases from Brazil's Ministry of Health and India's Universal Immunization Program.
Input-output matrices mapping antigen manufacturing capacity, adjuvant supply constraints, and procurement demand across product type, delivery mode, end user, and age group segmentation dimensions generated volume and value trajectories across the projection horizon. CAGRs were derived from regression analysis of historical immunization coverage rates, tender award patterns, and manufacturing capacity expansion announcements, with serotype coverage breadth and regulatory pathway timelines as key forecast inputs.
Caveats apply where EMA interchangeability guidance revisions, WHO prequalification pathway delays, or aluminum adjuvant supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding school-based program expansion rates and domestic manufacturing scale-up timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
North America Hormone Replacement Therapy Market