
 Oral Solid Dosage Contract Manufacturing Market | 2026-2036
Oral Solid Dosage Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Solid Dosage Contract Manufacturing Market Intelligence
Indian pharmaceutical clusters is shifting capacity toward high-volume oral solid dosage contract manufacturing for regulated markets. Catalent, Inc. leverages integrated development-to-commercialization platforms across multiple continents. Lonza Group AG anchors its position through specialized high-potency compound handling capabilities. Jubilant Pharmova Limited competes on cost-optimized large-batch tablet production from its Indian manufacturing network.
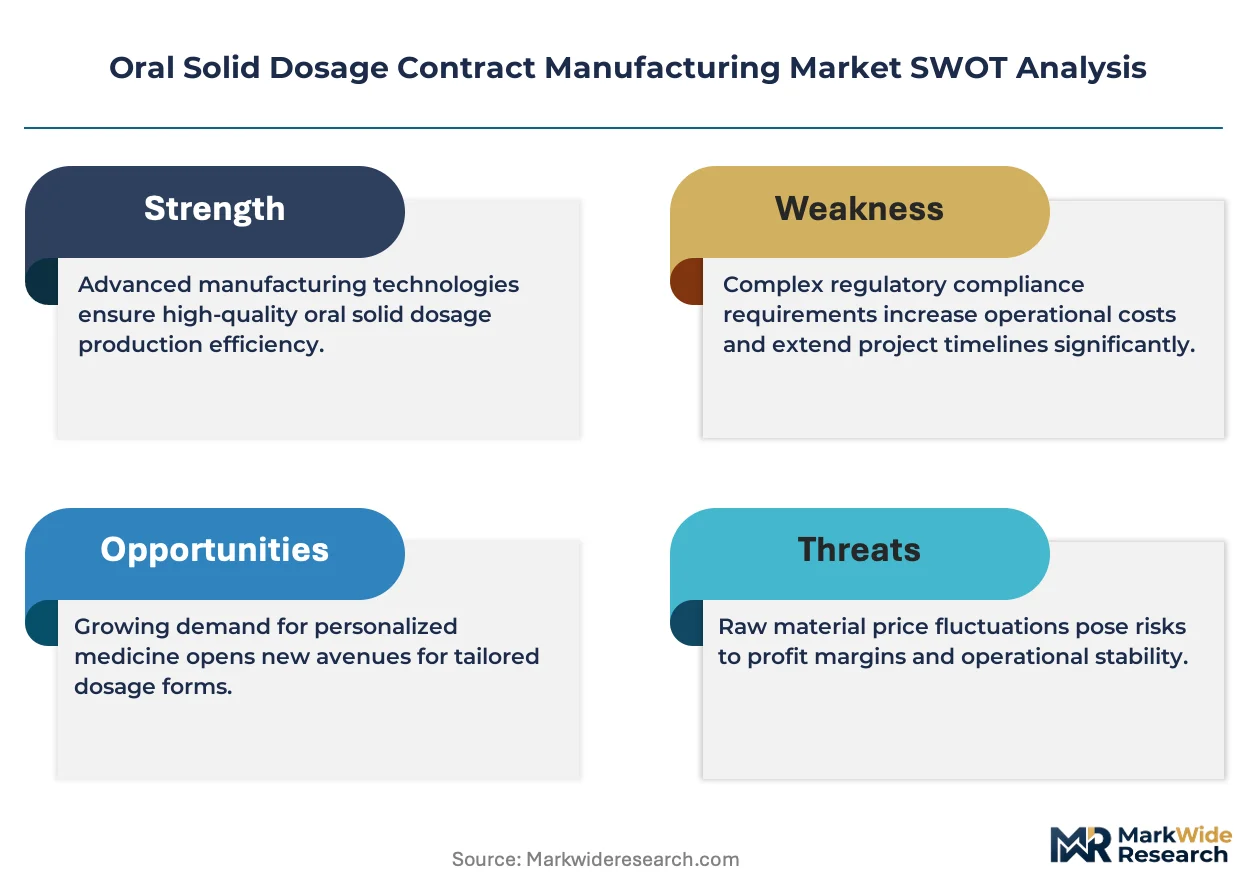
Oral solid dosage contract manufacturing encompasses the outsourced production of tablets, capsules, powders, and granules through processes including direct compression, wet granulation, and fluid bed drying, typically achieving batch uniformity within strict weight-variation and dissolution specifications to ensure therapeutic bioequivalence. The primary commercial purpose is enabling pharmaceutical and biotech firms to access validated manufacturing capacity without capital-intensive facility construction. Tablets dominate current volume flows due to established tooling infrastructure and patient acceptance, while controlled-release formulations capture disproportionate margin pools as formulation complexity creates technical barriers to entry. Immediate-release tablets remain the most mature segment with intense price competition among generic manufacturers.
FDA inspections, EMA GMP guidelines, and ICH Q12 lifecycle management standards collectively determine market access for contract manufacturers serving regulated jurisdictions. These frameworks elevate quality-system investments and documentation burdens, effectively filtering smaller competitors from commercial supply chains to major pharmaceutical buyers. Stakeholders must monitor evolving serialization requirements and continuous manufacturing guidance as regulatory preferences reshape facility qualification criteria and client sourcing decisions.
Market Dynamics
Contract manufacturers face intensifying pressure from FDA's Quality Management Maturity program, which rewards top-tier compliance with reduced inspection frequency while marginalizing facilities below threshold standards. This regulatory stratification is compressing viable supplier pools for multinational pharmaceutical procurement teams.
Growth Catalysts
- EMA GMP Annex 1 alignment:European regulatory harmonization with sterile manufacturing standards creates upgrade demand for oral solid facilities handling potent compounds. Contract manufacturers investing in barrier isolation technology capture volume from reformulation pipelines.
- Generic manufacturer outsourcing:Cost-pressured generic firms in the United States and Germany are shedding in-house tableting capacity. Third-party providers absorb this transferred volume through dedicated production lines with guaranteed minimum commitments.
- Continuous manufacturing adoption:Real-time release testing and powder flow monitoring technologies reduce batch failure rates. Early adopters achieve faster FDA approval timelines for abbreviated new drug applications.
Market Restraints
- API supply concentration:China and India control critical starting material flows for high-volume oral solids. Geopolitical friction or export restrictions cascade immediately into contract manufacturing scheduling disruptions.
- Specialized equipment lead times:Fluid bed dryers and high-shear granulators from German and Italian suppliers extend to 18-24 month delivery windows. Capacity expansion plans face mechanical commissioning bottlenecks.
- Skilled formulation scientist scarcity:Wet granulation and modified-release expertise concentrates among aging workforces in Switzerland and the United States. Knowledge transfer gaps constrain complex project onboarding.
Strategic Opportunities
- Brazilian regulatory convergence:ANVISA's accelerated pathway for bioequivalence-approved generics opens dedicated capacity opportunities. Local contract manufacturing partnerships circumvent import tariff structures for South American distribution.
- Continuous direct compression integration:Twin-screw granulation is converging with real-time spectroscopic monitoring. Combined platforms enable smaller-footprint facilities in high-cost labor markets.
- Japan's elderly formulation demand:PMDA guidance on orodispersible tablets drives specialized line investments. Contract manufacturers with rapid-disintegration capabilities access premium pricing for geriatric-focused portfolios.
Industry Challenges
- Serialization system interoperability:EU Falsified Medicines Directive track-and-trace requirements demand integration with legacy enterprise resource planning platforms. Validation timelines extend commercial launch windows.
- High-potency containment capex:Isolator technology and dedicated HVAC infrastructure for cytotoxic oral solids require capital deployment exceeding standard multi-purpose suites. Return-on-investment horizons stretch beyond typical contract durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Solid Dosage Contract Manufacturing Market |
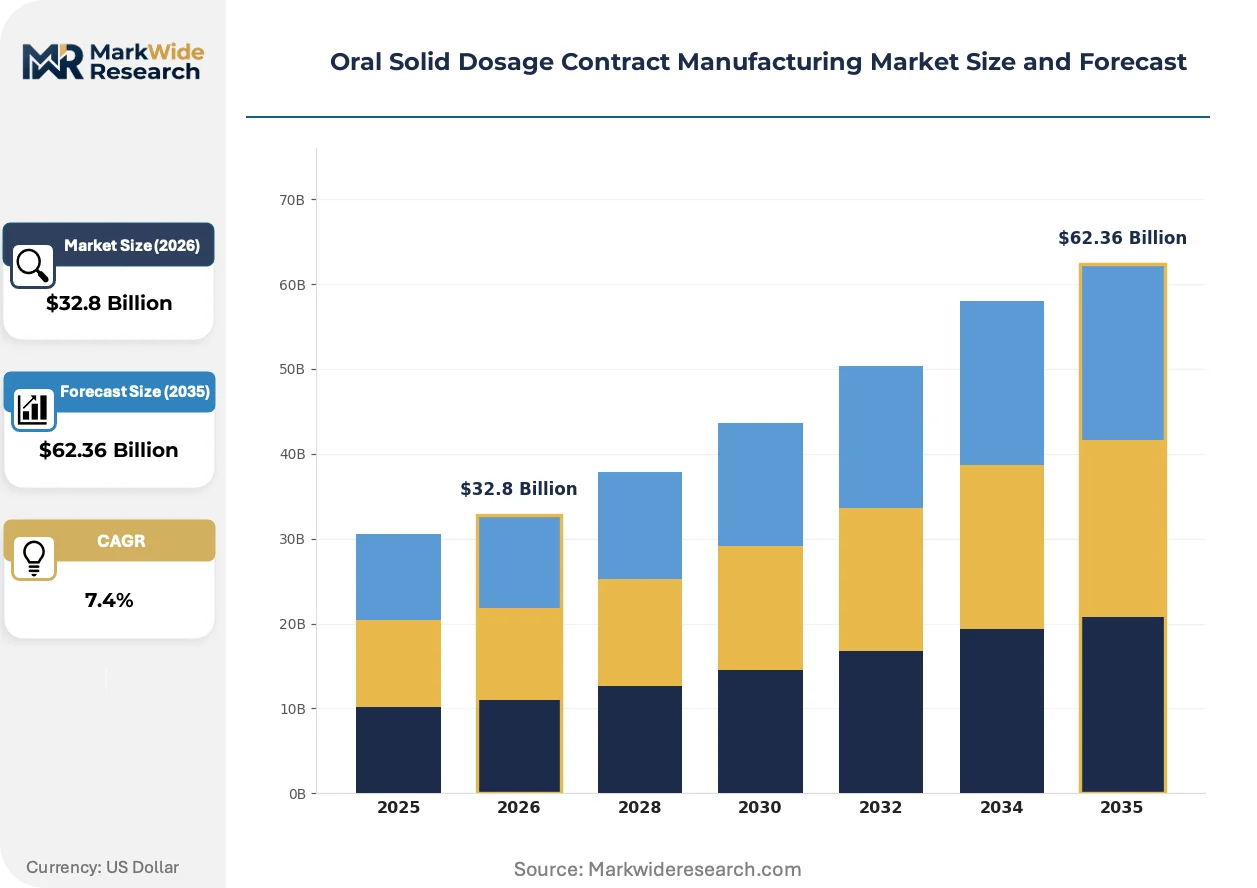
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $62.36 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Granules Delivery Mode: Sustained Release, Immediate Release, Controlled Release, Enteric Coated End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Generic Manufacturers Packaging Type: Bottles, Blister Packs, Pouches, Cartons |
| Companies Covered | Catalent, Inc., Lonza Group AG, Aenova Group, Boehringer Ingelheim International GmbH, Recipharm AB, Jubilant Pharmova Limited, Corden Pharma International, Piramal Pharma Solutions, Siegfried Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Solid Dosage Contract Manufacturing Market Strategic Shifts & Innovations
Process analytical technology is migrating from pilot-scale demonstration to qualified commercial deployment. Regulatory acceptance of real-time release testing is reshaping quality assurance staffing models and batch documentation burdens.
Artificial intelligence-driven formulation optimization is converging with robotic powder handling systems. Generic manufacturers in India deploy machine learning platforms to predict blend uniformity from raw material variability data. This convergence compresses development timelines from 18 months to under 12 months for immediate-release tablet portfolios.
FDA's draft guidance on continuous manufacturing quality considerations is forcing facility redesign investments. Sponsors with approved continuous processes gain priority review incentives for subsequent submissions. European contract manufacturers are responding with modular skid-mounted production trains that accelerate regulatory qualification.
Buyer consolidation among top-ten pharmaceutical firms is concentrating procurement leverage. Tier-one contract manufacturers face unbundling pressure as sponsors separate development, clinical supply, and commercial manufacturing awards. This fragmentation is most visible in United States sourcing decisions, where risk-mitigation strategies favor geographic redundancy over single-source efficiency.
Oral Solid Dosage Contract Manufacturing Market Segmentation
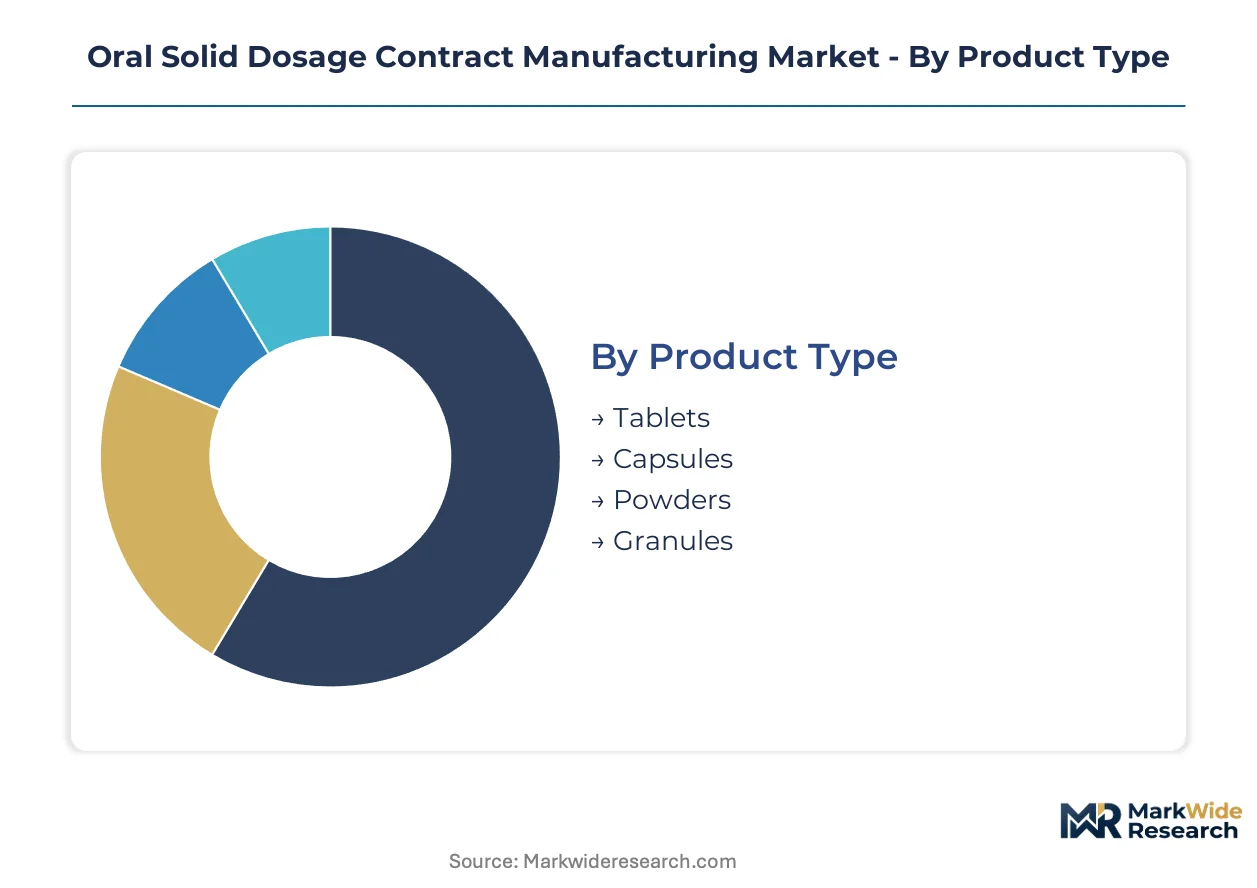
Segmentation in oral solid dosage contract manufacturing reveals how technical specifications, release kinetics, and packaging formats determine facility qualification requirements and client matching algorithms. Understanding these divisions exposes where capital deployment concentrates and where margin compression threatens.
Product Type:
Tablets and capsules operate as standalone dosage forms with dedicated production lines, while powders and granules often embed as intermediates requiring further processing before patient administration.
- Tablets:Compressed solid units formed through direct compression or granulation routes, achieving hardness and friability specifications through calibrated tooling and force settings. Demand concentrates among generic manufacturers in India and Germany seeking high-volume, cost-optimized production for regulated markets, driven by established patient acceptance and mature quality control protocols.
- Capsules:Gelatin or HPMC shells enclosing powder, granule, or pellet fills, enabling combination therapies and taste masking. Biotech firms in the United States source hard-shell capsules for early-phase compounds, constrained by shell supply lead times and cross-linking stability requirements during accelerated stability studies.
- Powders:Uncompressed active and excipient blends for reconstitution or sachet dosing, typically requiring specialized containment for potent compounds.
- Granules:Intermediate agglomerated forms produced via fluid bed or high-shear processes, feeding tablet compression or capsule filling operations.
Volume placements concentrate in Tablets; the faster expansion belongs to Capsules.
Delivery Mode:
Release profile engineering separates commoditized immediate-release formats from specialized barrier and matrix technologies commanding technical premiums and extended development timelines.
- Immediate Release:Conventional dissolution profiles achieving rapid drug availability, manufactured through standard compression or encapsulation without functional coatings. Generic manufacturers in India deploy immediate-release platforms for high-volume, abbreviated new drug applications, facing intense price competition and batch size minimums that favor dedicated line arrangements.
- Controlled Release:Matrix or reservoir systems modulating plasma concentration through polymer erosion or osmotic pressure mechanisms. Contract manufacturers with validated hydroxypropyl methylcellulose or ethylcellulose coating capabilities capture reformulation projects from originator firms seeking lifecycle extensions, constrained by bioequivalence study costs and regional regulatory divergence.
- Sustained Release:Extended-duration formulations reducing dosing frequency through rate-controlling membranes or swellable matrices.
- Enteric Coated:pH-dependent protection systems releasing active ingredient in intestinal rather than gastric environments, requiring validated coating pan or fluid bed processes.
Immediate Release commands current volume; Controlled Release is climbing the fastest as complexity barriers filter competition.
End User:
Client type determines project scale, quality system intensity, and whether manufacturing embeds within integrated development programs or operates as standalone commercial supply.
- Pharmaceutical Companies:Large originator and established generic firms outsourcing capacity for marketed products or pipeline compounds. Multinational pharmaceutical buyers in Switzerland and the United States source commercial tablet batches through multi-year agreements, driven by capital avoidance strategies and FDA Quality Management Maturity program compliance tiering.
- Generic Manufacturers:Cost-pressured firms shedding in-house tableting capacity to focus on API sourcing and regulatory filing. Indian generic specialists transfer volume to Ahmedabad and Hyderabad contract facilities, constrained by guaranteed minimum commitments and geographic redundancy requirements from North American procurement teams.
- Biotech Firms:Development-stage companies requiring clinical-scale supply and technology transfer support for first commercial batches.
- Contract Research Organizations:Service providers managing integrated development-to-manufacturing programs for sponsor clients.
Generic Manufacturers anchor current placements; Biotech Firms are gaining share fastest as pipeline outsourcing deepens.
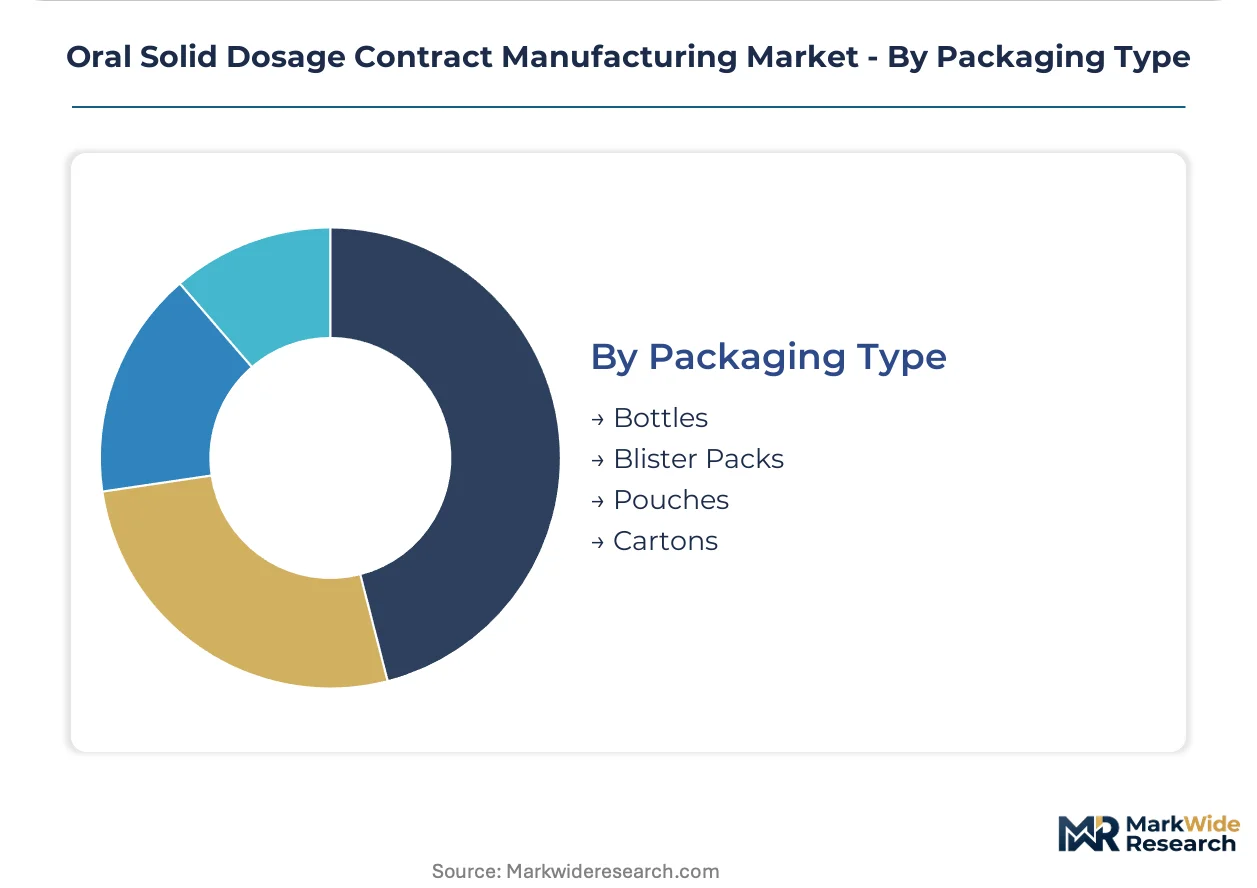
Packaging Type:
Primary and secondary packaging configurations align with distribution channel requirements, patient compliance features, and serialization system capabilities.
- Blister Packs:Thermoformed or cold-form cavities with lidding foil, enabling unit-dose compliance and child-resistant features. European pharmaceutical procurement favors blister configurations for retail pharmacy distribution, driven by EU Falsified Medicines Directive serialization mandates and patient adherence monitoring programs.
- Bottles:High-density polyethylene or glass containers with desiccant systems for moisture-sensitive tablets. United States generic manufacturers specify bottle packaging for institutional and mail-order channels, constrained by line changeover efficiencies and count verification automation investments.
- Pouches:Flexible film sachets for powder or granule dosing, common in emerging market affordability segments.
- Cartons:Secondary packaging aggregating primary containers for logistics and information display.
Bottles dominate North American volume; Blister Packs show the steepest expansion trajectory as European serialization requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API precursor supply from Zhejiang and Shandong provinces feeds contract manufacturing demand across three continents. Regulatory divergence between FDA, EMA, and PMDA standards shapes facility qualification investments. Geographic redundancy requirements from multinational procurement teams redistribute volume toward secondary production clusters.
United States
Generic manufacturer outsourcing and biotech clinical supply needs drive contract manufacturing demand. FDA's Quality Management Maturity program stratifies supplier tiers through inspection frequency incentives. New Jersey and North Carolina host dense concentrations of FDA-inspected facilities serving domestic and export markets.
Germany
Established pharmaceutical firms shed in-house tableting capacity to focus on specialty API development. EMA GMP Annex 1 alignment requirements elevate barrier isolation investments for potent compound handling. Baden-Württemberg and North Rhine-Westphalia maintain specialized high-shear granulation and fluid bed coating capabilities.
India
Cost-optimized large-batch production and abbreviated new drug application filing volumes attract North American procurement. CDSCO's harmonization with ICH Q12 lifecycle management standards accelerates facility qualification timelines. Ahmedabad and Hyderabad clusters concentrate FDA-inspected capacity serving regulated export markets.
Switzerland
High-potency compound containment and specialized modified-release formulation expertise command technical premiums. Swissmedic's alignment with EMA inspection standards enables seamless European supply integration. Basel and Zurich regions anchor precision granulation and isolator technology deployment.
Japan
Geriatric-focused orodispersible tablet demand and rapid-disintegration formulation requirements create specialized line opportunities. PMDA guidance on elderly-appropriate dosage forms drives investment in orally disintegrating tablet platforms. Kansai and Kanto regions concentrate PMDA-inspected facilities with advanced coating capabilities.
Oral Solid Dosage Contract Manufacturing Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized containment and continuous manufacturing niches. The vendor base stratifies across three maturity levels: integrated development-to-commercialization platforms, dedicated commercial manufacturing specialists, and regional cost-optimized batch producers. Strategic differentiation concentrates in high-potency handling certifications, real-time release testing capabilities, and geographic redundancy coverage. Dominant competitive moves include modular capacity expansion and technology licensing partnerships for continuous direct compression platforms.
Among Swiss-based specialists, Lonza Group AG and Siegfried Holding AG exemplify high-potency compound containment archetypes. Catalent, Inc. represents the integrated platform model spanning development through commercial supply. Jubilant Pharmova Limited anchors the cost-optimized large-batch segment from its Indian manufacturing network. These three entities illustrate the competitive spectrum: specialized containment expertise, end-to-end service integration, and volume-driven efficiency positioning.
| Leading Market Players |
|---|
| Catalent, Inc. |
| Lonza Group AG |
| Aenova Group |
| Boehringer Ingelheim International GmbH |
| Recipharm AB |
| Jubilant Pharmova Limited |
| Corden Pharma International |
| Piramal Pharma Solutions |
| Siegfried Holding AG |
| Others |
Cost & Logistics Intelligence
Guaranteed minimum commitments from North American generic procurement teams are compressing contract manufacturing margins and forcing capacity allocation toward dedicated line arrangements with volume floors. This buyer consolidation dynamic elevates pricing power for FDA-inspected facilities in Ahmedabad and Hyderabad while marginalizing smaller batch producers without redundancy coverage.
Pricing Analysis
Service bundling separates development-phase formulation support from standalone commercial manufacturing awards. Three-tier pricing structure across premium, standard, and economy levels tracks FDA Quality Management Maturity program compliance tiers and isolator technology deployment. Cost compression in immediate-release tablet production is intensifying because Indian generic manufacturers compete on abbreviated new drug application filing volumes. Generic manufacturers exhibit highest price sensitivity; originator firms seeking high-potency containment accept technical premiums.
Supply Chain Analysis
EMA GMP Annex 1 certification and FDA establishment status function as non-negotiable gating criteria for commercial supply qualification. Active pharmaceutical ingredient precursors draw from Zhejiang and Shandong provinces in China, with intermediate processing concentrated in Gujarat and Telangana states of India. Single-source vulnerability pervades fluid bed dryer and high-shear granulator procurement from German and Italian equipment suppliers. Distribution runs through validated cold-chain logistics for temperature-sensitive coated tablets to European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing quality considerations from FDA are displacing batch processing infrastructure, creating asymmetric returns for early adopters of real-time release testing platforms.
For Market Incumbents: Extend high-potency containment capabilities through isolator technology investments in Swiss and North Carolina facilities to defend against emerging entrants with modular continuous direct compression platforms. Backward integration into specialized excipient sourcing secures supply continuity for hydroxypropyl methylcellulose coating operations. For New Entrants and Emerging Players: Direct-to-biotech digital sourcing platforms offer lower customer acquisition costs than traditional pharmaceutical procurement relationship models. Target orodispersible tablet formulation capabilities for Japan's geriatric market through PMDA-aligned quality system investments, leveraging rapid-disintegration technology licensing partnerships. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with validated continuous manufacturing submissions and FDA Quality Management Maturity program top-tier ratings. Acquisition candidates with real-time spectroscopic monitoring deployment and modular skid-mounted production trains align with regulatory preference trajectories. Watch FDA draft guidance finalization on continuous manufacturing as inflection signal for facility valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Licensing | Enables faster FDA approval timelines for abbreviated new drug applications from sponsor partners. |
| High-Potency Containment Capacity Expansion | Captures reformulation projects from originator firms seeking lifecycle extensions for cytotoxic compounds. |
| Backward Integration into Excipient Supply | Secures hydroxypropyl methylcellulose and ethylcellulose flows for modified-release coating operations. |
| PMDA-Aligned Orodispersible Line Investment | Accesses premium pricing for Japan's geriatric-focused rapid-disintegration tablet portfolios. |
| Geographic Redundancy Partnership Structure | Satisfies multinational pharmaceutical procurement risk-mitigation requirements across Ahmedabad and Hyderabad clusters. |
Research Approach
Document review covered FDA establishment inspection reports, EMA GMP non-compliance records, and CDSCO manufacturing facility registrations, complemented by interviews with contract manufacturing executives, regulatory affairs leads at sponsor firms, pharmaceutical procurement managers, and formulation science directors. Secondary validation drew from ClinicalTrials.gov manufacturing site disclosures, FDA warning letter databases, and ICH Q12 implementation guidance documents. Bottom-up capacity modeling triangulated against top-down pharmaceutical outsourcing expenditure estimates.
Historical capacity utilization trends cross-referenced against expert panel input on continuous manufacturing adoption timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, release kinetics, end-user category, and regional regulatory cluster. CAGRs derived from weighted average of facility expansion announcements and sponsor outsourcing commitment disclosures, with specific inputs including fluid bed equipment order backlogs and abbreviated new drug application filing volumes.
The model holds under stable FDA inspection frequency policies and uninterrupted API precursor trade flows; deviation in export restriction implementation or EMA GMP Annex 1 enforcement intensity would shift capacity allocation assumptions. Forecasts reflect documented facility qualification timelines and sponsor technology transfer completion rates. A model refresh is warranted upon material change in FDA continuous manufacturing guidance finalization or CDSCO-ICH harmonization pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Indobufen API Market