
 Czech Republic Pharmaceutical Market | 2026-2036
Czech Republic Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Pharmaceutical Market Insights
Subscription-based medication adherence programs is shifting how pharmaceutical value gets captured in the Czech Republic. Novartis leverages its oncology portfolio to anchor hospital formulary relationships across major university hospitals. Zentiva specializes in generic manufacturing and sustains cost-competitive supply through its Prague-based production network.
The Czech Republic pharmaceutical sector encompasses chemically synthesized and biologically derived medicinal products formulated for therapeutic intervention, with active pharmaceutical ingredients typically manufactured through fermentation, chemical synthesis, or recombinant DNA processes before tableting, filling, or lyophilization into finished dosage forms. Prescription drugs occupy the dominant revenue position due to reimbursement anchoring through the Czech public health insurance system, while biologics represent the fastest-expanding margin pool as hospital-based oncology and immunology protocols deepen. Generics compete primarily on tender pricing within the State Institute for Drug Control procurement framework, compressing returns for mature oral solid portfolios.
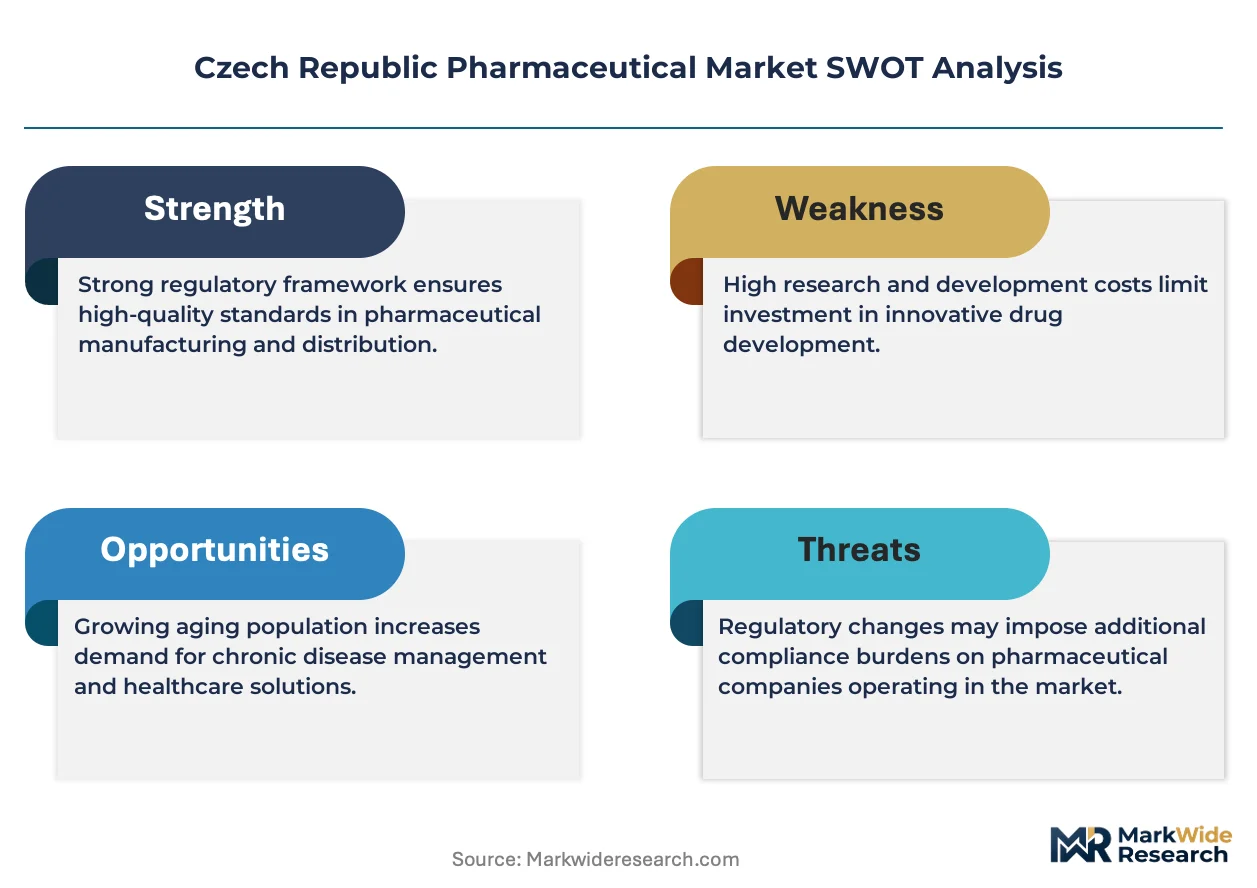
The State Institute for Drug Control enforces marketing authorization and Good Manufacturing Practice compliance, shaping product standards for both domestic production and imported medicines entering the Czech supply chain. EMA centralized procedures and national Czech legislation jointly determine reimbursement eligibility, constraining market access timelines for novel therapies. Stakeholders must monitor evolving pharmacovigilance obligations and health technology assessment criteria as these frameworks increasingly determine which therapy areas secure sustainable formulary placement.
Market Dynamics
The State Institute for Drug Control's pharmacovigilance tightening is restructuring how oncology biologics secure hospital formulary placement, compressing timelines for safety documentation while expanding procurement volume thresholds for high-cost therapies.
Growth Catalysts
- EMA centralized procedures:Streamlined marketing authorization pathways accelerate novel therapy access across Czech university hospitals, reducing redundant national filings.
- Prague clinical research corridor:Contract manufacturing organizations serving Central European clients expand production capacity for biologics and specialized dosage forms.
- Public health insurance reimbursement anchoring:Prescription drug coverage through Czech statutory insurers stabilizes demand for chronic disease therapies.
Market Restraints
- Active pharmaceutical ingredient import dependence:Supply concentration in Asian fermentation and chemical synthesis facilities exposes Czech formulators to input cost volatility and logistics disruption.
- Health technology assessment timelines:Czech reimbursement eligibility reviews create extended market access delays for innovative therapies compared to Western European benchmarks.
- Generics tender pricing compression:State Institute for Drug Control procurement frameworks drive mature oral solid margins toward cost-plus structures.
Strategic Opportunities
- Brno-Moravian biotech cluster:Underdeveloped regional production capacity offers greenfield sites for advanced therapy medicinal product manufacturing.
- Subscription-based adherence programs:Digital therapeutics integration with pharmacy benefit management creates recurring revenue models beyond unit sales.
- EU Green Deal pharmaceutical manufacturing standards:Sustainability compliance requirements favor early movers in solvent recovery and waste reduction technologies.
Industry Challenges
- Qualified pharmacovigilance personnel scarcity:Czech regulatory affairs specialists with EMA procedure experience command premium compensation, constraining mid-tier sponsor expansion.
- Legacy serialization system integration:EU Falsified Medicines Directive compliance requires capital expenditure for track-and-trace infrastructure at domestic packaging facilities.
- Biologics cold chain certification complexity:Good Distribution Practice validation for temperature-sensitive oncology therapies extends distribution partner onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Pharmaceutical Market |
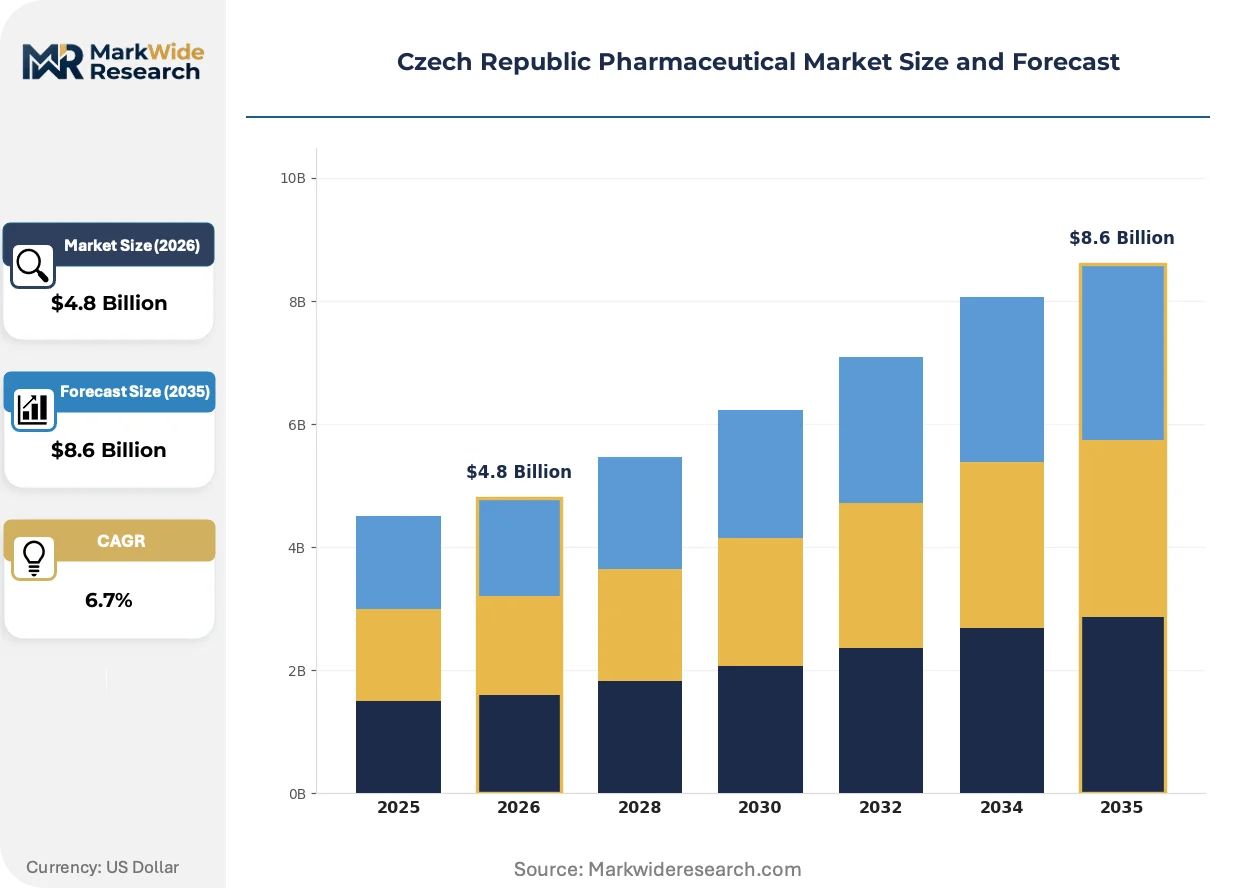
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medication, Biologics, Generics Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Hospitals, Retail Pharmacies, Clinics, Home Care |
| Companies Covered | Novartis, Sanofi, Roche, Omega Pharma, MSD Czech Republic, Zentiva, AstraZeneca, Pfizer, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Pharmaceutical Market Trends and Innovations
Continuous manufacturing technologies and real-world evidence integration are displacing batch processing and randomized trial exclusivity as the basis for competitive positioning in Czech pharmaceutical supply.
Continuous direct compression is converging with process analytical technology to enable real-time quality assurance during oral solid production. Zentiva and domestic generic manufacturers are retrofitting Prague-area facilities to reduce batch failure rates and API waste. This convergence is compressing cost structures for high-volume generics while raising technical barriers for new facility entrants.
The EU Medical Device Regulation and In Vitro Diagnostic Regulation are extending conformity assessment requirements to drug-device combination products. Czech notified body capacity constraints are delaying market access for auto-injector and pre-filled syringe presentations. Oncology and diabetes therapy categories are most affected, with sponsors accelerating parallel EMA and national filings to mitigate timeline risk.
Hospital pharmacy consolidation is concentrating purchasing authority within Czech regional healthcare administrative structures. Independent community pharmacies are losing oncology and biologics dispensing volume to hospital outpatient departments. Moravia and peripheral Bohemian regions show the fastest consolidation pace as university hospital networks expand satellite infusion centers.
Czech Republic Pharmaceutical Market Segmentation
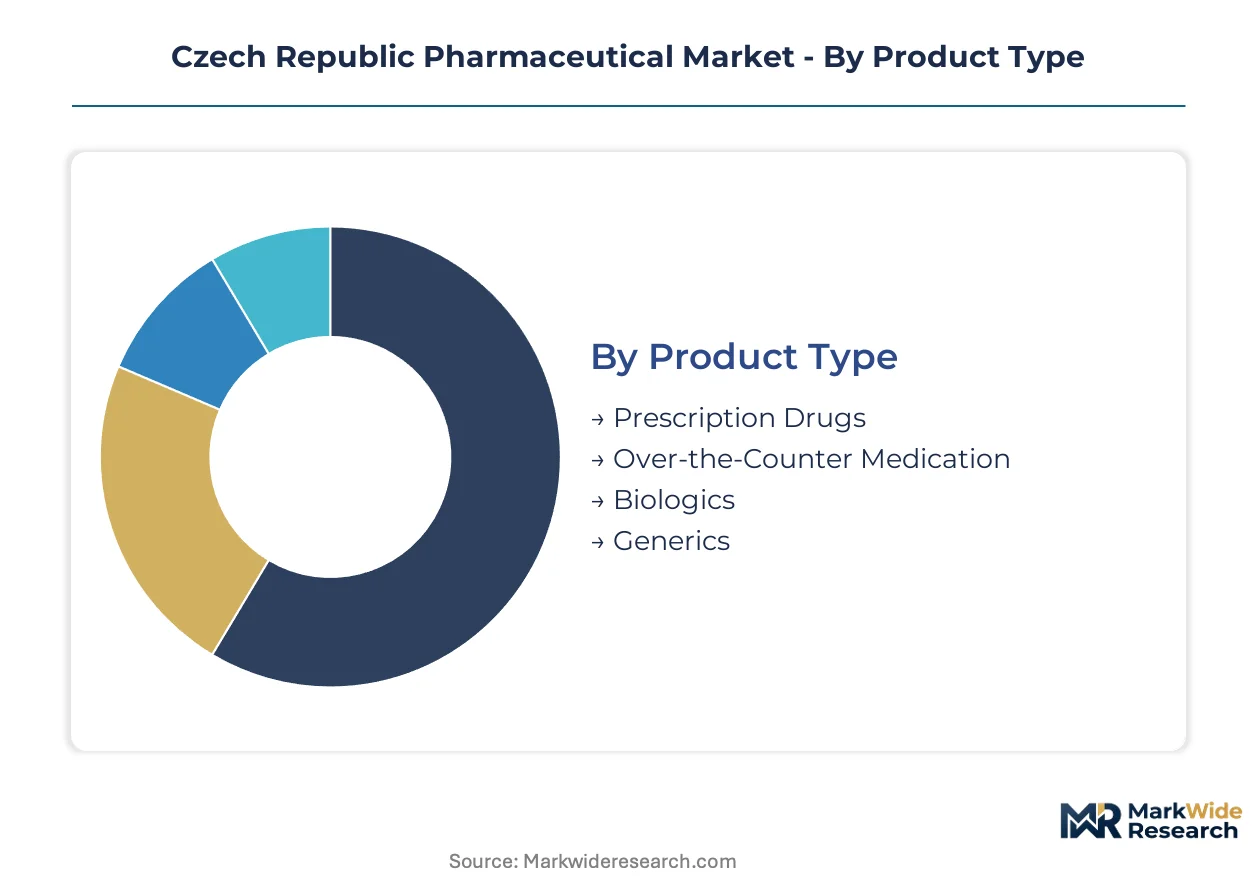
Segmentation in the Czech Republic pharmaceutical market reveals how reimbursement anchoring and procurement centralization concentrate value capture. Hospital formulary placement and State Institute for Drug Control tender frameworks determine which product categories sustain margin versus volume strategies.
Product Type:
Prescription drugs anchor volume through public health insurance coverage, while biologics command premium positioning in hospital oncology protocols.
- Prescription Drugs:Chemically synthesized therapeutic agents requiring medical authorization for dispensing. Chronic disease management in Prague university hospitals and regional healthcare networks drives sustained demand through statutory insurance reimbursement mechanisms.
- Biologics:Recombinant DNA-derived medicinal products manufactured via fermentation or cell culture processes. Oncology and immunology departments at Motol University Hospital and Brno's Masaryk Memorial Cancer Institute are expanding infusion center capacity to accommodate rising patient volumes for monoclonal antibody therapies.
- Over-the-Counter Medication:Self-care formulations available without prescription through retail pharmacy networks.
- Generics:Bioequivalent copies of off-patent molecules competing primarily on State Institute for Drug Control tender pricing.
Mature deployment sits with Prescription Drugs. Newer deployment is concentrated in Biologics.
Therapy Area:
Cardiovascular and oncology segments split between chronic outpatient management and acute hospital-based intervention.
- Oncology:Cytotoxic, targeted, and immuno-oncology agents addressing solid tumors and hematological malignancies. Masaryk Memorial Cancer Institute and Prague's General University Hospital are consolidating regional purchasing authority for high-cost biologics through expanded satellite infusion networks in Moravia and peripheral Bohemia.
- Cardiovascular:Antihypertensive, anticoagulant, and lipid-lowering therapies for chronic disease management. General practitioners and cardiologists in Prague's clinical research corridor prescribe these agents through standard reimbursement pathways with limited formulary variation.
- Neurology:Agents for epilepsy, Parkinson's disease, and multiple sclerosis requiring specialized hospital oversight.
- Infectious Diseases:Antibacterial, antiviral, and antifungal therapies spanning hospital and community settings.
Volume concentration favors Cardiovascular. Margin expansion is climbing the fastest in Oncology.
Delivery Mode:
Oral solid dominance in chronic disease management contrasts with injectable complexity in hospital biologics administration.
- Oral:Tablets, capsules, and liquid formulations for self-administered chronic therapy. Zentiva's Prague-area manufacturing network and domestic generic producers optimize direct compression processes to serve high-volume tender requirements for cardiovascular and metabolic agents.
- Injectable:Parenteral formulations including intravenous infusions and subcutaneous injections. Cold chain Good Distribution Practice certification requirements for oncology biologics extend onboarding timelines for regional distribution partners serving Brno-Moravian hospital networks.
- Topical:Dermatological and transdermal preparations dispensed through retail pharmacy channels.
- Inhalation:Aerosol and dry powder devices for respiratory disease management.
Manufacturing maturity concentrates in Oral. Technical complexity is expanding most quickly in Injectable.
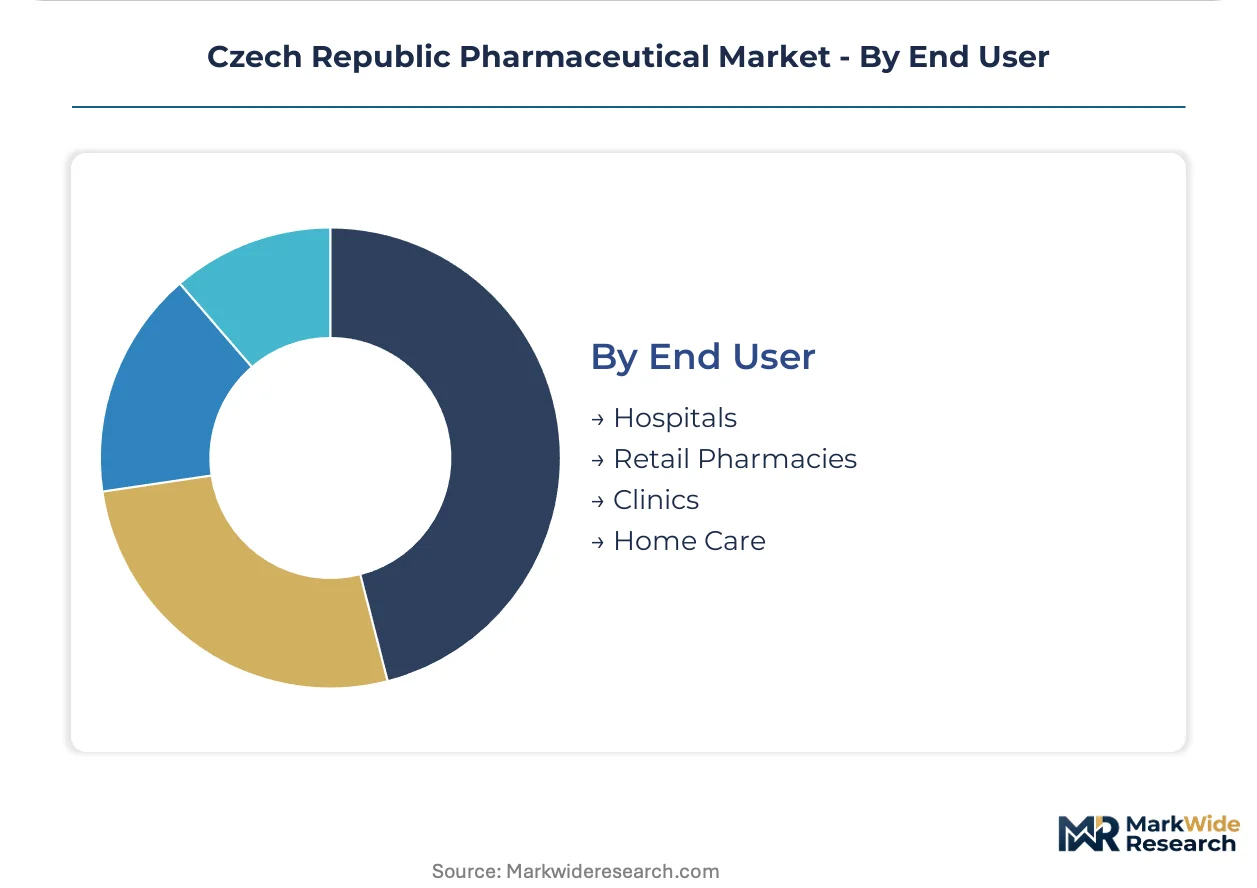
End User:
Hospital consolidation is shifting oncology and biologics dispensing from community pharmacies to outpatient departments.
- Hospitals:Acute care institutions and university medical centers with centralized pharmacy committees. Regional healthcare administrative structures in Moravia and peripheral Bohemian regions are accelerating purchasing authority concentration as university hospital networks expand satellite infusion centers.
- Retail Pharmacies:Independent and chain community dispensaries handling prescription fulfillment and OTC sales. Prague's dense pharmacy network retains chronic disease prescription volume while losing high-margin biologics dispensing to hospital outpatient departments.
- Clinics:Outpatient specialist facilities with limited formulary autonomy.
- Home Care:Self-administration settings supported by nursing services and digital adherence programs.
Established infrastructure dominates Hospitals. Service model innovation is gaining share fastest in Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production clusters in Prague and Brno supply formulation capacity, yet active pharmaceutical ingredient sourcing concentrates beyond Czech borders. Regional demand flows through Central European distribution networks anchored by German logistics hubs and Austrian wholesale infrastructure.
Germany
Oncology biologics demand from Bavarian university hospitals drives cross-border procurement into Czech hospital networks. EMA centralized procedures streamline marketing authorization pathways for therapies entering both markets. Frankfurt's pharmaceutical logistics corridor channels temperature-sensitive shipments through cold chain infrastructure serving Prague and Brno medical centers.
Poland
Generic tender pricing pressure from Polish regional health funds shapes competitive dynamics for Czech State Institute for Drug Control procurement frameworks. The country's national pharmaceutical regulator enforces parallel pharmacovigilance standards that Czech sponsors must mirror for cross-border portfolio consistency. Warsaw-based contract research organizations collaborate with Prague clinical sites on multicenter oncology trials.
Austria
Vienna's biotech cluster attracts Czech research talent while supplying specialized dosage form technologies to Moravian manufacturers. Austrian social insurance reimbursement precedents influence Czech health technology assessment timelines for novel therapies. Linz pharmaceutical logistics hubs serve as distribution gateways for Czech hospital pharmacy consolidation in peripheral Bohemian regions.
Slovakia
Shared Visegrad procurement frameworks create pricing spillover effects for generics tendered through Czech administrative structures. Bratislava's regional healthcare networks purchase through overlapping distribution channels serving South Moravian hospital systems. The country's national pharmaceutical regulator maintains harmonized pharmacovigilance protocols with Czech State Institute for Drug Control requirements.
Hungary
Budapest-based manufacturing of active pharmaceutical ingredients supplies fermentation-derived inputs to Czech formulators. Hungarian oncology biologics consumption patterns inform Czech hospital formulary placement strategies for comparable patient populations. Debrecen's clinical research infrastructure competes with Brno-Moravian sites for Central European trial sponsorship.
Czech Republic Pharmaceutical Market Competitive Landscape
Top-tier multinational vendors anchor hospital formulary relationships, while mid-tier regional specialists compete on tender pricing for mature oral solid portfolios. The vendor base stratifies across three tiers: global innovators commanding oncology biologics premiums, European generics manufacturers optimizing cost structures, and domestic formulators serving local distribution networks. Two competitive moves dominate: backward integration into active pharmaceutical ingredient sourcing to reduce import dependence, and strategic partnerships with Prague clinical research organizations to accelerate trial enrollment.
Among the named participants, Novartis and Zentiva exemplify divergent strategic archetypes within this structure. Novartis occupies a position consistent with global innovators leveraging oncology portfolio breadth to secure reimbursement anchoring across Czech university hospitals. Zentiva represents the regional manufacturing specialist archetype, with Prague-based production networks optimized for high-volume generics tender compliance. Sanofi sits within the diversified multinational tier, spanning both innovative biologics and established primary care portfolios that interface with distinct procurement channels.
| Leading Market Players |
|---|
| Novartis |
| Sanofi |
| Roche |
| Omega Pharma |
| MSD Czech Republic |
| Zentiva |
| AstraZeneca |
| Pfizer |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across oncology biologics, prescription chronic therapies, and tender-driven generics manifests in divergent procurement channels and API sourcing strategies throughout Czech pharmaceutical supply. State Institute for Drug Control reimbursement anchoring for hospital formulary placement concentrates pricing power with multinationals, while tender compression funnels generics through cost-plus manufacturing networks anchored in Prague.
Pricing Analysis
Cost-down pressure on oral solid generics accelerates because State Institute for Drug Control tender frameworks reward lowest-compliant bids with volume allocation. Pricing stratifies across premium biologics, standard prescription drugs, and economy generics, with differentiation driven by EMA centralized procedure certification and hospital formulary tier placement. Procurement managers at university hospitals exhibit lowest price sensitivity for oncology monoclonal antibodies, while regional healthcare administrative structures enforce maximum sensitivity for cardiovascular and metabolic generics.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on fermentation and chemical synthesis capacity concentrated in India, China, and Hungary. Czech formulators draw from imported recombinant DNA-derived inputs, small-molecule chemical intermediates, and specialized excipients for biologics lyophilization. Single-source vulnerability for temperature-sensitive oncology inputs creates exposure to logistics disruption across Central European cold chain infrastructure. Distribution runs through German logistics hubs and Austrian wholesale networks serving Prague and Brno hospital consolidation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital pharmacy consolidation and pharmacovigilance tightening are forcing mid-tier generic manufacturers toward exit or acquisition, rewarding scale players with EMA procedure experience and captive production capacity.
For Market Incumbents: Extend formulary anchoring at Motol University Hospital and Masaryk Memorial Cancer Institute through subscription-based adherence program integration with outpatient infusion networks. Backward integration into fermentation-derived API sourcing mitigates import cost volatility threatening margin structures for Prague-based manufacturers. State Institute for Drug Control pharmacovigilance personnel scarcity creates defensive moat against mid-tier sponsor expansion. For New Entrants and Emerging Players: Direct-to-clinic digital therapeutics partnerships offer lowest competitive intensity entry path, bypassing hospital pharmacy consolidation capturing biologics dispensing volume. Brno-Moravian biotech cluster greenfield sites for advanced therapy medicinal product manufacturing represent underdeveloped regional capacity with proximity to Vienna biotech talent flows. EU Green Deal pharmaceutical manufacturing standards compliance creates differentiation lever for early movers in solvent recovery technology. For Investors and Strategic Acquirers: Re-rating potential sits with domestic formulators possessing EMA centralized procedure track records given accelerating hospital procurement centralization favoring approved-vendor status. Five-to-ten year viability framing favors acquisition targets with Prague-area production infrastructure and existing State Institute for Drug Control manufacturing authorization. Watch signal: Brno-Moravian regional healthcare administrative structure expansion timelines indicating infusion center buildout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Prague clinical research corridor enrollment accelerates EMA centralized procedure timelines for oncology biologics. |
| Manufacturing Scale-Up | Continuous direct compression retrofit at Zentiva facilities reduces API waste for high-volume generic tenders. |
| Regulatory Approval Pathway | State Institute for Drug Control marketing authorization compliance secures hospital formulary placement for novel therapies. |
| Backward Integration | Captive fermentation capacity mitigates Asian API import dependence and logistics disruption exposure. |
| Licensing Agreement | Contract manufacturing organization partnerships with Central European clients expand Prague production network utilization. |
Research Methodology
Independent corroboration across formulary database reviews, EMA centralized procedure filings, and State Institute for Drug Control marketing authorization records underwrites the qualitative findings. Primary interviews with regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from ClinicalTrials.gov entries, Czech public health insurance reimbursement schedules, and SEC 10-K pharmaceutical segment disclosures. Bottom-up prescription volume modeling and top-down market size triangulation anchored segmentation outputs.
Comparable-period anchoring to historical reimbursement anchoring patterns and tender pricing trajectories structured the projection framework. Segmentation dimensions spanned product type, therapy area, delivery mode, and end-user channel across the modeling period. CAGRs derived from patient population epidemiology, hospital infusion center expansion plans, and generics tender volume allocation shifts. Forecast inputs incorporated pharmacovigilance staffing constraints and EU Falsified Medicines Directive serialization capital requirements.
The model holds under stable State Institute for Drug Control reimbursement eligibility criteria; deviation in health technology assessment timeline acceleration or EMA centralized procedure backlog would shift market access trajectories. A small set of triggers—hospital pharmacy consolidation pace, API import tariff exposure, and qualified pharmacovigilance personnel availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Trenbolone Acetate Market