
 Global Migraine Therapeutics Market | 2026-2036
Global Migraine Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Migraine Therapeutics Market Foresight
Specialty neurology clinics is decoupling from primary care facilities as the dominant site of care for complex migraine patients. AbbVie Inc. anchors its position through deep specialization in CGRP-targeted biologics for both acute and preventive settings. Eli Lilly and Company differentiates via manufacturing scale across multiple mechanism classes. Pfizer Inc. competes through channel control spanning hospital, retail, and direct-to-patient distribution.
Migraine therapeutics comprise pharmaceutical agents designed to abort acute attacks, prevent episodic or chronic migraine recurrence, or manage associated symptoms such as aura and nausea; these formulations range from small-molecule vasoconstrictors like triptans to monoclonal antibodies and receptor antagonists targeting calcitonin gene-related peptide pathways, with dosing regimens spanning oral tablets, subcutaneous injections, and intravenous infusions. Their primary purpose is to reduce disability-adjusted life years by restoring functional capacity in patients experiencing moderate to severe headache disorders. CGRP antagonists now command the fastest expansion within product type segmentation as payer formularies broaden access beyond prior authorization barriers. Preventive treatment represents the dominant therapy area by revenue commitment, while acute treatment retains higher prescription volume. Neurology clinics capture premium pricing within end user segmentation due to specialist-driven protocol adherence.
The FDA's Breakthrough Therapy designation and the EMA's PRIME scheme have compressed development timelines for novel migraine mechanisms, while the EU AI Act begins shaping real-world evidence collection for adaptive trial designs. Japan's PMDA has streamlined reviews for drugs addressing unmet neurological need, accelerating market entry for subcutaneous preventive options. Stakeholders must monitor how pharmacovigilance requirements for CGRP-class agents evolve across FDA, EMA, and PMDA jurisdictions as post-market exposure databases mature.
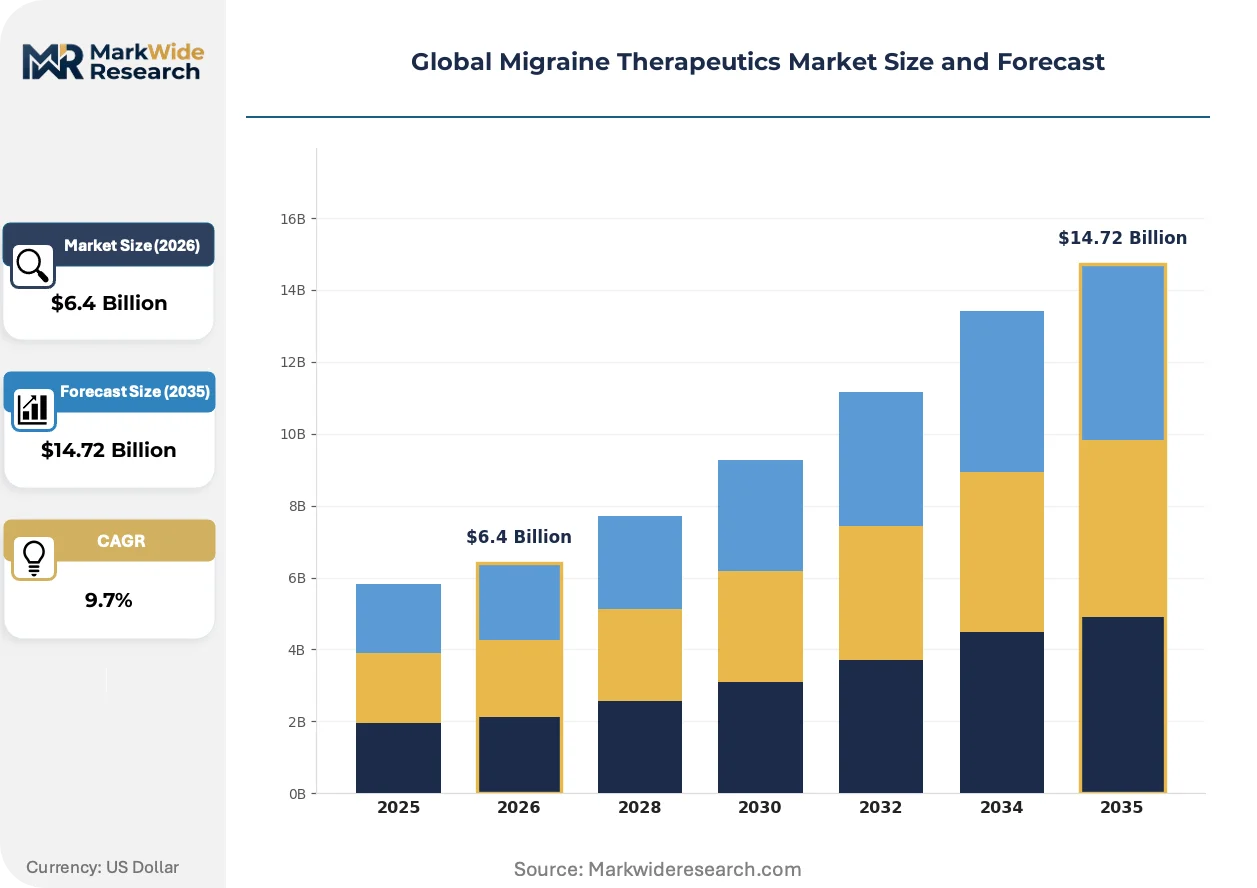
Market Dynamics
CGRP-targeted biologics are compressing development timelines and forcing specialty neurology centers to absorb complex patient flows previously managed in primary care settings.
Growth Catalysts
- FDA Breakthrough Therapy designation:The FDA's accelerated pathway compresses Phase II-to-approval timelines for novel mechanisms. Developers gain earlier revenue recognition and reduced clinical trial cost exposure.
- Headache center network expansion:Germany, Japan, and the United States are building dedicated migraine treatment infrastructure. These facilities concentrate high-value patients and drive protocol-driven prescribing.
- Real-world evidence integration:The EU AI Act is enabling adaptive trial designs that incorporate post-market surveillance data. Regulators accept richer safety profiles without requiring additional controlled studies.
Market Restraints
- Biologics manufacturing concentration:Subcutaneous CGRP antibody production clusters among contract manufacturers in Switzerland and Ireland. Capacity constraints create supply vulnerability for new market entrants.
- Prior authorization persistence:US commercial payers maintain step-therapy requirements that delay CGRP antagonist access. Patients exhaust generic triptan trials before qualifying for biologic coverage.
- Small-molecule substitution pressure:Oral gepants compete with injectable preventives on convenience and cost. Price-sensitive patients and payers favor oral options despite shorter half-lives.
Strategic Opportunities
- Chronic migraine underdiagnosis in India:India's CDSCO has streamlined neurological drug registration. First-movers can establish specialist referral networks before domestic competitors scale.
- Direct-to-patient distribution:Specialty pharmacies now manage cold-chain biologic delivery and injection training. This channel captures patient data and adherence monitoring revenue streams.
- Dual acute-preventive positioning:Gepant molecules demonstrate efficacy in both attack abortion and recurrence prevention. Formulary placement expands without requiring separate indication submissions.
Industry Challenges
- Headache specialist workforce scarcity:Fellowship-trained neurologists concentrate in urban academic centers. Community hospitals lack personnel to operate dedicated migraine clinics.
- Pharmacovigilance database maturity:Post-market cardiovascular safety surveillance for CGRP-class agents remains incomplete. FDA, EMA, and PMDA requirements diverge on signal detection thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Migraine Therapeutics Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $14.72 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triptans, Ergots, CGRP Antagonists, NSAIDs, Beta Blockers Therapy Area: Acute Treatment, Preventive Treatment, Pain Relief, Aura Management, Symptom Control End User: Neurology Clinics, Specialty Centers, Primary Care Facilities, Telemedicine Providers, Pharmacies Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct-to-Patient, Wholesale Distributors |
| Companies Covered | AbbVie Inc., Amgen Inc., Eli Lilly and Company, Pfizer Inc., Teva Pharmaceutical Industries, Novartis AG, Lundbeck A/S, GSK plc, Biohaven Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Migraine Therapeutics Market Shifts & Advancements
Digital biomarker integration and mechanism diversification are compressing diagnosis-to-treatment intervals while expanding addressable patient populations beyond traditional migraine definitions.
Oral CGRP receptor antagonists are rewriting access economics for preventive therapy. Primary care physicians in the United States and Germany are prescribing gepants without specialist referral, collapsing the traditional neurology gatekeeping function. Retail pharmacy fulfillment is displacing infusion center visits for a significant share of maintenance therapy.
The EU AI Act's risk-classification framework for clinical decision-support tools is reshaping how real-world evidence gets incorporated into label expansion submissions. Developers must document algorithmic transparency and training data provenance to satisfy EMA reviewers. Preventive therapy protocols in European headache centers are adopting these validated digital endpoints faster than acute treatment pathways.
Patient-reported outcome instruments are displacing clinician-administered disability scales in reimbursement negotiations. US commercial payers and Germany's statutory health insurers now require monthly migraine-day tracking via smartphone applications. This behavioral shift concentrates data ownership with platform vendors and fragments traditional pharmaceutical value demonstration.
Global Migraine Therapeutics Market Segmentation
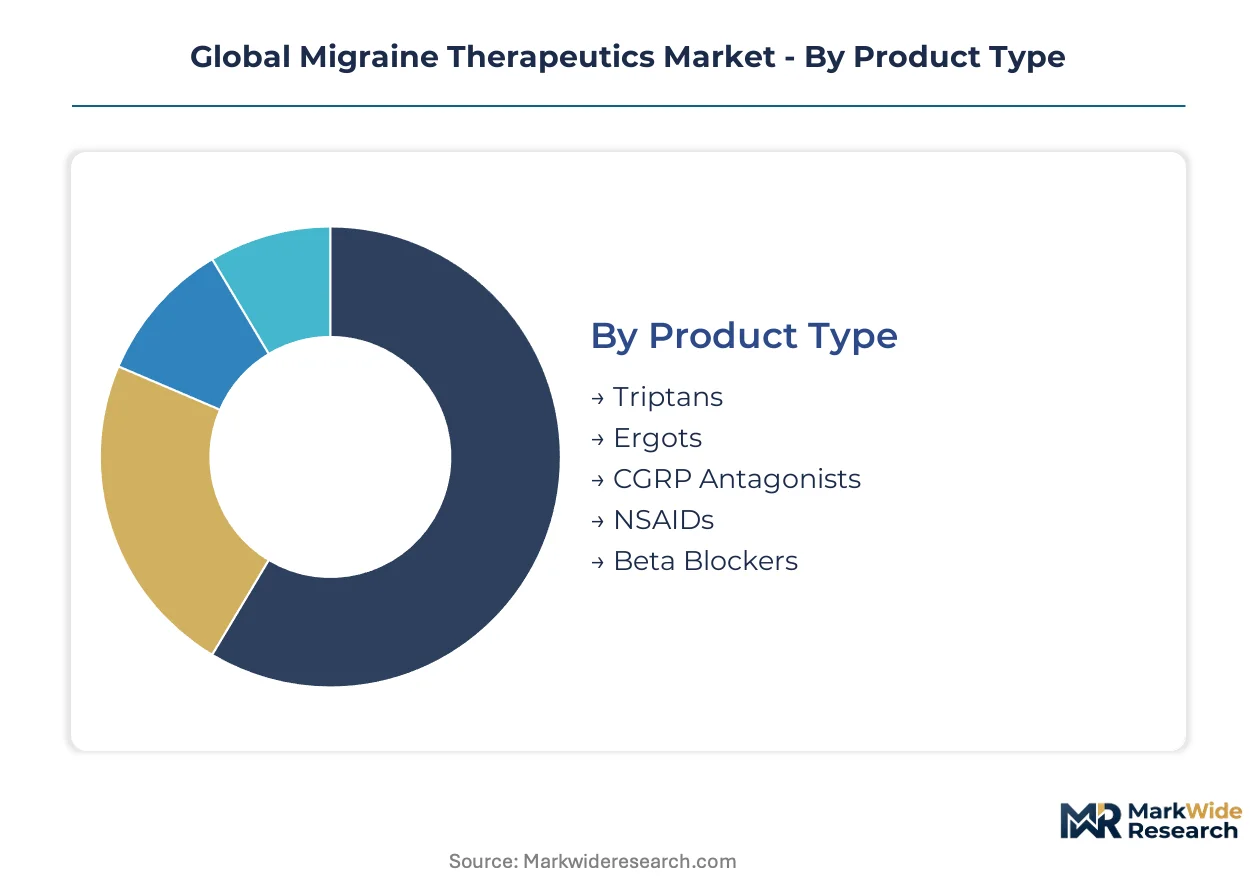
Migraine therapeutics segmentation reveals divergent economics across acute and preventive paradigms. Volume concentration in oral generics contrasts with premium capture by biologic injectables, while site-of-care shifts redistribute channel power.
Product Type:
Volume leadership belongs to legacy small-molecules with generic erosion, while premium capture concentrates in biologics with manufacturing barriers.
- CGRP Antagonists:Monoclonal antibodies and small-molecule receptor antagonists targeting calcitonin gene-related peptide pathways. Subcutaneous formulations command specialist administration in the United States and Germany, where payer formularies now permit primary care initiation of oral gepants.
- Triptans:Serotonin 5-HT1B/1D receptor agonists including sumatriptan and rizatriptan derivatives. Mass prescription volume persists in Japan and the United States despite cardiovascular contraindications, driven by acute attack familiarity and generic pricing.
- Ergots:Ergotamine and dihydroergotamine formulations with potent vasoconstrictive properties. Restricted to refractory cases in Germany due to regulatory safety monitoring.
- NSAIDs:Non-steroidal anti-inflammatory drugs including naproxen and ibuprofen combinations. Over-the-counter access in Japan sustains first-line acute therapy before specialist referral.
- Beta Blockers:Propranolol and metoprolol repurposed for migraine prophylaxis. Cardiology co-prescribing in the United States extends reach beyond neurology clinics.
Mature deployment sits with Triptans. Newer deployment is concentrated in CGRP Antagonists.
Therapy Area:
Revenue commitment favors long-term prevention protocols over episodic intervention, though prescription frequency inverts this hierarchy.
- Preventive Treatment:Scheduled regimens reducing attack frequency and severity in episodic and chronic migraine. Monthly injectable dosing in United States specialty centers captures adherence premiums through pharmacy benefit management integration.
- Acute Treatment:Attack-abortive agents administered at headache onset. Higher prescription velocity in Germany and Japan retail pharmacies reflects patient self-administration patterns.
- Pain Relief:Adjunctive analgesia addressing non-headache symptoms including neck tension and photophobia. Co-formulation demand in Japanese combination products.
- Aura Management:Interventions targeting cortical spreading depression and sensory disturbances preceding headache. Unmet need concentration in academic neurology centers across the United States.
- Symptom Control:Anti-emetic and autonomic stabilizers for nausea and autonomic dysfunction. Hospital emergency department protocols in Germany.
Preventive Treatment commands the steepest expansion trajectory as chronic migraine recognition improves. Acute Treatment retains volume density.
End User:
Site-of-care economics separate protocol-driven premium capture from commoditized prescription fulfillment.
- Neurology Clinics:Fellowship-trained specialist facilities with diagnostic capability and infusion infrastructure. United States academic medical centers concentrate biologic initiation and outcome monitoring.
- Specialty Centers:Dedicated headache programs with multidisciplinary staffing. Germany's statutory health insurance reimbursement favors these facilities for refractory case management.
- Primary Care Facilities:General practitioner offices managing uncomplicated episodic migraine. Japan's community healthcare system routes stable patients here.
- Telemedicine Providers:Remote consultation platforms with e-prescribing integration. United States commercial payer expansion post-pandemic.
- Pharmacies:Community and hospital dispensaries with patient counseling protocols. German Apotheken provide injection training for take-home biologics.
Neurology Clinics anchor premium therapy initiation. Telemedicine Providers are gaining share fastest in stable patient maintenance.
Distribution Channel:
Cold-chain requirements and patient education needs fragment fulfillment economics across institutional and direct models.
- Direct-to-Patient:Specialty pharmacy home delivery with injection training and adherence monitoring. United States hub models capture data assets for pharmaceutical manufacturers.
- Hospital Pharmacies:Inpatient and outpatient dispensaries attached to acute care facilities. Japan's integrated delivery networks centralize biologic procurement here.
- Retail Pharmacies:Community-based fulfillment for oral acute therapies. German pharmacy chains dominate gepant dispensing.
- Online Pharmacies:Mail-order platforms with automated refill management. United States Medicare Part D plan integration.
- Wholesale Distributors:Third-party logistics providers managing temperature-controlled storage. Swiss and Irish contract manufacturing clusters feed these networks.
Hospital Pharmacies dominate biologic flow control. Direct-to-Patient channels are climbing the fastest as specialty pharmacy networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in Ireland and Switzerland concentrate CGRP antibody production capacity. Tax incentives in Singapore and Research Triangle Park, North Carolina, attract clinical trial operations. These zones reshape where biologic development capital deploys.
United States
Headache center networks in Boston, Phoenix, and Cleveland concentrate high-value patient flows. The FDA's Breakthrough Therapy designation compresses Phase II-to-approval timelines for novel mechanisms. Massachusetts biotech clusters anchor monoclonal antibody manufacturing for subcutaneous preventive therapies.
Germany
Statutory health insurance reimbursement favors dedicated headache programs in Berlin and Munich. The EMA's centralized marketing authorization procedure enables simultaneous EU-wide access for new CGRP antagonists. Baden-Württemberg's pharmaceutical manufacturing corridor supplies injection devices to specialty centers.
Japan
Community healthcare routes stable patients to primary care while academic centers in Tokyo and Osaka manage refractory cases. PMDA has streamlined reviews for drugs addressing unmet neurological need. Kansai region hospitals centralize biologic procurement through integrated delivery networks.
Switzerland
Contract manufacturing clusters in Basel and Zurich produce subcutaneous CGRP antibodies for global distribution. Swissmedic maintains alignment with EMA pharmacovigilance standards while offering faster review timelines. The country's pharmaceutical special economic zone status attracts cold-chain logistics investment.
India
CDSCO has streamlined neurological drug registration, opening specialist referral networks in Mumbai and Hyderabad. Domestic manufacturing of small-molecule generics competes with imported biologics on cost. Telangana's life sciences corridor attracts contract research organizations for adaptive trial designs.
Global Migraine Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biologic developers capturing premium pricing while generic houses dominate acute therapy volume. The vendor base concentrates around three strategic archetypes: CGRP-targeted biologic specialists, diversified neurology portfolio owners, and manufacturing-scale operators with cross-mechanism presence. M&A activity targets gepant pipeline assets and headache center network integration. Capacity expansion concentrates in Swiss and Irish contract manufacturing sites.
Among North American biopharmaceutical developers, AbbVie Inc., Eli Lilly and Company, and Pfizer Inc. exemplify distinct competitive positions. AbbVie occupies the CGRP-targeted specialization archetype through deep investment in monoclonal antibody platforms. Eli Lilly represents manufacturing-scale diversification across multiple mechanism classes including small-molecule and biologic formats. Pfizer anchors channel control capabilities spanning hospital, retail, and direct-to-patient distribution infrastructure. These three patterns illustrate how market participants defend position through divergent capability accumulation rather than direct feature competition.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| Eli Lilly and Company |
| Pfizer Inc. |
| Teva Pharmaceutical Industries |
| Novartis AG |
| Lundbeck A/S |
| GSK plc |
| Biohaven Pharmaceuticals |
| Others |
Supply & Pricing Matrix
US commercial payer step-therapy mandates force manufacturers to absorb longer qualification timelines for CGRP antagonist coverage, compelling supply chain investments in patient support infrastructure and adherence monitoring platforms that inflate net delivered cost. Biologic cold-chain requirements compound this pressure by limiting fulfillment flexibility to specialty pharmacy networks with validated temperature control capabilities.
Pricing Analysis
Short lead-time premiums attach to subcutaneous CGRP antibody formulations stocked in United States specialty pharmacies for same-day patient initiation, while spot inventory discounts emerge for oral gepants in German retail channels with generic substitution pressure. The dominant pricing structure runs contract-based long-term offtake agreements between manufacturers and pharmacy benefit managers, with price differentiation hinging on FDA Breakthrough Therapy certification tier and volume scale commitments through integrated delivery networks. Cost compression in the acute therapy tier intensifies because Japanese over-the-counter NSAID access diverts prescription volume, leaving preventive biologics as the least price-sensitive segment where prior authorization filters concentrate covered lives.
Supply Chain Analysis
FDA cGMP certification and EMA GMP qualification gating restrict subcutaneous CGRP antibody production to contract manufacturing facilities in Switzerland, Ireland, and limited Massachusetts biotech clusters. These sites draw from Chinese recombinant protein production inputs, German-engineered injection devices, and Swiss cold-chain logistics infrastructure, creating single-source vulnerability around bioreactor capacity allocation during regulatory inspection cycles. Distribution runs through specialty pharmacy hub models in the United States and hospital pharmacy networks in Japan, with wholesale distributors managing temperature-controlled storage handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The migraine therapeutics sector sits in a mechanism-transition phase as oral CGRP receptor antagonists displace legacy triptan volume in primary care settings, forcing portfolio repositioning across acute and preventive paradigms.
For Market Incumbents: Lock in headache center network exclusivity through co-developed digital biomarker platforms that capture patient-reported outcome data required by US and German payers. Deepen backward integration into Swiss and Irish biologic manufacturing capacity before contract manufacturer allocation constraints harden, while accelerating gepant pipeline assets to defend against small-molecule substitution pressure from oral generics.
For New Entrants and Emerging Players: Specialty pharmacy partners offer the fastest channel credibility for subcutaneous preventive launches without established hospital formulary relationships. India's CDSCO-streamlined neurological drug registration presents the most penetrable geography for first-mover specialist referral network construction, with direct-to-patient distribution models capturing adherence monitoring revenue streams unavailable through institutional procurement.
For Investors and Strategic Acquirers: Re-rating potential sits with dual acute-preventive gepant developers given FDA formulary placement flexibility without separate indication submissions. Long-term viability favors assets with validated real-world evidence collection infrastructure under EU AI Act compliance frameworks, with the signal to watch being PMDA cardiovascular safety surveillance harmonization across FDA and EMA pharmacovigilance thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses Phase II-to-approval timelines for novel CGRP mechanisms. |
| Manufacturing Scale-Up | Swiss and Irish contract manufacturing clusters expand bioreactor capacity for subcutaneous antibody production. |
| Pipeline Diversification | Gepant molecules targeting dual acute-preventive indications expand formulary placement without separate submissions. |
| Strategic Partnership | Specialty pharmacy hub models in the United States capture patient data assets for adherence monitoring revenue. |
| Geographic Expansion | India's CDSCO streamlined registration opens specialist referral networks before domestic competitors scale. |
Research Methodology
FDA filings, EMA centralized marketing authorization submissions, and ClinicalTrials.gov protocol registrations formed the secondary backbone, cross-referenced with formulary database snapshots from US commercial payers and Germany's statutory health insurers. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated pipeline progression assumptions and reimbursement timeline expectations. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation reconciled volume and value estimates across the analysis window.
Historical trendline analysis of CGRP antagonist adoption curves in the United States, Germany, and Japan established baseline penetration rates, with forward projection incorporating therapy area segmentation across preventive and acute paradigms, dosage form differentiation between subcutaneous and oral delivery, and regional regulatory cluster dynamics. CAGRs were derived from segmented growth rate blending rather than single-point extrapolation, with forecast inputs including PMDA review timeline compression effects and EU AI Act real-world evidence integration parameters.
Caveats apply where FDA pharmacovigilance signal detection threshold changes, EMA adaptive trial design acceptance variance, or PMDA cardiovascular safety requirement shifts could materially shift the outlook. Forecasts reflect documented assumptions about headache specialist workforce expansion rates and prior authorization barrier persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Olanzapine API Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Drug Repurposing Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market