
 Amlodipine Besylate Market | 2026-2036
Amlodipine Besylate Market Size, Share, and Industry Trends Forecast 2026-2036
Amlodipine Besylate Market Analysis
A capital-intensity divergence between large-scale API producers and regional formulation packagers is bifurcating competitive returns in the Amlodipine Besylate landscape. Pfizer leverages its originator heritage and institutional relationships in regulated markets to sustain premium positioning for branded formulations. Dr. Reddy's Laboratories anchors its competitive stance through backward integration into API manufacturing and ANDA filing density in the United States. Lupin Pharmaceuticals specializes in complex generic combinations and differentiated dosage forms that command pharmacist substitution preferences.
Amlodipine besylate is the besylate salt form of amlodipine, a dihydropyridine calcium channel blocker with molecular formula C20H25ClN2O5·C6H6O3S, manufactured through multi-step organic synthesis involving chiral resolution or asymmetric catalysis followed by salt formation and crystallization; it functions as a selective vasodilator for hypertension and angina management by inhibiting calcium ion influx across vascular smooth muscle. Tablets dominate volume throughput due to manufacturing simplicity and patient compliance familiarity, while extended release formulations capture margin pools where patent differentiation and dosing convenience reduce substitution pressure. Retail pharmacies occupy the primary distribution node for chronic refill prescriptions, though online pharmacies are gaining script flow where reimbursement frameworks permit mail-order fulfillment.
FDA bioequivalence standards and EMA quality guidelines shape product development costs and approval timelines for generic entrants, while India's CDSCO manufacturing facility inspections determine export eligibility for API and finished dose supplies. WHO prequalification requirements influence tender participation for emerging market procurement programs, creating tiered access conditions. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards that could reshape specification compliance burdens across manufacturing networks.
Market Dynamics
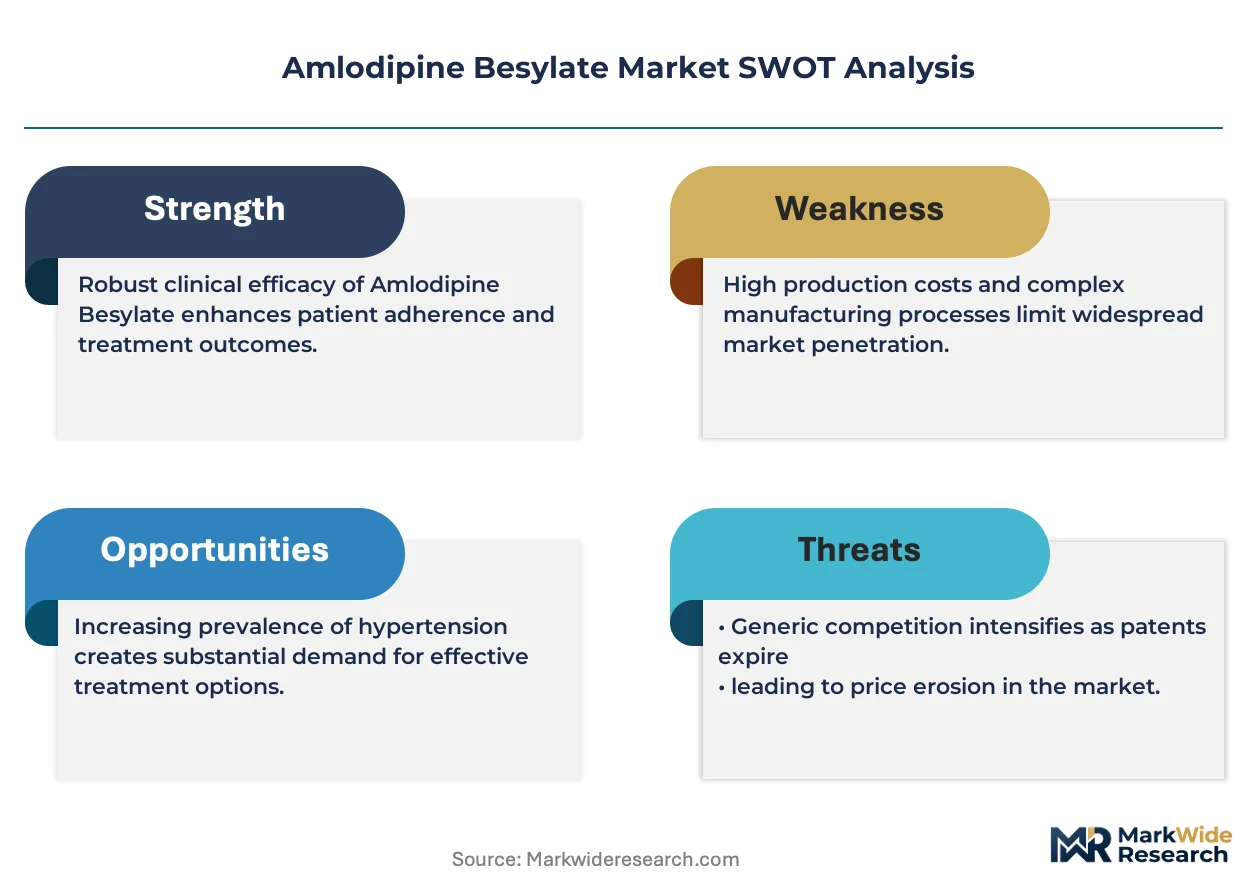
Generic substitution pressure from India's API-exporting manufacturers is compressing formulation margins while fragmenting competitive returns across the Amlodipine Besylate value chain.
Growth Catalysts
- Chronic disease prevalence:Hypertension patient pools in aging populations sustain prescription refill volumes for calcium channel blockers in North American and European healthcare systems.
- EMA centralized procedures:Streamlined bioequivalence assessments accelerate market entry for generic manufacturers seeking pan-European distribution rights.
- Fixed-dose combinations:Amlodipine-valsartan and amlodipine-olmesartan pairings command pharmacist substitution preferences through simplified adherence protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in Gujarat and Hyderabad create single-geography vulnerability for global finished dose manufacturers.
- FDA bioequivalence standards:Stringent pharmacokinetic study requirements elevate development costs and extend approval timelines for abbreviated new drug applications.
- Formulation commoditization:Immediate-release tablet standardization eliminates product differentiation and compresses pricing power across retail pharmacy channels.
Strategic Opportunities
- Pediatric liquid formulations:Unmet dosage flexibility for geriatric and pediatric populations creates white space for differentiated delivery systems beyond standard tablets.
- CDSCO export certification:Indian manufacturers leveraging domestic regulatory approvals can accelerate WHO prequalification for emerging market tender participation.
- Mail-order pharmacy penetration:Reimbursement frameworks permitting ninety-day script fulfillment through online channels reduce patient acquisition costs for chronic therapy providers.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent USP, EP, and IP specification requirements force manufacturers to maintain parallel quality systems and testing protocols.
- Chiral synthesis expertise scarcity:Asymmetric catalysis and resolution capabilities required for API production concentrate within specialized chemical engineering talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amlodipine Besylate Market |
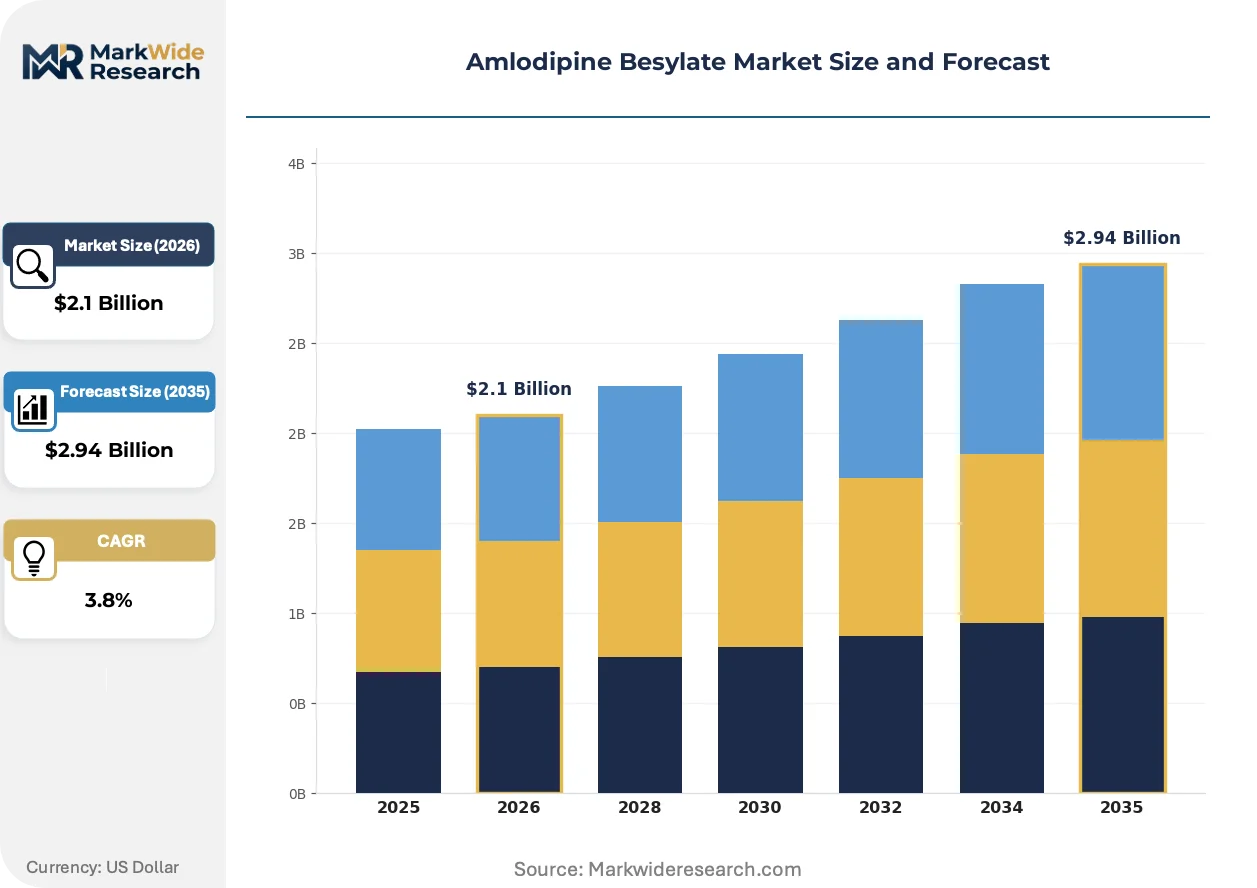
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable Solutions, Extended Release Therapy Area: Hypertension, Angina, Heart Failure, Coronary Artery Disease Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Wholesalers Customer Type: Patients, Healthcare Providers, Pharmacies, Payers |
| Companies Covered | Dr. Reddy's Laboratories, Lupin Pharmaceuticals, Pfizer, Viatris, Teva Pharmaceutical Industries, Sanofi, Cipla, Zydus Lifesciences, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amlodipine Besylate Market Emerging Trajectories
Manufacturing process intensification and regulatory data harmonization are reshaping competitive economics across the Amlodipine Besylate supply base, with technology adoption pacing varying sharply by geography and facility vintage.
Continuous flow chemistry for dihydropyridine ring construction is supplanting traditional batch reactor operations in large-scale API facilities. European and North American producers with capital reserves are retrofitting Hyderabad and Ahmedabad plants with microreactor systems. This transition compresses solvent volumes and reaction times while raising barriers for batch-dependent regional packagers.
REACH substance registration requirements are tightening impurity profiling obligations for European market entrants. Manufacturers must now document genotoxic impurity thresholds below traditional pharmacopeial limits. Indian exporters with EMA-approved sites are investing in mass spectrometry infrastructure to preempt regulatory queries.
Retail pharmacy consolidation into centralized purchasing cooperatives is altering contract negotiation leverage across generic cardiovascular portfolios. Independent pharmacist substitution autonomy is yielding to formulary committee protocols in United States health systems. This concentration is most visible in Medicare Part D plan structures where preferred drug lists determine volume allocation.
Amlodipine Besylate Market Segmentation
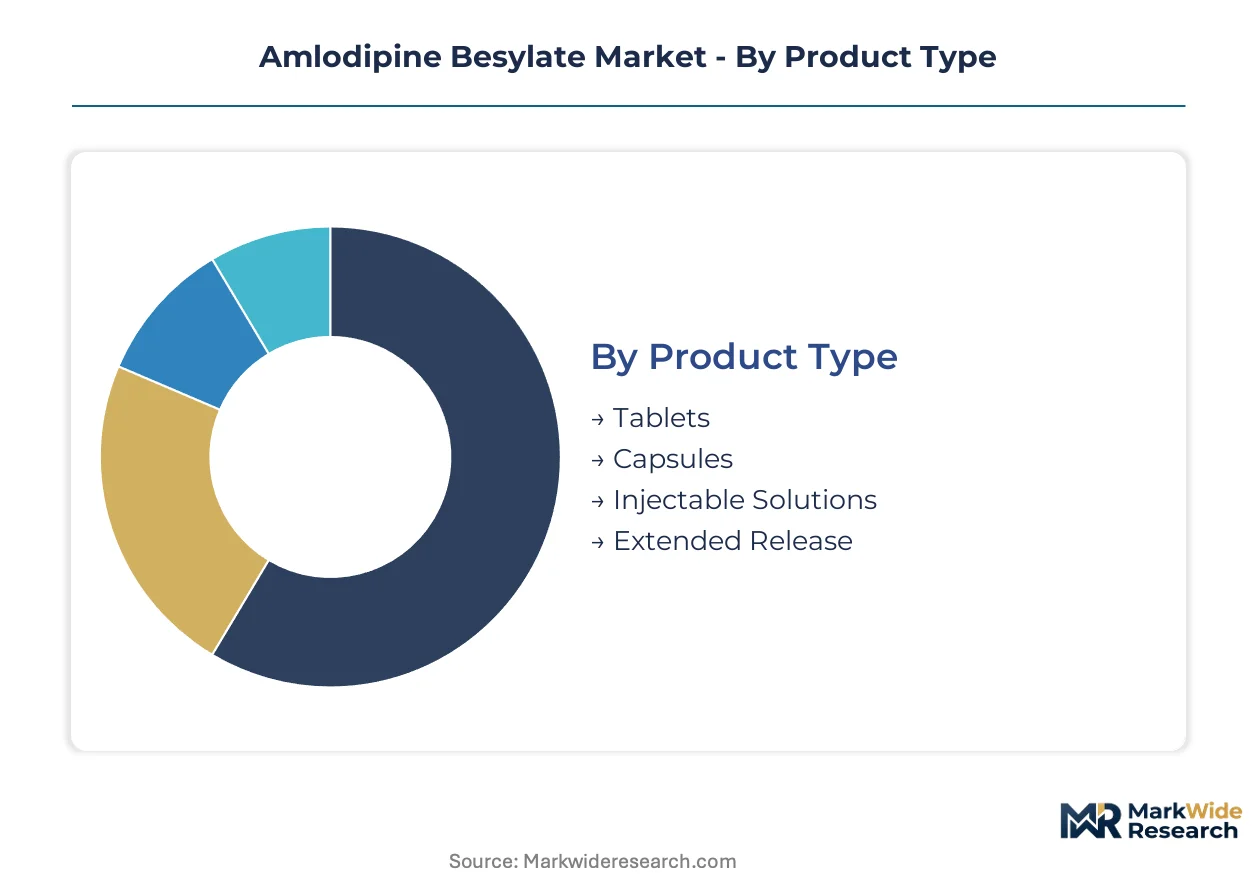
Segmentation in the Amlodipine Besylate market reveals how formulation standardization and distribution channel concentration create divergent margin profiles across the value chain. Understanding these splits enables manufacturers to allocate development resources toward segments with sustainable pricing power.
Product Type:
Substitution pressure varies sharply by formulation complexity, with immediate-release tablets facing the most aggressive price erosion while extended-release variants retain differentiation leverage.
- Tablets:Immediate-release compressed formulations dominate prescription volumes through manufacturing simplicity and patient familiarity with once-daily dosing regimens. Demand concentrates in India's export-oriented formulation clusters where Gujarat and Hyderabad facilities supply regulated markets with bioequivalent copies. Tablet commoditization forces manufacturers to compete on batch scale and procurement efficiency rather than clinical differentiation.
- Extended Release:Matrix-controlled or osmotic pump systems deliver sustained plasma concentration profiles that reduce dosing frequency and improve adherence in polypharmacy populations. Adoption is climbing fastest in United States Medicare Part D formularies where ninety-day dispensing incentives favor adherence-optimized regimens. Patent-protected coating technologies and modified-release excipients create temporary barriers to therapeutic substitution.
- Capsules:Gelatin or HPMC shells containing powder or granule fills serve pediatric and geriatric populations with swallowing difficulties. CDSCO-approved Indian manufacturers supply these to emerging markets where tablet alternatives remain limited.
- Injectable Solutions:Sterile parenteral formulations for acute hypertensive crisis management in hospital emergency departments. Production requires aseptic fill-finish capabilities that concentrate supply among specialized contract manufacturers.
Tablets anchor the volume base while Extended Release gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention protocols, with hypertension management occupying the mass-market position and coronary artery disease commanding premium positioning.
- Hypertension:First-line calcium channel blocker therapy for essential and secondary blood pressure elevation, typically combined with ACE inhibitors or diuretics in stepped-care protocols. Patient pools in aging United States and European populations sustain refill volumes through retail pharmacy channels. Generic substitution rates exceed ninety percent in most reimbursement frameworks.
- Coronary Artery Disease:Vasodilator therapy for chronic stable angina and vasospastic disorders where amlodipine's long half-life supports consistent anti-ischemic protection. Prescription concentration in cardiology specialty practices and hospital outpatient clinics supports pricing premiums over primary-care hypertension scripts.
- Angina:Symptomatic relief for exertional and variant angina pectoris through coronary vasodilation and afterload reduction. Demand tracks cardiac catheterization procedure volumes in tertiary care centers.
- Heart Failure:Off-label and guideline-directed use in preserved ejection fraction populations where arterial vasodilation reduces ventricular workload. Prescription volumes remain constrained by competing beta-blocker and SGLT2 inhibitor protocols.
Hypertension represents the largest addressable population while Coronary Artery Disease delivers the highest per-script margins.
Distribution Channel:
Customer type concentration is reshaping channel economics, with institutional purchasers gaining leverage over independent retail operators and mail-order fulfillment capturing chronic therapy volumes.
- Retail Pharmacies:Community-based dispensing locations handling thirty-day prescription refills for commercially insured and cash-pay patients. Pharmacist substitution autonomy varies by United States state law and European national formularies.
- Hospitals:Inpatient and outpatient pharmacy departments managing acute presentations and care transitions. Formulary committee control limits product selection to contracted suppliers with proven supply reliability.
- Online Pharmacies:Mail-order and digital-first dispensers capturing ninety-day maintenance prescriptions where reimbursement frameworks permit remote fulfillment. United States Medicare Part D plans increasingly mandate mail-order for chronic cardiovascular therapies.
- Wholesalers:Regional and national distributors managing inventory aggregation and just-in-time delivery to fragmented pharmacy networks. McKesson, AmerisourceBergen, and Cardinal Health dominate United States distribution.
Retail Pharmacies retain the highest transaction frequency while Online Pharmacies are expanding most quickly in chronic therapy segments.
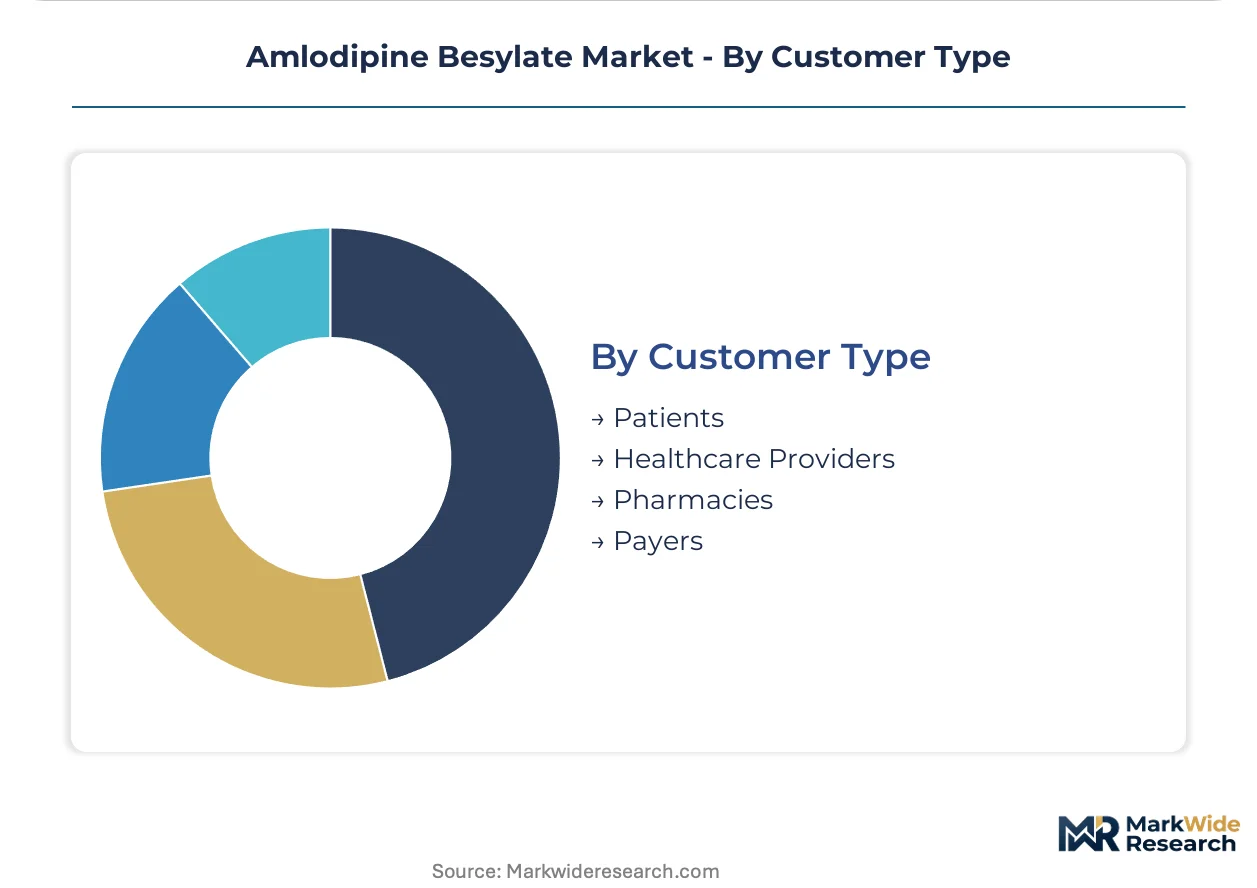
Customer Type:
Maturity gradients separate established prescriber relationships from emerging payer control mechanisms, with pharmacy benefit managers increasingly intermediating between manufacturers and end-users.
- Healthcare Providers:Primary care physicians and cardiologists initiating and titrating therapy based on guideline recommendations and patient comorbidity profiles. Prescription authority remains concentrated in United States and European medical practices with established amlodipine familiarity.
- Payers:Insurance carriers and pharmacy benefit managers setting formulary tiers, prior authorization requirements, and step-therapy protocols that determine product access and patient cost-sharing levels.
- Patients:End-users with varying adherence patterns influenced by co-payment burden, dosing convenience, and side-effect tolerability. Direct-to-patient channels remain limited by prescription requirements.
- Pharmacies:Dispensing entities managing generic substitution decisions within regulatory and contractual constraints. Independent operators retain more substitution autonomy than chain-affiliated locations.
Healthcare Providers drive initial therapy selection while Payers are capturing the greatest influence over continued product access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for finished formulations concentrates in United States Medicare Part D channels while API cost advantages cluster in Indian manufacturing zones. This asymmetry drives cross-border supply chain configurations that prioritize FDA and EMA compliance at the formulation stage.
United States
Medicare Part D formularies and pharmacy benefit manager tiering sustain premium positioning for extended-release variants. FDA bioequivalence standards and REMS requirements elevate entry barriers for generic entrants. New Jersey and North Carolina formulation facilities handle high-volume compression and coating operations for domestic distribution.
India
CDSCO-approved API manufacturing in Gujarat and Telangana supplies over sixty percent of global amlodipine besylate raw material. The country's PLI scheme for pharmaceuticals incentivizes capacity expansion in active ingredient synthesis. Hyderabad and Ahmedabad clusters specialize in chiral resolution and salt formation chemistry for export markets.
Germany
EMA centralized procedures and REACH substance registration requirements shape importer obligations for Indian API suppliers. German pharmacy substitution rules permit automatic generic exchange at dispensing. The Rhine-Main region houses quality control laboratories serving pan-European distribution networks.
United Kingdom
NHS England prescribing guidelines favor amlodipine as first-line calcium channel blocker therapy in stepped-care hypertension protocols. MHRA post-Brexit recognition agreements with FDA streamline parallel import pathways. Manufacturing formulation activity concentrates in the East Midlands and North West England.
Japan
PMDA manufacturing site inspections and foreign manufacturer registration requirements govern Indian API supplier eligibility. Aging demographic profiles sustain chronic cardiovascular prescription volumes through community pharmacy networks. Osaka and Tokyo metropolitan areas host importation and secondary packaging operations.
Amlodipine Besylate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Amlodipine Besylate value chain. Originators with institutional formulary relationships command premium positioning in regulated markets, while integrated Indian manufacturers capture API and generic formulation volume. The competitive structure separates into three archetypes: patent-era originators defending branded positioning, vertically integrated API-to-formulation specialists, and regional packagers dependent on external active ingredient supply. Dominant competitive moves include backward integration into API manufacturing and geographic expansion through ANDA filing density in United States markets.
Among originator-heritage multinationals, Pfizer occupies a position exemplifying premium-tier defense through institutional relationships and extended-release patent portfolios. Within the integrated Indian specialist tier, Dr. Reddy's Laboratories and Lupin Pharmaceuticals represent the archetype of backward-integrated API manufacturers leveraging domestic production clusters for regulated market entry. These three companies anchor the competitive spectrum from branded premium to cost-optimized generic supply.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Lupin Pharmaceuticals |
| Pfizer |
| Viatris |
| Teva Pharmaceutical Industries |
| Sanofi |
| Cipla |
| Zydus Lifesciences |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Indian API manufacturers and European formulation packagers lock in multi-year supply access while capping price volatility for critical amlodipine besylate inputs. These contracts tether procurement costs to CDSCO inspection cycles and REACH registration timelines, embedding regulatory compliance directly into pricing visibility.
Pricing Analysis
The customization-premium spread between standard immediate-release tablets and modified-release formulations reaches its widest point in United States Medicare Part D channels. Three-tier pricing structure across patent-protected extended-release, bioequivalent generic tablets, and commodity-grade export formulations separates Pfizer's branded positioning from Dr. Reddy's ANDA-filed copies and unbranded Indian exports. Cost compression in immediate-release segments is intensifying because Gujarat-based API producers are expanding batch scale faster than formulation demand growth. Hospital procurement committees exhibit the lowest price sensitivity due to formulary lock-in, while retail pharmacy cooperatives drive the hardest volume-discount negotiations.
Supply Chain Analysis
India and China anchor global amlodipine besylate API production, with Gujarat and Hyderabad clusters handling chiral resolution chemistry and Zhejiang province contributing intermediate dihydropyridine synthesis. Finished dose formulation draws from Indian API supply, European excipient sources, and United States coating technologies. Single-source vulnerability concentrates in CDSCO-approved active ingredient facilities subject to unannounced FDA inspections. Distribution runs through McKesson and AmerisourceBergen in North America, with parallel import channels serving European pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in asymmetric catalysis expertise and EMA-approved manufacturing site capacity defines competitive durability in this market, favoring players with captive API production and established regulatory filing track records.
For Market Incumbents: Compound institutional formulary relationships through extended-release patent defenses and preferred supplier status in Medicare Part D plans. Deepen backward integration into Hyderabad API facilities to offset substitution pressure from Gujarat-based competitors. Prioritize CDSCO inspection readiness to preempt supply disruptions that would fracture hospital contracts. For New Entrants and Emerging Players: Differentiate on pediatric liquid formulation capabilities where dosage flexibility commands pharmacist preference and reduced substitution pressure. Target emerging market tender participation through WHO prequalification pathways, leveraging domestic Indian regulatory approvals as acceleration mechanisms. Pursue mail-order pharmacy partnerships where ninety-day dispensing incentives favor new supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated API-to-formulation specialists with established ANDA filing density in United States markets and EMA-approved European sites. Long-term viability rests on regulatory relationship durability rather than transient cost advantages. Monitor FDA warning letter issuance to Indian API facilities as the critical inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | ANDA filing density in United States markets accelerates volume capture through pharmacist substitution. |
| Backward Integration | Captive API production in Gujarat clusters insulates margin pressure from raw material cost volatility. |
| Manufacturing Scale-Up | Continuous flow chemistry retrofitting in Hyderabad facilities compresses solvent volumes and reaction times. |
| Licensing Agreement | Fixed-dose combination partnerships with valsartan or olmesartan producers command formulary preference. |
| Geographic Expansion | EMA centralized procedure filings unlock pan-European distribution rights for bioequivalent entrants. |
Methodological Framework
A standing panel of regulatory affairs leads, formulary directors at pharmacy benefit managers, API plant managers in Gujarat and Hyderabad, and hospital procurement managers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation from FDA ANDA filings, EMA centralized procedure submissions, CDSCO manufacturing facility inspection records, and WHO prequalification databases. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs against CMS Medicare Part D utilization data, NHS England prescribing analytics, and Indian pharmaceutical export statistics. The analytical framework modeled segmentation across dosage form complexity, therapy line positioning, distribution channel concentration, and regional regulatory cluster differentiation. CAGRs were derived from patient pool epidemiology, generic substitution rate trajectories, and reimbursement framework evolution throughout the projection horizon. Forecast inputs incorporated FDA bioequivalence study approval timelines and EMA REACH substance registration compliance costs.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO regimes; material policy shifts in bioequivalence standards or manufacturing facility inspection protocols would require re-modeling. Specific risk factors include pharmacopeial harmonization gaps between USP, EP, and IP specifications and chiral synthesis expertise scarcity constraining API production expansion. Recalibration cycles align with material shifts in ANDA approval velocity, CDSCO inspection outcomes, and Medicare Part D formulary restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Anti-Suicide Drugs Market